
 Blended Meat Market | 2026-2036
Blended Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Blended Meat Market Outlook
Flexitarian households is collapsing the distance between premium meat and plant-based alternatives as the dominant buyer archetype gaining share. Tyson Foods leverages its protein processing infrastructure to anchor blended product lines across retail channels. Perdue Farms competes through specialized poultry-plant formulations that occupy a distinct position in the category. Nestlé extends its prepared-foods expertise to navigate European regulatory requirements for hybrid labeling.
Blended meat combines animal protein with plant-based ingredients in controlled ratios to achieve specific nutritional, sensory, or sustainability targets, typically incorporating 20-70% plant matter alongside conventional meat to reduce saturated fat content or environmental footprint while maintaining familiar taste profiles. The product serves industrial foodservice operators and retail brands seeking to bridge consumer gaps between conventional meat and fully plant-based alternatives. Beef and chicken formulations lead current production volumes, though pork-based blends are gaining traction in European retail. Burgers and patties dominate the form category, with sausages representing the fastest-growing segment as manufacturers refine binding technologies for co-extruded casings.
FDA labeling standards and USDA-FSIS joint oversight shape how blended products communicate protein origin and nutritional claims to American consumers, while EFSA guidelines under the EU Green Deal influence reformulation priorities for European suppliers. The EU F-Gas Regulation indirectly affects processing equipment choices for cold-chain blended meat facilities. Stakeholders must monitor evolving definitions of "meat" across jurisdictions, as regulatory classification determines market access and consumer communication strategies.
Market Dynamics
Regulatory classification uncertainty around hybrid protein claims is forcing manufacturers to reconfigure labeling strategies and reformulation roadmaps before enforcement frameworks solidify across major jurisdictions.
Growth Catalysts
- EU Green Deal alignment:EFSA guidelines on sustainable protein sourcing incentivize reformulation toward plant-animal hybrids that reduce carbon intensity metrics in retail-ready formats.
- Cold-chain infrastructure expansion:Foodservice distributors in Germany are building dedicated blended meat handling capabilities to serve flexitarian household demand through supermarket deli counters.
- Binding technology maturation:Advanced extrusion processes enable co-extruded sausage casings that maintain structural integrity at higher plant-protein ratios than previously achievable.
Market Restraints
- Pea protein price volatility:Concentrated sourcing from Canadian and Ukrainian suppliers creates margin pressure when harvest yields fluctuate.
- FDA-USDA jurisdictional overlap:Dual oversight requirements for blended products slow label approval timelines and increase compliance documentation burdens.
- Fully plant-based substitution:Improving taste profiles in 100% plant alternatives threaten the middle-position value proposition of hybrid formulations.
Strategic Opportunities
- Pork-blend white space:Spanish and Italian retail channels show underdeveloped shelf presence for hybrid pork sausages compared to beef and chicken variants.
- Direct-to-foodservice channels:Institutional buyers in German canteen systems seek volume contracts for standardized blended patties with verified carbon footprint data.
- EU F-Gas Regulation adaptation:Processing facilities that retrofit refrigeration systems to low-GWP alternatives gain operational licenses in sustainability-focused municipal procurement.
Industry Challenges
- Hybrid protein characterization expertise:Analytical chemistry capabilities for verifying plant-animal ratios in finished goods remain scarce among third-party testing laboratories.
- Legacy equipment retrofit costs:Existing meat grinding and mixing infrastructure requires capital-intensive modification to handle divergent hydration properties of plant protein isolates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blended Meat Market |
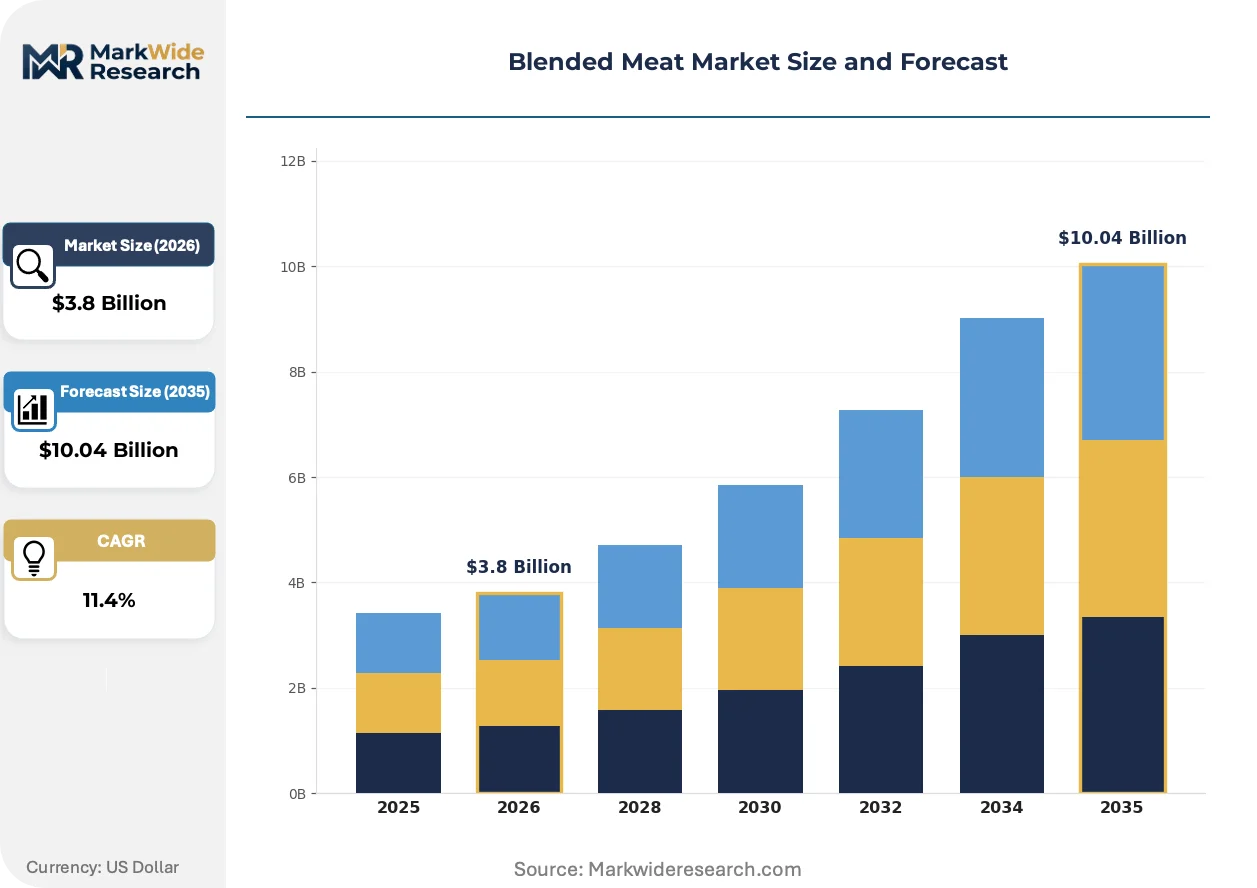
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Pork, Turkey Form: Burgers, Sausages, Meatballs, Patties Cooking Method: Grilling, Baking, Frying, Sous Vide Target Market: Health-Conscious Consumers, Flexitarians, Restaurants, Retail |
| Companies Covered | Tyson Foods, Inc., Perdue Farms, Smithfield Foods, Inc., Hormel Foods Corporation, Cargill, Incorporated, Beyond Meat Inc., Impossible Foods, JBS S.A., Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blended Meat Market Strategic Shifts
Processing technology convergence with precision fermentation-derived ingredients is creating new formulation possibilities that alter the technical boundaries between conventional, hybrid, and fully plant-based categories.
High-moisture extrusion technology is supplanting traditional texturized vegetable protein methods in blended meat production. German and Dutch manufacturers are adopting these systems at commercial scale to achieve muscle-like fiber alignment previously unattainable with dry extrusion. The structural improvement is supplanting cost-driven formulation logic with sensory-performance priorities in premium tier development.
EFSA's evolving guidance on hybrid protein nutrient density claims is compressing allowable fortification strategies for European suppliers. Manufacturers must now substantiate specific amino acid profiles and micronutrient equivalency statements through clinical validation studies. The regulatory burden falls most heavily on mid-size prepared-foods brands lacking in-house regulatory affairs departments.
Flexitarian households are consolidating purchase decisions around single-protein solutions rather than maintaining parallel conventional and plant-based stocks. Retailers in Germany are responding with end-cap displays that merchandise blended products between meat and vegetarian aisles rather than segregating them. This spatial repositioning is most visible in REWE and EDEKA flagship stores where hybrid SKUs now occupy dedicated four-foot sections.
Blended Meat Market Segmentation
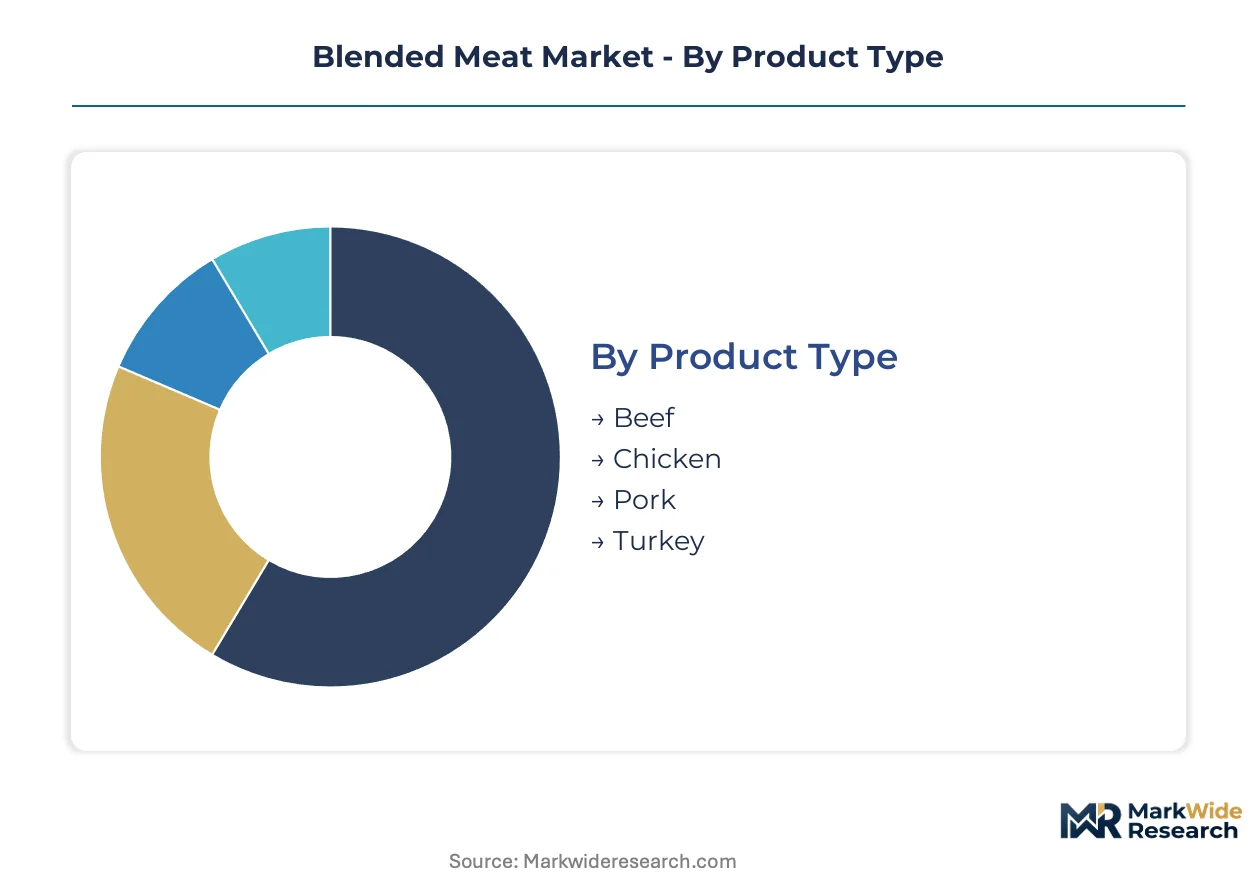
Blended meat manufacturers configure production lines around specific protein bases and form factors that dictate equipment investment, binding technology requirements, and cold-chain specifications. Segmentation clarity determines which reformulation pathways align with regulatory frameworks across target jurisdictions.
Product Type:
Margin pools concentrate in poultry-based formulations where plant-protein integration achieves the cleanest sensory crossover for flexitarian buyers.
- Beef:Formulations typically incorporate 25-40% pea or soy isolates to reduce saturated fat while maintaining iron content and umami depth. German retail chains anchor volume commitments here, driven by carbon footprint labeling requirements under EU Green Deal procurement guidelines.
- Chicken:Tyson Foods and Perdue Farms dominate capacity, leveraging existing poultry processing infrastructure for 30-50% plant inclusion ratios. EFSA nutrient density verification standards favor chicken blends for verified protein completeness claims in European markets.
- Pork:Spanish and Italian retail channels show emerging demand for hybrid sausages with fennel-forward Mediterranean flavor profiles.
- Turkey:Lean protein positioning attracts health-conscious segments in US Northeast corridor retail.
Beef holds installed capacity. Chicken is rotating up the share rankings.
Form:
Volume concentration follows form factor compatibility with existing grinding, mixing, and portioning equipment across co-manufacturing networks.
- Burgers:Standardized patty dimensions enable seamless substitution in foodservice griddle operations. Binding technology maturation allows 40-60% plant inclusion without structural failure during high-heat searing.
- Sausages:Co-extruded casings represent the steepest expansion trajectory as high-moisture extrusion enables muscle-like fiber alignment previously unattainable. Dutch manufacturers lead commercial-scale deployment for bratwurst and breakfast link variants.
- Meatballs:Frozen retail formats dominate, with IKEA-style foodservice contracts driving standardization.
- Patties:Breaded and formed products serve school nutrition programs seeking cost-reduced protein with maintained portion consistency.
Burgers command production line utilization. Sausages are climbing the fastest in new SKU introductions.
Cooking Method:
Application-specific thermal processing requirements shape ingredient selection, particularly hydrocolloid systems for moisture retention.
- Grilling:High-heat char applications demand fat-mimicking coconut oil or sunflower oil emulsions to prevent desiccation. German backyard barbecue culture drives seasonal demand spikes.
- Baking:Lower-temperature uniformity suits meatball and loaf formats where extended cook times allow complete starch gelatinization from added legume flours.
- Frying:Shallow or deep-fat applications require specific crumb adhesion properties in breaded patties.
- Sous Vide:Precision temperature control enables higher plant-protein ratios by eliminating surface dehydration risks.
Grilling anchors seasonal promotional calendars. Sous Vide is gaining traction in premium retail positioning.
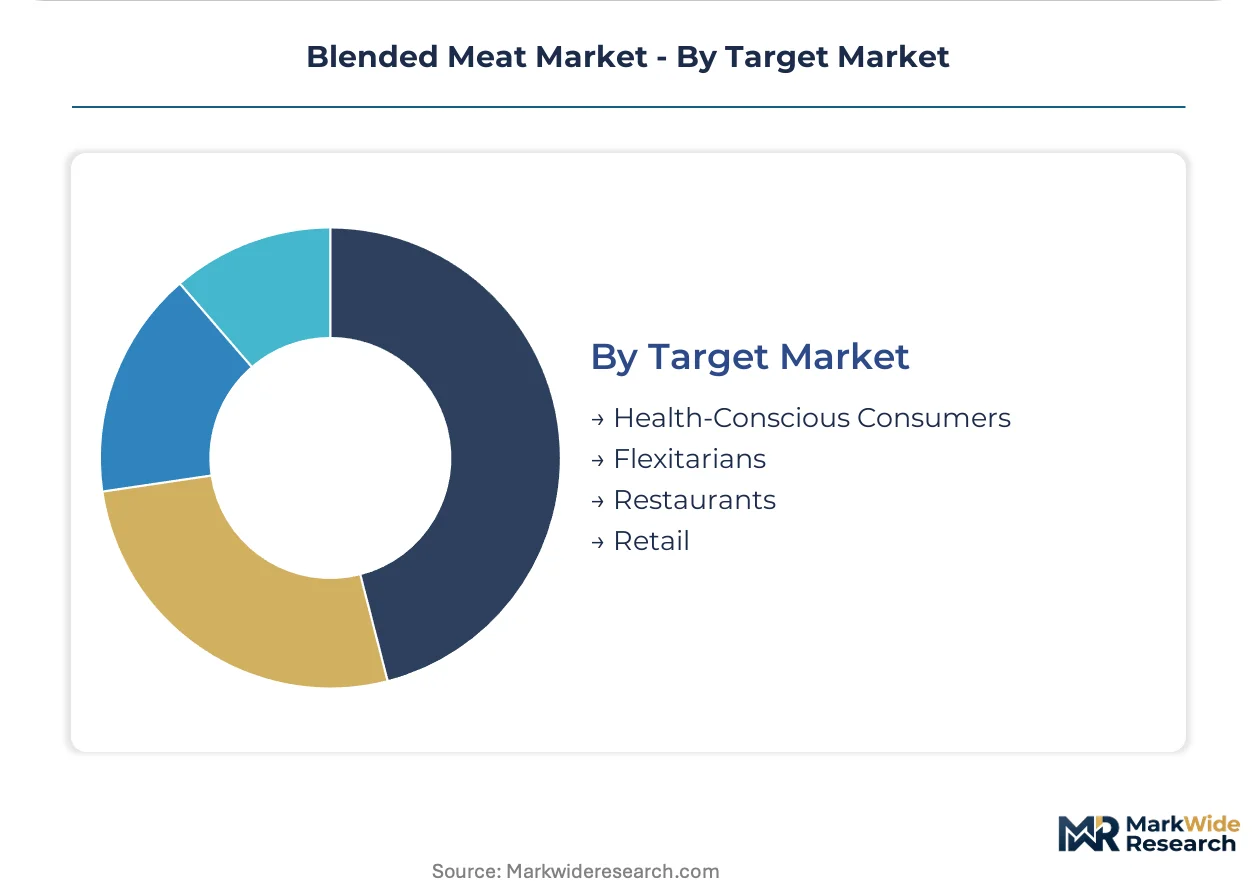
Target Market:
Customer type determines certification requirements, labeling complexity, and price-positioning bandwidth.
- Health-Conscious Consumers:Nutritional panel optimization focuses on sodium reduction and fiber enhancement. FDA dual-jurisdiction labeling creates compliance friction for US retail entrants.
- Flexitarians:German households consolidate purchase decisions around single-protein solutions, driving REWE and EDEKA end-cap placement between conventional meat and vegetarian aisles.
- Restaurants:Foodservice operators seek verified carbon footprint data for menu sustainability claims.
- Retail:Private label programs demand consistent supply for promotional pricing cycles.
Flexitarians hold volume concentration. Restaurants are expanding fastest in contract manufacturing inquiries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexitarian households in Germany anchor volume concentration for blended meat products, with regulatory frameworks in the EU and North America shaping reformulation priorities and market access conditions.
United States
Foodservice distributors in Texas and California are building dedicated blended meat handling capabilities to serve institutional buyers seeking verified carbon footprint data. FDA and USDA-FSIS joint oversight creates dual-jurisdiction labeling complexity that slows product approval timelines. Chicago-area protein processors are retrofitting grinding infrastructure to accommodate plant-protein isolate hydration requirements.
Germany
REWE and EDEKA flagship stores now dedicate four-foot end-cap sections to hybrid SKUs positioned between conventional meat and vegetarian aisles. EU Green Deal procurement guidelines drive carbon footprint labeling requirements that favor beef-blend formulations with 25-40% plant inclusion. Bavarian high-moisture extrusion specialists are deploying commercial-scale systems for muscle-like fiber alignment in bratwurst variants.
Netherlands
Dutch manufacturers lead commercial adoption of co-extruded sausage casings that maintain structural integrity at elevated plant-protein ratios. EFSA guidelines on hybrid protein nutrient density claims compress allowable fortification strategies for mid-size prepared-foods brands. Rotterdam cold-chain distributors are expanding dedicated blended meat storage capacity to serve German retail demand.
United Kingdom
London-based foodservice operators are consolidating purchase decisions around single-protein solutions rather than maintaining parallel conventional and plant-based inventories. Health-conscious consumer segments in the Southeast drive demand for sodium-reduced and fiber-enhanced formulations. Midlands co-manufacturing networks are standardizing patty dimensions for seamless substitution in griddle operations.
Spain
Spanish retail channels show underdeveloped shelf presence for hybrid pork sausages compared to beef and chicken variants, creating white-space opportunity for fennel-forward Mediterranean formulations. Barcelona processors are exploring binding technology adaptations for traditional chorizo-style products. Andalusian agricultural cooperatives are evaluating pea protein sourcing partnerships to reduce exposure to Canadian harvest volatility.
Blended Meat Market Competitive Environment
Player mix skews toward diversified protein conglomerates with existing processing infrastructure rather than pure-play innovators. Market structure exhibits tiered concentration where large-scale meat processors leverage captive distribution networks while specialized prepared-foods brands compete on formulation differentiation. Strategic archetypes include infrastructure-anchored incumbents, hybrid-technology specialists, and retail-brand private-label suppliers. Competitive moves center on binding technology licensing and cold-chain partnership expansion rather than vertical integration.
Among North American protein processors, Tyson Foods, Perdue Farms, and Nestlé occupy distinct positions within the competitive hierarchy. Tyson exemplifies infrastructure-anchored scale through its poultry processing network repurposed for blended formulations. Perdue represents specialized poultry-plant hybrid expertise with distinct positioning in chicken-dominant segments. Nestlé sits within the prepared-foods archetype, leveraging regulatory affairs capabilities to navigate EFSA compliance requirements for European market access.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| Perdue Farms |
| Smithfield Foods, Inc. |
| Hormel Foods Corporation |
| Cargill, Incorporated |
| Beyond Meat Inc. |
| Impossible Foods |
| JBS S.A. |
| Nestlé |
| Others |
Value Chain & Pricing Dynamics
High-moisture extrusion capacity utilization in Dutch and German facilities creates scale economies that compress unit costs for premium-tier blended sausages while establishing price floors for mid-market entrants. Cold-chain infrastructure investments across Bavarian and Rotterdam distribution nodes concentrate supply leverage with established protein processors.
Pricing Analysis
Cost-plus contracts indexed to Canadian pea protein spot markets dominate procurement agreements between manufacturers and foodservice distributors. Price differentiation rests on EFSA nutrient-density certification tiers and verified carbon-footprint labeling depth. Cost compression in standard-tier patties is intensifying because Ukrainian legume supply disruptions force reformulation toward costlier soy isolates. Institutional buyers in German canteen systems exhibit lowest price sensitivity; private-label retail programs face acute margin pressure from promotional pricing cycles.
Supply Chain Analysis
Strategic stockpiling of pea and soy protein isolates prevails among Dutch and German processors buffering against Canadian harvest volatility, while just-in-time delivery governs fresh poultry inputs from domestic suppliers. Raw material sourcing draws from Canadian prairie provinces for legume isolates, Ukrainian Black Sea corridor for sunflower emulsifiers, and domestic German facilities for poultry processing. Single-source vulnerability concentrates in Canadian pea protein extraction capacity. Distribution runs through temperature-controlled networks serving REWE and EDEKA flagship stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blended meat platforms are approaching an interoperability inflection where EFSA nutrient-density data standards and EU Green Deal carbon-footprint protocols create ecosystem lock-in for compliant processors.
For Market Incumbents: Fortify binding technology IP positions through exclusive licensing arrangements with Bavarian high-moisture extrusion specialists. Expand captive cold-chain partnerships in Rotterdam and Hamburg to preempt foodservice distributor consolidation. Vertical integration into Canadian pea protein sourcing hedges harvest volatility exposure.
For New Entrants and Emerging Players: Lead with fennel-forward Mediterranean pork-blend formulations targeting Spanish retail white space. Pursue direct-to-foodservice channels in German municipal canteen systems seeking verified carbon-footprint contracts. Position around EFSA compliance capabilities that mid-size prepared-foods brands lack.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among prepared-foods brands with locked EFSA certification pathways and multi-year retail shelf agreements. Long-term viability favors hybrid-technology specialists with proprietary co-extrusion capabilities over commodity patty processors. Watch for FDA-USDA jurisdictional clarity as inflection signal for US market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Licensing | Proprietary fiber-alignment technology secures premium-tier positioning in German bratwurst variants. |
| EFSA Nutrient-Density Certification | Verified amino-acid profiles unlock flexitarian household consolidation in REWE end-cap placement. |
| Canadian Pea Protein Sourcing Partnership | Backward integration into prairie extraction capacity insulates margins from harvest volatility. |
| Rotterdam Cold-Chain Expansion | Dedicated blended-meat storage capabilities capture German retail demand through EDEKA distribution. |
| Co-Extruded Sausage R&D Investment | Structural integrity at elevated plant-protein ratios displaces traditional TVP methods in Dutch manufacturing. |
Study Parameters
Initial hypotheses were tested against primary input from protein processing plant managers, EFSA regulatory affairs leads, REWE category buyers, and Dutch co-manufacturing technical directors and refined through secondary validation. Trade data from German Federal Statistical Office, EFSA guidance documents, EU Green Deal procurement registries, and customs records for Canadian legume exports anchored supply-side modeling. Bottom-up capacity assessments across Bavarian and Dutch facilities triangulated against top-down retail audit data from Nielsen and Circana.
Variance decomposition across protein base, form factor, and target customer segments structured the analytical framework over the projection horizon. Modeled dimensions span beef-chicken-pork-turkey protein types, burger-sausage-meatball-patty forms, and flexitarian-health-conscious-restaurant-retail buyer archetypes. CAGRs derived from segment-level volume trajectories weighted by EFSA regulatory implementation timelines and cold-chain infrastructure buildout schedules.
Forecasts assume regulatory continuity in EFSA nutrient-density protocols and FDA-USDA joint oversight frameworks; material policy shifts would require re-modeling. Revision becomes warranted when pea protein spot price volatility exceeds historical bands or when binding technology patent expirations accelerate competitive entry.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Meat Market
Meat Products
Shark Meat Market
Meat Products
Animal Protein Market
Meat Products
Brazil Meat Products Market
Meat Products
Meat Packaging Market
Meat Products
Antibiotic Free Meat Market
Meat Products
Global Duck Meats Market
Meat Products
United States Frozen Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Canned Beef Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Emulsified Meat Market
Meat Products
Grass Fed Beef Market
Meat Products
United States Bacon Market
Meat Products
Smokehouse Market