
 Poultry Processing Meat Market | 2026-2036
Poultry Processing Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Processing Meat Market Insights
Foodservice distribution is narrowing as consolidated buyers demand just-in-time delivery of portion-controlled cuts. Tyson Foods leverages captive hatchery-to-retail integration to secure volume contracts with national chains. JBS S.A. anchors its position through South American feedlot dominance and export-grade certification. BRF S.A. differentiates via processed-product specialization across Middle Eastern halal markets.
Poultry processing meat encompasses the mechanical conversion of live birds into chilled, frozen, or value-added products through defeathering, evisceration, chilling, and cutting operations, typically achieving carcass temperatures below 4°C within two hours to inhibit microbial proliferation. The output serves retail, institutional foodservice, and further-manufacturing channels requiring standardized yield ratios and shelf-life extension. Fresh meat commands the largest revenue pool among product types due to consumer preference for unaltered texture in home cooking, though processed meat generates superior margins through brine injection, tumbling, and coating technologies. Modified atmosphere packaging captures expanding share as retailers prioritize case-ready presentation with extended color stability.
USDA FSIS inspection protocols, EU hygiene regulation 853/2004, and Codex Alimentarius HACCP guidelines collectively mandate pathogen-reduction performance standards and residue-testing cadences that determine market-access eligibility for exporting nations. China's SAMR import registration requirements and Brazil's MAPA federal inspection seals create additional compliance layers that filter supplier participation. Stakeholders must monitor evolving antimicrobial-resistance policies and alternative-protein substitution rates as dual forces that could reset capacity-planning assumptions.
Market Dynamics
Consolidated foodservice procurement is compressing supplier margins while demanding just-in-time portion control, forcing processors to choose between captive integration and specialized niche positioning.
Growth Catalysts
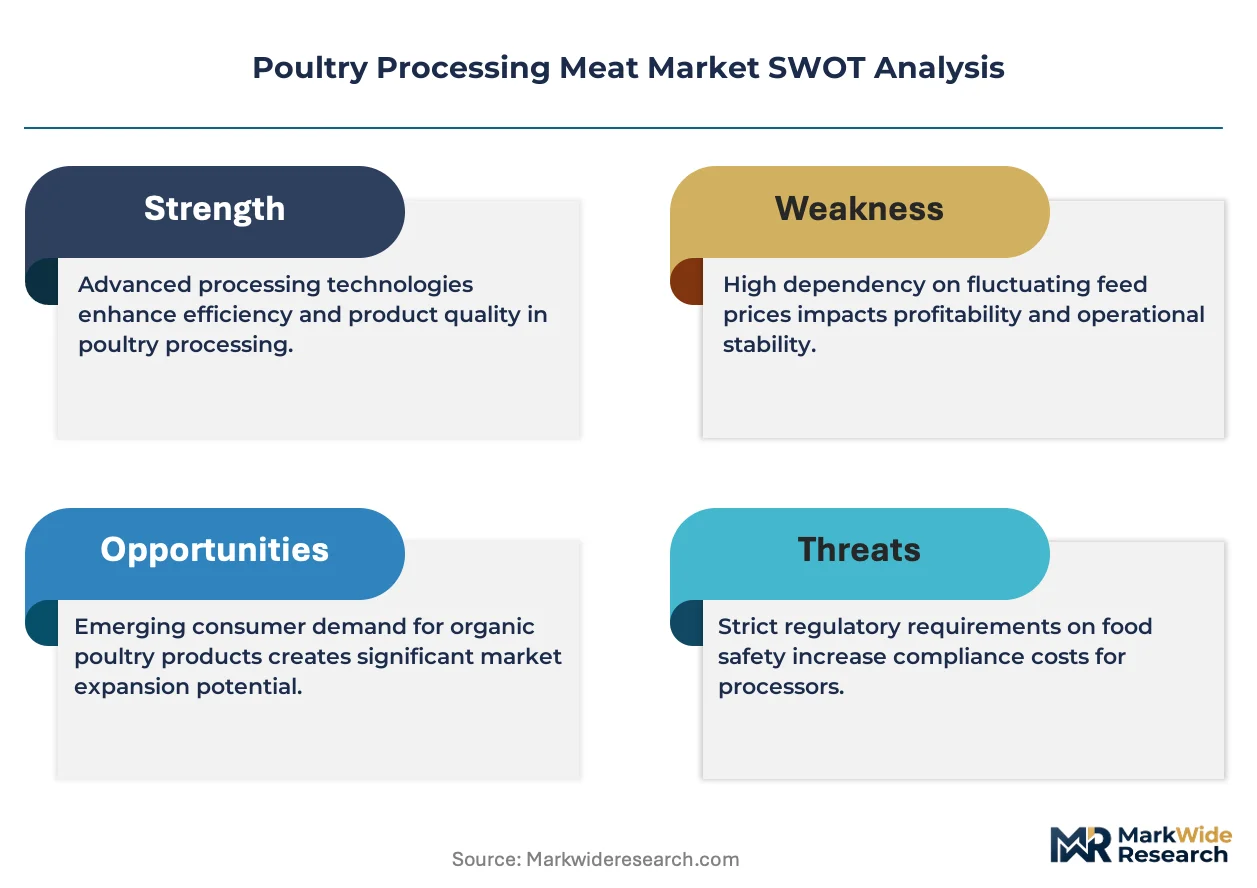
- EU Hygiene Regulation 853/2004:Mandatory HACCP alignment across cold-chain operations is accelerating capital deployment in automated evisceration and rapid-chilling systems, filtering out subscale operators.
- Quick-service restaurant chains:Southeast Asian QSR networks are scaling processed poultry procurement through centralized distribution hubs, creating volume anchors for export-certified processors.
- Modified atmosphere packaging:Retailer demand for case-ready presentation with extended color stability is displacing traditional overwrap methods in premium chilled segments.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings in Brazil's southern corridor directly compress processor margins, with integrated operators holding structural advantage over toll processors.
- USDA FSIS pathogen standards:Salmonella performance standards for imported product create compliance friction that delays market access for non-integrated exporters lacking in-house microbiological laboratories.
- Plant-based substitutes:Cultivated and fermentation-derived proteins are capturing trial among flexitarian consumers in urban European markets, pressuring conventional poultry volume growth in foodservice.
Strategic Opportunities
- Saudi Arabia halal certification:GACC-accredited Chinese processors are entering Middle Eastern markets through SFDA-registered joint ventures, bypassing traditional Brazilian supply dominance.
- Brine injection and tumbling convergence:Combination of high-pressure injection with vacuum tumbling is enabling 20-30% yield enhancement in further-processed segments, opening margin recovery in commodity-challenged markets.
- E-commerce chilled delivery:Direct-to-consumer subscription models in South Korean urban corridors are creating bypass channels around traditional retail consolidation.
Industry Challenges
- Antimicrobial resistance protocols:EU restrictions on coccidiostat use are forcing reformulation of feed additives, requiring 18-24 month revalidation cycles for export certification.
- Automated deboning integration:Robotics deployment demands simultaneous retraining of quality assurance personnel for machine-vision defect detection, creating workforce transition friction.
- Dual-carbon compliance:China's MEE emission intensity targets for slaughter and rendering operations are requiring anaerobic digester retrofits with 4-6 year payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Processing Meat Market |
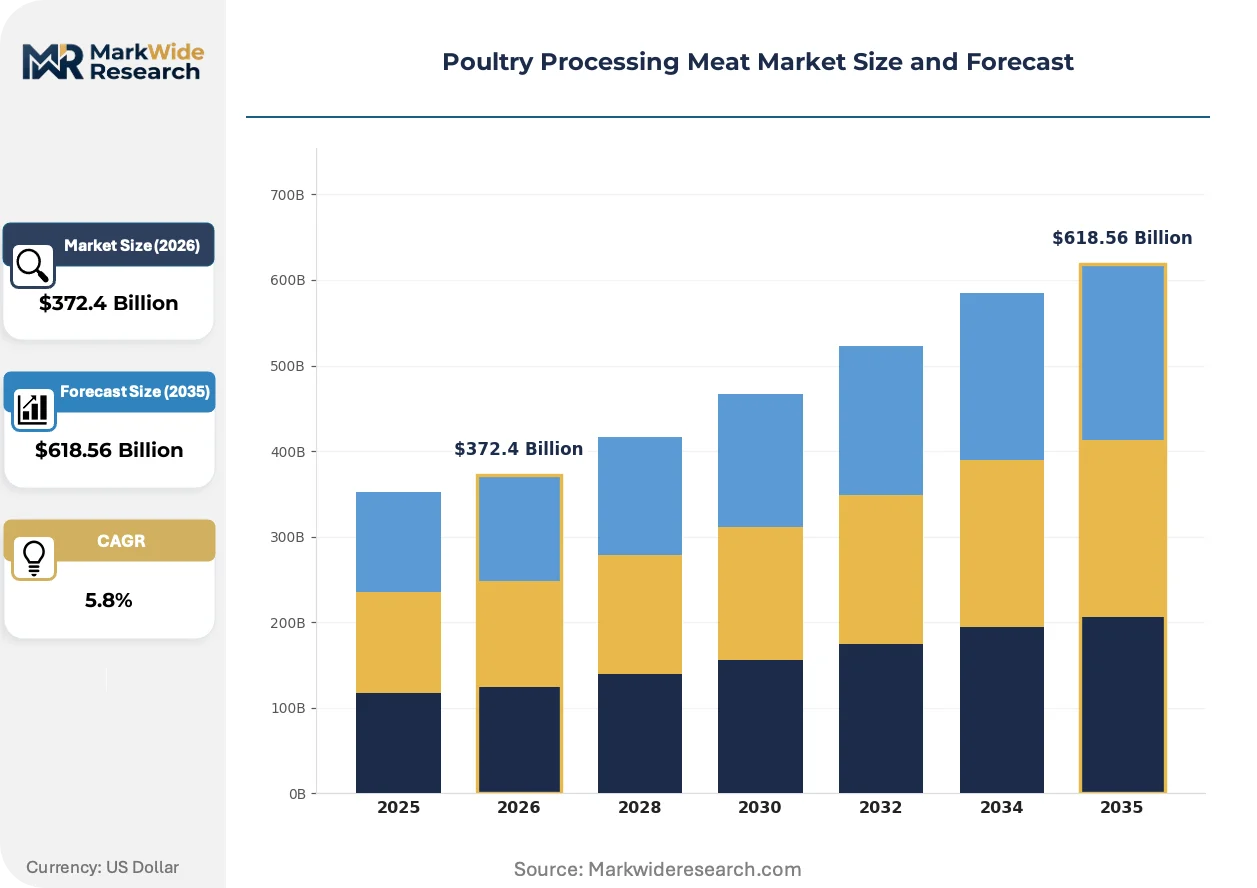
| Market Size in 2026 | $372.4 Billion |
| Market Size in 2035 | $618.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Meat, Frozen Meat, Processed Meat, By-products End User: Retailers, Restaurants, Food Services, Manufacturers Packaging Type: Vacuum Sealed, Modified Atmosphere, Skin Pack, Tray Pack Distribution Channel: Direct Sales, E-commerce, Wholesalers, Distributors |
| Companies Covered | Tyson Foods, JBS S.A., BRF S.A., Cargill Incorporated, Hormel Foods Corporation, WH Group Limited, Pilgrim's Pride Corporation, Charoen Pokphand Foods, Perdue Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Processing Meat Market Trends and Innovations
Processing automation is converging with predictive microbiology to compress chill-chain timelines, while regulatory fragmentation across export markets forces modular plant designs.
High-pressure processing is hybridizing with conventional chilling operations to extend shelf life without thermal degradation. Premium retail chains in Japanese metropolitan markets are adopting HPP-treated cuts for 45-day case-life extension. This convergence is compressing the viable geography for centralized slaughter against distributed further-processing nodes.
REACH authorization requirements for processing aids are restricting phosphates and lactates in EU-bound product, forcing substitution with citrus fiber and seaweed-derived alternatives. Manufacturers serving dual EU and Middle Eastern markets are maintaining parallel formulation lines, raising complexity costs for mid-scale exporters.
Foodservice distributors are unbundling portion-control services from commodity procurement, charging separately for specification development and inventory management. National chain buyers in the United States are consolidating supplier panels to three or fewer per protein category, demanding dedicated production lines and audit transparency. This concentration is visible most acutely in the Southeast, where regional distributors have ceded direct poultry sourcing to national broadliners.
Poultry Processing Meat Market Segmentation
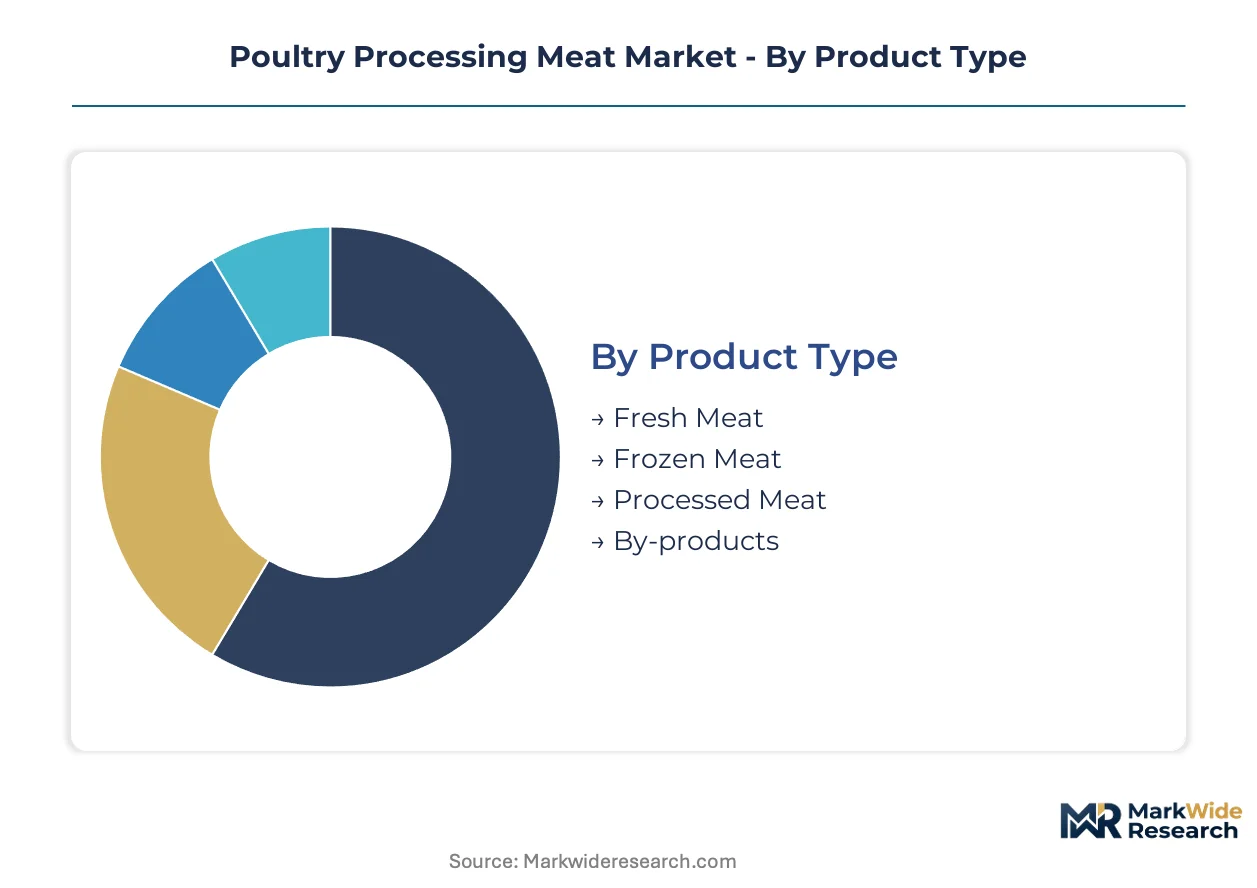
Poultry processing meat segments diverge sharply by preservation method, buyer procurement scale, and shelf-life requirements. Each category maps to distinct margin structures and capital intensity thresholds that determine competitive viability.
Product Type:
Use-case spectrum spans raw commodity through value-added convenience, with preservation state dictating cold-chain infrastructure requirements and geographic reach.
- Fresh Meat:Chilled carcasses and primal cuts maintained below 4°C through rapid-air or immersion chilling retain unaltered texture for home cooking. Brazilian southern corridor processors dominate volume contracts with Southeast Asian QSR chains seeking standardized yield ratios.
- Processed Meat:Brine-injected, tumbled, and coated products achieve 20-30% yield enhancement through mechanical tenderization and phosphate-based moisture retention. EU REACH restrictions on processing aids are forcing citrus fiber substitution, raising formulation complexity for dual-market exporters.
- Frozen Meat:Blast-frozen at -18°C for extended distribution radius, serving institutional buyers with lower turnover velocity.
- By-products:Rendered fats, feather meal, and pet food inputs captured through integrated slaughter operations.
Established volume favors Fresh Meat; emerging adoption favors Processed Meat.
End User:
Buyer scale determines specification precision and audit frequency, with national chains demanding dedicated production lines unavailable to fragmented accounts.
- Restaurants:Full-service and limited-service operators require portion-controlled cuts with consistent cook-loss performance. USDA FSIS Salmonella standards create compliance friction for imported product, privileging integrated processors with in-house microbiological laboratories.
- Food Services:Institutional caterers and contract feeders prioritize cost stability through forward-contracted volume. Brazilian MAPA federal inspection seals anchor procurement decisions for Middle Eastern buyers requiring SFDA-registered supply.
- Retailers:Supermarket chains and independent grocers sourcing case-ready presentation.
- Manufacturers:Further-processors converting raw material into ready-meal ingredients.
Procurement concentration favors Food Services; margin recovery favors Restaurants.
Packaging Type:
Gas-exchange control technologies segment by shelf-life extension and visual presentation requirements, with premium retail commanding advanced barrier materials.
- Modified Atmosphere:Nitrogen and carbon dioxide blends displace oxygen to inhibit pseudomonas growth and maintain myoglobin color stability. Japanese metropolitan retailers are adopting HPP-treated modified atmosphere cuts for 45-day case-life extension.
- Vacuum Sealed:Oxygen exclusion through barrier films enables centralized portioning with distributed retail fulfillment. South Korean e-commerce chilled delivery models leverage vacuum technology for direct-to-consumer subscription bypass channels.
- Skin Pack:Film-to-product adhesion reduces purge accumulation in premium chilled segments.
- Tray Pack:Traditional overwrap methods persisting in price-sensitive emerging markets.
Technology migration favors Modified Atmosphere; cost discipline favors Vacuum Sealed.
Distribution Channel:
Channel structure determines working capital intensity and traceability burden, with consolidated buyers unbundling logistics from commodity procurement.
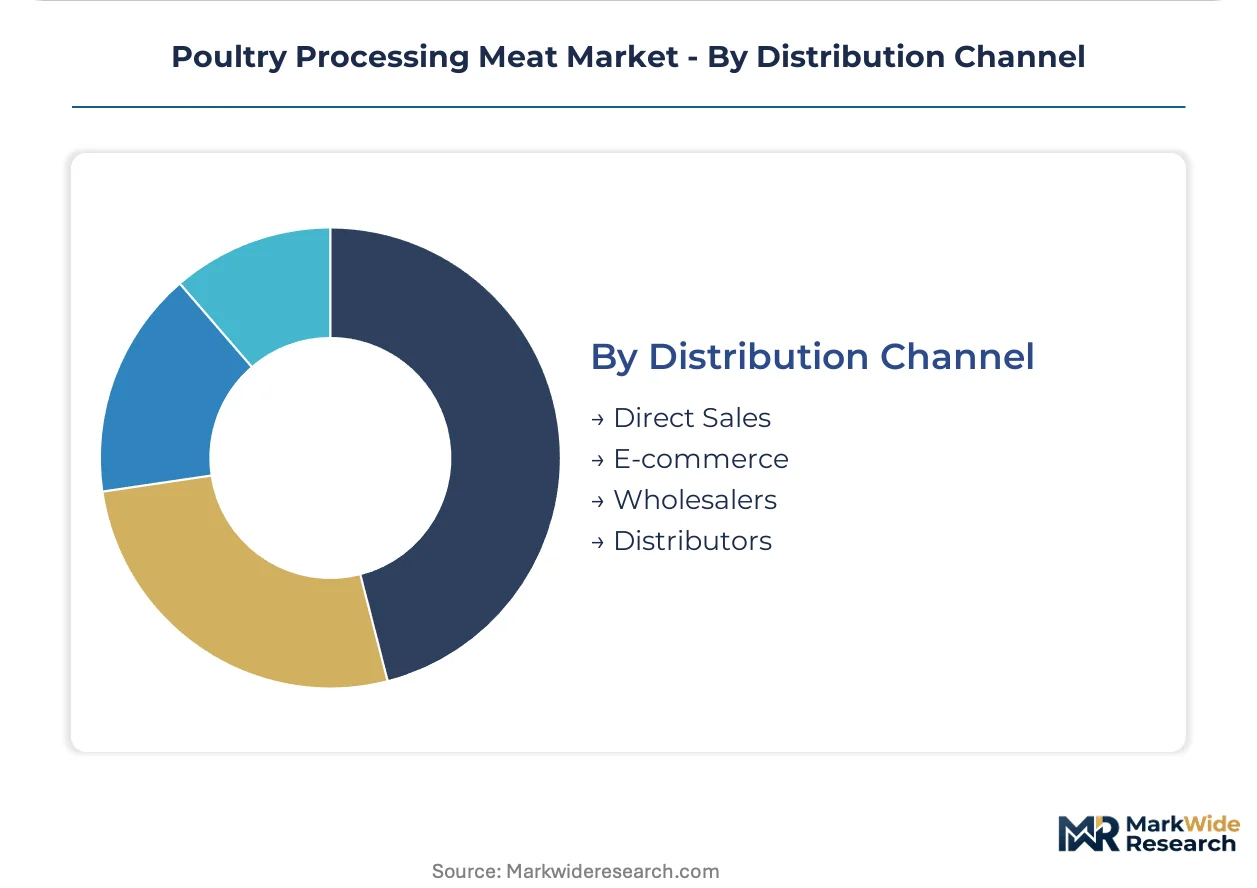
- Distributors:Broadline foodservice operators consolidate supplier panels to three or fewer per protein category, demanding audit transparency and dedicated production lines. Tyson Foods leverages captive hatchery-to-retail integration to secure national chain contracts through this channel.
- E-commerce:Direct-to-consumer platforms bypass traditional retail consolidation in urban corridors with cold-chain last-mile infrastructure. JBS S.A. anchors South American feedlot dominance to serve emerging digital procurement channels.
- Direct Sales:Processor-to-buyer contracts eliminating intermediary margin capture.
- Wholesalers:Traditional terminal market intermediaries serving fragmented independent accounts.
Consolidation pressure favors Distributors; channel innovation favors E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminals anchor Brazilian poultry export capacity, while Rotterdam's cold-chain infrastructure underwrites European distribution efficiency. These logistics assets determine which production corridors capture foodservice procurement contracts.
Brazil
Southeast Asian QSR chains source volume contracts from integrated processors in Paraná and Santa Catarina states. MAPA federal inspection seals anchor export eligibility for Middle Eastern buyers requiring SFDA-registered supply. The southern corridor's feedlot concentration enables yield-standardized production at scale.
United States
National restaurant chains consolidate supplier panels to three or fewer per protein category, demanding dedicated production lines. USDA FSIS Salmonella performance standards for imported product create compliance friction that privileges domestic integrated processors. Georgia and Arkansas processing clusters serve broadline distributor consolidation in the Southeast.
China
GACC-accredited processors are entering Middle Eastern markets through SFDA-registered joint ventures. SAMR import registration requirements and MEE emission intensity targets for slaughter operations are forcing anaerobic digester retrofits. Shandong Peninsula producers are building dual-market certification capacity for EU and halal segments.
Saudi Arabia
SFDA halal certification requirements are filtering supplier participation in foodservice procurement. Domestic processors are partnering with Brazilian exporters to secure year-round supply continuity. Riyadh and Jeddah distribution hubs are consolidating cold-chain infrastructure for centralized QSR delivery.
Germany
EU Hygiene Regulation 853/2004 and REACH authorization restrictions on phosphates are forcing citrus fiber substitution in processed formulations. Bavarian and Lower Saxony processors maintain parallel production lines for EU and Middle Eastern markets. EFSA residue-testing cadences determine market-access eligibility for non-EU suppliers.
Poultry Processing Meat Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The supplier base consolidates around three to five national-scale processors per major protein corridor, with subscale toll operators losing share to captive integration. Two strategic archetypes dominate: hatchery-to-retail integrators securing volume contracts, and processed-product specialists capturing halal and convenience segments. M&A activity concentrates in South American feedlot assets, while capacity expansion targets Southeast Asian QSR procurement hubs.
Among US-based integrators, Tyson Foods exemplifies the hatchery-to-retail archetype through national chain contract concentration. Brazilian processors JBS S.A. and BRF S.A. occupy positions on the export-grade certification tier, with the latter representing processed-product specialization across Middle Eastern markets. These three anchors illustrate how geographic feedlot dominance and regulatory certification competence determine competitive viability.
| Leading Market Players |
|---|
| Tyson Foods |
| JBS S.A. |
| BRF S.A. |
| Cargill Incorporated |
| Hormel Foods Corporation |
| WH Group Limited |
| Pilgrim's Pride Corporation |
| Charoen Pokphand Foods |
| Perdue Farms |
| Others |
Pricing and Supply Chain Analysis
Feed cost volatility in Brazil's southern corridor compresses processor margins and simultaneously widens pricing tier spreads between integrated operators and toll processors, while shaping supply chain consolidation toward captive hatchery-to-slaughter assets.
Pricing Analysis
Volume-discount tiering separates national QSR chains procuring standardized cuts from fragmented foodservice accounts buying spot quantities. Pricing stratifies across export-certified premium, domestic standard, and commodity economy tiers driven by MAPA federal inspection seals and cold-chain compliance investment. Cost compression in the economy tier is intensifying because Brazilian corn and soybean meal price swings transmit directly to processor margins. National chain buyers exhibit lowest price sensitivity due to contract security requirements, while independent restaurants face acute margin pressure from spot market exposure.
Supply Chain Analysis
Tariff exposure between Brazil and Middle Eastern markets dominates supply chain risk assessment for processors dependent on SFDA-registered export corridors. Production gravity centers on Brazil, the United States, and China, with raw material flows drawing from Paraná feedlot concentration, Georgia-Arkansas processing clusters, and Shandong Peninsula integration. Single-source vulnerability in modified atmosphere packaging films creates chokepoint exposure for case-ready retail programs. Distribution runs through broadline foodservice consolidators demanding dedicated production lines and audit transparency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated national chains that now demand captive production lines, squeezing supplier margins and forcing processors to choose between scale commitment and niche specialization.
For Market Incumbents: Insulate margin position through backward integration into hatchery and feedlot operations, particularly in Brazil's southern corridor where feed cost volatility threatens toll processors. Secure MAPA federal inspection seals and USDA FSIS equivalence certification to lock in Middle Eastern and Southeast Asian QSR volume contracts before regulatory compliance costs escalate further. For New Entrants and Emerging Players: Halal-certified further-processing facilities in China's Shandong Peninsula represent the most penetrable entry point, bypassing Brazilian supply dominance through GACC-accredited SFDA joint ventures. Target South Korean e-commerce chilled delivery channels with vacuum-sealed portion control products, leveraging direct-to-consumer subscription models that bypass consolidated retail gatekeepers. For Investors and Strategic Acquirers: EU Hygiene Regulation 853/2004 alignment requirements reshape the acquisition landscape toward processors with automated evisceration and rapid-chilling capital already deployed. Mid-scale Brazilian operators lacking in-house microbiological laboratories face stranded asset risk. Monitor antimicrobial resistance policy evolution in EU feed additive regulations as the signal indicating which export-certified assets will retain market access eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedlot Operations | Captive supply of corn and soybean meal buffers Brazilian processors against commodity margin compression. |
| Dual Certification Investment | Parallel MAPA and USDA FSIS equivalence unlocks simultaneous access to Middle Eastern and Southeast Asian QSR procurement. |
| Automated Deboning Deployment | Machine-vision quality assurance reduces labor dependency while meeting EU Hygiene Regulation throughput standards. |
| Modified Atmosphere Packaging Scale-Up | Nitrogen-carbon dioxide blend capacity captures retailer demand for 45-day case-life extension in Japanese metropolitan markets. |
| E-Commerce Cold-Channel Partnership | South Korean urban subscription models create bypass routes around consolidated broadline distributor control. |
Research Methodology
Initial hypotheses were tested against primary input from poultry processing plant managers, QSR procurement directors, cold-chain logistics operators, and feedlot operations executives, and refined through secondary validation against Brazilian MAPA inspection databases, USDA FSIS import refusal records, EU TRACES certification flows, and Southeast Asian customs trade statistics. Bottom-up volume estimates from processor capacity utilization were triangulated against top-down demand aggregation from foodservice distribution channels.
Demand-supply-balance modeling across the analysis window incorporated preservation state segmentation, buyer procurement scale tiers, and shelf-life requirement thresholds, with CAGRs derived from regression against protein substitution elasticities and QSR expansion trajectories. Forecast inputs included feed cost correlation coefficients and regulatory compliance cost curves for automated chilling system deployment.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, EU carbon border adjustment implementation, or Middle Eastern halal certification reciprocity agreements would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United States Poultry Meat Market
Meat Products
Animal Protein Market
Meat Products
Europe Meat Products Market
Meat Products
Meat Mincers Market
Meat Products
United States Bacon Market
Meat Products
Europe Canned Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Bacon Flavors Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
US Meat Market
Meat Products
Global Processed Pork Meat Market
Meat Products
Emulsified Meat Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Reduced Fat Meat Market
Meat Products
Saudi Arabia Edible Meat Market