
 Asia-Pacific Processed Meat Market | 2026-2036
Asia-Pacific Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Processed Meat Market Outlook
Quick-service restaurants and cloud kitchen operators are unwinding the traditional household-dominant demand structure for processed meat across the Asia-Pacific. WH Group Limited anchors its position through captive pork supply chains stretching from farms to processing plants. Nichirei Corporation dominates Japan's premium chilled segment with precision temperature-controlled logistics. Tyson Foods Inc. competes in Southeast Asia via localized flavor profiles tailored to Indonesian and Filipino palates.
Processed meat comprises animal proteins subjected to curing, smoking, fermentation, thermal processing, or mechanical restructuring to extend shelf life, enhance flavor, or improve texture, typically achieving water activity below 0.85 for ambient stability or maintained under continuous refrigeration at 0-4°C for fresh variants. Its primary commercial purpose is to deliver standardized, portion-controlled protein inputs to retail and food service channels with predictable cost structures and minimal preparation overhead. Sausages and deli meats lead volume due to their versatility across street food, fast-casual, and home cooking contexts, while vacuum packs capture margin pools by reducing spoilage rates in tropical climates with inconsistent cold-chain infrastructure. Bacon occupies a premium niche in urban Chinese and Australian markets where Western breakfast formats are proliferating.
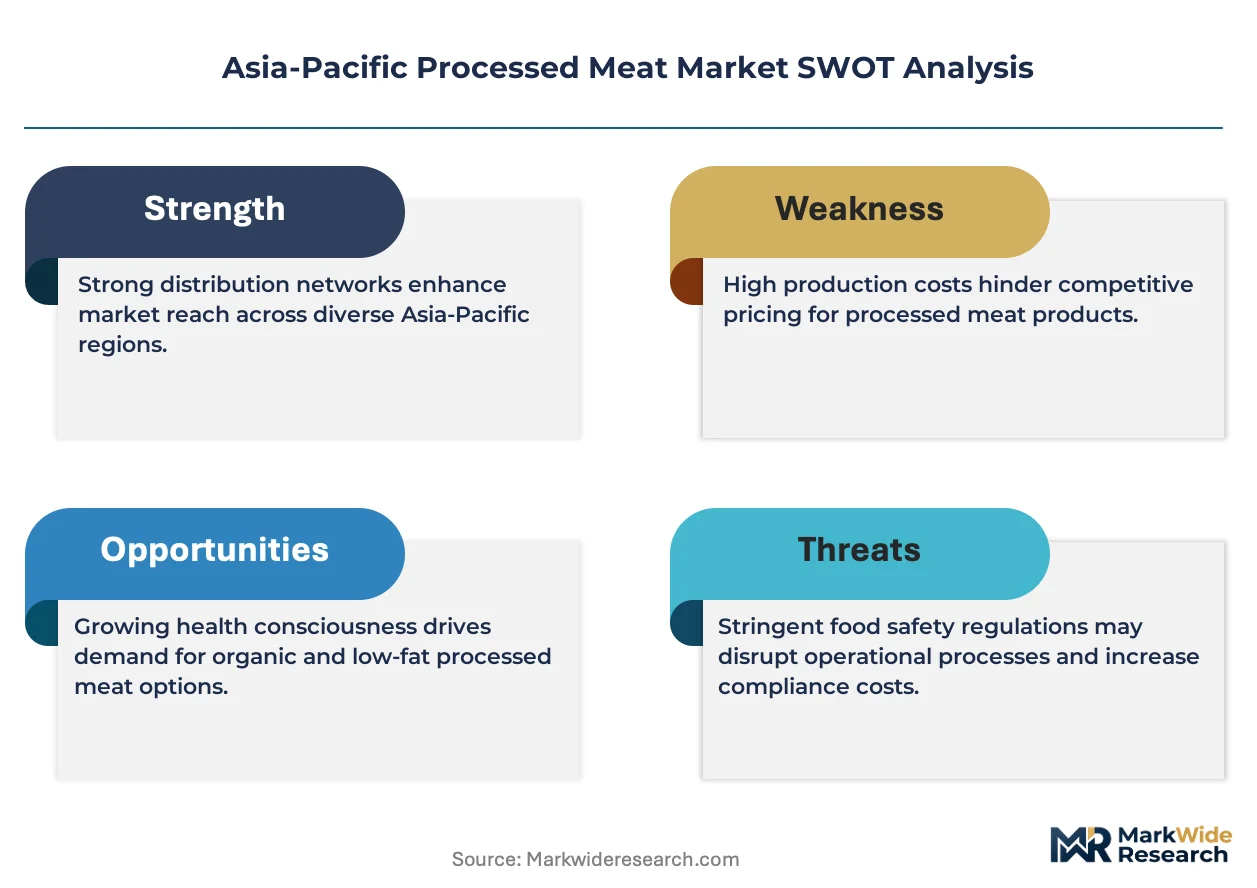
China's SAMR enforces GB standards governing nitrite residues and labeling disclosures, while Japan's Ministry of Health, Labour and Welfare administers stringent import sanitary requirements that shape regional trade flows. Australia's FSANZ and New Zealand's MPI jointly maintain trans-Tasman food standards that influence processed meat formulation for export-oriented Oceania producers. Stakeholders must monitor how Indonesia's BPOM and Philippines' FDA are tightening cold-chain certification rules, as compliance divergence will fragment procurement strategies across archipelagic markets.
Market Dynamics
Food service operators across Southeast Asia are expanding cold-chain procurement of sausages and deli meats, forcing processors to reconfigure production schedules around institutional volume commitments rather than traditional retail replenishment cycles.
Growth Catalysts
- Cloud Kitchen Proliferation:Quick-service restaurants and cloud kitchen operators are unwinding the traditional household-dominant demand structure for processed meat across the Asia-Pacific.
- Indonesian Modern Retail Penetration:Demand concentrates in Indonesia's urban corridor from Jakarta to Surabaya, where modern retail penetration is deepening processed meat access.
- China's SAMR Enforcement:Stricter additive labeling rules are forcing reformulation investments that improve product transparency and consumer trust.
Market Restraints
- Input Cost Volatility:Feed grain prices and live hog procurement costs fluctuate with climate disruptions across Australian and Chinese agricultural zones.
- Supply Concentration Risk:Captive pork supply chains stretching from farms to processing plants create dependency on integrated operators in China.
- Regulatory Friction:Japan's Ministry of Health, Labour and Welfare administers stringent import sanitary requirements that shape regional trade flows and limit supplier diversification.
Strategic Opportunities
- Underpenetrated Philippine Archipelago:Cold-chain certification gaps in island provinces present first-mover advantages for compliant processors establishing regional distribution hubs.
- Precision Temperature-Controlled Logistics:Nichirei Corporation's model demonstrates margin capture potential in Japan's premium chilled segment through continuous 0-4°C integrity.
- PLI-Aligned Localized Flavor Development:Tailored formulations for Indonesian and Filipino palates unlock food service contract volumes unavailable to standardized import portfolios.
Industry Challenges
- Cold-Chain Certification Timeline:Indonesia's BPOM and Philippines' FDA are tightening cold-chain certification rules, extending product approval cycles by months.
- Refrigeration Infrastructure Capex:Vacuum pack margin pools require continuous refrigeration investment in tropical climates with inconsistent grid reliability.
- Formulation Reformulation Costs:GB standard compliance for nitrite residues demands laboratory validation and label redesign across existing product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Processed Meat Market |
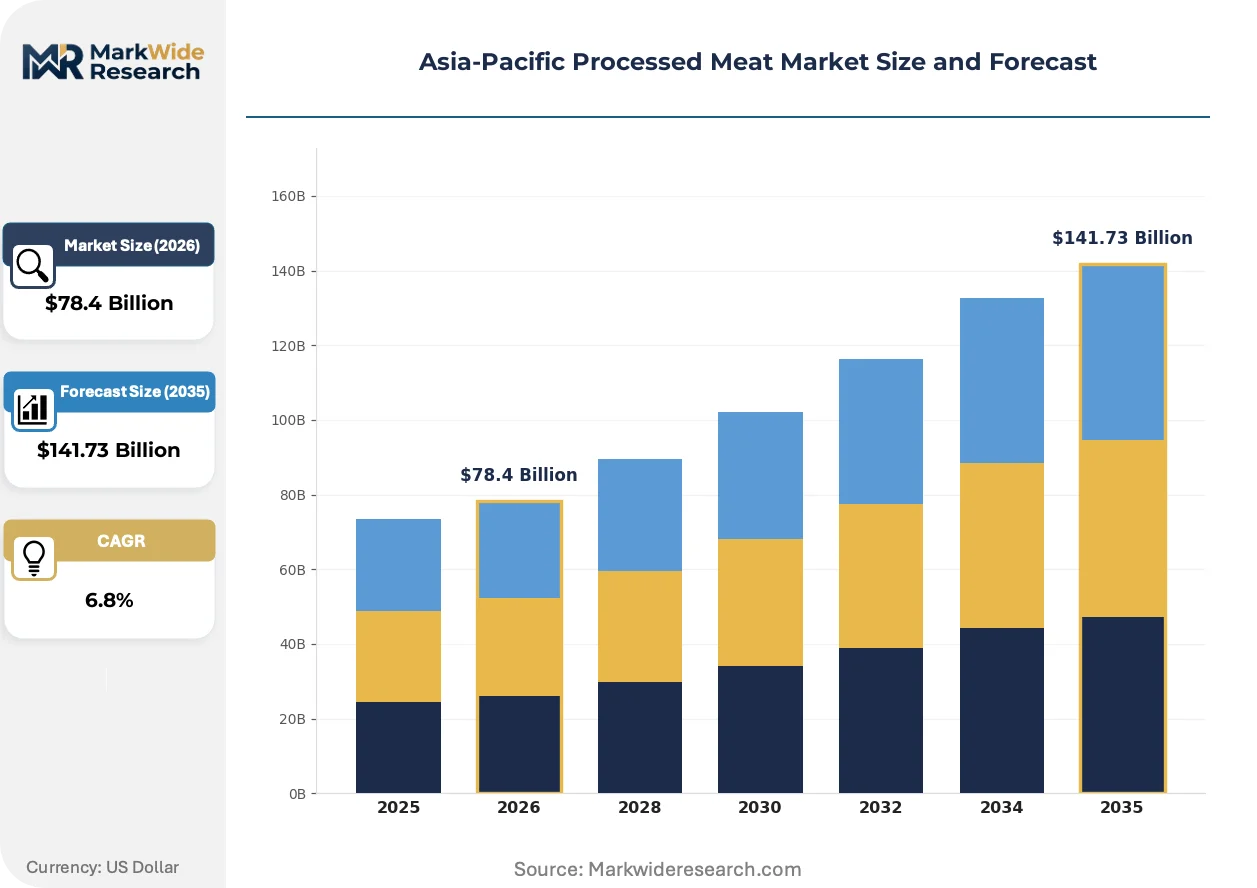
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
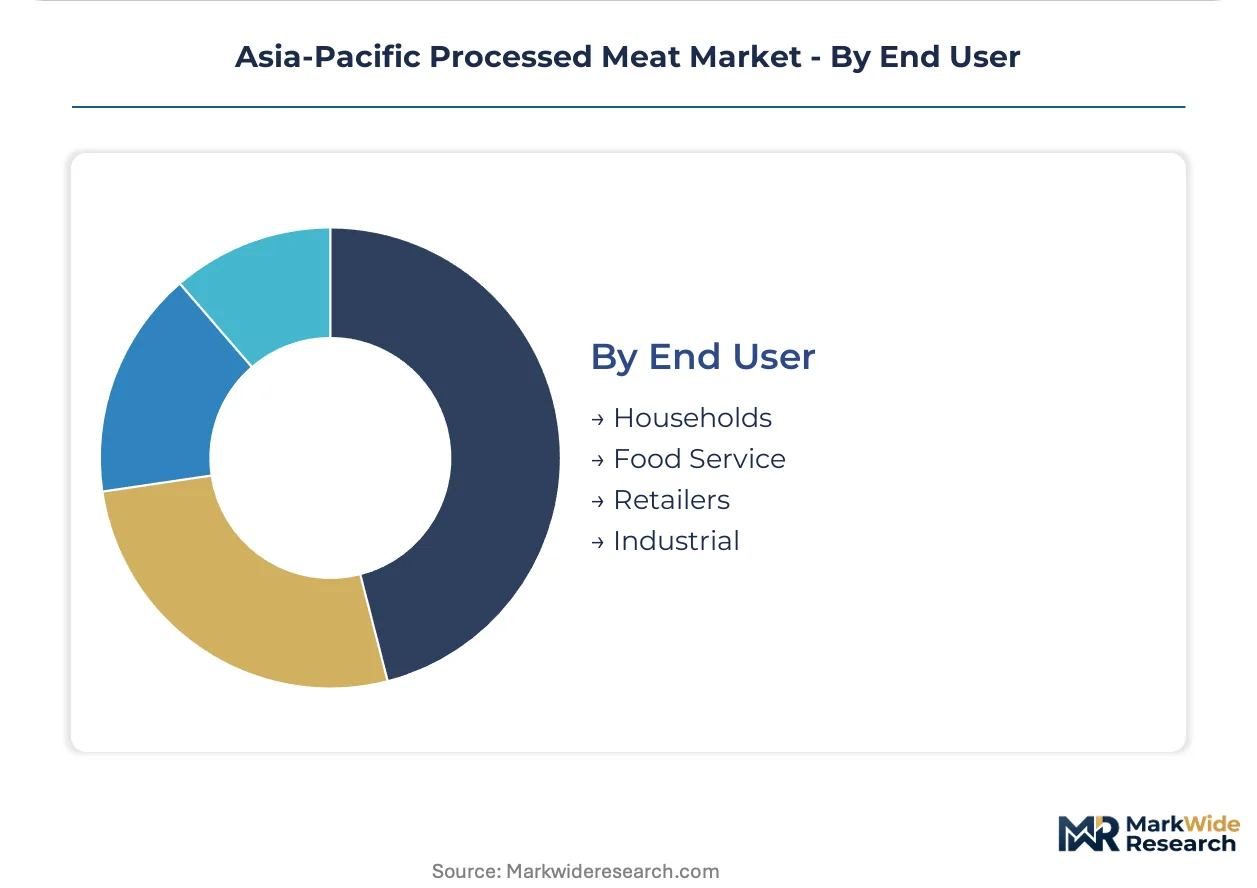
| Segmentation | Product Type: Sausages, Bacon, Ham, Deli Meats Packaging Type: Vacuum Packs, Cans, Pouches, Trays Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale End User: Households, Food Service, Retailers, Industrial |
| Companies Covered | Tyson Foods Inc., NH Foods Ltd., WH Group Limited, Smithfield Foods, Inc., Pilgrim's Pride Corporation, JBS S.A., Nichirei Corporation, Cargill Incorporated, Hormel Foods Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Processed Meat Market Strategic Shifts
Refrigeration technology and packaging science are compressing spoilage windows in tropical distribution, while regulatory disclosure mandates and food service procurement centralization are rewiring competitive positioning across the Asia-Pacific processed meat value chain.
Modified atmosphere packaging systems are extending shelf life for fresh processed meat variants without freezing degradation. Quick-service chains in Thailand and Vietnam are adopting these systems at accelerating rates for their commissary operations. The technology is miniaturizing distribution economics, enabling direct-to-kitchen delivery models that bypass traditional wholesale layers.
China's SAMR enforcement of GB standards governing nitrite residues and labeling disclosures is forcing processors to rebuild formulation databases and supply chain documentation. Industrial consequence includes delayed product launches and elevated compliance staffing across manufacturing facilities. Fresh sausage categories face the steepest reformulation burden, with operators accelerating clean-label development to preempt enforcement actions.
Buyer concentration among consolidated food service groups is compressing supplier negotiation leverage across Southeast Asia. Traditional wet-market wholesalers in Indonesia and Vietnam are losing volume share to contracted procurement desks at cloud kitchen aggregators and quick-service franchise networks. This shift is most visible in the Jakarta-Surabaya corridor, where modern retail and institutional buyers now dictate product specifications and delivery cadences previously set by fragmented traditional trade.
Asia-Pacific Processed Meat Market Segmentation
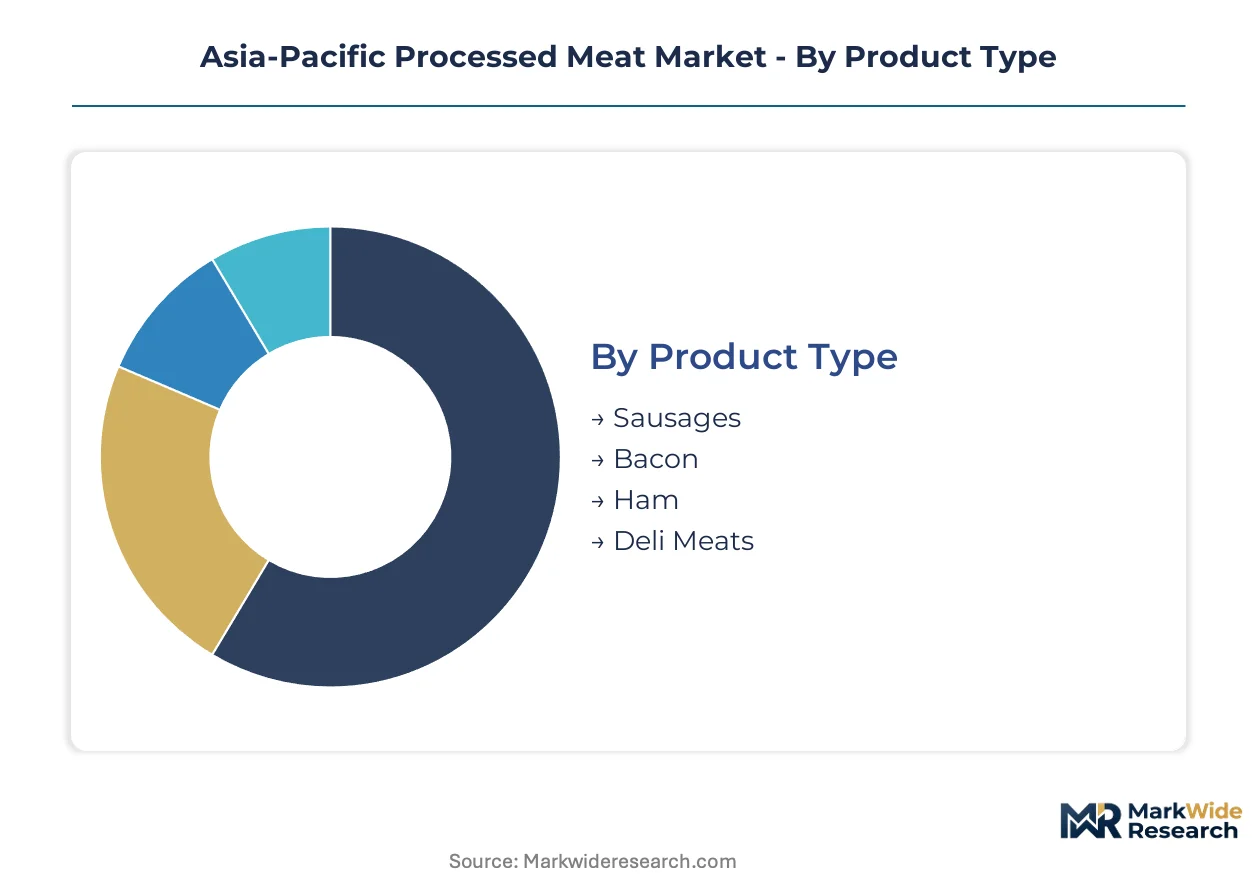
Segmentation in the Asia-Pacific processed meat market reveals how regulatory pressure, cold-chain infrastructure gaps, and food service procurement centralization fragment commercial opportunity across distinct product, packaging, and channel configurations. Understanding these divides exposes where margin pools concentrate and where compliance investments yield defensive positioning.
Product Type:
GB standards from China's SAMR enforce divergent nitrite residue limits across fresh versus shelf-stable formats, reshaping which categories absorb the heaviest reformulation burden.
- Sausages:Comminuted meat emulsions stuffed into casings, achieving water activity below 0.85 for ambient variants or maintained at 0-4°C for fresh retail. Demand concentrates in Indonesia's Jakarta-Surabaya corridor where cloud kitchen aggregators specify portion-controlled formats for commissary operations; BPOM cold-chain certification timelines extend approval cycles for imported raw-casing variants.
- Deli Meats:Cured and cooked whole-muscle products sliced for food service portioning, requiring continuous refrigeration integrity. Japanese quick-service chains and Vietnam's expanding fast-casual networks drive procurement volumes; METI import sanitary requirements limit supplier diversification for premium chilled shipments into Tokyo-Osaka logistics hubs.
- Bacon:Cured pork belly strips targeting Western breakfast proliferation in urban Chinese and Australian markets.
- Ham:Brined and thermally processed leg sections, with canned variants dominating Philippine archipelago distribution where grid reliability falters.
Sausages handle the majority of throughput; deli meats are gaining share fastest as food service contracts displace traditional retail replenishment.
Packaging Type:
Cost tier stratification separates premium cold-chain-dependent formats from economy ambient-stable alternatives, with tropical climate spoilage rates dictating investment recovery calculations.
- Vacuum Packs:Barrier films extracting headspace oxygen to extend refrigerated shelf life without freezing degradation. Thailand's quick-service commissaries and Vietnam's cloud kitchen networks adopt these systems at accelerating rates; modified atmosphere variants enable direct-to-kitchen delivery models bypassing wholesale layers.
- Cans:Thermally processed hermetic containers achieving commercial sterility for ambient distribution. Philippine island provinces and Indonesian outer regions rely on canned formats where continuous refrigeration infrastructure remains underdeveloped; BPOM tightening of cold-chain certification rules amplifies this dependency.
- Pouches:Flexible retort or vacuum structures offering weight efficiency for export logistics.
- Trays:Modified atmosphere overwrap systems for fresh retail presentation in Australian and Chinese supermarkets.
Vacuum packs command the premium margin tier; cans retain volume dominance in archipelagic markets with certification gaps.
Distribution Channel:
Customer type concentration among institutional buyers is compressing traditional wholesale structures and elevating contracted procurement desks.
- Supermarkets:Modern retail formats with dedicated refrigerated sections, deepening processed meat access in Indonesia's urban corridor. Jakarta-Surabaya chains now dictate product specifications and delivery cadences previously controlled by fragmented wet-market wholesalers; private label expansion forces branded processors to defend shelf space through promotional frequency.
- Food Service Wholesale:Institutional procurement desks serving cloud kitchen aggregators and quick-service franchise networks. Buyer consolidation across Southeast Asia compresses supplier negotiation leverage; Tyson Foods and WH Group compete for contract volumes through localized flavor development aligned with Indonesian and Filipino palate preferences.
- Convenience Stores:Small-format retail with limited refrigeration capacity favoring ambient-stable and short-case configurations.
- Online Retail:Direct-to-consumer platforms requiring last-mile cold-chain integrity for fresh variants.
Food service wholesale channels are expanding most quickly; supermarkets retain the largest absolute volume base.
End User:
Application maturity separates established household consumption patterns from emerging institutional demand structures rewiring production scheduling.
- Food Service:Quick-service restaurants, cloud kitchens, and institutional catering operations requiring standardized, portion-controlled protein inputs with predictable cost structures. Operators across Southeast Asia are expanding cold-chain procurement of sausages and deli meats, forcing processors to reconfigure production schedules around institutional volume commitments rather than traditional retail replenishment cycles.
- Households:Individual consumers purchasing for home cooking contexts, historically dominant but losing share to prepared food alternatives. Urban Chinese and Australian markets show Western breakfast format adoption elevating bacon and premium ham purchases; elsewhere, convenience demands shift volume toward ready-to-eat and pre-cooked formats.
- Retailers:Intermediary buyers merchandising to final consumers, facing margin pressure from direct procurement relationships.
- Industrial:Further-processing manufacturers incorporating processed meat as ingredient inputs.
Food service end users are climbing the fastest on share; households maintain the deepest volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's refrigerated container throughput anchors China's processed meat import corridor, while the Jakarta-Surabaya toll road network underwrites Indonesia's cold-chain expansion. These infrastructure assets concentrate procurement gravity across the region's two largest demand centers.
China
Cloud kitchen aggregators in Beijing and Shanghai are reconfiguring sausage procurement toward portion-controlled formats. SAMR enforcement of GB nitrite residue standards is forcing reformulation investments across fresh processed meat lines. Yangtze River Delta processors absorb the heaviest compliance burden as enforcement concentrates in Shanghai-Ningbo logistics hubs.
Indonesia
Modern retail penetration along the Jakarta-Surabaya corridor is displacing wet-market wholesalers with contracted procurement desks. BPOM cold-chain certification timelines are extending approval cycles for imported raw-casing sausage variants. Surabaya's emerging food service cluster now dictates delivery cadences previously controlled by fragmented traditional trade.
Japan
Quick-service chains in Tokyo-Osaka logistics corridors are driving deli meat volumes through precision temperature-controlled specifications. METI import sanitary requirements limit supplier diversification for premium chilled shipments. Kanto region cold-chain infrastructure captures margin pools through continuous 0-4°C integrity mandates.
Vietnam
Fast-casual network expansion in Ho Chi Minh City is accelerating modified atmosphere packaging adoption for commissary operations. The country's national food safety regulator is tightening import documentation for processed meat derivatives. Mekong Delta distribution hubs are miniaturizing economics through direct-to-kitchen delivery models.
Australia
FSANZ standards alignment with New Zealand's MPI is shaping export-oriented formulation for Oceania producers. Western breakfast format proliferation in Sydney and Melbourne is elevating bacon and premium ham purchases. Victorian processing facilities are defending shelf space against private label expansion through promotional frequency.
Asia-Pacific Processed Meat Market Competitive Environment
Listed leaders compete with private specialists across supply chain control dimensions, creating a tiered structure where scale advantages clash with captive sourcing flexibility. WH Group Limited anchors the integrated operator archetype through farm-to-plant pork supply chains, while Tyson Foods Inc. exemplifies the multinational flavor localization model. Three strategic archetypes dominate: integrated livestock-processor hybrids, multinational flavor adaptors, and precision logistics specialists. Competitive moves concentrate on backward integration into livestock supply and geographic flavor portfolio diversification.
Within the integrated operator tier, WH Group Limited represents captive supply chain control from farms through processing plants. Tyson Foods Inc. and Nichirei Corporation exemplify divergent specialization vectors—Tyson occupying the multinational flavor adaptation position across Southeast Asian procurement desks, Nichirei anchoring premium chilled logistics integrity in Japanese metropolitan corridors. These three entities collectively illustrate how scale, integration depth, and temperature-controlled precision define competitive positioning across the region's fragmented regulatory and infrastructure environments.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| NH Foods Ltd. |
| WH Group Limited |
| Smithfield Foods, Inc. |
| Pilgrim's Pride Corporation |
| JBS S.A. |
| Nichirei Corporation |
| Cargill Incorporated |
| Hormel Foods Corporation |
| Others |
Value Chain & Pricing Dynamics
China's SAMR cold-chain certification gates both supply qualification and price differentiation across the Asia-Pacific processed meat corridor. Processors lacking GB-compliant documentation face automatic exclusion from institutional procurement desks, while certified operators command premium positioning in Jakarta-Surabaya and Tokyo-Osaka logistics hubs.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement contracts across Southeast Asian cloud kitchen networks. Three-tier pricing separates premium chilled deli meats from standard vacuum-packed sausages and economy canned formats. Price differentiation rests on cold-chain integrity certification and localized flavor development investment. Cost compression in standard tiers is intensifying because feed grain volatility and live hog procurement fluctuations squeeze processor margins. Quick-service franchise networks show least price sensitivity due to standardized menu cost structures, while traditional wet-market wholesalers face acute margin pressure from modern retail displacement.
Supply Chain Analysis
China and Indonesia anchor live hog production and primary processing capacity across the regional value chain. Australia's grain-fed pork operations and Vietnam's emerging slaughter capacity feed into secondary processing networks. Raw material dependencies center on feed corn and soybean meal imports, live animal procurement contracts, and cold-chain equipment components. Single-source vulnerability concentrates in integrated operators controlling captive farm-to-plant supply chains. Distribution runs through refrigerated container corridors at Port Shanghai and Jakarta-Surabaya toll road networks, with last-mile fragmentation in Philippine archipelago provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cold-chain logistics capability scarcity defines competitive moats in this market. Operators possessing continuous 0-4°C integrity documentation capture institutional contract volumes unavailable to uncertified competitors, while formulation laboratories capable of rapid clean-label reformulation absorb SAMR compliance burdens that strand legacy processors.
For Market Incumbents: Compound defensive positioning through backward integration into feed grain procurement and captive livestock supply chains. WH Group's farm-to-plant model demonstrates margin protection against input cost volatility. Accelerate clean-label formulation database rebuilds to preempt GB standard enforcement actions. Channel control through direct procurement desk relationships with cloud kitchen aggregators locks out competing suppliers in Jakarta-Surabaya corridor. For New Entrants and Emerging Players: Cold-chain certification service gaps in Philippine island provinces present first-mover entry points where BPOM documentation bottlenecks strand imported competitors. Target underpenetrated archipelago distribution through compliant regional hub establishment. Direct-to-kitchen delivery models bypassing traditional wholesale layers unlock food service contract access unavailable to established import portfolios. For Investors and Strategic Acquirers: Indonesia's BPOM and Philippines' FDA cold-chain certification tightening reshapes the acquisition landscape toward processors with pre-qualified documentation libraries. Long-term viability centers on operators capable of navigating divergent regulatory regimes across archipelagic markets. Precision temperature-controlled logistics specialists with established Kanto or Yangtze River Delta infrastructure represent priority acquisition archetypes. Recalibration signal: material acceleration in SAMR enforcement scope or BPOM approval timeline extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Livestock Supply | Captive hog procurement shields WH Group from Australian and Chinese feed grain price volatility. |
| Clean-Label Formulation Development | Rapid reformulation capability absorbs SAMR nitrite residue compliance burdens that strand legacy operators. |
| Cold-Chain Certification Investment | BPOM-compliant documentation unlocks institutional procurement volumes in Jakarta-Surabaya corridor. |
| Localized Flavor Portfolio Expansion | Tyson Foods' Indonesian and Filipino palate adaptation secures food service contract exclusivity. |
| Precision Logistics Infrastructure | Nichirei's continuous 0-4°C integrity captures premium margin pools in Tokyo-Osaka metropolitan corridors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs and secondary validation protocols. Food service procurement directors at cloud kitchen aggregators, quick-service franchise operations heads, cold-chain logistics managers, and regulatory affairs specialists at processing facilities provided operational perspective. Secondary sources included SAMR GB standard filings, BPOM certification databases, Japan's METI import sanitary documentation, and trade flow records from Port Shanghai refrigerated container throughput. Bottom-up volume modeling and top-down value reconciliation triangulated market estimates.
Across the analysis window, projections incorporate product type segmentation by water activity and thermal processing method, packaging format tiering by refrigeration dependency, and distribution channel stratification between institutional procurement desks and traditional wholesale structures. CAGRs derive from regression analysis against protein input cost indices and modern retail penetration curves. Forecast inputs include cold-chain infrastructure investment trajectories and regulatory enforcement intensity assumptions for nitrite residue standards.
Forecasts assume regulatory continuity in China's SAMR, Indonesia's BPOM, and Japan's METI regimes; material policy shifts would require re-modeling. Specific risks include feed grain price spikes from Australian drought cycles, grid reliability failures disrupting tropical cold-chain integrity, and accelerated SAMR clean-label mandates forcing unplanned reformulation costs. Recalibration cycles align with material shifts in enforcement scope or infrastructure investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Germany Meat Products Market
Meat Products
South Africa Processed Meat Market
Meat Products
Blended Meat Market
Meat Products
Pepperoni Foods Market
Meat Products
Pork Meat Market
Meat Products
Chicken Fat Market
Meat Products
Europe Poultry Meat Market
Meat Products
Germany Poultry Meat Market
Meat Products
Beef Tallow Market
Meat Products
North America Bacon Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Bacon Flavors Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Europe Meat Products Market
Meat Products
Emulsified Meat Market