
 Germany Meat Products Market | 2026-2036
Germany Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Meat Products Market Insights
Subscription-based cold-chain monitoring and predictive maintenance contracts for processing equipment is recalibrating how German meat producers monetize customer relationships. Tönnies Holding GmbH leverages its integrated slaughter-to-retail network to sustain volume leadership across pork and beef categories. Westfleisch SCE anchors cooperative sourcing structures that dominate regional supply in northwestern Germany. Vion Food Group differentiates through specialized halal and organic certification lines serving export channels.
Germany meat products encompass fresh, chilled, and processed animal proteins governed by EU hygiene regulations and national Lebensmittel- und Futtermittelgesetzbuch standards, with critical parameters including pH values, water-holding capacity, and cold-chain integrity from slaughter through retail. Pork maintains structural dominance as the highest-volume category, though poultry shows the fastest growth trajectory driven by health-positioned consumer shifts. Vacuum-sealed packaging commands premium shelf-life extension margins, while butcher shops retain loyalty in regional sausage and cured-meat segments despite supermarket consolidation.
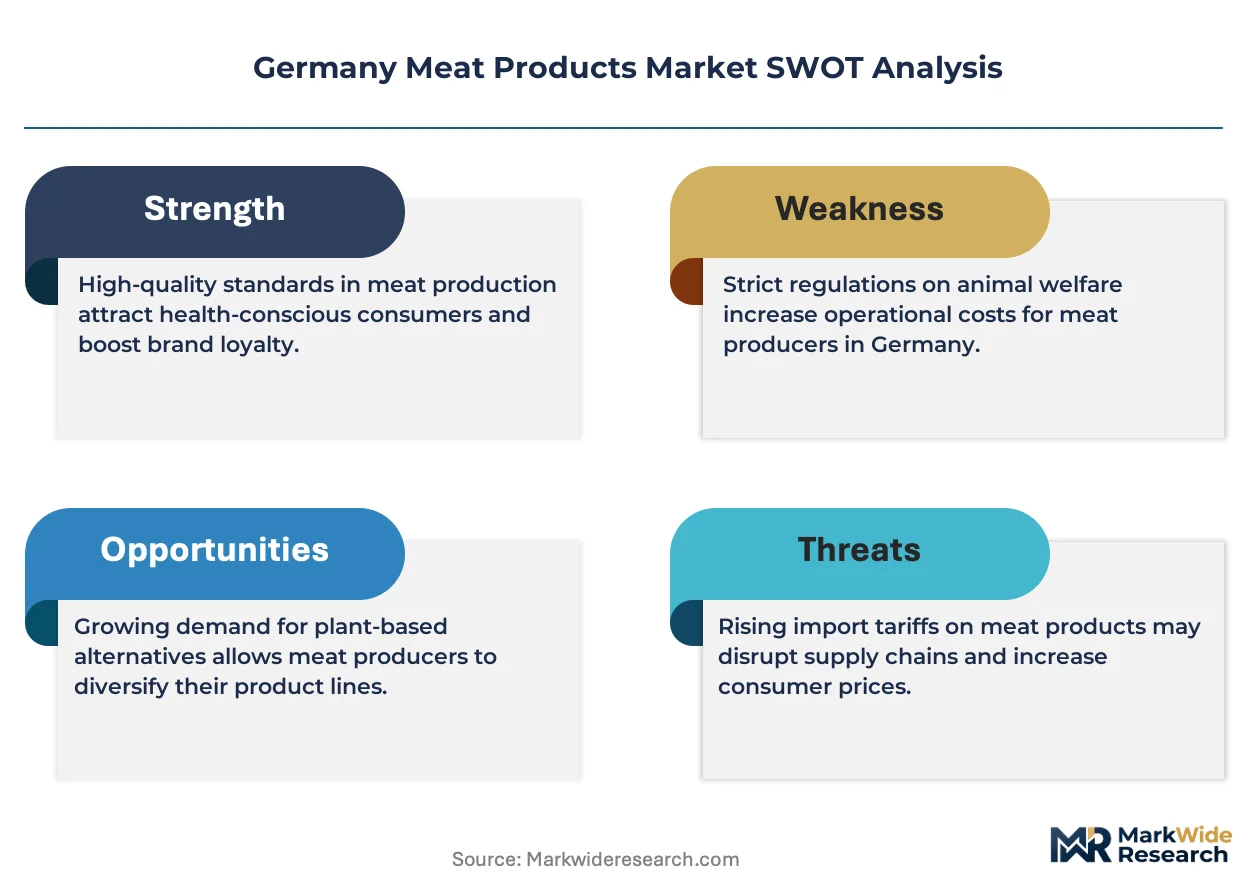
The Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces strict HACCP and traceability protocols, while EU Green Deal agricultural targets pressure methane reduction and feed-source documentation across the supply chain. Germany's Tierschutzgesetz mandates specific stocking densities and slaughtering methods that elevate compliance costs for domestic producers relative to import competitors. Stakeholders must monitor evolving carbon-footprint labeling requirements and alternative protein substitution rates to calibrate capacity investments and product portfolio priorities.
Market Dynamics
German meat processors face intensifying pressure from the EU Farm to Fork Strategy's animal welfare mandates, which elevate compliance costs while import competitors operate under looser standards. This structural asymmetry is compressing domestic margins and accelerating consolidation.
Growth Catalysts
- EU Green Deal agricultural targets:Methane reduction mandates and feed-source documentation requirements create first-mover advantages for domestic producers with verified supply chains.
- North Rhine-Westphalia processing clusters:Proximity to Dutch border infrastructure enables cross-border cold-chain efficiencies and export hub positioning.
- High-pressure processing technology:Adoption extends shelf life without chemical preservatives, opening premium retail placement for value-added cuts.
Market Restraints
- Tierschutzgesetz compliance costs:Specific stocking densities and slaughtering methods required by German animal welfare law inflate domestic production expenses relative to Polish and Danish imports.
- Feed grain price volatility:Ukraine supply disruptions and energy-intensive fertilizer production compress margins across pork and poultry operations.
- Plant-based protein substitution:Pea and soy protein isolates capture flexitarian consumers in urban centers, eroding volume in traditional sausage categories.
Strategic Opportunities
- Halal certification lines:Export channels into Turkey and Gulf states reward specialized processing capabilities that most EU competitors lack.
- Subscription cold-chain monitoring:Predictive maintenance contracts for processing equipment transform capital expenditure into recurring revenue streams.
- Baden-Württemberg organic demand:Affluent consumer base in southwestern Germany pays structural premiums for Demeter-certified products with full traceability.
Industry Challenges
- Veterinary inspector shortages:Bundesamt für Verbraucherschutz und Lebensmittelsicherheit staffing gaps delay slaughterhouse approvals and compress processing schedules.
- HACCP traceability system integration:Legacy paper-based recordkeeping at mid-sized cooperatives conflicts with real-time digital compliance requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Meat Products Market |
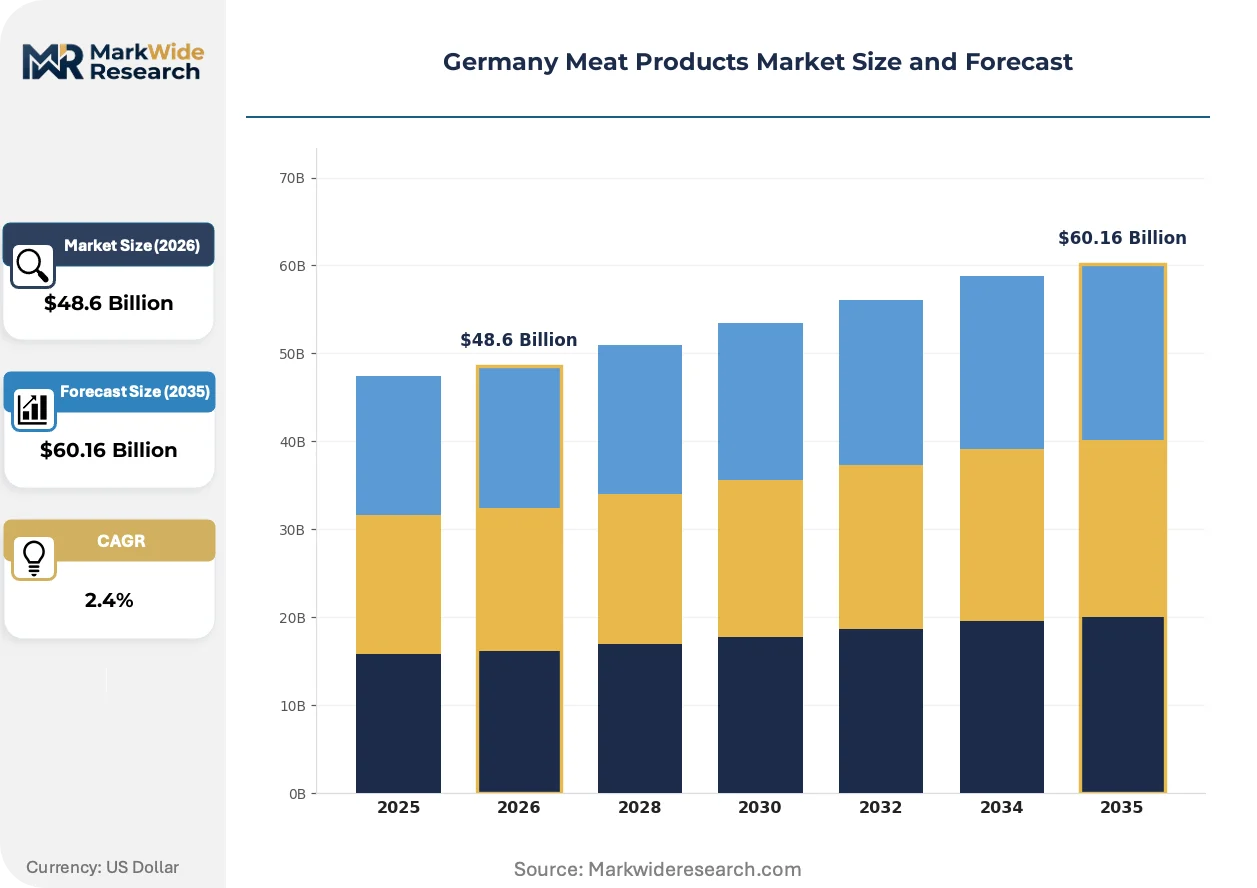
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $60.16 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Packaging Type: Bags, Cans, Trays, Vacuum Sealed Distribution Channel: Supermarkets, Butcher Shops, Online Retail, Convenience Stores End User: Households, Restaurants, Catering Services, Food Processing |
| Companies Covered | Tönnies Holding GmbH, Westfleisch SCE, Vion Food Group, PHW Group, Müller Fleisch GmbH, Heidemark GmbH, Rothkötter Group, Plukon Food Group, Premium Food Group ApS & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Meat Products Market Trends and Innovations
Digitalization is penetrating German meat operations from farm gate to retail shelf, with sensor networks and automation compressing cycle times while regulatory transparency demands intensify.
Blockchain-enabled traceability platforms is converging with IoT temperature logging to create immutable cold-chain records. Major retail chains now mandate this dual-layer verification for private-label fresh meat contracts. The technology is converging with predictive analytics to preempt spoilage events before they trigger regulatory violations.
The EU Green Deal's Farm to Fork Strategy tightens methane reporting obligations across livestock operations. German producers must document feed conversion ratios and manure management practices with granular precision. Pig farming in Lower Saxony faces the steepest compliance curve due to concentrated operation densities.
Direct sourcing contracts between processors and restaurant groups are displacing traditional wholesale intermediaries. Large-scale catering operators now negotiate specification-grade agreements for standardized cuts with fixed-volume commitments. This pattern concentrates in Bavaria's hospitality-dense urban corridors.
Germany Meat Products Market Segmentation
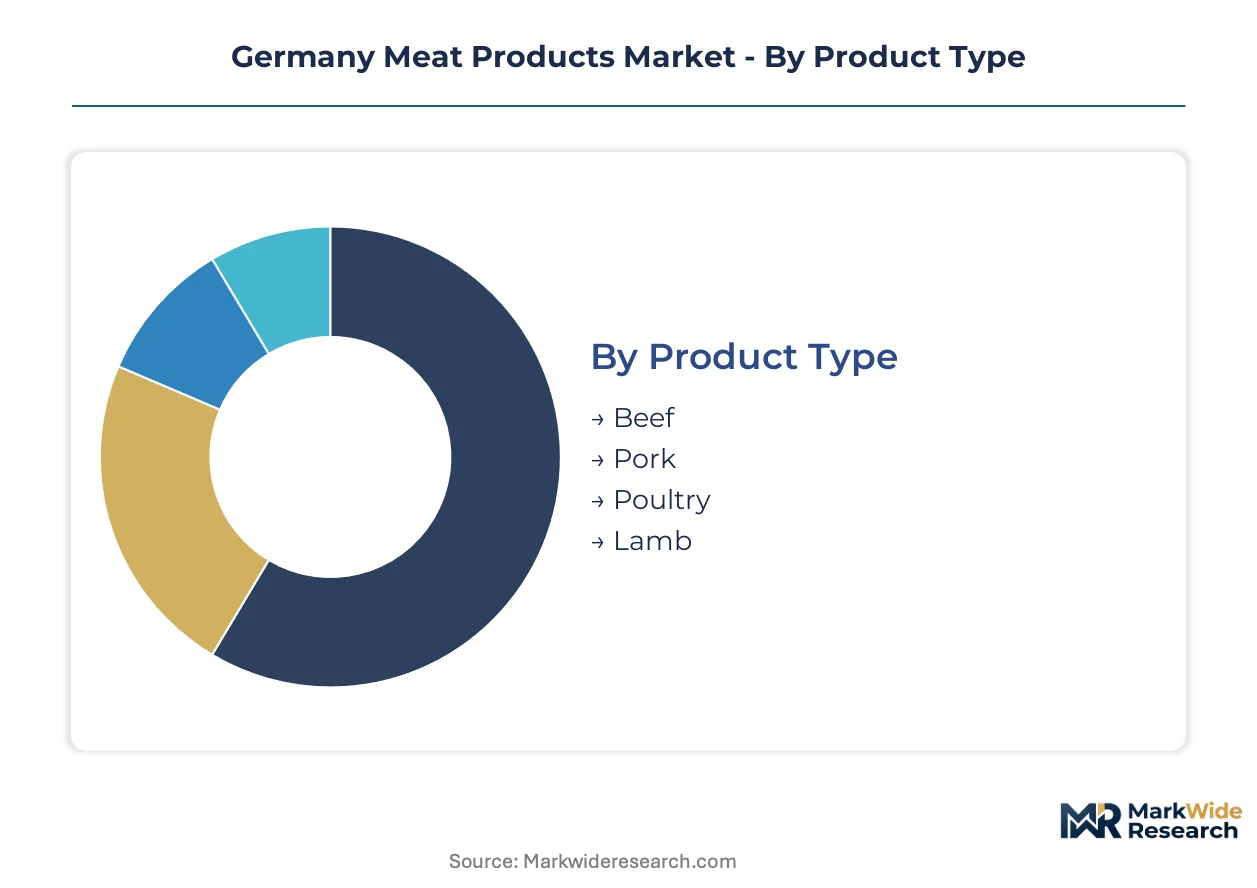
Segmentation in the Germany meat products market reveals how regulatory pressure and channel evolution are reshaping procurement priorities. Producers calibrate capacity investments across product lines and packaging formats based on diverging margin profiles and compliance burdens.
Product Type:
Supply concentration clusters around species with established slaughter infrastructure and cold-chain density in North Rhine-Westphalia and Lower Saxony.
- Pork:Carcass utilization rates exceed other species through integrated processing into sausages, hams, and fresh cuts. Demand concentrates in food processing channels where standardized primal cuts enable automated portioning, though Tierschutzgesetz stocking density rules elevate compliance costs relative to Danish imports.
- Poultry:Breast and thigh meat specifications dominate quick-service restaurant procurement contracts. Bavaria's processing plants are expanding most quickly due to health-positioned consumer shifts and shorter production cycles that reduce methane exposure under EU Green Deal reporting.
- Beef:Grass-fed and grain-finished categories serve divergent price tiers in retail and hospitality channels.
- Lamb:Niche positioning in ethnic foodservice and Easter seasonal demand limits scale economies.
Today's leader: Pork. Tomorrow's challenger: Poultry.
Packaging Type:
Cost tier differentiation separates commodity formats from premium shelf-life extension technologies that command retail placement premiums.
- Vacuum Sealed:Modified atmosphere packaging with oxygen scavengers extends retail case life to 21-28 days without preservative additives. Discounter chains in North Rhine-Westphalia mandate this format for private-label fresh meat, driving capital expenditure concentration among mid-sized processors.
- Trays:Expanded polystyrene and fiber-based alternatives balance presentation appeal against circular economy compliance costs. Baden-Württemberg's organic retailers specify molded pulp trays with bio-based films, creating margin premiums for certified suppliers.
- Bags:Polyethylene and nylon laminates serve frozen and value-added categories with cost-minimized barrier properties.
- Cans:Sterilized shelf-stable formats retain relevance in emergency preparedness and military procurement segments.
Current margin concentration: Vacuum Sealed. Emerging pressure point: Trays.
Distribution Channel:
Customer type fragmentation is accelerating as direct sourcing contracts displace traditional wholesale intermediaries in foodservice procurement.
- Supermarkets:EDEKA and REWE Group buying offices enforce blockchain-enabled traceability mandates and fixed-volume commitment structures. Their private-label specifications dominate mass-market volume, compressing supplier margins through centralized tender processes.
- Butcher Shops:Regional sausage and cured-meat craftsmanship retains loyalty in Bavaria and Rhineland-Palatinate despite retail consolidation. These outlets source primals from cooperative slaughterhouses rather than integrated processors, preserving traditional cutting specifications.
- Online Retail:Subscription box models and flash-frozen direct delivery are gaining share fastest in urban centers with cold-chain logistics density.
- Convenience Stores:Grab-and-go prepared meat snacks target commuter demand with limited refrigeration footprints.
Volume dominance: Supermarkets. Relationship preservation: Butcher Shops.
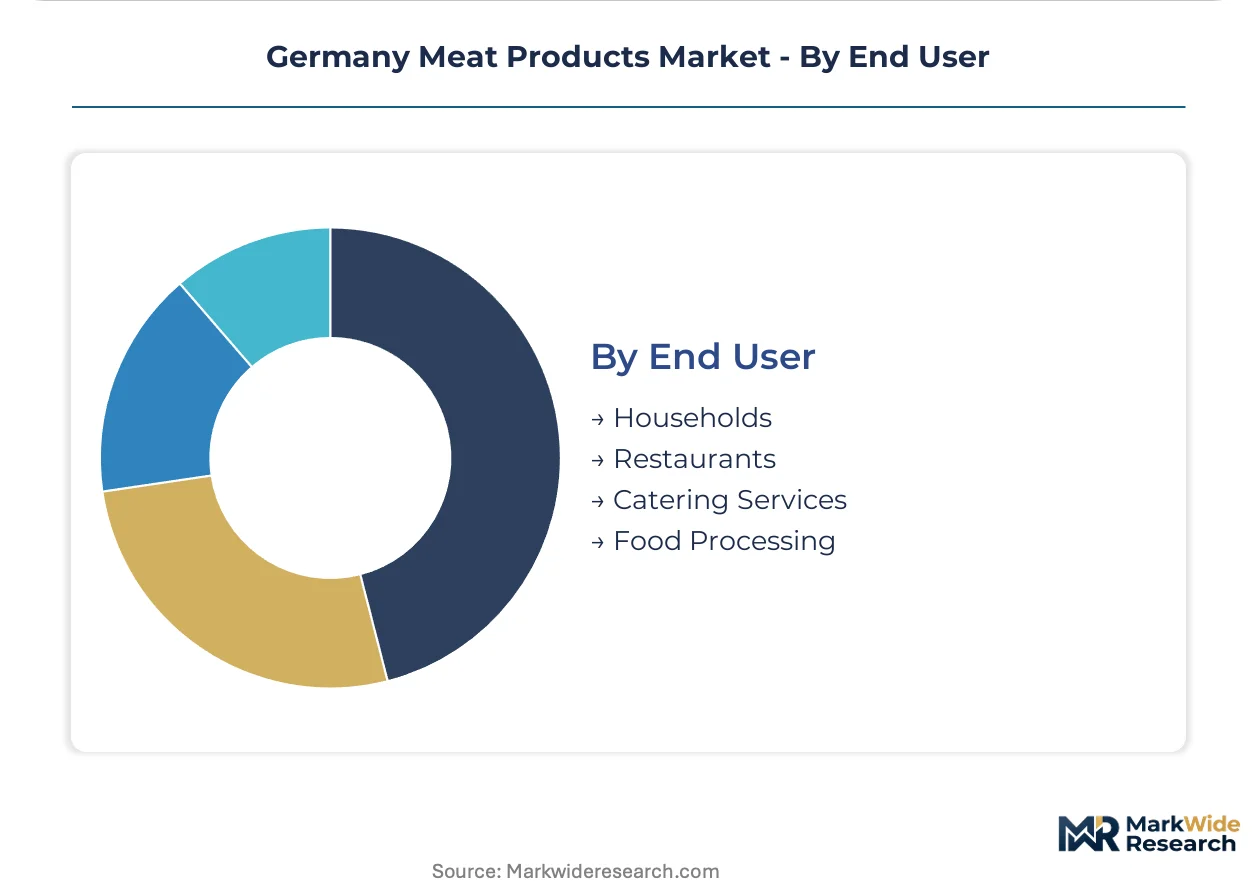
End User:
Application-specific requirements drive specification divergence between retail-ready and industrial ingredient categories.
- Food Processing:Precooked and pre-seasoned meat ingredients require precise pH and water-holding capacity specifications for further manufacturing integration. North Rhine-Westphalia's clustered operations supply ready-to-cook components for pan-European ready meal producers.
- Restaurants:Specification-grade agreements for standardized cuts with fixed-volume commitments are displacing spot market purchasing in Bavaria's hospitality corridors. Chained operators negotiate directly with processors for consistent portion weights and trim specifications.
- Households:Retail-packaged fresh and frozen categories serve weekly shopping patterns with price-sensitive substitution elasticity.
- Catering Services:Bulk portioning and extended holding requirements favor blast-chilled and sous-vide prepared formats.
Contract innovation leader: Food Processing. Margin recovery focus: Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's lower-cost pork exports challenge German processors on price, while Dutch cold-chain infrastructure enables cross-border efficiency gains for North Rhine-Westphalia clusters. Regulatory asymmetries between neighboring jurisdictions create competitive pressure gradients across Central European meat corridors.
North Rhine-Westphalia
Slaughter-to-retail integration and Dutch border logistics anchor regional dominance. The state's implementation of EU Farm to Fork animal welfare mandates elevates compliance costs above Polish competitors. The Rheda-Wiedenbrück processing corridor concentrates Europe's highest-density pig slaughter capacity.
Lower Saxony
Intensive pig farming operations face the steepest methane reporting obligations under EU Green Deal targets. The Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces granular feed-source documentation across concentrated animal feeding operations. Emsland and Oldenburg districts host cooperative slaughterhouse networks supplying pan-European ready-meal manufacturers.
Bavaria
Health-positioned poultry demand and hospitality-dense urban corridors accelerate processing expansion. The state's Tierschutzgesetz enforcement creates structural cost premiums relative to Czech imports. Nuremberg and Munich processing plants specialize in quick-service restaurant specification contracts.
Baden-Württemberg
Affluent organic consumer bases sustain Demeter-certified premium positioning. Regional organic retailers specify molded pulp packaging with bio-based films, creating margin premiums for certified suppliers. Stuttgart and Karlsruhe distribution hubs serve southwestern Germany's quality-differentiated retail channels.
Germany Meat Products Market Competitive Landscape
Top-tier vendors anchor integrated slaughter-to-retail networks, while mid-sized cooperatives compete on regional sourcing relationships and specialized certification lines. The market structure concentrates around three strategic archetypes: volume-driven integrated processors, cooperative sourcing structures, and halal-organic specialists. Consolidation accelerates through cooperative mergers in northwestern regions, while portfolio diversification into value-added cuts represents the dominant competitive maneuver.
Within the integrated processing tier, Tönnies Holding GmbH and Westfleisch SCE exemplify divergent organizational models—private versus cooperative—that shape competitive dynamics across pork and beef categories. Vion Food Group occupies a specialist position through certification-focused export positioning. These three entities collectively represent how German meat processing competitive advantage flows from either scale-driven vertical coordination or cooperative member governance structures.
| Leading Market Players |
|---|
| Tönnies Holding GmbH |
| Westfleisch SCE |
| Vion Food Group |
| PHW Group |
| Müller Fleisch GmbH |
| Heidemark GmbH |
| Rothkötter Group |
| Plukon Food Group |
| Premium Food Group ApS & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Captive slaughter-to-retail integration anchors both supply security and pricing power for German meat processors, with Tönnies Holding and Westfleisch leveraging in-house cold-chain control to defend margin structures against Polish import pressure. This upstream consolidation enables premium positioning for vacuum-sealed value-added cuts while Tierschutzgesetz compliance costs compress price floors for domestic commodity pork.
Pricing Analysis
Capacity additions in Lower Saxony and Bavaria are reshaping price floors for poultry and processed pork categories. Three-tier pricing structure across premium, standard, and economy levels separates Demeter-certified organic lines from conventional retail packs and bulk foodservice formats. Price differentiation hinges on certification grade and volume scale, with discounter chains extracting maximum leverage through fixed-volume commitment structures. Pricing pressure stems from feed grain volatility and veterinary inspector shortages that compress processing schedules. Quick-service restaurant procurement teams show highest price sensitivity, while organic retail channels in Baden-Württemberg accept structural premiums for full traceability.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised returns and blast-chilled product refurbishment concentrate cost recovery efforts at North Rhine-Westphalia distribution hubs. Geographic supply concentration clusters in Germany, Denmark, and Poland, with Dutch cold-chain infrastructure enabling cross-border efficiency gains for Rheda-Wiedenbrück processors. Raw material dependencies center on Ukrainian feed grains, Brazilian soy protein, and domestic straw bedding supplies. Single-source vulnerability runs through concentrated slaughterhouse approvals where Bundesamt für Verbraucherschutz und Lebensmittelsicherheit staffing gaps create chokepoints. Distribution runs through cooperative slaughterhouse networks serving regional butcher shops and integrated processor direct contracts with supermarket buying offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in German meat processing rests on cold-chain digitization reducing spoilage losses and organic certification capturing Baden-Württemberg premium tiers.
For Market Incumbents: Hedge against Polish import price pressure by deepening backward integration into feed sourcing and expanding high-pressure processing capacity for shelf-life extension premiums. Prioritize blockchain-enabled traceability investments to meet REWE and EDEKA private-label mandates before competitors achieve compliance. Certification leverage in halal and Demeter lines offers defensive positioning against commodity margin compression. For New Entrants and Emerging Players: Subscription-based direct-to-consumer channels unlock white-space penetration in urban centers with cold-chain logistics density, bypassing supermarket tender processes that favor incumbents. Target Bavaria's quick-service restaurant specification contracts where health-positioned poultry demand outpaces established processor capacity. Flash-frozen delivery models with predictive maintenance service bundles create differentiated recurring revenue streams. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative slaughterhouse networks face HACCP digitization costs exceeding member capital reserves. Mid-sized processors with halal certification infrastructure and North Rhine-Westphalia logistics positioning represent prime acquisition archetypes over a multi-year viability window. Monitor alternative protein substitution rates in urban sausage categories as early inflection indicator for traditional volume erosion.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Scale-Up | Extends retail case life to 28 days without chemical preservatives, opening premium placement. |
| Blockchain Traceability Integration | Meets EDEKA and REWE mandatory verification for private-label fresh meat contracts. |
| Halal Certification Line Expansion | Unlocks export channels into Turkey and Gulf states with specialized processing premiums. |
| Subscription Cold-Chain Monitoring | Transforms capital expenditure into recurring revenue through predictive maintenance contracts. |
| Cooperative Merger Execution | Consolidates northwestern slaughterhouse networks to achieve scale economies against integrated processors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with slaughterhouse operations directors, supermarket category buyers, veterinary inspection officials, and cooperative board members with secondary validation against Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforcement records, EU Farm to Fork Strategy documentation, and German agricultural trade statistics. Bottom-up capacity modeling across North Rhine-Westphalia, Lower Saxony, Bavaria, and Baden-Württemberg facilities triangulated against top-down consumption surveys.
Comparable-period anchoring tied projection assumptions to historical slaughter volume patterns and cold-chain investment cycles across the analysis window. Segmentation dimensions modeled include species category, packaging technology tier, distribution channel structure, and end-use application with organic certification status as an overlay variable. CAGRs derived from regression analysis of processing capacity expansion rates against feed cost indices and regulatory compliance cost trajectories. Forecast inputs incorporated EU Green Deal methane reporting obligations and Tierschutzgesetz enforcement intensity variations by federal state.
The model assumes a particular technology adoption path for IoT temperature logging and predictive analytics; alternative pathways for blockchain traceability platform deployment would alter the outlook for mid-sized cooperative competitive positioning. Forecasts reflect assumptions regarding veterinary inspector staffing resolution and feed grain supply normalization. Practitioners should monitor plant-based protein substitution velocity in urban centers and carbon-footprint labeling mandate timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Smokehouse Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Europe Canned Meat Market
Meat Products
Oman Poultry Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Hot Dog and Sausages Market
Meat Products
North America Canned Meat Market
Meat Products
Meat Ingredients Market
Meat Products
GCC Edible Meat Market
Meat Products
United States Bacon Market
Meat Products
Organic Lamb Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Global Duck Meats Market
Meat Products
Europe Poultry Meat Market
Meat Products
Organic Meat Market