
 Western Europe Ready-To-Eat Meat Market | 2026-2036
Western Europe Ready-To-Eat Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Western Europe Ready-To-Eat Meat Market Analysis
Competitive Dynamics
A capital-intensity divergence between large-scale processors and mid-tier specialists is rotating competitive advantage toward integrated supply chains. JBS S.A. leverages its protein processing infrastructure to control raw material flows across Iberian and Central European facilities. Tönnies Group anchors its position through slaughter-to-retail integration in Germany, while Dawn Farms specializes in cooked and fermented meat solutions for foodservice clients. Plukon Food Group BV dominates poultry-based RTE formats through dedicated processing lines in the Netherlands and Belgium.
Product and Segment Structure
Western Europe ready-to-eat meat comprises thermally processed, cured, or fermented animal proteins packaged for immediate consumption without further preparation, typically requiring refrigeration at zero to four degrees Celsius and shelf lives ranging from seven to forty-five days depending on preservation method. The category serves retail, foodservice, and institutional buyers seeking labor reduction and portion control. Chilled products lead value generation due to premium positioning and shorter supply cycles, while pouches represent the fastest-growing packaging format as retailers prioritize shelf efficiency and reduced plastic weight. Supermarkets capture the largest margin pool through private-label RTE programs, though online channels are gaining traction in urban French and UK markets.
Regulatory Environment and Outlook
ECHA enforces REACH compliance for packaging substrates and food-contact substances, while EFSA sets microbiological criteria for Listeria monocytogenes in RTE products that dictate plant sanitation investments and shelf-life claims. The EU Green Deal's Farm-to-Fork strategy pressures processors to document carbon intensity across protein sourcing, energy use, and distribution. Stakeholders must monitor evolving CSRD disclosure requirements and national extended producer responsibility schemes that will reshape packaging material selection and reverse logistics obligations.
Market Dynamics
The EU Green Deal's Farm-to-Fork strategy is compressing processing margins while mandating carbon documentation across protein sourcing, forcing RTE meat processors to reconfigure cold-chain infrastructure and packaging substrates simultaneously.
Growth Catalysts
- Urban convenience retail:France's dense metropolitan networks are expanding chilled RTE shelf space in response to single-person household density and commute-pattern eating.
- F-Gas Regulation compliance:Refrigeration retrofit deadlines are accelerating adoption of transcritical CO2 systems in German and Dutch processing plants, cutting energy intensity per unit.
- Clean-label fermentation:Natural preservation cultures are extending shelf life without synthetic additives, satisfying EFSA microbiological criteria while meeting retailer private-label specifications.
Market Restraints
- Pork input volatility:Iberian and Danish slaughterhouse capacity constraints create raw material price swings that compress margin predictability for cured and fermented product lines.
- Supply concentration risk:Three integrated groups control over sixty percent of Western European poultry processing, creating bottleneck vulnerability for mid-tier RTE specialists without captive supply.
- REACH substrate costs:ECHA compliance for food-contact packaging films is raising material costs fifteen to twenty-five percent above non-compliant alternatives, squeezing private-label economics.
Strategic Opportunities
- Belgian foodservice penetration:Institutional catering and contract foodservice in Brussels and Antwerp remain underdeveloped for premium cooked-meat formats, offering first-mover positioning.
- CSRD disclosure services:Mandatory carbon reporting under EU Corporate Sustainability Reporting Directive creates adjacent revenue streams for processors with verified supply chain data infrastructure.
- Pouch-to-tray convergence:Retort pouch technology combined with modified atmosphere packaging is enabling ambient-stable RTE meat for vending and automated retail channels.
Industry Challenges
- Microbiological validation timelines:EFSA Listeria monocytogenes testing protocols extend new product qualification cycles by eight to fourteen weeks, delaying seasonal line launches.
- Cold-chain talent scarcity:Refrigeration engineering and HACCP system management skills are concentrating at large processors, leaving mid-tier plants dependent on contracted technical services.
Report Scope
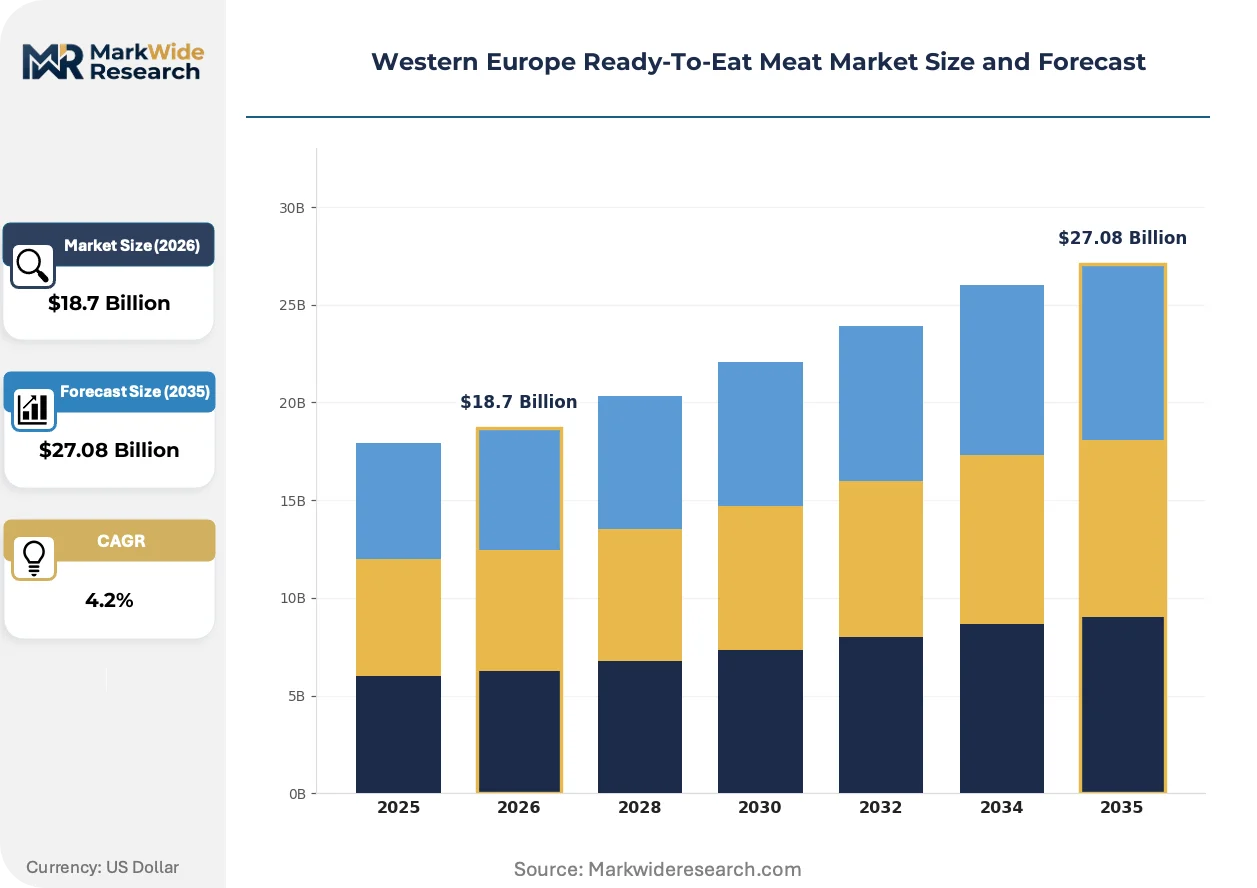
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Western Europe Ready-To-Eat Meat Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled, Frozen, Canned, Dried Packaging Type: Bags, Trays, Cans, Pouches End User: Restaurants, Supermarkets, Convenience Stores, Catering Services Distribution Channel: Online, Offline, Direct, Wholesalers |
| Companies Covered | Tyson Foods, Smithfield Foods, JBS S.A., Cargill, Tönnies Group, OSI Group, Dawn Farms, Vismara SpA, Plukon Food Group BV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Western Europe Ready-To-Eat Meat Market Emerging Trajectories
Active packaging technologies and carbon-accounting software are converging to reshape how RTE meat moves from slaughterhouse to retail shelf, with regulatory compliance now inseparable from product design decisions.
High-barrier mono-material films are supplanting multi-layer laminates in chilled RTE meat packaging. German discount retailers are mandating these substrates for private-label lines by 2026. This material transition is compressing equipment amortization cycles as processors retrofit form-fill-seal lines for seal-integrity testing at higher throughputs.
The EU F-Gas Regulation's phasedown schedule is forcing refrigeration system replacement across French and Benelux processing plants. Transcritical CO2 and ammonia-based systems are capturing new-build and retrofit investment. Small-to-mid processors in Northern France face disproportionate capex burdens relative to integrated competitors with centralized engineering capabilities.
Urban French and UK buyers are consolidating weekly food purchases into fewer, larger trips while demanding same-day delivery for protein categories. This bifurcation is fragmenting distribution strategy: supermarkets optimize for basket-building margin while dark-store operators prioritize SKU velocity and temperature integrity in last-mile handoffs.
Western Europe Ready-To-Eat Meat Market Segmentation
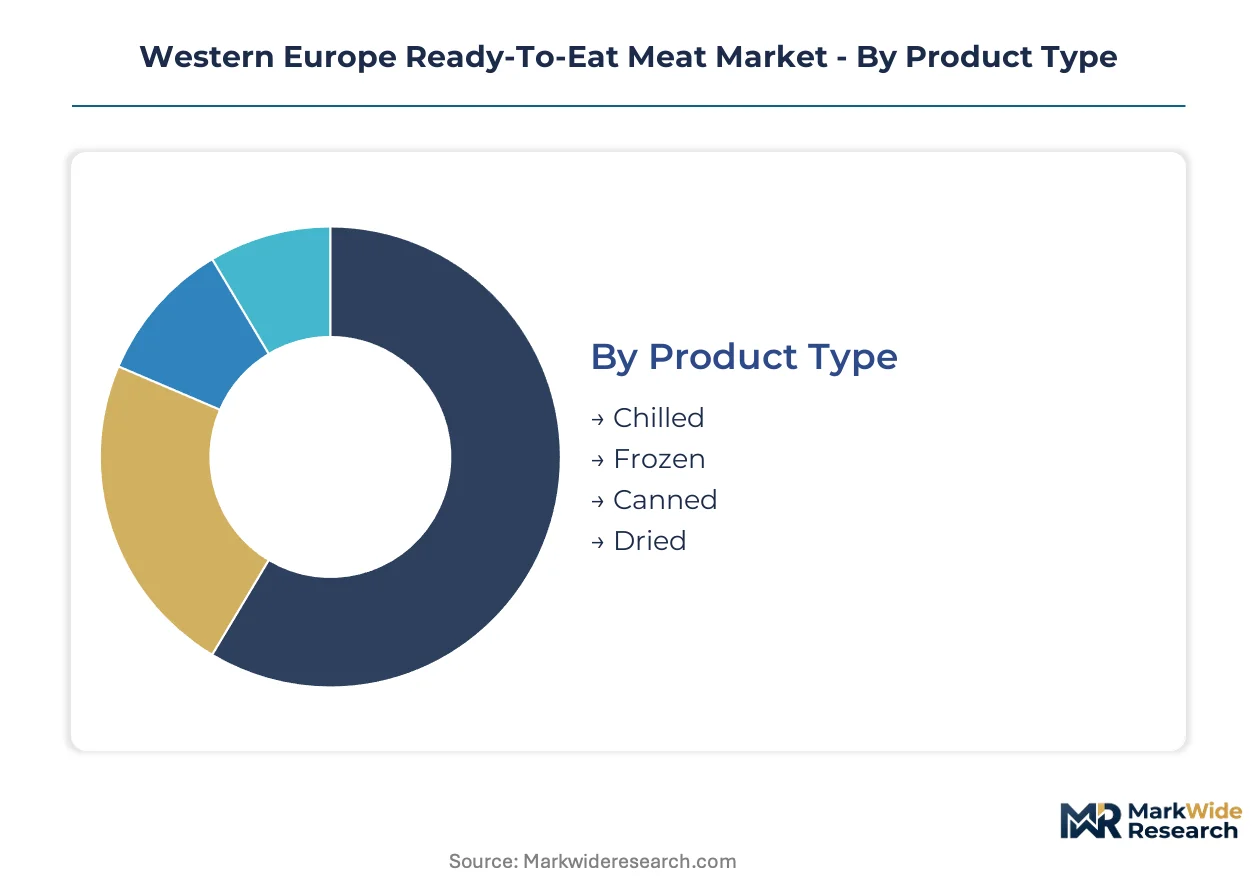
RTE meat segmentation in Western Europe reflects divergent cold-chain economics and channel-specific shelf requirements. Product temperature class and packaging format decisions cascade through margin structure, regulatory compliance burden, and retail negotiation leverage.
Product Type:
Chilled formats dominate domestic consumption across German discount retail and French urban convenience networks, while frozen and shelf-stable variants serve export-adjacent and institutional channels with longer logistics cycles.
- Chilled:Thermally processed or cured meats held at zero to four degrees Celsius with seven to forty-five day shelf lives. German discount retailers and French convenience chains concentrate procurement here, prioritizing rapid inventory turns and premium positioning over extended distribution reach.
- Frozen:Blast-frozen products at minus eighteen degrees Celsius enabling twelve to twenty-four month stability. Benelux foodservice distributors and UK meal-kit operators drive demand, accepting higher energy intensity for supply security and menu planning flexibility.
- Canned:Retort-sterilized meats in hermetic containers achieving ambient stability. Emergency preparedness channels and military procurement in France and Spain sustain volume, though retail presence contracts against fresher alternatives.
- Dried:Dehydrated or fermented products with water activity below critical thresholds for pathogen growth. Italian and Spanish specialty exporters anchor this segment, serving delis and gourmet retail with traditional processing claims.
Chilled holds the largest share; momentum sits with frozen formats as foodservice operators rebuild post-pandemic inventory buffers.
Packaging Type:
Material selection now hinges on REACH compliance costs and retailer sustainability mandates rather than purely functional barrier properties.
- Pouches:High-barrier flexible films with modified atmosphere capability, reducing plastic weight versus rigid alternatives. German discount retailers are mandating mono-material variants by 2026, forcing equipment retrofits at Dutch and Belgian processing plants.
- Trays:Expanded polystyrene or fiber-based containers with lidding film for case-ready presentation. French supermarkets dominate procurement, accepting higher per-unit material costs for shelf impact and portion clarity.
- Bags:Vacuum or gas-flushed flexible packaging for bulk foodservice and institutional catering. UK contract caterers concentrate demand here, prioritizing cube efficiency in cold storage over retail aesthetics.
- Cans:Tinplate or aluminum containers for ambient-stable products. Spanish and Portuguese processors maintain lines for export markets and traditional retail channels where refrigeration infrastructure remains limited.
Trays command the highest unit economics; pouches are climbing the fastest as shelf-efficiency metrics reshape retailer scorecards.
End User:
Channel concentration varies sharply by country: Germany's discount density, France's urban convenience penetration, and the UK's online grocery maturity create distinct customer archetypes.
- Supermarkets:Full-assortment retailers operating private-label RTE programs with direct processor relationships. German chains leverage volume concentration to dictate packaging specifications and carbon disclosure requirements.
- Convenience Stores:Small-format urban retailers with limited backroom refrigeration. French metropolitan networks are expanding chilled RTE space fastest, responding to single-person household density and commute-pattern eating.
- Restaurants:Full-service and limited-service operators seeking labor reduction through pre-portioned proteins. Belgian institutional catering and contract foodservice remain underdeveloped for premium cooked-meat formats.
- Catering Services:Event, corporate, and healthcare foodservice requiring bulk portion control and temperature integrity guarantees. UK hospital and school catering contracts drive specification standardization.
Supermarkets capture the largest margin pool; convenience stores are gaining share fastest as urban retail formats proliferate.
Distribution Channel:
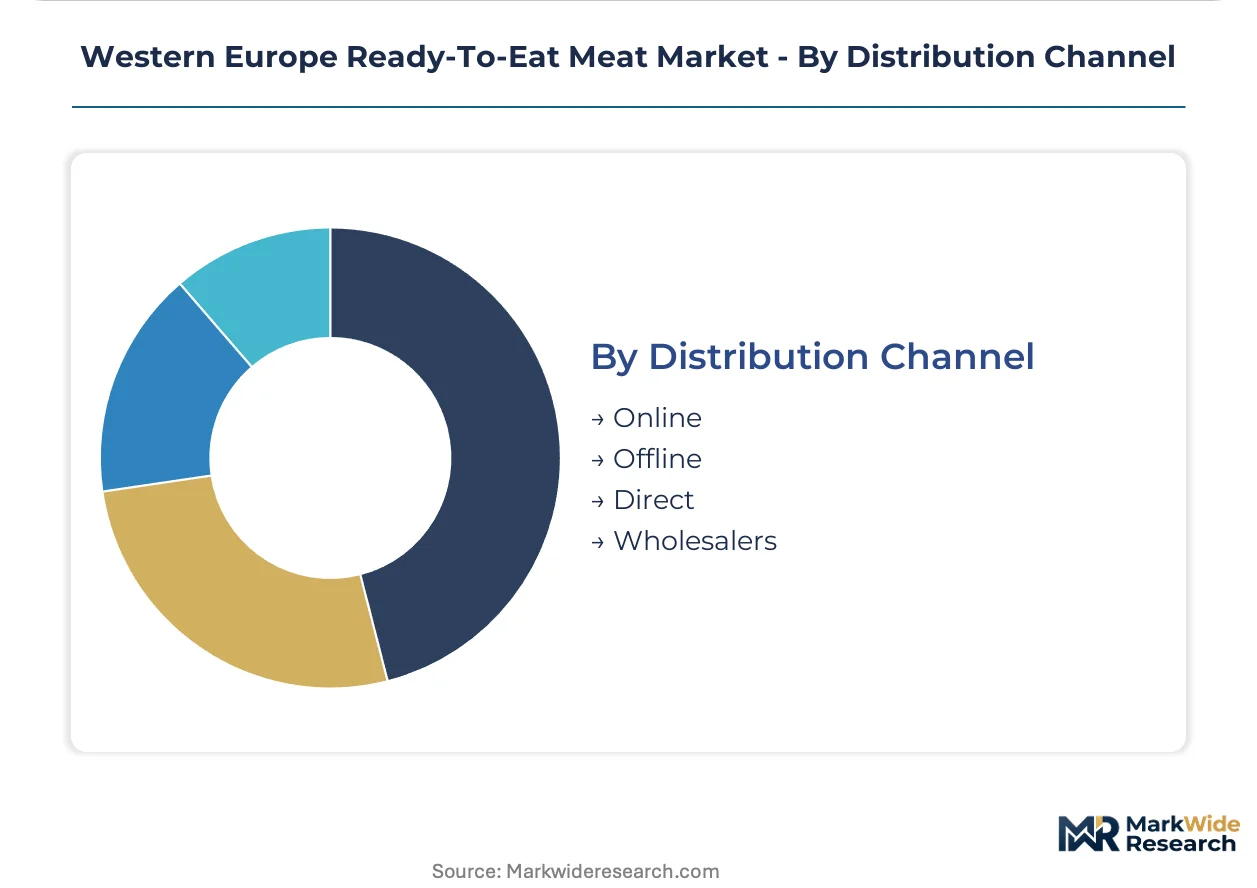
Channel strategy fragments between basket-building supermarket trips and velocity-optimized dark-store fulfillment, with temperature integrity as the common constraint.
- Offline:Traditional brick-and-mortar retail including supermarkets, convenience stores, and specialty butchers. German and French retail concentration sustains this channel's dominance despite online encroachment.
- Wholesalers:Foodservice distributors and buying groups aggregating demand from fragmented restaurant and catering operators. Bid pricing and specification compliance dominate procurement dynamics.
- Online:E-commerce platforms and dark-store operators promising same-day or scheduled delivery. Urban French and UK buyers are consolidating weekly purchases while demanding expedited protein fulfillment.
- Direct:Processor-to-operator relationships bypassing distributor markup for large-volume accounts. Integrated processors with captive logistics networks exploit this channel most effectively.
Offline retains the largest volume base; online channels show the steepest expansion trajectory as last-mile cold-chain solutions mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Western Europe: German discount retail channels drive aggressive procurement negotiations, while French urban convenience buyers absorb premium positioning for chilled formats with minimal volume sensitivity.
Germany
Discount retail density and private-label concentration create procurement leverage unmatched elsewhere in the region. The EU Green Deal's Farm-to-Fork strategy pressures processors to document carbon intensity across slaughter-to-retail chains. North Rhine-Westphalia's processing corridor hosts Tönnies Group's integrated facilities, where slaughter-to-packaging consolidation controls raw material flows.
France
Single-person household density and commute-pattern eating expand chilled RTE shelf space in Parisian convenience networks. ANSM enforces strict microbiological surveillance protocols that extend new product qualification timelines. The Île-de-France region anchors demand, with urban dark-store operators prioritizing same-day protein fulfillment for time-constrained professionals.
United Kingdom
Online grocery maturity and meal-kit subscription growth fragment distribution between basket-building supermarket trips and velocity-optimized dark-store fulfillment. EFSA Listeria monocytogenes criteria dictate plant sanitation investments that favor large-scale processors with centralized HACCP management. Greater London's cold-chain infrastructure concentrates last-mile innovation for temperature-critical handoffs.
Netherlands
Poultry-based RTE specialization and Benelux foodservice distribution create export-adjacent demand for frozen formats. The F-Gas Regulation's phasedown schedule accelerates transcritical CO2 refrigeration retrofits at processing plants. The Eindhoven-Rotterdam corridor hosts Plukon Food Group BV's dedicated processing lines, where equipment amortization cycles compress under retailer sustainability mandates.
Belgium
Institutional catering and contract foodservice in Brussels-Antwerp remain underdeveloped for premium cooked-meat formats, offering positioning whitespace. REACH compliance costs for food-contact packaging films raise material expenditures fifteen to twenty-five percent above non-compliant alternatives. Flanders' logistics hubs enable cross-border distribution to French and German retail networks.
Western Europe Ready-To-Eat Meat Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence rotating advantage toward captive supply chains. Three strategic archetypes dominate: protein conglomerates with slaughter-to-retail integration, poultry specialists with dedicated RTE processing lines, and cooked-meat solution providers for foodservice channels. Competitive moves concentrate on cold-chain infrastructure retrofit and carbon-accounting data infrastructure to satisfy CSRD disclosure requirements.
Among integrated protein processors, JBS S.A. and Tönnies Group exemplify the slaughter-to-retail archetype, occupying positions where upstream control over raw material flows insulates margin predictability from pork input volatility. Plukon Food Group BV represents the poultry-specialist tier, sitting within a format-dedicated positioning that captures retailer shelf-efficiency mandates. These three entities anchor the competitive structure, with their respective geographic footprints in Iberian, Central European, and Benelux processing corridors shaping regional supply configurations.
| Leading Market Players |
|---|
| Tyson Foods |
| Smithfield Foods |
| JBS S.A. |
| Cargill |
| Tönnies Group |
| OSI Group |
| Dawn Farms |
| Vismara SpA |
| Plukon Food Group BV |
| Others |
Supply Flow & Price Mechanics
Mono-material film substitution for multi-layer laminates is redrawing procurement geography toward Dutch and Belgian processing plants while compressing equipment amortization cycles and resetting price floors for private-label compliance.
Pricing Analysis
After-sales cold-chain service contracts and extended refrigeration maintenance agreements drive lifetime value for German discount retailers demanding carbon disclosure documentation. Three-tier pricing structure across premium private-label, standard branded, and economy bulk formats separates EFSA-certified chilled lines from frozen foodservice alternatives. Pricing pressure stems from REACH substrate cost premiums running fifteen to twenty-five percent above non-compliant films, squeezing mid-tier processor margins. German discount retail buyers exhibit highest price sensitivity, while French urban convenience channels absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Inventory lead times for Iberian pork inputs extend qualification cycles as Danish and Spanish slaughterhouse capacity constraints create raw material bottlenecks. Supply concentrates in Germany, the Netherlands, and Belgium, with Dutch poultry processing and German pork integration anchoring regional flows. Raw material dependencies center on live hog procurement, natural fermentation cultures, and high-barrier packaging films. Single-source vulnerability sits with three integrated poultry groups controlling sixty percent of Western European processing. Distribution runs through German discount retail networks, French convenience chains, and Benelux foodservice wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is rotating toward German discount retail concentration and French urban convenience consolidation, compressing processor negotiation leverage across private-label procurement cycles.
For Market Incumbents: Shield margin predictability through captive slaughter-to-packaging integration in North Rhine-Westphalia and Eindhoven-Rotterdam corridors, countering pork input volatility. Deepen HACCP system management capabilities to offset cold-chain talent scarcity concentrating at larger processors. Prioritize carbon-accounting data infrastructure to satisfy CSRD disclosure requirements and defend shelf space against retailer sustainability mandates.
For New Entrants and Emerging Players: Anchor in Belgian institutional catering whitespace around Brussels-Antwerp, where premium cooked-meat formats remain underdeveloped relative to neighboring markets. Target French dark-store operators seeking same-day protein fulfillment partnerships with temperature-integrity guarantees. Pursue pouch-to-tray convergence technology for automated retail channels as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: The EU F-Gas Regulation's refrigeration retrofit deadlines reshape the acquisition landscape toward processors with transcritical CO2 system investments already deployed. Long-term viability favors integrated specialists with verified supply chain data infrastructure and retailer-mandated packaging compliance. Watch EFSA Listeria monocytogenes protocol extensions as the signal indicating qualification timeline compression and new product launch delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Retrofit | Transcritical CO2 system deployment satisfies F-Gas Regulation deadlines at Dutch and German processing plants. |
| Carbon-Accounting Data Infrastructure | Verified supply chain documentation enables CSRD disclosure services and retailer compliance positioning. |
| Mono-Material Packaging Transition | High-barrier film retrofit meets German discount retailer mandates by 2026 while cutting plastic weight. |
| Clean-Label Fermentation Investment | Natural preservation cultures extend shelf life without synthetic additives, satisfying EFSA microbiological criteria. |
| Dark-Store Distribution Partnership | Same-day fulfillment capability captures French urban convenience demand from time-constrained professionals. |
Methodological Framework
Cross-validation between regulatory filing analysis and trade data anchors the qualitative findings across this study. Primary interviews with RTE meat processing plant managers, German discount retail category buyers, French convenience chain procurement leads, and cold-chain logistics engineers combined with secondary validation from EFSA guidance documents, ECHA REACH substance registrations, EU customs trade databases, and national extended producer responsibility filings. Bottom-up volume triangulation across product temperature classes, packaging formats, and distribution channels converged with top-down market sizing.
Sensitivity analysis around pork input cost volatility and F-Gas Regulation compliance timelines tested forecast robustness across the projection horizon. Segmentation dimensions modeled include product temperature class, packaging substrate type, end-user channel, and country-specific retail format concentration. CAGRs derived from trend extrapolation calibrated against historical volume patterns and regulatory inflection points. Industry-specific inputs incorporated EFSA Listeria monocytogenes testing protocol durations and retailer sustainability mandate phase-in schedules.
Material uncertainties — Iberian slaughterhouse capacity constraints, REACH substrate cost trajectories, and CSRD disclosure requirement evolution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and retailer mandate adherence without guarantee of timing precision. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Nitrate-Free Bacon Market
Meat Products
Beef Tallow Market
Meat Products
Smokehouse Market
Meat Products
GCC Red Meat Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Pork Flavors Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
North America Processed Meat Market
Meat Products
US Meat Market
Meat Products
Hams Market
Meat Products
GCC Edible Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Global Beef Market
Meat Products
Organic Lamb Market
Meat Products
Europe Animal Protein Market