
 Saudi Arabia Edible Meat Market | 2026-2036
Saudi Arabia Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Edible Meat Market Analytics
Plant-based protein alternatives is rebalancing traditional livestock economics as feed cost volatility pressures margins across the value chain. BRF S.A. leverages its integrated poultry operations to sustain volume leadership in frozen chicken segments. Almarai Food Company anchors its position through backward integration into grain farming and captive feed milling. Tanmiah Food Company differentiates via specialized halal processing lines that meet strict export certification requirements.
Edible meat encompasses muscle tissue from slaughtered animals, processed under controlled temperature and hygiene parameters to maintain protein integrity, moisture content below specified thresholds, and microbial safety standards for human consumption. The category serves as a primary dietary protein source across retail, foodservice, and industrial manufacturing channels. Chicken dominates volume flows through supermarket and HoReCa channels due to its price accessibility and shorter production cycles. Frozen processing leads value retention for imported beef and lamb, while fresh deli formats capture premium margins in urban household segments.
SFDA halal certification mandates shape product standards and market access for all domestic and imported meat offerings. SASO technical regulations on labeling, storage temperature, and traceability enforce compliance costs that favor scaled processors with dedicated quality systems. The country's national agricultural regulator oversees livestock import quotas and biosecurity protocols that constrain supply elasticity. Stakeholders must monitor evolving subsidy frameworks for domestic feed grain production and their impact on cost structures for local versus imported meat.
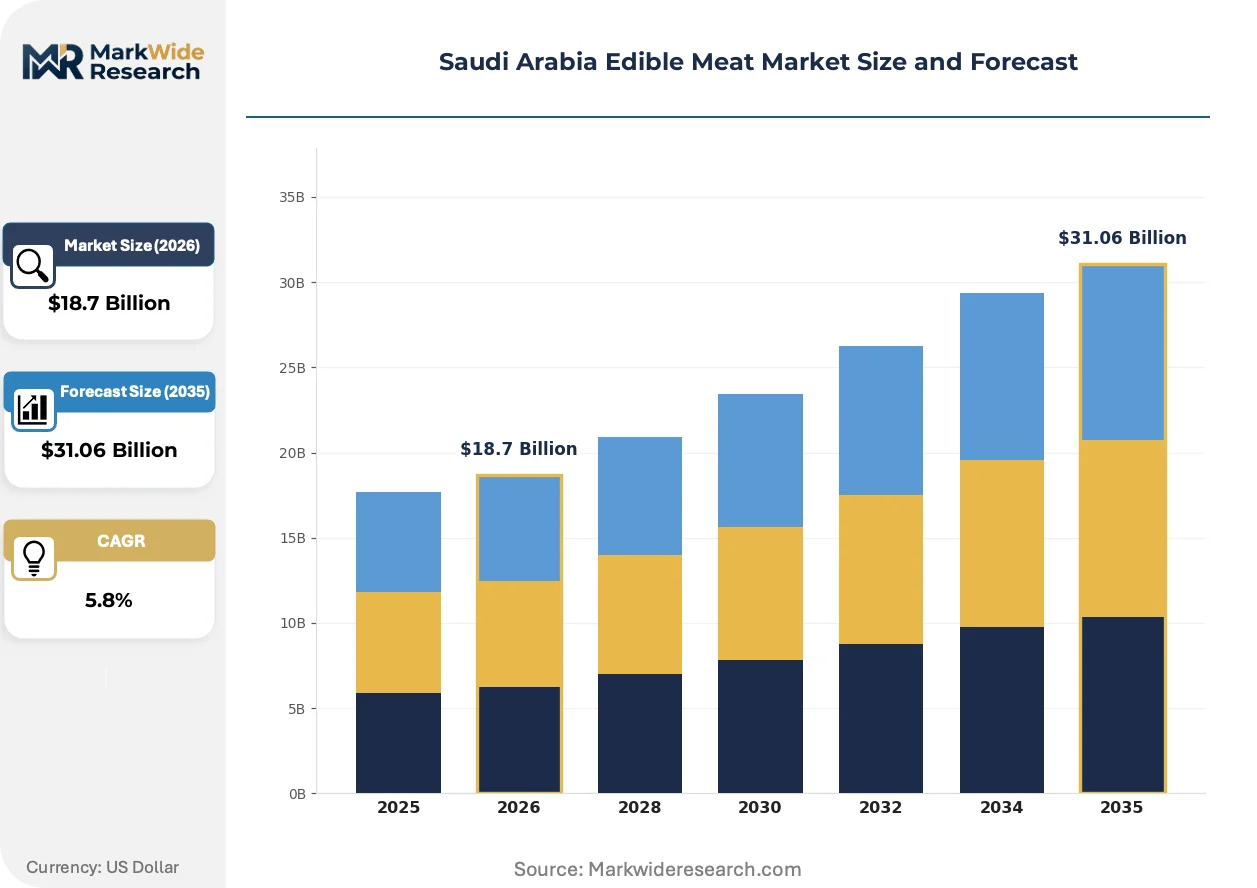
Market Dynamics
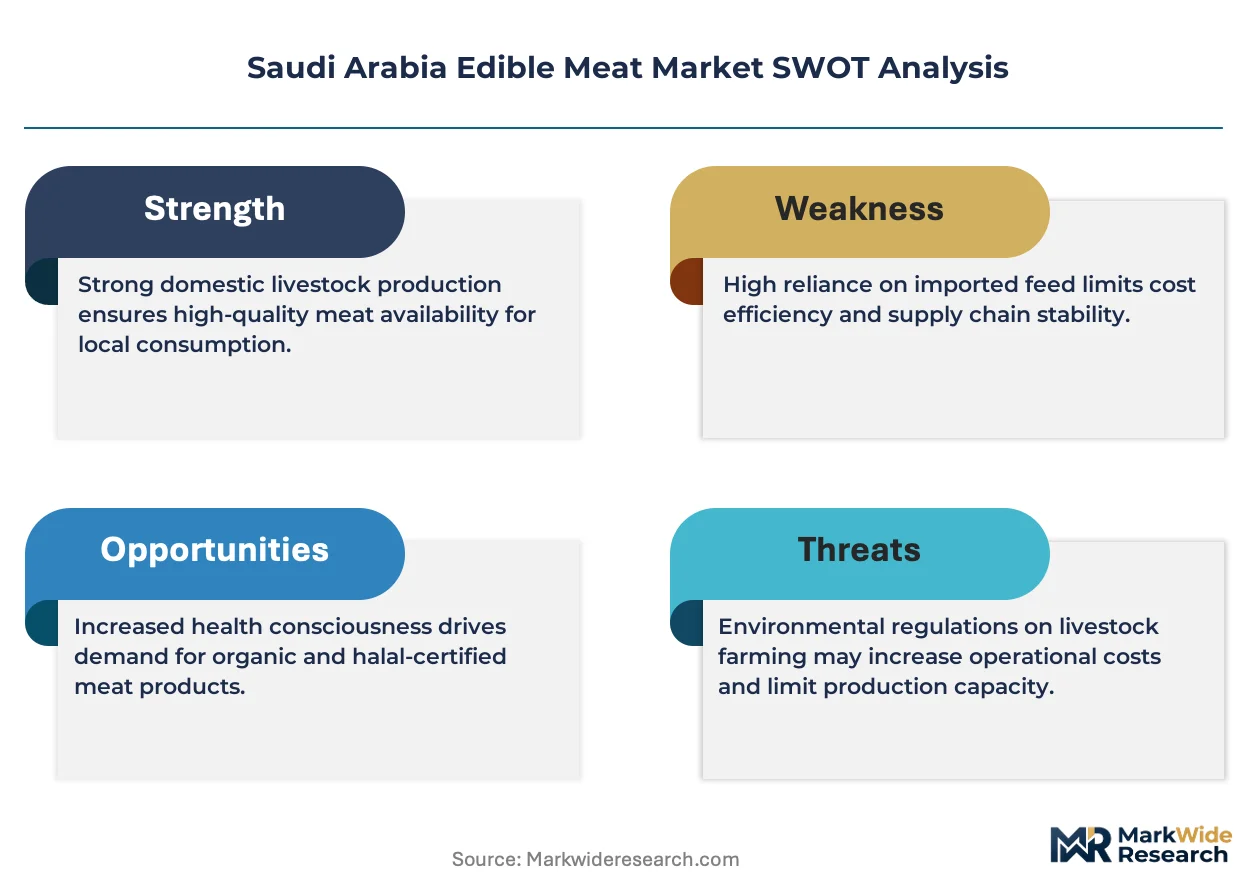
SFDA halal certification enforcement is compressing supplier margins while consolidating procurement authority among scaled processors with dedicated compliance infrastructure.
Growth Catalysts
- Vision 2030 hospitality expansion:Riyadh and Jeddah hotel chains are expanding F&B footprints, pulling premium chilled meat volumes through centralized procurement.
- SFDA cold-chain mandates:Temperature traceability requirements are favoring processors with captive logistics networks over fragmented importers.
- Feed grain subsidies:Domestic barley and sorghum price supports are narrowing cost gaps between local poultry and imported beef.
Market Restraints
- Import quota rigidity:Livestock biosecurity protocols constrain supply elasticity during seasonal demand spikes in Ramadan and Hajj periods.
- Water scarcity:Alfalfa irrigation limits constrain domestic cattle feedlot expansion in the Central Region.
- Plant protein substitution:Soy and pea protein isolates are capturing institutional foodservice contracts previously held by processed chicken.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar retail density lags Riyadh, creating whitespace for branded fresh meat counters.
- Export halal certification:GCC mutual recognition agreements enable Saudi-processed lamb access to UAE and Bahrain foodservice channels.
- Blockchain traceability:Integration of IoT sensors with distributed ledger systems is opening premium positioning for provenance-verified products.
Industry Challenges
- Halal auditor scarcity:SFDA-certified slaughter inspectors are concentrated in Riyadh, creating bottlenecks for regional plant expansions.
- Legacy ERP integration:Batch-level traceability mandates are forcing mid-tier processors to replace decades-old inventory systems.
- Biosecurity capex cycles:Foot-and-mouth disease containment requires continuous quarantine facility upgrades that strain processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Edible Meat Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Lamb, Goat Distribution Channel: Supermarkets, Online Retail, Butcher Shops, HoReCa End User: Households, Restaurants, Hotels, Catering Services Processing Type: Fresh, Frozen, Canned, Deli |
| Companies Covered | BRF S.A., The Savola Group, Almarai Food Company, Halwani Bros, Entaj, Al Watania Poultry, Sunbulah Group, NADEC, Tanmiah Food Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Edible Meat Market Evolving Landscape
Automation and digital traceability are compressing processing timelines while SFDA enforcement raises compliance thresholds across the value chain.
Robotic deboning systems are automating labor-intensive poultry processing stages that previously required skilled manual cutters. Major supermarket private-label programs are adopting these systems to secure consistent portion weights and reduce foreign object contamination risks. The technology is automating workforce reallocation toward quality control and packaging functions, shrinking unit labor costs for frozen chicken operations.
SFDA's 2024 amendments to halal slaughter documentation requirements mandate real-time video verification and blockchain-anchored certificates for all export-bound meat. Processors must now maintain redundant data infrastructure to satisfy both domestic inspectors and importing country regulators. The chilled lamb export segment bears the heaviest compliance burden, with smaller abattoirs exiting the certification queue entirely.
Foodservice buyers are consolidating procurement through centralized purchasing cooperatives that bypass traditional distributor markups. Hospital and university cafeteria networks in Riyadh are forming volume aggregates to secure direct contracts with integrated poultry processors. This concentration is most visible in the Central Region, where institutional buyers now command price premiums for guaranteed supply continuity during peak consumption periods.
Saudi Arabia Edible Meat Market Segmentation
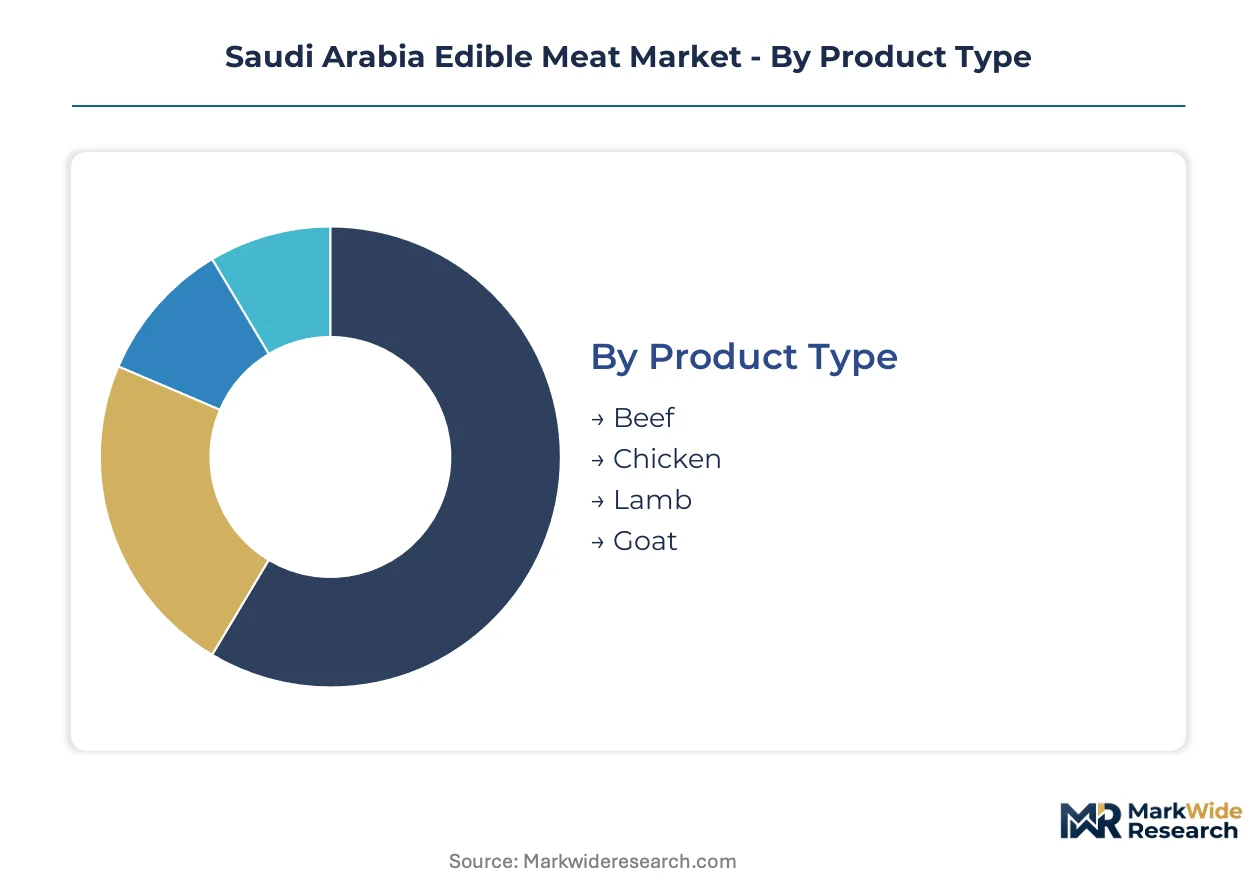
Segmentation in the Saudi Arabia edible meat market reveals how procurement authority, consumption occasion, and compliance infrastructure reshape channel economics. Distinct buyer requirements across hospitality, retail, and institutional segments drive divergent margin structures and cold-chain investment priorities.
Product Type:
Price sensitivity and production cycle length differentiate buyer procurement patterns across protein categories.
- Chicken:Short grow-out periods and feed conversion efficiency make poultry the default protein for volume foodservice contracts. Riyadh-based hotel chains specify chilled chicken for premium buffet lines, while frozen portions dominate school and hospital cafeteria procurement.
- Beef:Grain-fed imported beef commands premium positioning in Jeddah's high-end steakhouse segment, though water-scarce domestic feedlot constraints limit local supply elasticity. SFDA traceability mandates favor Brazilian and Australian suppliers with established halal certification infrastructure.
- Lamb:Religious occasion demand spikes concentrate in Ramadan and Hajj periods, with Australian live exports filling seasonal gaps.
- Goat:Smaller carcass sizes suit extended-family household purchases in Asir and Jazan provinces where traditional preparation methods persist.
Chicken leads volumes today; beef is gaining share fastest among premium foodservice channels.
Distribution Channel:
Cold-chain maturity and buyer consolidation intensity separate channel economics.
- Supermarkets:Private-label fresh meat counters in Riyadh and Jeddah now deploy RFID-enabled inventory systems that sync with SFDA temperature logging requirements. Central Region retail density supports dedicated procurement teams that bypass traditional distributor layers.
- HoReCa:Hotel and restaurant chains aggregate purchasing through centralized procurement cooperatives, extracting volume discounts from integrated processors with captive slaughter and deboning capacity.
- Butcher Shops:Traditional neighborhood outlets retain loyalty in older Riyadh districts and secondary cities where personal relationships govern supplier selection.
- Online Retail:Same-day chilled delivery platforms are capturing urban household segments with subscription-based portion packs.
Supermarkets anchor volume flows; online retail is climbing the fastest as logistics networks mature.
End User:
Consumption scale and certification stringency define procurement sophistication tiers.
- Restaurants:Casual dining chains in Jeddah's Tahlia Street corridor specify portion-controlled cuts to minimize kitchen labor and waste. Menu engineering favors chicken and lamb given predictable cost structures.
- Hotels:Five-star properties in Riyadh's King Abdullah Financial District require dual-certified halal suppliers with blockchain-anchored provenance documentation for guest-facing retail counters.
- Households:Weekly fresh meat purchases concentrate in Central Region urban cores where supermarket penetration exceeds peripheral provinces.
- Catering Services:Institutional contractors serving government and corporate events manage extreme demand volatility around religious holidays.
Restaurants dominate procurement volumes; hotels are expanding share fastest through premium positioning.
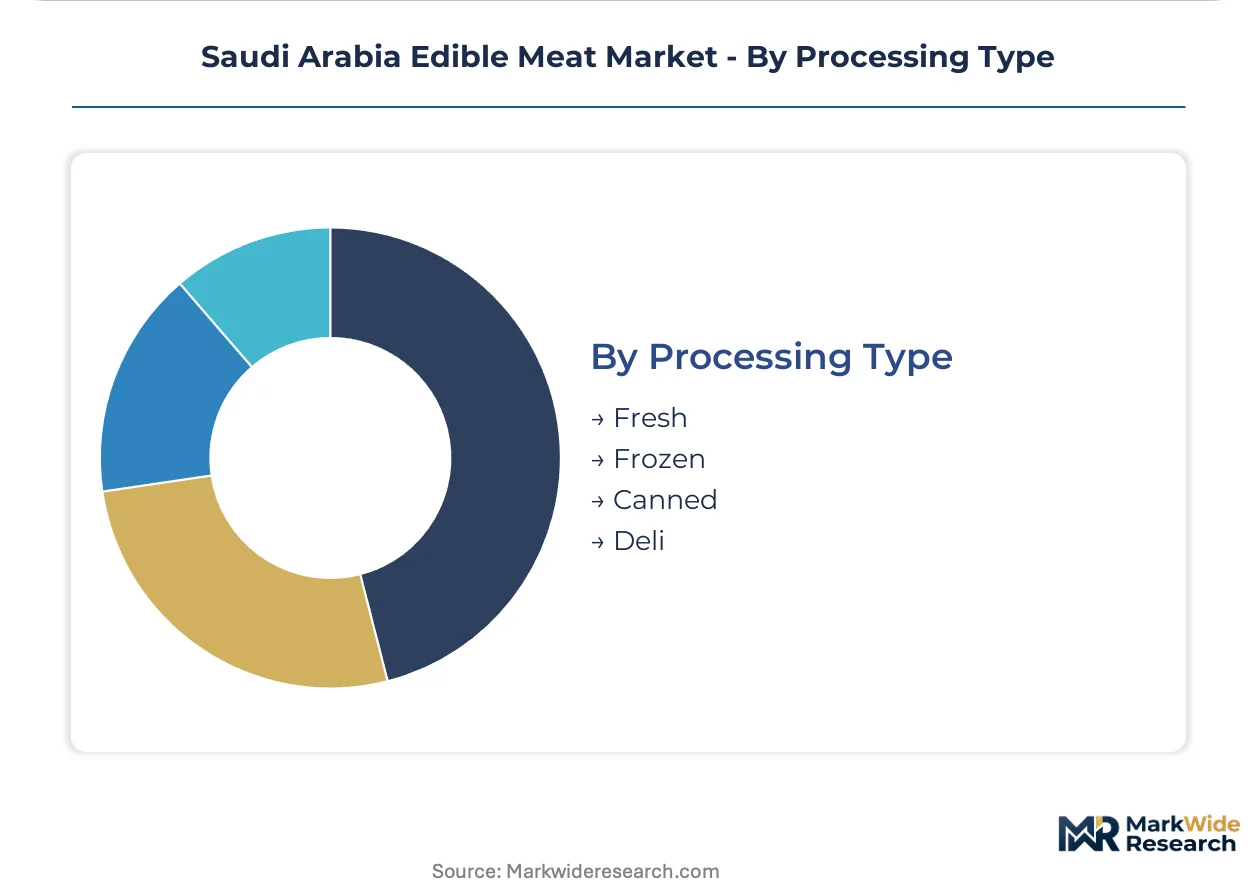
Processing Type:
Shelf-life requirements and margin capture potential determine processor capital allocation.
- Frozen:Blast-freezing at point of slaughter preserves protein integrity for imported beef and lamb traversing extended supply chains. Major supermarket chains specify frozen product for private-label economy tiers.
- Fresh:Chilled distribution within 72 hours of slaughter commands price premiums in urban household segments and hotel fine-dining channels. SFDA cold-chain mandates favor processors with captive logistics networks.
- Deli:Further-processed formats including marinated cuts and value-added portion packs capture margin expansion in time-constrained consumer segments.
- Canned:Shelf-stable formats serve emergency stockpiling requirements and remote area distribution where refrigeration infrastructure remains limited.
Frozen processing leads volume today; fresh formats are expanding most quickly in premium urban channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors national consumption patterns through dense hospitality networks and centralized procurement infrastructure. The Central Region's income concentration sustains premium fresh meat channels that outpace peripheral provinces. SFDA regulatory enforcement radiates from the capital, shaping compliance costs and cold-chain investment priorities across sub-regional markets.
Riyadh
Five-star hotel chains along King Abdullah Financial District drive chilled lamb and beef volumes through centralized procurement cooperatives. SFDA mandates real-time temperature logging for all hospitality deliveries, favoring processors with captive logistics fleets. The King Salman Park corridor hosts expanding supermarket private-label meat counters deploying RFID inventory systems.
Eastern Province
Dammam and Khobar industrial zones support petrochemical workforce demand for standardized frozen chicken portions in institutional cafeterias. The national agricultural regulator allocates livestock import quotas through Damman port, constraining seasonal supply elasticity during Ramadan. ARAMCO-affiliated catering contracts are consolidating procurement authority among scaled poultry processors with dedicated halal certification infrastructure.
Western Region
Jeddah's Tahlia Street casual dining corridor specifies portion-controlled chicken and lamb cuts to minimize kitchen labor costs. The Jeddah Islamic Port handles Australian live sheep imports that fill seasonal gaps in domestic lamb supply. Makkah and Madinah pilgrimage infrastructure generates concentrated demand spikes requiring specialized cold-storage buffers.
NEOM Northwest
The linear city project is importing construction workforce catering demand for blast-frozen protein formats with extended shelf stability. SFDA is piloting blockchain-anchored halal certification protocols for NEOM-bound export shipments to GCC markets. The Oxagon industrial zone plans dedicated livestock processing zones with integrated quarantine facilities.
Saudi Arabia Edible Meat Market Competitive Landscape
Global majors compete with regional champions across halal certification infrastructure and captive cold-chain networks. The vendor base clusters around three tiers: Brazilian and Australian exporters with established SFDA relationships, Saudi integrated processors with backward grain farming control, and specialized halal abattoirs serving export GCC channels. Strategic moves concentrate on M&A for captive logistics assets and portfolio diversification into value-added deli formats.
Among Brazilian-origin exporters, BRF S.A. anchors the frozen poultry tier through volume scale and established halal slaughter infrastructure. Saudi integrated processors Almarai Food Company and Tanmiah Food Company exemplify the backward-integration archetype, controlling grain milling and captive feed supply to narrow cost gaps with imports. These three entities represent distinct competitive positions: export-scale halal certification, domestic upstream control, and specialized export-line differentiation.
| Leading Market Players |
|---|
| BRF S.A. |
| The Savola Group |
| Almarai Food Company |
| Halwani Bros |
| Entaj |
| Al Watania Poultry |
| Sunbulah Group |
| NADEC |
| Tanmiah Food Company |
| Others |
Value Network & Pricing Analysis
Centralized hospitality procurement cooperatives in Riyadh and Jeddah anchor pricing power for premium chilled meat tiers, compressing distributor markups and forcing processors to absorb SFDA compliance costs within contract structures. This buyer concentration creates asymmetric negotiating leverage that favors scaled suppliers with captive cold-chain infrastructure over fragmented importers.
Pricing Analysis
Feed cost pass-through from domestic barley and sorghum subsidies narrows price gaps between local poultry and imported beef, though Brazilian-origin frozen chicken retains volume leadership through scale economies. Price differentiation separates blockchain-traceable halal certifications from standard SFDA compliance tiers, with hospitality buyers commanding premiums for redundant documentation. Margins are tightening due to robotic deboning capex cycles and real-time video verification infrastructure requirements. Institutional cafeteria networks exhibit highest price sensitivity, while five-star hotel chains in King Abdullah Financial District absorb certification premiums for guaranteed supply continuity.
Supply Chain Analysis
Reverse-logistics flows for temperature-exposed returns are minimal in frozen beef and lamb segments, though fresh chilled formats face spoilage-driven reclamation costs that erode urban retail margins. Supply concentrates in Brazil for frozen poultry, Australia for live sheep and grain-fed beef, and domestic Central Region feedlots for local chicken. Raw material dependencies include imported soybean meal, domestic barley, and veterinary biologics for foot-and-mouth containment. Single-source vulnerability runs through Damman port livestock import quotas. Distribution runs through supermarket private-label programs and HoReCa procurement cooperatives that bypass traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's edible meat market functions as a stable compounder, with Vision 2030 hospitality expansion providing secular demand tailwinds that outpace cyclical feed cost volatility. Steady growth rests on irreversible urbanization and protein consumption intensification across institutional channels.
For Market Incumbents: Cement halal certification infrastructure advantages by acquiring SFDA-accredited slaughter inspectors and expanding captive cold-chain fleets into Eastern Province whitespace. Plant protein substitution in institutional foodservice contracts threatens volume retention, requiring backward integration into grain farming to narrow cost gaps with imports.
For New Entrants and Emerging Players: Enter via Dammam and Khobar retail density gaps where branded fresh meat counters remain underpenetrated relative to Riyadh. Online retail subscription models for portion-controlled packs offer the most penetrable go-to-market angle, leveraging same-day delivery logistics maturation in urban household segments.
For Investors and Strategic Acquirers: Regional poultry processors with established GCC export halal certification are the most active acquirers in this space, consolidating mid-tier abattoirs facing legacy ERP replacement burdens. Long-term viability hinges on blockchain traceability infrastructure deployment. Acquisition target archetypes include specialized lamb processors with Australian live import relationships. Monitor SFDA amendments to video verification requirements as inflection indicators for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | SFDA's 2024 halal documentation amendments mandate redundant data infrastructure for export-bound meat verification. |
| Robotic Deboning Deployment | Supermarket private-label programs automate labor-intensive poultry stages to secure consistent portion weights. |
| Backward Grain Farming Integration | Almarai and Tanmiah narrow cost gaps with imports through captive feed milling and domestic barley sourcing. |
| Eastern Province Retail Expansion | Dammam and Khobar whitespace creates branded fresh meat counter opportunities absent in saturated Central Region. |
| GCC Export Halal Certification | Mutual recognition agreements unlock UAE and Bahrain foodservice channels for Saudi-processed lamb. |
Research Methodology
Direct dialogue with SFDA compliance officers, hospitality procurement directors, integrated poultry processor operations heads, and supermarket category managers grounded qualitative findings in regulatory and channel-specific dynamics. Secondary validation drew from SFDA halal certification registries, SASO technical regulation amendments, Vision 2030 hospitality investment disclosures, and customs import quota allocations. Bottom-up volume modeling triangulated against top-down protein consumption intensity benchmarks.
Segmented outputs across product type, distribution channel, end user, and processing type dimensions were generated through the projection horizon. CAGRs emerged from feed cost elasticity modeling, hospitality F&B footprint expansion rates, and SFDA enforcement intensity assumptions. Forecast inputs incorporated livestock import quota rigidity, water scarcity constraints on domestic feedlot expansion, and plant protein substitution curves in institutional contracts.
Inputs from SFDA certification databases and hospitality procurement cooperatives were available through the study window; gaps in real-time blockchain adoption rates introduce uncertainty bands around traceability-premium capture assumptions. Forecasts reflect documented assumptions regarding subsidy framework continuity and biosecurity protocol stringency. Practitioners should monitor SFDA amendments to video verification mandates and GCC mutual recognition agreement expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Emulsions Market
Meat Products
Global Poultry Meat Market
Meat Products
Organic Pork Market
Meat Products
Canned Pork Market
Meat Products
Hams Market
Meat Products
Beef Bouillon Market
Meat Products
Meat Ingredients Market
Meat Products
Blended Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Meat Mincers Market
Meat Products
Europe Canned Meat Market
Meat Products
Organic Meat Market
Meat Products
Chicken Fat Market