
 Global Red Meat Market | 2026-2036
Global Red Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Red Meat Market Foresight
The capital-intensity divergence between integrated packers and regional processors is unwinding competitive stability in red meat supply chains. JBS leverages captive cattle supply and owned processing capacity across Brazil, Argentina, and the United States. Tyson Foods anchors its margin structure through in-house feed production and controlled distribution to food service accounts. Cargill competes via diversified protein sourcing that spans beef, pork, and poultry to buffer species-specific price cycles.
Red meat encompasses skeletal muscle tissue from domesticated and game mammals, principally cattle, swine, sheep, and goats, characterized by myoglobin concentrations exceeding 0.6 percent that produce distinctive color and iron content. Industrial processing transforms carcasses into primal cuts, ground formulations, and value-added items through chilling, aging, and mechanical separation for retail and food service distribution. Beef dominates value generation across most geographies due to extended finishing periods and premium positioning in food service channels, while pork leads volume throughput in fresh and cured formats across Asian wholesale markets. The ready-to-cook segment captures expanding margin pools as institutional buyers seek labor-saving portion control, though fresh carcass trade remains the structural baseline for price discovery in producer markets.
FDA oversight of pathogen reduction and residue testing shapes product standards for US export eligibility, while EU Green Deal emission benchmarks and REACH chemical safety protocols constrain feed additive portfolios and manure management systems across European operations. Brazil's MAPA enforces equivalent sanitary standards for access to Chinese and Middle Eastern import markets, creating regulatory convergence pressure on South American packers. Stakeholders must monitor divergence between EU livestock emission caps and import demand growth in Southeast Asia and the Gulf states, where regulatory stringency lags consumer income expansion.
Market Dynamics
EU Green Deal livestock emission benchmarks are tightening feedlot compliance costs for European processors while Southeast Asian food manufacturers expand cold-chain procurement of ready-to-cook portions. This regulatory divergence between emission-constrained Europe and demand-surging Asia is redrawing competitive advantage toward Brazilian and Australian packers with lower-carbon intensity herds.
Growth Catalysts
- EU Green Deal livestock emission benchmarks:European processors investing in methane-reduction feed additives and manure management systems gain preferential access to carbon-conscious retail channels in Germany and the Netherlands.
- Ready-to-cook portion demand:Food service operators in Singapore, Thailand, and Vietnam are consolidating procurement around pre-portioned beef and pork to reduce kitchen labor costs and standardize portion control.
- Brazilian export processing clusters:Minas Gerais and Mato Grosso packers leverage integrated cattle supply and port logistics to dominate Middle Eastern and Chinese import tenders.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with Black Sea export disruptions and US drought cycles, compressing finishing margins for non-integrated feedlot operators.
- Chinese import quota concentration:Brazil and Australia control over three-quarters of frozen beef access permits, locking out smaller exporting nations from premium chilled segment growth.
- Cell-cultured protein substitution:Singapore and Israel regulatory approvals for lab-grown beef are establishing technical pathways that food service buyers will pilot for sustainability commitments.
Strategic Opportunities
- Indonesian cold-chain infrastructure gaps:Domestic beef consumption outruns refrigerated distribution capacity, creating first-mover advantage for packers building halal-certified processing and last-mile freezing networks.
- Blockchain traceability mandates:Walmart and Carrefour supplier requirements for farm-to-fork tracking are opening premium shelf space for early adopters of distributed ledger verification systems.
- Precision fermentation feed additives:Dutch and Danish biotechnology firms are commercializing methane-suppressing supplements that reduce enteric emissions without antibiotic residue concerns under FDA and EFSA guidelines.
Industry Challenges
- Veterinary pharmacology compliance timelines:Residue testing protocols under Brazil's MAPA and China's GACC require 12-18 month validation cycles that delay product launches in high-growth import markets.
- Halal certification fragmentation:Divergent standards between Indonesia's MUI, Malaysia's JAKIM, and Saudi Arabia's SFDA force packers to maintain multiple audit trails and slaughter protocols for Muslim-majority markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Red Meat Market |
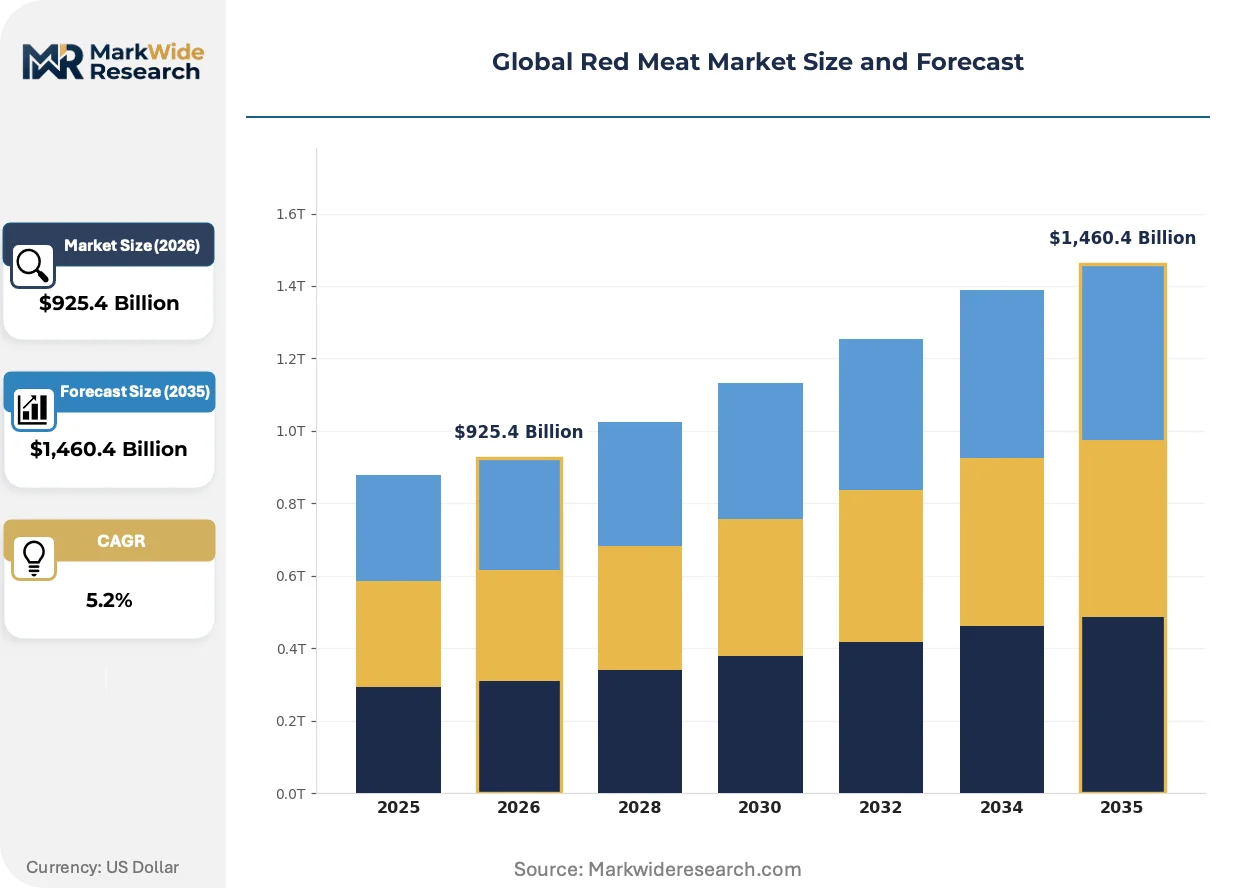
| Market Size in 2026 | $925.4 Billion |
| Market Size in 2035 | $1,460.4 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Lamb, Pork, Goat, Venison Processing Method: Fresh, Frozen, Cured, Smoked, Ready-to-Cook Distribution Channel: Supermarkets, Butcher Shops, Online Retailers, Food Service, Wholesalers End User: Restaurants, Institutional Buyers, Catering Services, Food Manufacturers |
| Companies Covered | JBS, Tyson Foods, Cargill, WH Group, Marfrig, Minerva Foods, Hormel Foods, BRF, OSI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Red Meat Market Shifts & Advancements
Processing technology and regulatory transparency requirements are compressing traditional margin structures while opening new value pools in verification and precision agriculture. Three developments are restructuring how red meat moves from farm to consumer.
Blockchain-enabled provenance tracking is fragmenting the historical information asymmetry between producers and retailers. Supermarket chains in France and the United Kingdom are mandating immutable farm-origin records for premium beef lines. This transparency infrastructure is compressing spot-market anonymity and forcing commodity packers to document welfare and environmental credentials previously treated as trade secrets.
REACH chemical safety protocols and EU Green Deal emission benchmarks are constraining feed additive portfolios across European operations. Manufacturers must reformulate growth promoters and acidifiers to meet substance restriction lists while maintaining feed conversion ratios. German and Danish compound feed producers are accelerating enzyme-based alternatives that satisfy EFSA safety thresholds without sacrificing performance metrics in finisher diets.
Food service buyers in the United Arab Emirates and Saudi Arabia are consolidating procurement through centralized tender platforms that disintermediate traditional meat traders. Hospital and airline catering contracts now specify exact fat content, aging duration, and origin documentation that only integrated packers can guarantee. This specification tightening favors Brazilian and Australian suppliers with captive breeding-to-processing control over fragmented European spot-market sourcing.
Global Red Meat Market Segmentation
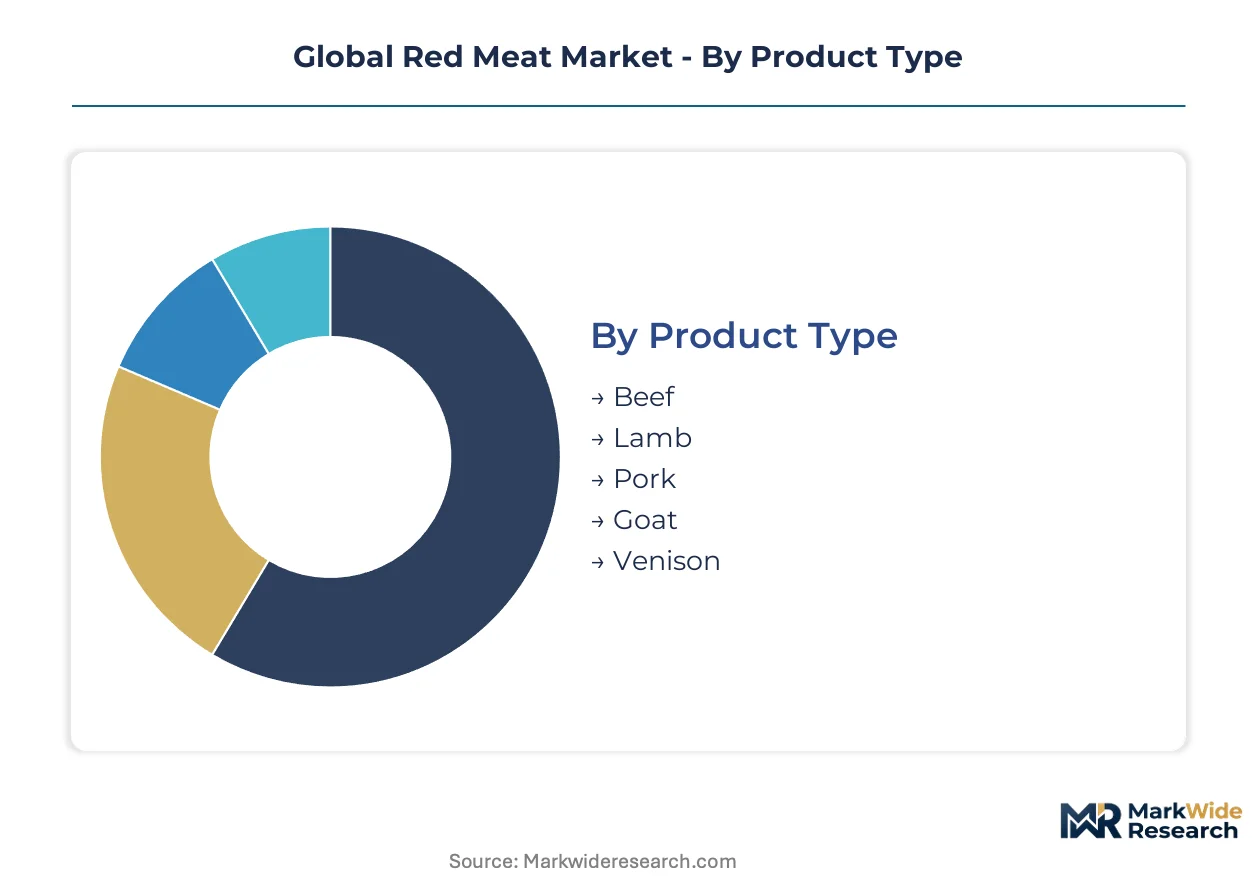
Red meat markets fragment across species lines, processing intensity, and channel control points that determine margin capture. Understanding these divisions reveals where capital concentrates and where regulatory or logistics barriers create defendable positions.
Product Type:
Beef and pork dominate export-led trade flows while lamb and goat serve culturally specific domestic markets with limited cross-border movement.
- Beef:Extended grain-finishing periods and marbling specifications command premium positioning in food service channels across the United Arab Emirates and Japan. Brazilian and Australian packers with integrated breeding-to-processing control capture the bulk of chilled export tenders to high-specification buyers.
- Pork:Higher reproductive efficiency and shorter finishing cycles enable volume throughput in fresh and cured formats across Asian wholesale markets. Chinese consumption patterns and German processing standards together shape global pricing benchmarks for bellies and hams.
- Lamb:Seasonal production cycles and halal slaughter requirements limit export scalability outside New Zealand and Australia. Demand concentrates in Middle Eastern import markets and European Easter-season retail promotions.
- Goat:Small-scale herding structures and localized consumption in South Asia, the Caribbean, and parts of Africa restrict industrial processing penetration. Live animal trade exceeds carcass exports due to cold-chain infrastructure gaps in producing regions.
- Venison:Game farming regulations in New Zealand and wild harvest quotas in North America constrain supply predictability. Premium positioning in European retail and North American restaurant channels depends on traceability certification and seasonal availability.
Beef holds the largest share; momentum sits with pork as Asian food service demand climbs the fastest.
Processing Method:
Cost tier differentiation separates commodity carcass trade from value-added formats that capture labor savings downstream.
- Fresh:Chilled carcass and primal cuts remain the structural baseline for price discovery in producer markets from Nebraska to Mato Grosso. Rapid spoilage windows and refrigerated transport requirements limit export radius to regional trade zones.
- Frozen:Blast-freezing at -18°C extends shelf life for intercontinental shipment to Chinese and Middle Eastern import markets. Brazilian and Australian exporters dominate frozen beef tenders through dedicated port cold storage infrastructure.
- Cured:Salt, nitrite, and fermentation treatments transform pork into hams, bacon, and salami with extended ambient stability. Italian and Spanish protected designation of origin frameworks create premium pricing tiers inaccessible to commodity processors.
- Smoked:Thermal processing with hardwood combustion deposits flavor compounds and surface preservation barriers. Central European and North American regional styles command loyalty in specialty retail and food service niches.
- Ready-to-Cook:Pre-portioned, marinated, or seasoned products reduce kitchen labor costs for Singaporean, Thai, and Vietnamese food manufacturers. Margin pools expand as institutional buyers consolidate procurement around specification-guaranteed convenience formats.
Fresh maintains volume leadership; ready-to-cook formats gain share fastest as labor costs rise across Southeast Asian food service.
Distribution Channel:
Customer type concentration determines whether packers sell on spot markets or lock in multi-year contract structures.
- Supermarkets:French and British chains now mandate blockchain-enabled farm-origin records for premium beef lines, compressing anonymity for commodity suppliers. Carrefour and Walmart supplier requirements favor integrated packers with documented welfare and environmental credentials.
- Butcher Shops:Independent meat cutters in Italy, Argentina, and Japan maintain relationships with specific farms or regional slaughterhouses. Personalized cutting specifications and aging preferences sustain premium pricing outside standardized retail formats.
- Online Retailers:Direct-to-consumer platforms in Chinese tier-one cities and South Korean urban centers bypass traditional wholesale layers. Cold-chain last-mile capabilities determine whether fresh or frozen formats dominate regional e-commerce penetration.
- Food Service:Hospital and airline catering contracts in Saudi Arabia and the United Arab Emirates specify exact fat content, aging duration, and origin documentation. Centralized tender platforms disintermediate traditional meat traders and favor suppliers with captive breeding-to-processing control.
- Wholesalers:Traditional meat traders in Indonesian and Vietnamese wet markets handle live animal and carcass distribution where refrigeration remains inconsistent. Consolidation pressure from modern retail and food service procurement platforms erodes historical intermediary roles.
Food service commands the steepest expansion trajectory; supermarkets retain the largest value share through private label consolidation.
End User:
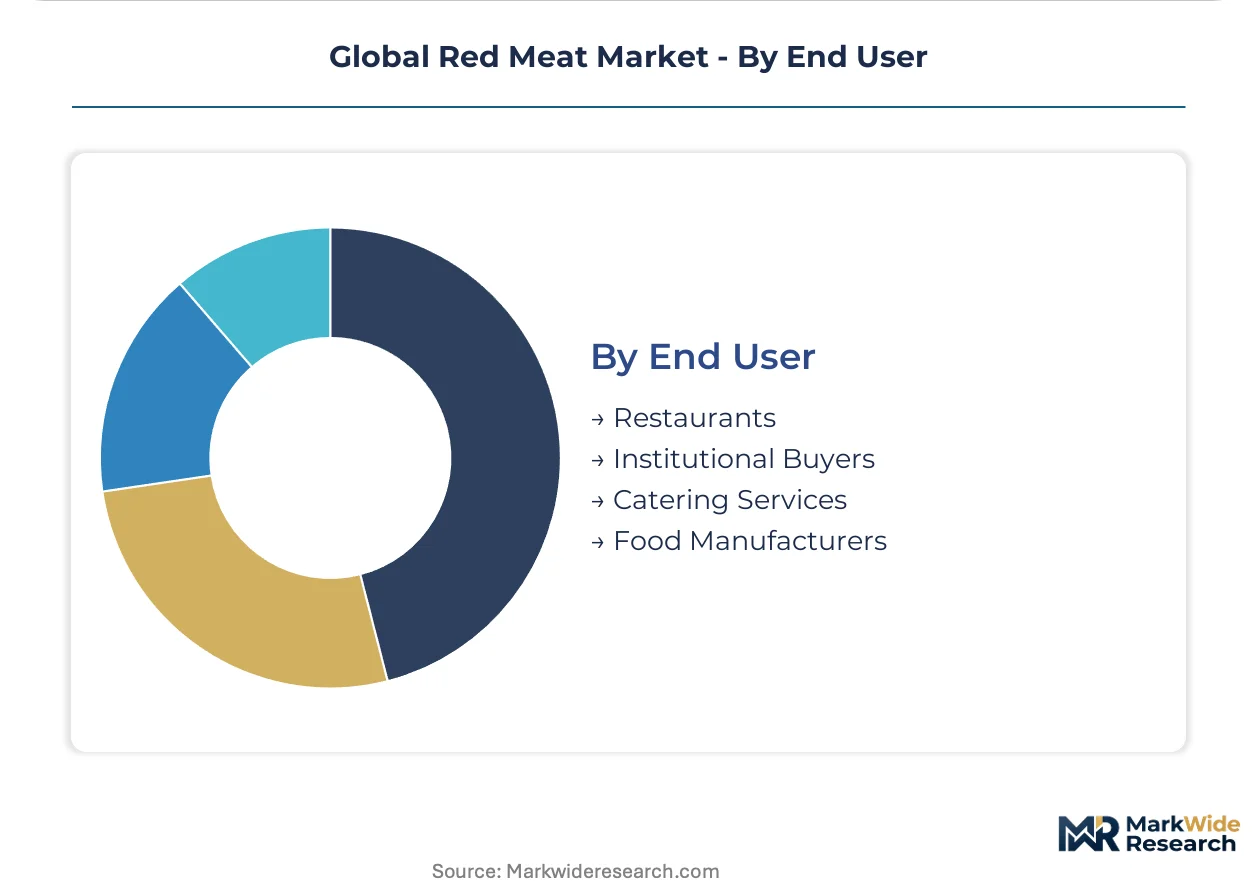
Application intensity varies from high-volume commodity procurement to specification-driven premium contracting.
- Restaurants:Steakhouse chains in Japan, South Korea, and the United States compete on USDA grade or Wagyu lineage authentication. Menu engineering around specific primal cuts creates demand concentration for ribeye and tenderloin that distorts carcass valuation.
- Institutional Buyers:School districts, military commissaries, and prison systems in the United States and Europe prioritize cost control through ground beef and processed pork tenders. Specifications emphasize lean percentage and pathogen testing compliance over provenance attributes.
- Catering Services:Event and airline catering operations in the Gulf states require halal certification, portion consistency, and just-in-time delivery reliability. Brazilian and Australian suppliers with multiple halal audit trails capture contract renewals through compliance breadth.
- Food Manufacturers:Processed meat producers in Thailand, Vietnam, and the Philippines source frozen pork and beef for sausage, canned, and ready-meal formulations. Ingredient cost sensitivity drives procurement toward Brazilian and European spot markets with price volatility exposure.
Restaurants generate the highest margin per kilogram; food manufacturers represent the largest absolute volume offtake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Brazilian and Australian buyers accept premium pricing for specification-guaranteed chilled beef, while Indonesian and Vietnamese markets remain acutely price-sensitive on frozen imports.
Brazil
Export-oriented processors dominate Middle Eastern and Chinese tender markets through integrated Mato Grosso and Minas Gerais clusters. MAPA enforces sanitary standards equivalent to Chinese GACC protocols for chilled beef access. São Paulo-based packers anchor halal-certified production lines serving Gulf state procurement platforms.
United States
Grain-fed beef commands food service premiums in Japan and South Korea through USDA grade authentication. FDA pathogen reduction and residue testing frameworks shape export eligibility protocols. Nebraska and Texas feedlot corridors supply Tyson Foods and Cargill with captive cattle flows for international chilled programs.
China
Import quota concentration limits market access to Brazilian and Australian frozen beef suppliers. NMPA and SAMR enforce dual carbon goals that tighten feedlot emission disclosures for domestic processors. Shanghai and Guangzhou cold-chain hubs distribute premium chilled cuts to tier-one restaurant chains.
Australia
Grass-fed positioning captures carbon-conscious retail channels in Germany and the Netherlands. EFSA-equivalent standards under DAWR protocols maintain EU market access despite Brexit trade friction. Queensland and New South Wales breeding operations supply integrated packers with traceable herd documentation for blockchain-enabled provenance programs.
Germany
Domestic consumption shifts toward pork as EU Green Deal livestock emission benchmarks compress beef finishing margins. ECHA REACH protocols and EFSA feed additive restrictions force reformulation of growth promoters. Lower Saxony and North Rhine-Westphalia processing clusters invest in methane-suppressing supplement trials to defend retail shelf access.
Global Red Meat Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in red meat supply chains. Brazilian and US packers with captive cattle supply and owned processing capacity capture premium export tenders, while regional processors compete on spot-market spot purchasing. Three archetypes dominate: integrated breeding-to-processing conglomerates, diversified protein platforms spanning species, and halal-certified specialists serving Muslim-majority import markets. Competitive moves concentrate on backward integration into feed production and port cold storage infrastructure to guarantee specification compliance.
Within the integrated conglomerate tier, JBS and Tyson Foods occupy positions defined by geographic production breadth and channel control. Minerva Foods exemplifies the export-specialist archetype with concentrated Brazilian processing clusters. Cargill represents diversified protein platforms that buffer species-specific price cycles through portfolio spanning beef, pork, and poultry operations.
| Leading Market Players |
|---|
| JBS |
| Tyson Foods |
| Cargill |
| WH Group |
| Marfrig |
| Minerva Foods |
| Hormel Foods |
| BRF |
| OSI Group |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Brazilian packers and Chinese state-owned importers lock in both supply access and price visibility across eighteen-month tender windows, insulating integrated processors from spot-market volatility while exposing non-contracted operators to margin compression when feed grain costs spike.
Pricing Analysis
After-sales service revenue from halal certification maintenance and blockchain traceability subscriptions drives lifetime value for premium beef exporters. Three-tier pricing structure across premium chilled, standard frozen, and economy carcass tiers stratifies according to marbling grade and origin documentation depth. Pricing pressure stems from Black Sea grain export disruptions elevating feed input costs for non-integrated European finishers. Food manufacturers in Southeast Asia exhibit acute price sensitivity, while Gulf state hospital catering contracts tolerate premiums for specification-guaranteed consistency.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates container dwell times on the Asia-South America trade lane, compressing exporter margins through demurrage exposure and vessel scheduling uncertainty. Supply concentrates in Brazil, Australia, and the United States, with Mato Grosso breeding operations and Queensland grass-fed herds anchoring global export flows. Feed grain, veterinary pharmaceuticals, and refrigerated container capacity constitute critical input dependencies. Single-source vulnerability to Chinese import quota allocation decisions threatens market access for emerging exporters. Distribution runs through centralized tender platforms in Saudi Arabia and the United Arab Emirates that disintermediate traditional wholesale traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-cultured protein regulatory approvals in Singapore and Israel signal a technological inflection that will disrupt conventional red meat procurement patterns within food service sustainability commitments.
For Market Incumbents: Fortify backward integration into captive cattle supply and owned port cold storage infrastructure to defend margin position against feed grain volatility and emerging lab-grown protein substitutes. Invest in methane-suppressing feed additive portfolios to preempt EU Green Deal emission benchmark compliance costs and secure carbon-conscious retail shelf access in Germany and the Netherlands. For New Entrants and Emerging Players: Differentiate on halal-certified ready-to-cook portion innovation for Indonesian and Vietnamese food manufacturers where domestic cold-chain infrastructure gaps create first-mover advantage. Target centralized hospital and airline catering tender platforms in the Gulf states with blockchain-enabled provenance documentation that incumbent commodity traders cannot match. For Investors and Strategic Acquirers: Export-specialist packers with integrated breeding-to-processing control in Brazil's Mato Grosso corridor offer asymmetric exposure to Chinese import quota concentration and Middle Eastern procurement platform consolidation. Watch for Singaporean regulatory pathway expansions for cell-cultured beef as the signal indicating accelerated substitution timelines in premium food service channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Production | Corn and soybean meal cost exposure diminishes for Tyson Foods and JBS through captive supply. |
| Blockchain Traceability Deployment | Carrefour and Walmart supplier mandates open premium shelf space for early adopter packers. |
| Halal Certification Expansion | Multiple audit trails covering Indonesia's MUI, Malaysia's JAKIM, and Saudi Arabia's SFDA secure Gulf state contract renewals. |
| Precision Fermentation Feed Additives | Dutch biotechnology firms commercialize methane-suppressing supplements satisfying EFSA thresholds without antibiotic residue concerns. |
| Cold-Chain Infrastructure Buildout | Last-mile freezing networks in Indonesian urban centers capture domestic beef consumption outpacing refrigerated distribution capacity. |
Research Methodology
Desk research of customs trade databases, FDA and EFSA regulatory filings, and MAPA sanitary protocol documentation preceded structured interviews with beef procurement directors at Southeast Asian food manufacturers, halal certification auditors in Indonesia and Malaysia, and cold-chain logistics operators in São Paulo and Shanghai. Primary fieldwork with Brazilian export packers and Australian grass-fed breeding operations combined with secondary validation against GACC import quota records and EU Green Deal emission benchmark drafts. Bottom-up volume modeling across species segments triangulated against top-down trade flow analysis.
Variance decomposition across the projection horizon isolates feed grain price volatility, Chinese import quota reallocation, and cell-cultured protein substitution elasticity as primary forecast uncertainty drivers. Segmentation dimensions span species type, processing intensity, distribution channel control, and regional regulatory cluster. CAGRs derive from trade flow momentum analysis and capacity expansion pipelines in Mato Grosso and Queensland. Industry-specific inputs include veterinary pharmacology compliance timelines under Brazil's MAPA and blockchain provenance adoption curves in French and British retail.
The analysis sits within stated boundaries; outcomes outside sustained Chinese import demand growth, stable Black Sea grain export corridors, and incremental rather than disruptive cell-cultured protein substitution would require recalibration. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and Southeast Asian cold-chain infrastructure investment flows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Paste Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
North America Canned Meat Market
Meat Products
China Processed Meat Market
Meat Products
North America Edible Meat Market
Meat Products
Chilled Meat Market
Meat Products
Global Edible Meat Market
Meat Products
Low Fat Sausage Market
Meat Products
North America Processed Meat Market
Meat Products
Global Canned Meat Market
Meat Products
Global Duck Meats Market
Meat Products
Organic Halal Meat Market
Meat Products
Organic Beef Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Hams Market