
 Gas and Solid Fuels (Wood) Fireplaces Market | 2026-2036
Gas and Solid Fuels (Wood) Fireplaces Market Size, Share, and Industry Trends Forecast 2026-2036
Gas and Solid Fuels (Wood) Fireplaces Market Foresight
European hearth manufacturers is recalibrating production schedules after Nordic pellet supply tightened through Baltic Sea routing constraints. Travis Industries leverages its vertically integrated foundry network across the Pacific Northwest to sustain cast-component availability for wood-burning inserts. FPI Fireplace Products International anchors its competitive stance through CSA-certified gas fireplace engineering tailored to Canadian efficiency mandates. HNI Corporation dominates the commercial lodge segment with modular built-in systems engineered for high-altitude combustion performance.
Gas and solid fuels fireplaces encompass enclosed combustion chambers designed for residential and hospitality heating, typically fabricated from steel or cast iron with refractory brick linings and rated for thermal outputs between 20,000 and 70,000 BTU per hour depending on fuel configuration and venting architecture. Their primary purpose centers on zone heating, architectural ambiance, and supplementary thermal load management in detached dwellings and boutique lodging properties. Wood-burning fireplaces retain the largest installed base across North American rural markets, yet gas fireplace inserts capture margin concentration through higher average selling prices and reduced installation complexity. Pellet stoves represent the fastest-expanding fuel-type category, propelled by automated feed systems and particulate emissions profiles that satisfy EPA Phase II certification thresholds.
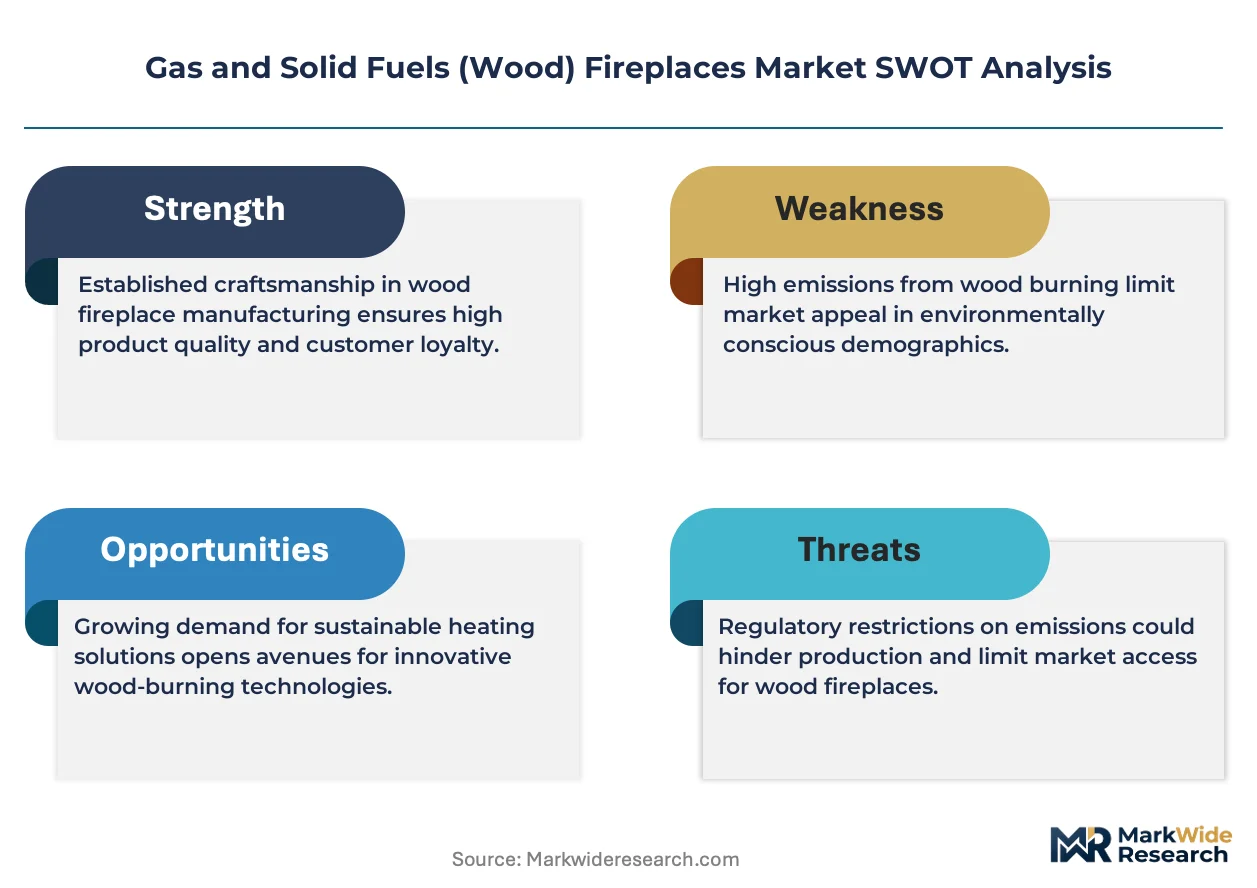
The EPA's New Source Performance Standards for residential wood heaters mandate maximum particulate emissions of 2.0 grams per hour, forcing manufacturers to redesign combustion air delivery and catalytic after-treatment systems. The EU Ecodesign Directive and associated F-Gas Regulation constrain gas fireplace efficiency minimums and refrigerant-based heat pump alternatives, indirectly preserving market space for direct-vent gas technologies. CSA Group and Underwriters Laboratories maintain parallel certification pathways that shape cross-border product eligibility between the United States and Canada. Stakeholders must monitor evolving municipal burn bans and wood moisture content enforcement protocols that could abruptly restrict addressable markets in high-growth western states and provinces.
Market Dynamics
The EPA's New Source Performance Standards and the EU Ecodesign Directive are compressing product development cycles, forcing manufacturers to redesign combustion architectures around sub-2.0 gram per hour particulate thresholds while maintaining thermal efficiency ratings.
Growth Catalysts
- EPA Phase II Certification Thresholds:Stringent particulate caps are accelerating R&D investment in catalytic after-treatment systems and automated air-mixing controls among hearth equipment fabricators.
- Rural Residential Retrofit Demand:Cold-climate homeowners in Minnesota, Wisconsin, and Vermont are replacing open masonry hearths with EPA-certified inserts to capture zone-heating efficiency gains.
- Pellet Fuel Infrastructure Maturation:Automated feed systems and bulk delivery networks in Austria and northern Italy are reducing operational friction for solid-fuel adopters.
Market Restraints
- Cast Iron Input Cost Volatility:Foundry-grade pig iron pricing swings are compressing margin buffers for manufacturers dependent on Pacific Northwest and Great Lakes metal sourcing.
- Baltic Sea Routing Constraints:Nordic wood pellet supply concentration through constrained maritime corridors is elevating inventory carrying costs for European distributors.
- Heat Pump Substitution:Cold-climate air-source heat pumps achieving coefficient of performance above 2.5 are capturing share in new-construction segments previously served by gas fireplaces.
Strategic Opportunities
- Western US Municipal Incentive Programs:Colorado and Utah counties are offering tax credits for EPA-certified wood-burning retrofits, opening addressable markets under burn-ban jurisdictions.
- Hospitality Biophilic Design Integration:Boutique lodge developers in British Columbia and Montana are specifying modular built-in systems as architectural focal points with zone-heating functionality.
- Direct-to-Installer Digital Platforms:Configurator tools enabling HVAC contractors to specify venting architectures and clearances are compressing specification cycles in the professional channel.
Industry Challenges
- Combustion Engineering Talent Scarcity:Specialized expertise in catalytic reactor design and computational fluid dynamics modeling is concentrating among a narrow cohort of veteran practitioners.
- CSA-UL Cross-Border Certification Parallelism:Maintaining dual certification pathways for United States and Canadian eligibility extends product launch timelines by eight to fourteen months.
- Legacy Masonry Retrofit Integration:Field-modified venting configurations in pre-1980 dwellings create liability exposure and installation variability that erodes standardized margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas and Solid Fuels (Wood) Fireplaces Market |
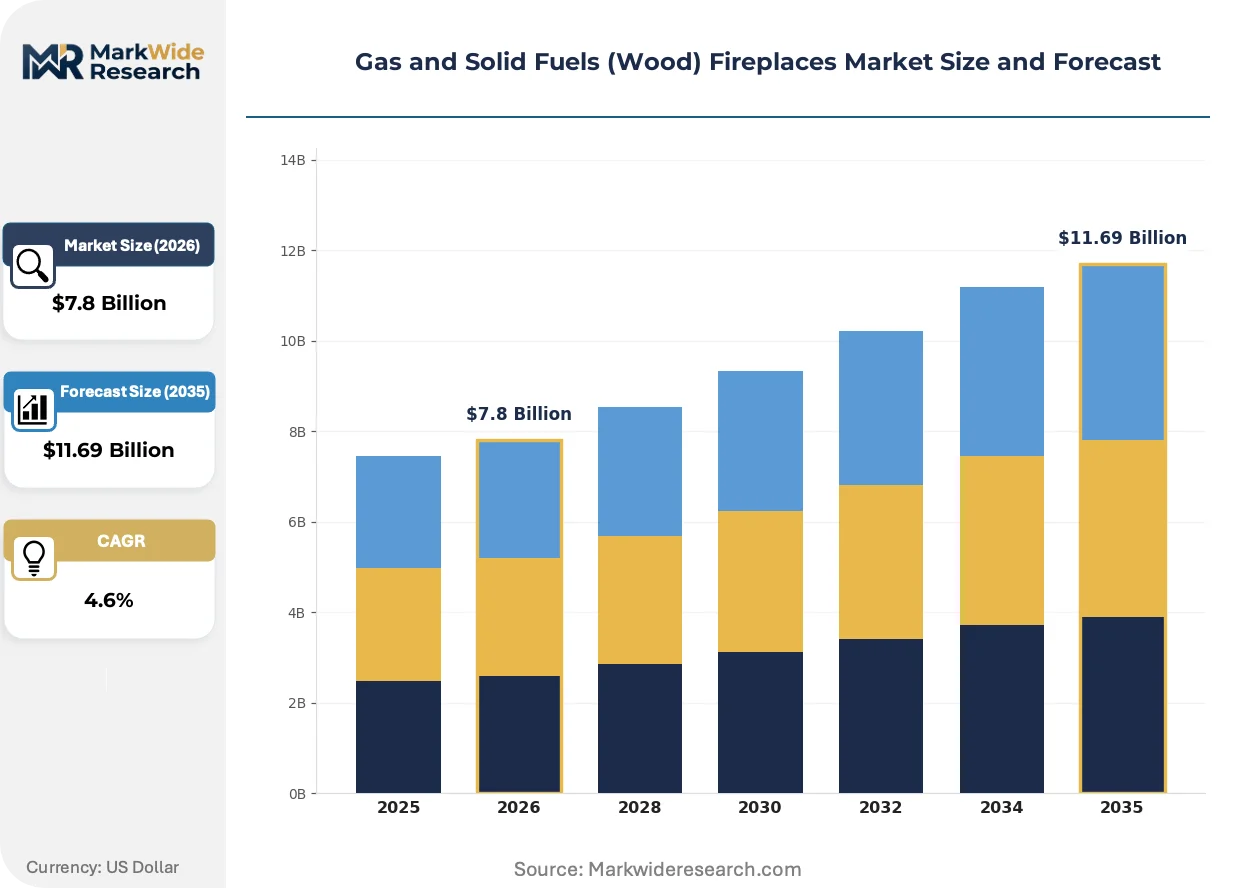
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
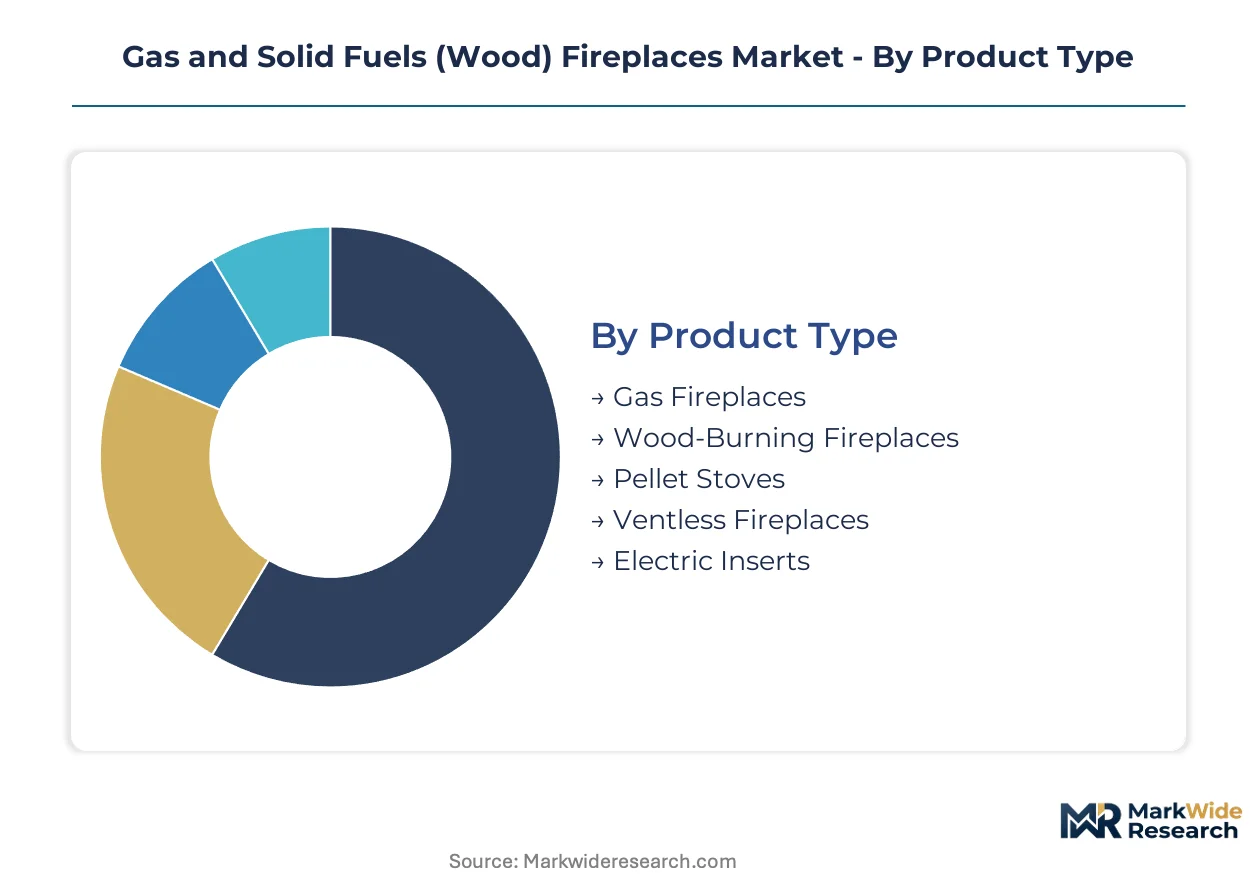
| Segmentation | Product Type: Gas Fireplaces, Wood-Burning Fireplaces, Pellet Stoves, Ventless Fireplaces, Electric Inserts Fuel Type: Natural Gas, Propane, Wood Logs, Wood Pellets, Ethanol, Coal Installation Type: Built-in, Freestanding, Wall-mounted, Insert, Corner, Outdoor End User: Homeowners, Lodge Facilities, Cabin Owners, Vacation Rentals, Boutique Inns |
| Companies Covered | Travis Industries, Inc., FPI Fireplace Products International Ltd., HNI Corporation, Stovax Gazco, Jotul Group, Glen Dimplex Group, Empire Comfort Systems Inc., Kozy Heat, Napoleon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas and Solid Fuels (Wood) Fireplaces Market Shifts & Advancements
Combustion control electronics and connected-home platforms are converging with traditional hearth engineering, reshaping how manufacturers differentiate thermal performance and user experience.
Hybrid gas-wood dual-fuel combustion chambers are unifying flexibility and emissions compliance in single-platform architectures. Rural property owners in Quebec and Maine are specifying these systems at accelerating rates to hedge fuel price volatility. The technology is unifying previously segmented product categories, compressing SKU proliferation while expanding addressable use cases across heating-degree-day zones.
REACH chemical restrictions and the EU F-Gas Regulation are constraining refrigerant-based heat pump alternatives in European residential applications. This regulatory friction is preserving market space for direct-vent gas technologies that achieve efficiency minimums without vapor-compression cycles. German and Austrian manufacturers are responding by engineering condensing gas fireplace architectures that recover latent heat from flue gases.
Specification decisions are migrating from retail showrooms toward HVAC contractor and builder channels as installation complexity rises. Professional installers in Ontario and Pennsylvania are displacing consumer-direct purchases through bundled mechanical-system proposals. This channel rotation is most visible in new-construction segments where fireplaces are specified as components of integrated thermal packages rather than standalone aesthetic additions.
Gas and Solid Fuels (Wood) Fireplaces Market Segmentation
Combustion architecture and venting configuration determine thermal efficiency, installation cost, and regulatory compliance across hearth product categories. Specification decisions increasingly flow through HVAC contractors rather than retail channels as emissions certification complexity rises.
Product Type:
Combustion chamber design and fuel delivery mechanisms differentiate thermal output ranges and particulate emissions profiles.
- Gas Fireplaces:Direct-vent and B-vent configurations employing ceramic fiber or refractory brick linings achieve steady-state thermal outputs between 20,000 and 70,000 BTU per hour. Demand concentrates in Minnesota and Wisconsin where homeowners retrofit open masonry hearths for zone-heating efficiency under EPA Phase II guidelines.
- Wood-Burning Fireplaces:EPA-certified inserts with catalytic after-treatment systems and automated air-mixing controls satisfy sub-2.0 gram per hour particulate thresholds. Rural property owners across Vermont and Maine are replacing inefficient open hearths to capture heating-degree-day performance gains and qualify for municipal retrofit incentives.
- Pellet Stoves:Automated auger-fed systems burning compressed wood biomass achieve emissions profiles below EPA Phase II certification thresholds with reduced operational friction versus cordwood.
- Ventless Fireplaces:Unvented combustion chambers employing oxygen depletion sensors and catalytic converters for indoor air quality management in jurisdictions permitting their installation.
- Electric Inserts:Resistance-element or infrared heating modules requiring no venting infrastructure, specified primarily for aesthetic flame simulation in multi-family dwellings with combustion restrictions.
Mature deployment sits with wood-burning fireplaces. Newer deployment is concentrated in pellet stoves.
Fuel Type:
Energy density and supply chain accessibility shape operating economics and geographic adoption patterns.
- Natural Gas:Pipeline-delivered methane achieving consistent combustion characteristics and reduced particulate emissions versus solid fuels. Specified across Colorado and Utah counties offering tax credits for efficient heating retrofits under burn-ban jurisdictions.
- Propane:Liquefied petroleum gas stored in on-site tanks, enabling fireplace installation in rural localities beyond natural gas distribution networks. Demand concentrates in cabin properties across Montana and British Columbia where pipeline infrastructure is absent.
- Wood Logs:Cordwood fuel sourced from hardwood species with moisture content enforcement protocols varying by municipality.
- Wood Pellets:Densified biomass fuel standardized for automated feed systems, with Nordic supply routing through Baltic Sea corridors.
- Ethanol:Liquid biofuel burned in ventless configurations for architectural ambiance without thermal load management requirements.
- Coal:Anthracite or bituminous fuel specified in legacy installations, declining under emissions regulations.
Established heating infrastructure favors natural gas. Expanding most quickly are wood pellets.
Installation Type:
Spatial integration and venting architecture determine project complexity and margin structures for professional installers.
- Built-in:Factory-engineered firebox assemblies framed into wall cavities during new construction or major renovation. Boutique lodge developers in British Columbia and Montana specify modular built-in systems as architectural focal points with zone-heating functionality.
- Freestanding:Self-supporting stove units on non-combustible hearth pads, permitting relocation and simplified venting through ceiling penetrations. Cabin owners across rural Quebec and Maine favor these configurations for heating flexibility and fuel hedging.
- Wall-mounted:Suspended combustion chambers minimizing floor footprint in compact residential footprints.
- Insert:Retrofit firebox assemblies sliding into existing masonry chimney throats, capturing efficiency gains without structural modification.
- Corner:Angled firebox designs maximizing sightlines in spatially constrained great rooms.
- Outdoor:Weatherized combustion chambers for patio heating and hospitality exterior zones.
Retrofit activity centers on inserts. Steepest expansion trajectory is occurring in built-in systems.
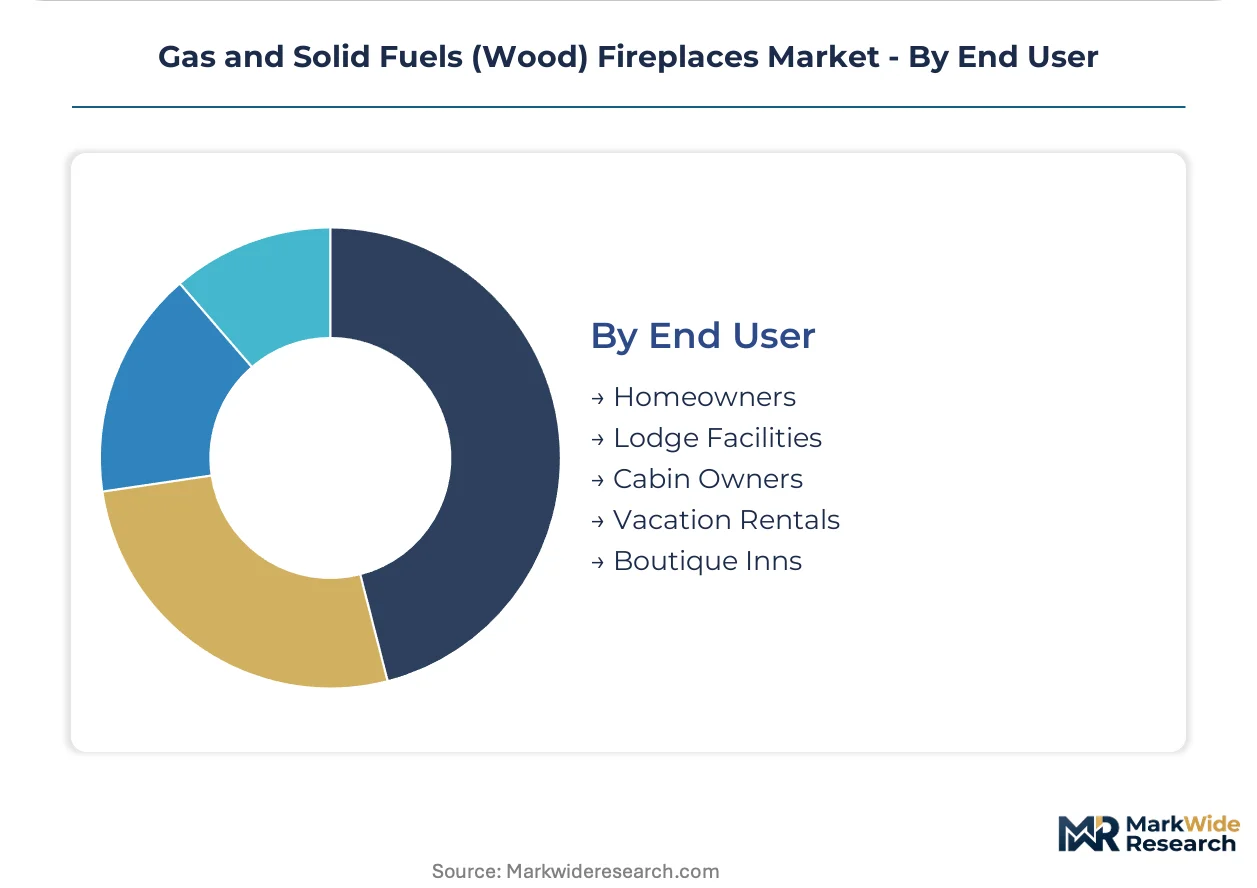
End User:
Application context dictates performance requirements, aesthetic priorities, and procurement channel preferences.
- Homeowners:Residential occupants specifying zone-heating solutions for detached dwellings, increasingly routing purchases through HVAC contractor channels rather than retail showrooms as installation complexity rises. Professional installers in Ontario and Pennsylvania displace consumer-direct purchases through bundled mechanical-system proposals.
- Lodge Facilities:Commercial hospitality properties requiring modular built-in systems engineered for high-altitude combustion performance and continuous operation cycles. HNI Corporation dominates this segment with products specified for boutique properties across mountain regions.
- Cabin Owners:Seasonal or remote property occupants prioritizing fuel flexibility and off-grid heating independence.
- Vacation Rentals:Short-term hospitality properties specifying low-maintenance gas configurations for guest safety and operational simplicity.
- Boutique Inns:Small-scale hospitality properties integrating fireplaces as biophilic design elements with zone-heating functionality.
Volume concentration rests with homeowners. Gaining share fastest are lodge facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Great Lakes foundry clusters supply cast-iron firebox components to North American assembly plants, while Baltic Sea pellet terminals anchor European solid-fuel distribution networks. Regional demand patterns diverge sharply between mature replacement markets and jurisdictions with active retrofit incentive programs.
United States
Minnesota and Wisconsin homeowners are replacing open masonry hearths with EPA-certified inserts to capture zone-heating efficiency gains. The EPA's New Source Performance Standards mandate sub-2.0 gram per hour particulate thresholds, forcing combustion redesigns. Colorado counties are offering tax credits for certified wood-burning retrofits under burn-ban jurisdictions.
Canada
CSA-certified gas fireplace engineering dominates specification flows in Ontario and Quebec as efficiency mandates tighten. Health Canada and the CSA Group maintain certification pathways that shape cross-border product eligibility with the United States. British Columbia boutique lodge developers are specifying modular built-in systems as architectural focal points with zone-heating functionality.
Germany
Condensing gas fireplace architectures are recovering latent heat from flue gases under pressure from the EU Ecodesign Directive and F-Gas Regulation. REACH chemical restrictions constrain refrigerant-based heat pump alternatives, preserving market space for direct-vent gas technologies. Bavarian manufacturers are engineering automated feed systems for pellet stove expansion.
Austria
Bulk delivery networks for densified biomass fuel are reducing operational friction for solid-fuel adopters across Alpine heating-degree-day zones. The EU Ecodesign Directive efficiency minimums are accelerating R&D investment in catalytic after-treatment systems. Upper Austrian industrial clusters are integrating automated auger-fed systems with Nordic pellet supply chains.
Italy
Northern Italian distributors are navigating Baltic Sea routing constraints that elevate inventory carrying costs for wood pellet supply. The EU F-Gas Regulation indirectly preserves market space for gas fireplace technologies achieving efficiency minimums without vapor-compression cycles. Lombardy-based fabricators are recalibrating production schedules after Nordic supply tightened.
Gas and Solid Fuels (Wood) Fireplaces Market Competitive Landscape
Global majors compete with regional champions across certification complexity and foundry integration depth. The vendor base spans vertically integrated metalcasters, modular system engineers, and hospitality-focused built-in specialists. Three archetypes dominate: Pacific Northwest foundry-integrated fabricators, CSA-certified Canadian engineering houses, and commercial lodge segment modular providers. Competitive moves concentrate on dual-certification parallelism for cross-border eligibility and captive supply of cast-iron firebox components.
Among North American fabricators, Travis Industries, Inc. exemplifies foundry-integrated production architecture, while FPI Fireplace Products International Ltd. anchors CSA-certified engineering positioning for Canadian efficiency mandates. HNI Corporation occupies the commercial lodge segment with modular built-in system specialization. These three represent distinct competitive vectors: upstream metalcasting control, regulatory certification depth, and hospitality application focus.
| Leading Market Players |
|---|
| Travis Industries, Inc. |
| FPI Fireplace Products International Ltd. |
| HNI Corporation |
| Stovax Gazco |
| Jotul Group |
| Glen Dimplex Group |
| Empire Comfort Systems Inc. |
| Kozy Heat |
| Napoleon |
| Others |
Supply & Pricing Matrix
EPA Phase II certification thresholds gate both qualified component supply and premium-tier pricing access for hearth manufacturers, compressing margins for uncertified producers while rewarding CSA-UL dual-certified engineering houses with pricing power in cross-border channels. Foundry-integrated fabricators capture margin buffers through captive cast-iron firebox production, whereas assembly-only operators face input cost volatility that erodes competitive positioning.
Pricing Analysis
Warranty and installation service bundling separates premium hearth offerings from unbundled transactional sales, with certified installers commanding 15-25% price premiums for EPA-compliant retrofit packages. Three-tier pricing structure across premium catalytic systems, standard non-catalytic inserts, and economy cordwood stoves reflects certification grade and thermal efficiency differentials. Pricing pressure stems from foundry-grade pig iron cost swings that compress margins for metal-dependent fabricators. Rural cabin owners exhibit highest price sensitivity, while boutique lodge developers prioritize architectural integration over unit economics.
Supply Chain Analysis
Direct-to-installer digital platforms and HVAC contractor channels handle professional specification demand, displacing retail showroom volumes across Minnesota, Wisconsin, and Ontario. Great Lakes foundry clusters in the United States and Canada supply cast-iron firebox components, while Nordic pellet terminals in Sweden and Finland anchor European solid-fuel distribution. Supply chains draw from Baltic Sea maritime corridors, refractory brick linings sourced from Appalachian clay deposits, and ceramic fiber insulation from German industrial clusters. Single-source vulnerability concentrates in Pacific Northwest metalcasting capacity for catalytic reactor housings. Distribution runs through regional distributor networks serving contractor channels rather than big-box retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid gas-wood dual-fuel combustion architectures are displacing single-fuel legacy systems, compressing SKU proliferation while expanding addressable use cases across heating-degree-day zones. This technology transition rewards engineering depth over brand heritage.
For Market Incumbents: Hedge fuel price volatility exposure by deepening backward integration into pellet fuel distribution networks and catalytic reactor foundry capacity. Prioritize CSA-UL dual certification investment to defend cross-border eligibility as Canadian efficiency mandates tighten. Acquire automated feed system engineering capabilities before Austrian and German competitors consolidate Alpine supply chains. For New Entrants and Emerging Players: Enter via direct-to-installer digital configurators that compress specification cycles for HVAC contractors in Colorado and Utah counties offering retrofit tax credits. Target Western US municipal incentive jurisdictions where burn-ban compliance creates qualified demand for EPA-certified wood-burning inserts. Pursue hospitality biophilic design specifications in British Columbia and Montana boutique lodge developments as the most penetrable commercial segment. For Investors and Strategic Acquirers: Baltic Sea routing constraint resolution is the leading indicator that Nordic pellet supply stability will restore European distributor margins and validate solid-fuel technology bets. Five-to-ten-year viability favors foundry-integrated mid-cap specialists with captive cast-component supply and CSA-certified engineering depth. Monitor EPA enforcement variance across high-growth western states as the signal for addressable market expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic After-Treatment R&D Investment | EPA Phase II compliance secures market access in Minnesota, Wisconsin, and Vermont retrofit channels. |
| Foundry Capacity Expansion | Captive cast-iron firebox production insulates Travis Industries from Great Lakes pig iron price volatility. |
| Dual Certification Parallelism | CSA-UL simultaneous approval compresses Ontario and Pennsylvania product launch timelines by eight to fourteen months. |
| Pellet Supply Chain Integration | Backward integration into Nordic bulk delivery networks reduces Austrian and Italian distributor inventory carrying costs. |
| Installer Digital Platform Launch | Direct-to-contractor configurators displace retail showroom purchases across Pennsylvania bundled mechanical-system proposals. |
Research Methodology
Independent corroboration across hearth equipment fabricators, HVAC contractor purchasing managers, and municipal retrofit program administrators underwrites the qualitative findings in this study. Primary interviews with foundry operations directors, catalytic reactor engineering specialists, and boutique lodge development architects combined with secondary validation from EPA New Source Performance Standards filings, CSA Group certification databases, and EU Ecodesign Directive implementation reports. Bottom-up unit shipment analysis across gas fireplace, wood-burning insert, and pellet stove categories triangulates against top-down market value reconstruction.
Comparable historical reference periods spanning pre-EPA Phase II, Phase II implementation, and post-Ecodesign Directive enforcement anchor the forecast window to observed regulatory shock effects. Segmentation modeling incorporates combustion architecture, fuel type, installation configuration, and end-user application across the projection horizon. CAGRs derive from heating-degree-day correlations, retrofit incentive program uptake curves, and foundry capacity utilization trends. Cold-climate air-source heat pump substitution rates and Baltic Sea logistics cost indices feed sensitivity scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt municipal burn-ban expansion or Nordic pellet supply disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
LPG Cylinder Manufacturing Market
Fuels
Coal Liquefaction Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Global Industrial Burner Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
CNG Dispenser Market
Fuels
Smart Gas Market
Fuels
LNG As a Fuel Market
Fuels
India Coal Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Global Wood Gas Generator Market
Fuels
No.2 Diesel Fuel Market
Fuels
China LNG Market
Fuels
Industrial Fuel Filter Market