
 Lithium-Ion Battery Wet-Process Separator Market | 2026-2036
Lithium-Ion Battery Wet-Process Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Wet-Process Separator Market Insights
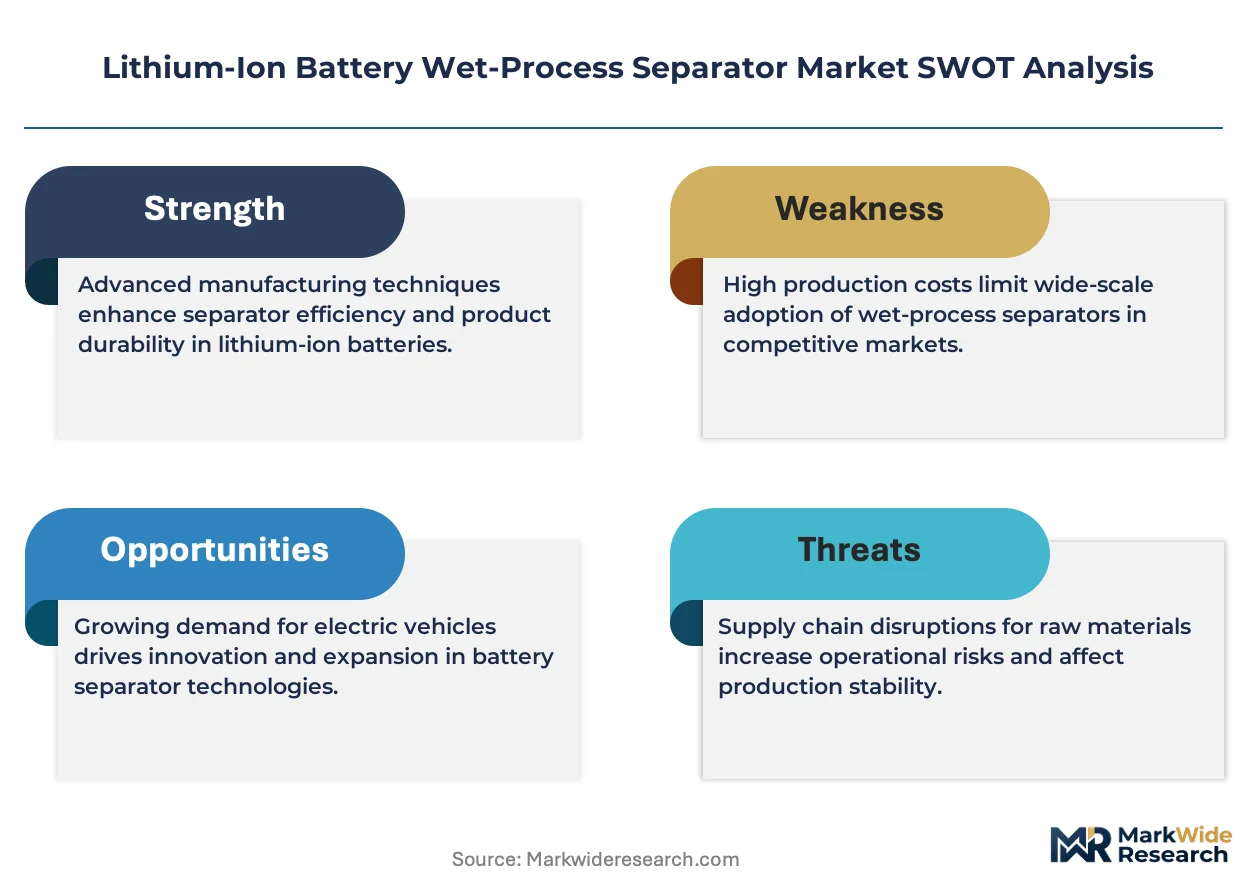
Solid-state battery development is narrowing the performance gap that wet-process separators must defend against next-generation alternatives. Asahi Kasei Corporation anchors its position through backward integration into polymer resin production. Toray Industries differentiates via ultra-thin polyethylene films engineered for high-nickel cathode chemistries. SK IE Technology dominates South Korean supply chains with automated coating lines serving domestic cell makers.
A lithium-ion battery wet-process separator is a microporous membrane, typically 7-25 micrometers thick, produced by extruding polyolefin resin with a plasticizer followed by solvent extraction to create uniform pore structures; it functions as the critical physical barrier between anode and cathode while enabling lithium-ion transport during charge and discharge cycles. Polyethylene separators sustain premium pricing in electric vehicle applications where puncture resistance and thermal shutdown properties are non-negotiable. Composite and ceramic-coated variants are capturing margin pools as automotive manufacturers specify separators capable of withstanding elevated temperatures in high-energy-density cell architectures.
China's MIIT enforces GB standards for separator mechanical strength and thermal stability, directly determining which formulations qualify for domestic battery supply contracts. The EU Green Deal and REACH chemical restrictions are reshaping material composition requirements for separators exported to European automotive manufacturers. Korea's MFDS battery safety framework mandates traceable quality systems that favor suppliers with certified automated production lines. Stakeholders must monitor which regulatory jurisdiction tightens separator specifications first, as compliance sequencing will determine competitive access to the fastest-growing cell production regions.
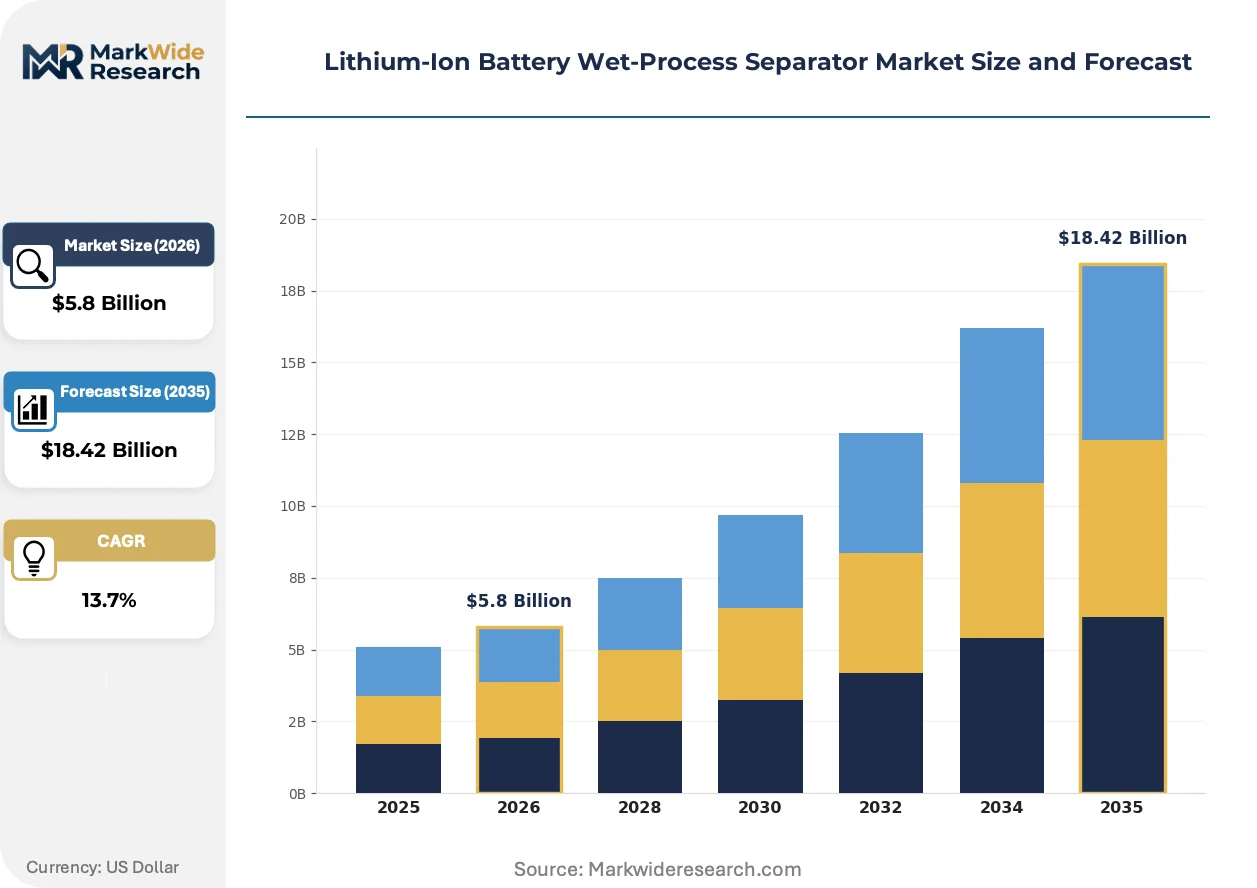
Market Dynamics
The transition toward high-nickel cathode chemistries and solid-state battery competition is compressing performance tolerances for wet-process separators, forcing material suppliers to defend thermal stability advantages while ceramic coating adoption accelerates among automotive cell manufacturers.
Growth Catalysts
- GB Standards Enforcement:China's MIIT mandates for separator mechanical strength and thermal stability are disqualifying non-compliant formulations from domestic battery supply contracts, tightening qualification barriers for market entry.
- Automotive Cell Demand:Electric vehicle manufacturers specify separators with puncture resistance above 300 grams force and shutdown temperatures below 130 degrees Celsius for high-energy-density architectures.
- Gumi Cluster Concentration:South Korea's battery production hub concentrates procurement volumes, enabling suppliers with localized coating lines to capture multi-year supply agreements from domestic cell makers.
Market Restraints
- Polyolefin Resin Volatility:Feedstock price swings for ultra-high-molecular-weight polyethylene directly compress separator margins, with producers unable to pass through full cost increases under long-term automotive contracts.
- Single-Geography Supply Risk:China's dominance in both base film extrusion and ceramic coating equipment creates vulnerability for non-Chinese cell makers seeking supply chain diversification.
- Solid-State Substitution Threat:Next-generation battery architectures utilizing solid electrolytes eliminate the physical separator function entirely, capping long-term addressable market for wet-process membranes.
Strategic Opportunities
- Poland Silesian Expansion:European battery gigafactory construction creates demand for localized separator supply, with EU Green Deal traceability requirements favoring producers establishing coating operations within the trading bloc.
- Coating Technology Convergence:Integration of artificial intelligence-driven pore structure optimization with traditional solvent extraction processes enables thinner films without sacrificing mechanical integrity.
- IRA Domestic Content Credits:The US Inflation Reduction Act's battery component sourcing rules create preferential market access for separators manufactured with qualifying critical mineral and processing thresholds.
Industry Challenges
- Electrolyte Compatibility Certification:Cell makers require 18-24 month validation cycles for new separator formulations against proprietary electrolyte chemistries, extending time-to-revenue for product innovations.
- Coater Equipment Lead Times:Automated ceramic coating line delivery schedules from specialized machinery suppliers now extend beyond 14 months, constraining capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Wet-Process Separator Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $18.42 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Composite, Ceramic Application: Electric Vehicles, Consumer Electronics, Industrial Storage, Grid Storage End User: Automotive Manufacturers, Electronics Producers, Energy Providers, Aerospace Firms Technology: Wet Coating, Dry Coating, Automated Production, Manual Production |
| Companies Covered | Asahi Kasei Corporation, Toray Industries, Sumitomo Chemical Co., Ltd., ENTEK International, Shanghai Energy New Materials Technology Co., Ltd., SK IE Technology, Ube Corporation, Sinoma Lithium Film Co., Ltd., Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Wet-Process Separator Market Trends and Innovations
Separator technology is bifurcating between ultra-thin commodity films for consumer electronics and engineered composite structures for automotive thermal management, with coating automation and quality traceability systems emerging as the primary competitive differentiators.
Artificial intelligence-driven process control is digitizing pore size distribution uniformity in solvent extraction lines, enabling real-time adjustment of plasticizer removal rates. Korean and Japanese cell makers are adopting these systems fastest, demanding sub-micron consistency certificates for high-nickel cathode pairings. The structural consequence is digitizing quality assurance from offline laboratory testing to in-line spectral monitoring, compressing rejection rates and reducing material waste.
REACH chemical restrictions are eliminating certain phthalate-based plasticizers from separator formulations exported to European automotive manufacturers. Industrial consequence includes accelerated reformulation timelines and qualification costs for suppliers serving Mercedes-Benz, BMW, and Volkswagen cell supply chains. Ceramic-coated variants utilizing alternative extractable compounds are capturing specification share in German and Hungarian battery plants.
Cell makers are consolidating separator procurement under direct long-term agreements rather than distributor-mediated spot purchases, compressing intermediary margins. Tier-one automotive battery suppliers in South Korea and China are establishing dedicated supplier development programs with technical collaboration clauses. This consolidation is most visible in the electric vehicle vertical, where single-source qualification for platform-specific cell designs locks out secondary suppliers for 5-7 year contract durations.
Lithium-Ion Battery Wet-Process Separator Market Segmentation
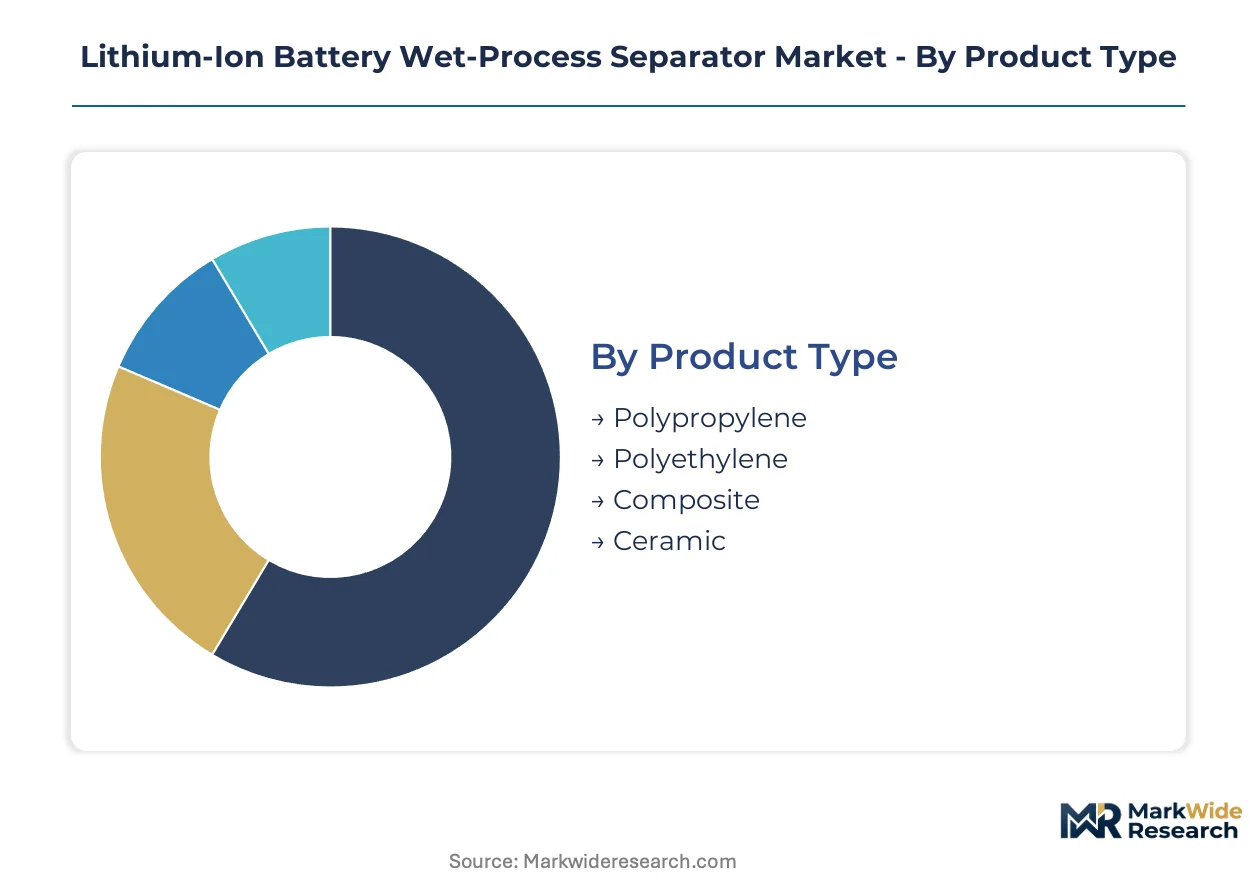
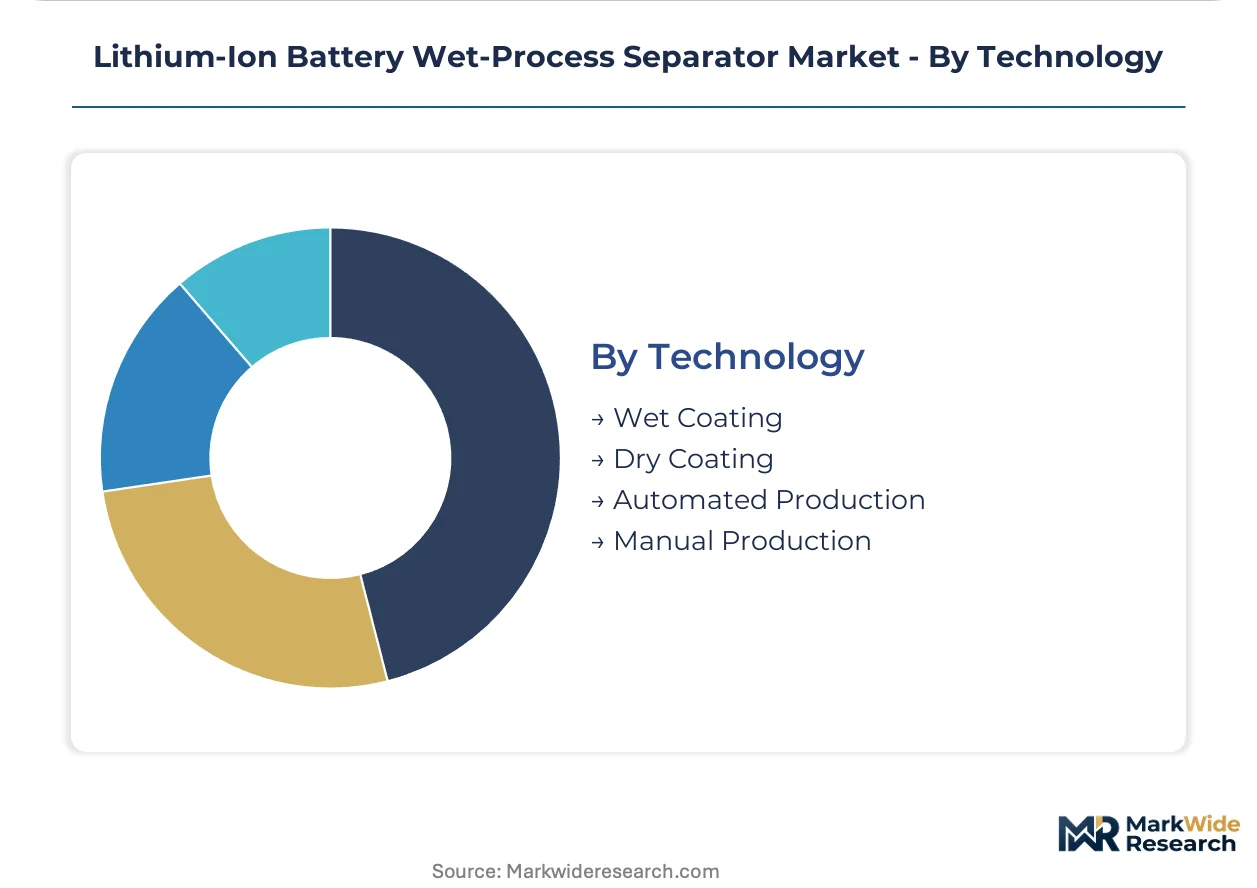
Wet-process separator procurement patterns diverge sharply across material chemistry, end-use thermal requirements, and production automation levels. Cell manufacturers specify formulations based on cathode chemistry pairing, safety certification tiers, and regional regulatory compliance obligations.
Product Type:
Cost tier stratification separates commodity base films from engineered composite structures commanding formulation premiums.
- Polyethylene:Ultra-high-molecular-weight formulations deliver puncture resistance above 300 grams force and thermal shutdown below 130 degrees Celsius. Electric vehicle manufacturers in South Korea's Gumi cluster specify polyethylene for high-nickel cathode architectures where safety margins are non-negotiable.
- Ceramic:Alumina and boehmite coatings deposited via automated lines withstand elevated temperatures in energy-dense cell designs. European automotive supply chains under REACH restrictions favor ceramic variants for traceable thermal performance in German and Hungarian battery plants.
- Polypropylene:Lower-density formulations serve consumer electronics with reduced thickness specifications and cost constraints.
- Composite:Multi-layer structures combining polyethylene substrates with ceramic surface treatments target premium automotive contracts requiring dual-property optimization.
Polyethylene holds installed capacity. Ceramic is rotating up the share rankings.
Application:
Volume concentration tracks battery gigafactory construction cycles and cathode chemistry roadmaps across mobility and stationary segments.
- Electric Vehicles:Automotive cell architectures demand 12-25 micrometer films with sub-micron pore uniformity certified for 5-7 year platform lifecycles. China's MIIT GB standards disqualify non-compliant separators from domestic battery supply contracts, tightening qualification barriers for high-volume procurement.
- Consumer Electronics:Ultra-thin 7-12 micrometer membranes prioritize energy density over thermal margins in smartphone and laptop cell designs. South Korean and Japanese electronics brands drive specification standardization through consolidated supplier development programs.
- Industrial Storage:Forklift and material handling equipment batteries favor thicker separators with extended cycle life over extreme thinness.
- Grid Storage:Utility-scale installations prioritize cost-per-kilowatt-hour optimization, accepting modest performance tradeoffs for volume pricing.
Electric Vehicles holds installed capacity. Grid Storage is rotating up the share rankings.
End User:
Customer type determines contract structure, technical collaboration depth, and qualification timeline intensity.
- Automotive Manufacturers:Direct long-term agreements with technical collaboration clauses now dominate procurement, compressing intermediary margins. Tier-one battery suppliers establish single-source qualifications locking out secondary vendors for multi-year platform durations.
- Electronics Producers:Consolidated volume purchasing through designated cell suppliers creates specification cascades from brand owners to separator makers.
- Energy Providers:Utility and independent power producer procurement emphasizes total cost of ownership over upfront unit pricing.
- Aerospace Firms:Specialized certification requirements for aviation battery systems create niche demand for highest-reliability separator grades.
Automotive Manufacturers holds installed capacity. Energy Providers is rotating up the share rankings.
Technology:
Supply concentration in coating automation and process control digitization is separating qualified suppliers from capacity-constrained competitors.
- Automated Production:AI-driven pore structure optimization integrated with solvent extraction enables real-time plasticizer removal adjustment. Korean and Japanese cell makers demand sub-micron consistency certificates, with equipment lead times from specialized machinery suppliers now exceeding 14 months.
- Wet Coating:Traditional solvent-based ceramic deposition remains dominant for high-volume automotive contracts requiring proven reliability.
- Dry Coating:Emerging solvent-free alternatives target REACH compliance for European export markets eliminating phthalate-based extractables.
- Manual Production:Limited to specialty batches, qualification samples, and research-scale volumes outside commercial automotive supply chains.
Automated Production holds installed capacity. Dry Coating is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive cell manufacturers concentrate procurement authority in four countries commanding over 80% of wet-process separator demand. Each jurisdiction enforces distinct qualification regimes that determine supplier access to gigafactory supply contracts.
China
Domestic battery producers account for the majority of global separator consumption, with CATL and BYD driving polyethylene specification standards. MIIT's GB standards for mechanical strength and thermal stability disqualify non-compliant formulations from state-backed procurement programs. The Yangtze River Delta cluster around Shanghai hosts concentrated ceramic coating capacity serving export-oriented cell makers.
South Korea
LG Energy Solution and Samsung SDI anchor demand for ultra-thin films engineered for high-nickel cathode chemistries. MFDS battery safety frameworks mandate traceable quality systems favoring suppliers with certified automated production lines. The Gumi industrial complex concentrates multi-year supply agreements between domestic cell makers and localized coating operations.
Japan
Automotive OEMs and electronics brands drive specification standardization through consolidated supplier development programs. METI industrial policy supports domestic separator makers maintaining captive resin production capabilities. The Kansai region around Osaka retains specialized coating capacity for premium consumer electronics applications.
Germany
Mercedes-Benz, BMW, and Volkswagen cell supply chains enforce REACH-compliant formulations eliminating phthalate-based plasticizers from separator exports. The EU Green Deal's traceability requirements favor producers establishing coating operations within the trading bloc. Hungarian and Polish battery plants under construction create demand for localized ceramic-coated supply.
United States
The Inflation Reduction Act's domestic content credits create preferential market access for separators meeting critical mineral and processing thresholds. Ford, GM, and Tesla cell joint ventures are qualifying suppliers against IRA battery component sourcing rules. Michigan and Tennessee gigafactory construction is pulling coating capacity decisions toward North American production bases.
Lithium-Ion Battery Wet-Process Separator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct capability tiers. The market structure concentrates around resin-integrated manufacturers, automated coating specialists, and regional fabricators serving spot demand. Strategic archetypes separate backward-integrated polymer producers from equipment-dependent coaters and formulation-focused compounders. Capacity expansion and strategic partnerships dominate competitive moves as qualification timelines stretch beyond 18 months.
Within the integrated-manufacturer tier, Asahi Kasei Corporation exemplifies resin-to-film production control, while Toray Industries occupies a position in ultra-thin polyethylene engineering. SK IE Technology represents the automated-coating archetype serving concentrated South Korean demand. These three anchors demonstrate how geographic proximity to cell production clusters determines contract capture in an industry where logistics costs and qualification cycles favor localized supply relationships.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Toray Industries |
| Sumitomo Chemical Co., Ltd. |
| ENTEK International |
| Shanghai Energy New Materials Technology Co., Ltd. |
| SK IE Technology |
| Ube Corporation |
| Sinoma Lithium Film Co., Ltd. |
| Teijin Limited |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam maritime freight corridors transmit polyolefin resin cost volatility directly into European ceramic-coated separator quotations, compressing margins for coaters lacking backward integration while amplifying price spreads between automated and manual production tiers.
Pricing Analysis
Cost-plus contracts indexed to ultra-high-molecular-weight polyethylene spot benchmarks dominate automotive procurement, with Korean cell makers layering performance-based premiums for sub-micron pore consistency certificates. Three-tier pricing structure across premium ceramic-coated, standard polyethylene, and economy polypropylene grades reflects cathode chemistry pairing and thermal shutdown certification tiers. Pricing pressure stems from automotive OEMs consolidating procurement under direct long-term agreements, squeezing intermediary margins. Grid storage buyers exhibit highest price sensitivity, accepting modest performance tradeoffs for volume pricing, while aerospace firms show least sensitivity due to specialized reliability requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Chinese base film extruders are tethering Southeast Asian coaters to resin suppliers, amplifying working capital intensity for equipment-dependent players. Geographic concentration centers on China for base film extrusion and ceramic coating equipment, South Korea for automated coating lines serving the Gumi cluster, and Japan for captive resin production. Raw material dependencies include ultra-high-molecular-weight polyethylene resin, alumina and boehmite ceramic powders, and specialized plasticizer formulations. Single-source vulnerability in coating equipment creates capacity expansion bottlenecks. Distribution runs through direct long-term agreements between tier-one cell makers and qualified separator suppliers, compressing spot market volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are opening as solid-state battery competition and regional regulatory divergence create specialized supply niches, with cathode chemistry roadmaps splintering qualification requirements across automotive platforms.
For Market Incumbents: Harden thermal stability specifications through in-house polymer resin production, mirroring Asahi Kasei's backward integration model, while accelerating ceramic coating automation to defend against dry-coating substitution threats from REACH-compliant European entrants. Lock in multi-year platform qualifications with Korean and Chinese cell makers before solid-state architectures mature, leveraging existing 18-24 month electrolyte compatibility certifications as switching-cost barriers. For New Entrants and Emerging Players: Pursue Poland Silesian coating operations to capture EU Green Deal traceability premiums, targeting German automotive supply chains eliminating phthalate-based plasticizers under REACH restrictions. Establish dry-coating pilot lines for solvent-free ceramic deposition, qualifying against Hungarian and Polish battery plant specifications as a regulatory-compliant alternative to incumbent wet processes. Partner with equipment suppliers for AI-driven pore optimization systems to compress qualification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized polymer film assets and dormant coating capacity, particularly Japanese and European players lacking automotive battery market focus. Long-term viability hinges on coating automation capabilities and regional proximity to gigafactory construction cycles rather than commodity film scale. Watch solid-state battery pilot production announcements as the critical inflection signal for wet-process separator demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Asahi Kasei's captive UHMWPE production insulates margins from feedstock volatility. |
| Automated Ceramic Coating Line Deployment | SK IE Technology's AI-driven pore optimization commands premium pricing from Korean cell makers. |
| EU Green Deal Compliance Certification | Toray's REACH-compliant formulations secure Mercedes-Benz and BMW supply chain access. |
| Dry Coating Technology Pilot | Solvent-free deposition alternatives target phthalate elimination in European export markets. |
| Poland Silesian Production Base | Localized coating operations satisfy EU traceability requirements for Hungarian battery plants. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings, combining primary discussions with separator plant managers, automotive cell procurement leads, ceramic coating equipment specialists, and polymer resin technical directors with secondary validation through MIIT GB standard documentation, MFDS battery safety framework filings, EU REACH substance restriction updates, and customs trade data for polyolefin resin flows. Bottom-up capacity modeling triangulates against top-down gigafactory construction pipelines.
Calibration against historical qualification timeline data and cathode chemistry adoption curves shapes the analytical framework across the projection horizon, with segmentation modeling spanning material chemistry tiers, application thermal requirements, end-user contract structures, and production automation levels. CAGRs derive from installed capacity expansion schedules, equipment lead time constraints, and regional regulatory enforcement sequencing. Forecast inputs incorporate solid-state battery pilot production announcements and IRA domestic content credit threshold evolution.
Macroeconomic conditions sit as an overlay; deviation in electric vehicle penetration rates, polyolefin resin pricing cycles, or battery safety regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding qualification timeline stability and coating equipment delivery schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market