
 North America Electric Vehicle Charging Equipment Market | 2026-2036
North America Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Charging Equipment Market Insights
Bi-directional charging integration is reconfiguring how grid-interactive hardware is engineered and deployed across North America. ChargePoint Holdings, Inc. leverages its software-agnostic platform to anchor multi-site fleet contracts. Tesla, Inc. sustains proprietary connector dominance through its Supercharger network density. Blink Charging Co. competes on installation speed and maintenance service bundling for commercial property managers.
Electric vehicle charging equipment encompasses electrical systems that convert grid alternating current into direct current suitable for battery storage, typically operating at voltages from 120V residential levels to 800V+ DC fast-charging architectures. These systems manage power delivery, user authentication, and thermal regulation to enable safe, rapid energy transfer for electric drivetrains. DC Fast Chargers command premium hardware margins due to high-voltage power electronics and liquid-cooled cable assemblies. Level 2 Chargers occupy the volume position across workplace and multi-unit residential deployments. Wireless Chargers remain nascent but attract R&D allocation from automakers seeking seamless parking-lane integration.
The US Federal Highway Administration, Natural Resources Canada, and state-level public utility commissions shape deployment pace through NEVI formula funding, carbon pricing mechanisms, and demand-charge restructuring for commercial hosts. EPA tailpipe standards and California Air Resources Board mandates create compliance-driven fleet electrification timelines that pull charging infrastructure investment forward. Stakeholders must monitor interconnection queue delays and evolving interoperability standards as determinants of site economics and network scalability.
Market Dynamics
The US Inflation Reduction Act's NEVI formula funding is compressing deployment timelines for DC fast-charging networks across interstate corridors. Fleet electrification mandates from California Air Resources Board are pulling forward infrastructure investment from logistics operators.
Growth Catalysts
- Federal Tax Credits:The US Inflation Reduction Act's 30% investment tax credit for charger deployment reduces payback periods for commercial hosts. Property owners in Texas and Florida are accelerating site preparation.
- Fleet Electrification Timelines:California Air Resources Board's Advanced Clean Trucks regulation mandates zero-emission vehicle sales percentages that force logistics operators to secure charging capacity. Amazon, UPS, and FedEx ground fleets are contracting multi-site installations.
- 800V Architectures:Next-generation battery platforms from Hyundai, Kia, and Porsche enable 350kW charging sessions that cut dwell times. Highway corridor operators are prioritizing liquid-cooled cable assemblies to serve these vehicles.
Market Restraints
- Interconnection Queue Delays:Utility transformer lead times extend 18-24 months in California and Ontario. Site developers face revenue loss from energized-but-idle hardware.
- Semiconductor Concentration:Silicon carbide power modules for DC fast chargers source primarily from German and Japanese foundries. Supply constraints limit manufacturing scale-up.
- Demand Charge Exposure:Commercial electricity tariffs in Texas and Illinois impose peak-demand fees that erode station economics. Hosts require battery-buffered systems that add capital intensity.
Strategic Opportunities
- Bi-directional Integration:Vehicle-to-grid protocols enable fleet operators to monetize parked assets as grid resources. California's SGIP incentive stream covers bidirectional hardware premiums.
- Multi-Unit Residential Underpenetration:Apartment and condominium dwellers in Ontario and Quebec lack overnight charging access. Property managers are bundling EV-ready parking into lease renewals.
- Wireless Charging Corridors:Dynamic inductive charging embedded in roadways addresses range anxiety for commercial routes. Michigan and Indiana are piloting highway segments with Electreon and Magment.
Industry Challenges
- Certification Bottlenecks:UL 2594 and CSA C22.2 testing timelines for new charger models extend 6-9 months. Manufacturers face launch delays for seasonal construction windows.
- Interoperability Complexity:The shift from CCS1 to NACS connectors requires firmware updates and adapter strategies. Network operators must maintain dual-protocol support through 2027.
- Skilled Technician Scarcity:High-voltage electrical work for DC fast charger installation requires licensed electricians with power electronics training. Labor pools in Arizona and Nevada are insufficient for deployment targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Charging Equipment Market |
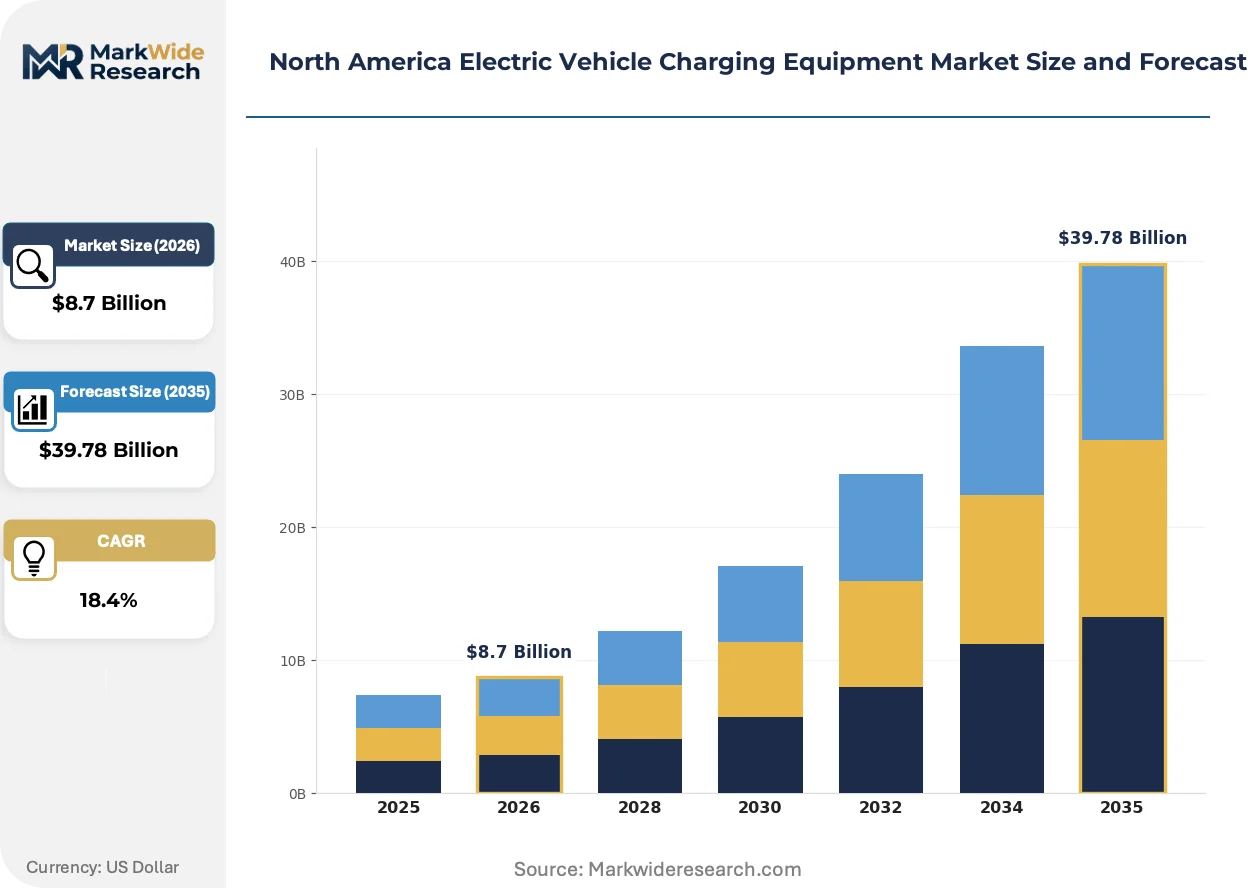
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers, Portable Chargers Technology: AC Charging, DC Charging, Inductive Charging, Conductive Charging, Solar-Powered Charging Application: Residential Use, Commercial Complexes, Public Parking, Fleet Charging Stations, Workplace Charging End User: Individual Consumers, Ride-Hailing Services, Delivery Companies, Municipal Services, Car Rental Agencies |
| Companies Covered | Blink Charging Co., ABB Ltd, ChargePoint Holdings, Inc., FLO, Leviton Manufacturing Co., Inc., EVgo Inc., Tesla, Inc., Delta, Electrify America, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Charging Equipment Market Trends and Innovations
Hardware-software decoupling is enabling new competitive entry points as charging networks compete on user experience rather than proprietary connector lock-in. Three developments are compressing incumbent advantages.
Silicon carbide power semiconductors are collapsing thermal management requirements for 350kW+ DC fast chargers. These devices switch at higher frequencies with lower losses than silicon IGBTs. Tier 1 suppliers including Delta Electronics and Infineon are shipping modules that enable air-cooled architectures previously requiring liquid cooling. The structural consequence is collapsing the cost gap between 150kW and 350kW hardware tiers.
The US Federal Highway Administration's NEVI program is mandating 97% uptime reliability and interoperable payment systems for formula-funded sites. States must withhold reimbursement for non-compliant installations. This is forcing network operators to consolidate fragmented software stacks and expose APIs for third-party roaming. Small regional networks in Montana and New Mexico are partnering with ChargePoint or Flo to meet technical requirements.
Fleet procurement is consolidating around charging-as-a-service contracts that bundle hardware, installation, energy management, and maintenance into per-mile or per-kWh rates. This displaces capital purchase models for logistics operators with thin balance sheets. The shift is most visible in California's Central Valley, where dairy and agricultural fleets are signing 10-year agreements with guaranteed uptime SLAs.
North America Electric Vehicle Charging Equipment Market Segmentation
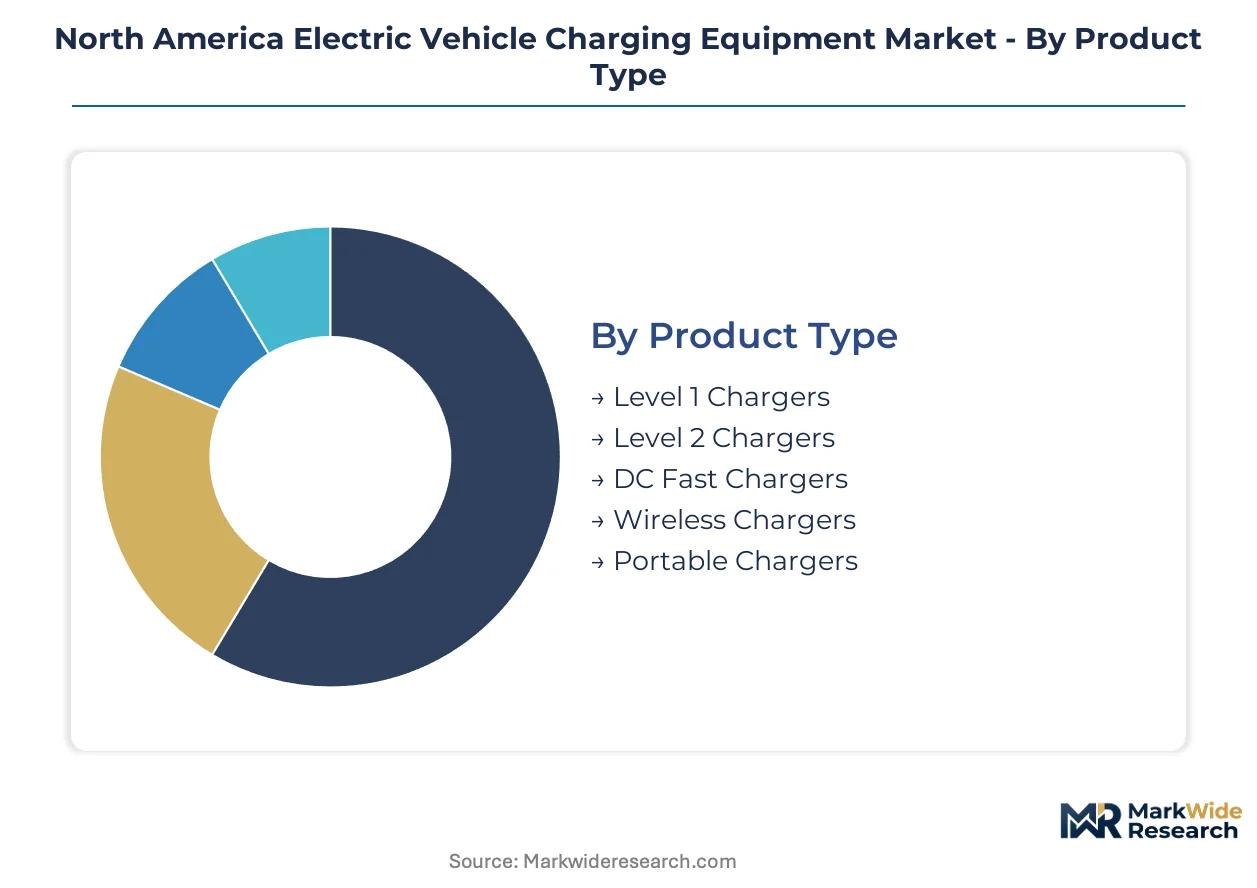
Segmentation in North American EV charging equipment reveals how hardware specifications, installation contexts, and user economics create distinct procurement patterns. Each dimension shapes capital deployment decisions differently across residential, commercial, and fleet operator budgets.
Product Type:
Residential garage installations and highway corridor deployments impose fundamentally different power delivery requirements on charging hardware.
- DC Fast Chargers:High-voltage power electronics convert grid AC to 400V-800V DC at 150kW-350kW output. California's Central Valley agricultural fleets and Texas interstate corridor operators are prioritizing liquid-cooled cable assemblies to serve 800V battery architectures from Hyundai and Kia.
- Level 2 Chargers:240V AC systems deliver 7kW-19kW through onboard vehicle rectifiers. Workplace installations in Ontario and Quebec dominate volume demand as employers bundle charging into sustainability benefits to retain talent in tight labor markets.
- Level 1 Chargers:Standard 120V residential outlets provide trickle charging for overnight dwell times.
- Wireless Chargers:Inductive pad systems enable parking-lane integration without connector wear.
- Portable Chargers:Mobile emergency units address range anxiety for rental fleet customers.
The dominant share belongs to Level 2 Chargers, while DC Fast Chargers is closing the gap fastest.
Technology:
Power conversion architectures determine thermal management costs and grid interconnection complexity across deployment sites.
- DC Charging:Off-board rectification bypasses vehicle onboard chargers to deliver direct current at highway speeds. Silicon carbide power modules from Infineon and Delta Electronics are collapsing thermal requirements, enabling air-cooled 350kW systems previously requiring liquid cooling.
- AC Charging:Alternating current delivery relies on vehicle-mounted converters, limiting speed but minimizing infrastructure capital. Multi-unit residential properties in Toronto and Montreal favor AC wallboxes for their lower electrical service upgrade costs.
- Inductive Charging:Magnetic field coupling eliminates physical connectors for automated fleet depots.
- Conductive Charging:Pantograph and overhead systems serve electric bus rapid transit corridors.
- Solar-Powered Charging:PV-to-vehicle direct coupling reduces grid dependency for off-grid commercial sites.
AC Charging retains volume leadership across workplace and residential segments, though DC Charging commands the steepest expansion trajectory as fleet electrification accelerates.
Application:
Site ownership structures and dwell-time economics fragment procurement authority across property managers, employers, and municipal authorities.
- Fleet Charging Stations:Dedicated depots for logistics and ride-hailing vehicles require 24/7 availability and guaranteed uptime SLAs. Amazon, UPS, and FedEx ground operations in California's Inland Empire are contracting 10-year charging-as-a-service agreements with hardware, installation, and maintenance bundled into per-mile rates.
- Workplace Charging:Employer-subsidized installations capture vehicles during daytime parking hours. Property owners in Austin and Dallas are accelerating site preparation ahead of Texas utility rate reforms that reduce demand-charge exposure for commercial hosts.
- Residential Use:Single-family home installations dominate overnight charging access.
- Commercial Complexes:Retail and hospitality properties use charging to extend customer dwell time.
- Public Parking:Municipal curb-side and garage installations serve transient vehicle populations.
Fleet Charging Stations captures the fastest-growing application segment, while Residential Use maintains the largest installed base.
End User:
Utilization intensity and route predictability separate high-volume commercial operators from intermittent individual consumers.
- Delivery Companies:Last-mile logistics operators face California Air Resources Board mandates requiring zero-emission vehicle sales percentages that force charging capacity commitments. Thin balance sheets are displacing capital purchase models in favor of operational expenditure structures.
- Ride-Hailing Services:Uber and Lyft driver fleets in Los Angeles and Phoenix require rapid turnaround charging between passenger pickups. High daily mileage creates utilization rates that justify premium DC fast-charging infrastructure investments.
- Individual Consumers:Homeowners and apartment dwellers with predictable overnight parking patterns.
- Municipal Services:City bus and sanitation fleets with centralized depot charging.
- Car Rental Agencies:Airport and urban location networks serving tourist and business travelers.
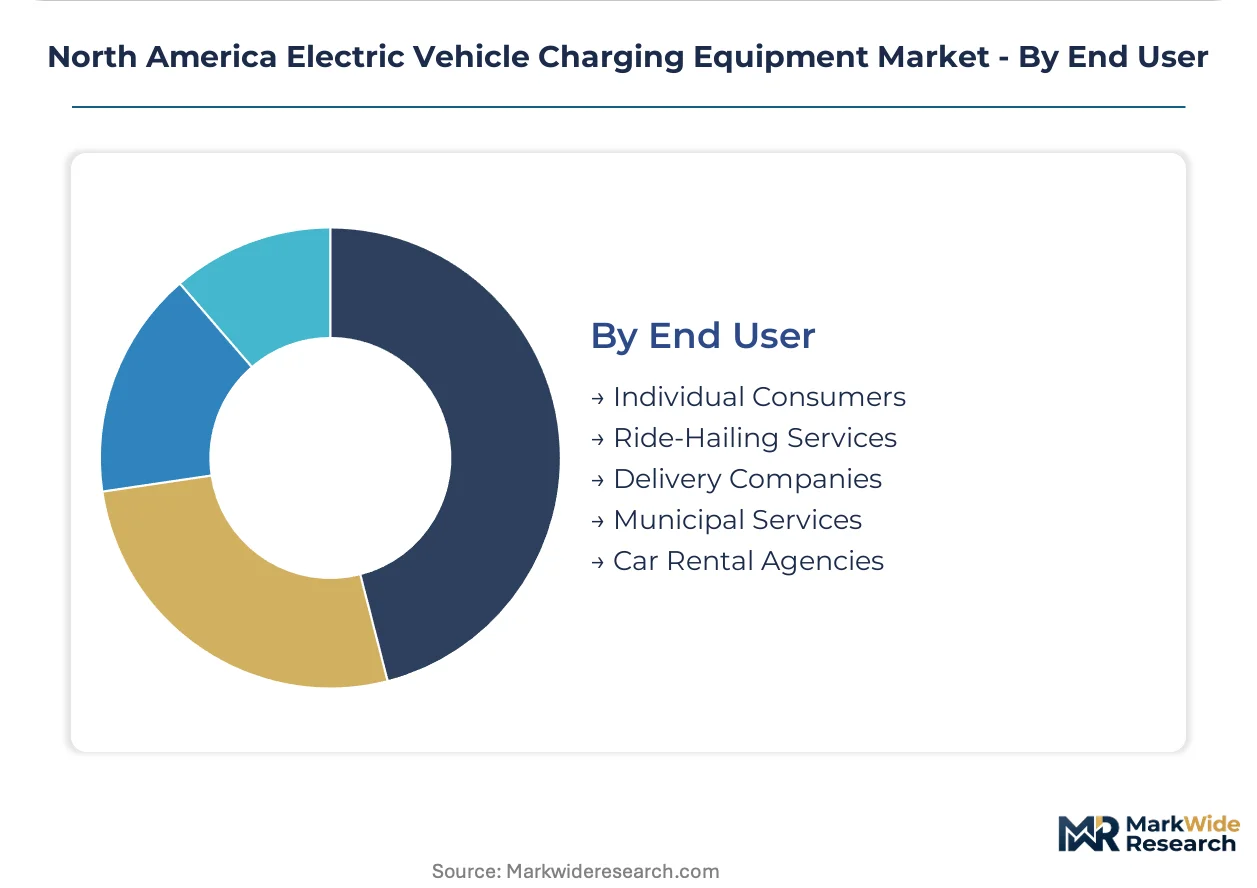
Individual Consumers represent the deepest penetration, yet Delivery Companies is gaining share fastest as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and commercial property managers concentrate procurement authority across three distinct national markets with divergent incentive structures and grid interconnection constraints.
United States
Logistics depots in California's Inland Empire and ride-hailing fleets in Phoenix drive DC fast-charging demand. The Federal Highway Administration's NEVI formula funding mandates 97% uptime reliability for interstate corridor sites. Texas utility rate reforms in Austin and Dallas are accelerating commercial host preparation ahead of demand-charge restructuring.
Canada
Multi-unit residential properties in Toronto and Montreal dominate Level 2 charger volume as landlords bundle EV-ready parking into lease renewals. Natural Resources Canada administers carbon pricing mechanisms that improve station economics for commercial hosts. Ontario's interconnection queue delays extend 18-24 months, idling energized hardware across the Golden Horseshoe.
Mexico
Manufacturing clusters in Nuevo León and Mexico City Metro attract fleet charging investment from cross-border logistics operators. The national utility regulator shapes deployment pace through grid access tariffs and commercial demand-charge structures. Bajío Region automotive assembly plants are piloting depot charging for supplier delivery routes.
North America Electric Vehicle Charging Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and network operation layers. The vendor base spans vertically integrated conglomerates, pure-play charging networks, and electrical equipment incumbents with distribution depth. Three archetypes dominate: network operators owning charging assets, hardware OEMs supplying third-party deployers, and software platforms enabling roaming interoperability. Consolidation is accelerating through strategic partnerships and technology licensing arrangements.
Within the network-operator tier, ChargePoint Holdings, Inc. and Tesla, Inc. exemplify divergent connector strategies. ChargePoint occupies a position as a software-agnostic platform anchoring multi-site fleet contracts. Tesla represents proprietary ecosystem control through Supercharger density. Blink Charging Co. sits within the installation-speed specialist archetype, bundling maintenance services for commercial property managers. These three companies collectively illustrate how hardware-software decoupling is reshaping competitive entry points.
| Leading Market Players |
|---|
| Blink Charging Co. |
| ABB Ltd |
| ChargePoint Holdings, Inc. |
| FLO |
| Leviton Manufacturing Co., Inc. |
| EVgo Inc. |
| Tesla, Inc. |
| Delta |
| Electrify America, LLC |
| Others |
Pricing and Supply Chain Analysis
I-35 corridor freight economics expose how silicon carbide module sourcing concentration in Germany and Japan feeds directly into DC fast charger price stratification across Texas and California deployment clusters. Cost-plus contracts with quarterly indexation to copper and rare earth oxide benchmarks dominate hardware procurement between Tier 1 suppliers and network operators.
Pricing Analysis
Cost-plus contracts with quarterly indexation to copper LME and neodymium oxide benchmarks dominate procurement agreements between power electronics suppliers and charging network operators. Price differentiation separates liquid-cooled 350kW systems from air-cooled 150kW tiers based on thermal management complexity and UL 2594 certification grade. Pricing pressure stems from NEVI uptime mandates forcing redundant hardware configurations at corridor sites. Fleet operators with charging-as-a-service contracts exhibit lowest price sensitivity; multi-unit residential property managers in Ontario show highest sensitivity due to capital constraint structures.
Supply Chain Analysis
Upstream feedstock for power electronics draws from German and Japanese foundries specializing in silicon carbide substrates, with copper busbar and liquid cooling loop components sourcing from Mexico and China. Raw material dependencies center on high-purity silicon carbide wafers, rare earth magnetic materials for inductive systems, and aluminum extrusions for enclosure thermal management. Single-source vulnerability concentrates in silicon carbide MOSFET supply from Wolfspeed and Infineon fabs. Distribution runs through electrical equipment distributors with certified installer networks across California, Texas, and Ontario.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American EV charging equipment functions as a service-attach market where software subscriptions and maintenance SLAs expand at multiples of hardware revenue growth. Charging-as-a-service contract structures now bundle energy management, uptime guarantees, and firmware updates into recurring revenue streams that outpace capex-driven equipment sales.
For Market Incumbents: Pre-empt NACS connector standardization disruption by accelerating firmware compatibility investments before 2027 dual-protocol maintenance burdens crystallize. Consolidate installation technician training programs in Arizona and Nevada to defend against labor scarcity threatening deployment timelines. Backward integration into power electronics assembly reduces silicon carbide module cost exposure from German and Japanese foundry concentration.
For New Entrants and Emerging Players: Multi-unit residential buildings in Quebec and Ontario represent the most penetrable entry point given landlord bundling incentives and underpenetrated overnight charging access. Agricultural fleet depots in California's Central Valley offer second white-space target with thin-balance-sheet operators seeking operational expenditure structures. Go-to-market positioning as charging-as-a-service pure-plays bypasses capital purchase friction against incumbent hardware vendors.
For Investors and Strategic Acquirers: Software-agnostic platform operators with established fleet relationships and open roaming APIs present the most defensible acquisition archetype for long-term viability across the electrification transition. Hardware-specialist vendors without network operation layers face margin compression from silicon carbide cost convergence and NEVI standardization mandates. Signal to watch is interconnection queue clearance velocity in California and Ontario as inflection indicator for deployment economics recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Bi-directional Hardware Certification | SGIP incentive capture in California requires UL 9741-SA compliance for vehicle-to-grid revenue streams. |
| Silicon Carbide Supply Agreement | Long-term offtake contracts with Infineon or Wolfspeed stabilize power module costs for 350kW system margins. |
| Installation Technician Training Program | Licensed electrician pipelines in Arizona and Nevada address labor scarcity constraining DC fast charger deployment. |
| Charging-as-a-Service Platform Launch | Per-mile billing structures displace capital purchase friction for logistics operators with thin balance sheets. |
| NEVI Compliance Software Stack | 97% uptime API exposure meets Federal Highway Administration reimbursement requirements for corridor sites. |
Research Methodology
Desk research of SEC filings from charging network operators, NEVI program disbursement records, and utility interconnection queue data preceded structured interviews with fleet electrification managers, commercial property asset directors, and electrical contractor operations leads. Primary fieldwork with DC fast charger OEM product managers and silicon carbide power electronics procurement specialists validated hardware cost structures. Secondary sources included Federal Highway Administration NEVI guidance documents, California Air Resources Board regulatory filings, and Natural Resources Canada carbon pricing mechanism reports. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment forecasts.
Assumption sets held federal tax credit percentages and NEVI funding authorization fixed across the projection horizon while varying fleet electrification mandate compliance timelines and utility rate reform adoption curves. Segmentation modeling spanned product type tiers, charging technology architectures, application contexts from residential to fleet depot, and end-user categories differentiated by utilization intensity. CAGRs derived from logistic diffusion curves fitted to historical deployment trajectories, with sensitivity analysis around silicon carbide cost decline rates and interconnection queue clearance assumptions.
Stress conditions across utility transformer lead times, semiconductor foundry utilization, and commercial electricity demand-charge restructuring were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about NEVI program continuity and state-level zero-emission mandate enforcement without federal preemption. Cross-checking against IEA EV charging infrastructure deployment benchmarks and BloombergNEF electric vehicle adoption curves is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Asia-Pacific Portable EV Charger Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
US Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Combined Charging System Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market