
 Digital Insurance Market | 2026-2036
Digital Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Insurance Market Insights
Commercial fleet operator demand for usage-based coverage is hardening as logistics firms replace annual contracts with telematics-linked policies. Guidewire Software leverages its cloud-native core platform to anchor mid-market property-casualty carriers transitioning off legacy mainframes. Salesforce competes through embedded insurance APIs that weave quoting into existing CRM workflows. Oscar Health differentiates by controlling full-stack health coverage delivery rather than distributing through traditional broker channels.
Digital insurance denotes the technology-enabled distribution, underwriting, and servicing of risk-transfer contracts through automated data pipelines, API orchestration, and real-time pricing engines that replace paper-based policy administration. Artificial Intelligence segments now command the widest margin pools as natural-language models automate claims triage and fraud pattern recognition. Cloud Computing sustains infrastructure scalability for insurers handling seasonal quote volume spikes. Blockchain occupies a narrower but growing niche in parametric smart contracts for crop and catastrophe coverage.
US state insurance commissioners, the EU's EIOPA under Solvency II, and the UK's FCA under Consumer Duty rules collectively tighten algorithmic transparency requirements that reshape product design and disclosure obligations. The SEC's climate disclosure mandates now force US-listed carriers to model and report weather-related exposure concentrations. Stakeholders must monitor how fragmented supervisory frameworks across federal and state levels will fragment compliance costs versus creating competitive moats for well-capitalized platforms.
Market Dynamics
Algorithmic underwriting is compressing policy issuance timelines from weeks to minutes, forcing carriers to rebuild core systems around real-time data pipelines or surrender mid-market share to cloud-native competitors.
Growth Catalysts
- Telematics-linked fleet policies:Commercial logistics operators in the United States now mandate GPS-verified mileage and driver behavior data as a condition of coverage placement.
- EU AI Act transparency mandates:Automated underwriting algorithms across European markets must now maintain auditable decision trails, accelerating investment in explainable AI infrastructure.
- Cloud-native core platforms:Mid-market property-casualty carriers are migrating policy administration off legacy mainframes to API-first architectures that enable embedded distribution partnerships.
Market Restraints
- Legacy system integration costs:Decades-old COBOL-based policy administration systems require multimillion-dollar transformation budgets that freeze capital allocation for smaller regional carriers.
- Fragmented state-level compliance:US insurance commissioners maintain divergent data privacy and algorithmic disclosure standards that multiply compliance overhead for multi-state operators.
- Cyber risk exposure concentration:Increasing reliance on interconnected third-party data vendors creates systemic vulnerability to single-point-of-failure breaches across distributed underwriting networks.
Strategic Opportunities
- Parametric smart contracts:Blockchain-based automatic payouts for weather-indexed crop and catastrophe coverage are penetrating agricultural markets in India and Brazil where traditional loss adjustment remains costly.
- Embedded insurance APIs:E-commerce platforms and ride-sharing applications are white-labeling coverage at point-of-transaction, bypassing traditional broker intermediation.
- SEC climate disclosure mandates:US-listed carriers must now model and report weather-related exposure concentrations, creating advisory service demand for predictive analytics vendors.
Industry Challenges
- Actuarial data science talent scarcity:Traditional underwriting functions require reskilling in Python-based machine learning pipelines, but compensation gaps with technology firms drain qualified candidates.
- Model governance complexity:Maintaining version control and bias testing across hundreds of algorithmic pricing models demands specialized MLOps infrastructure that mid-tier carriers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Insurance Market |
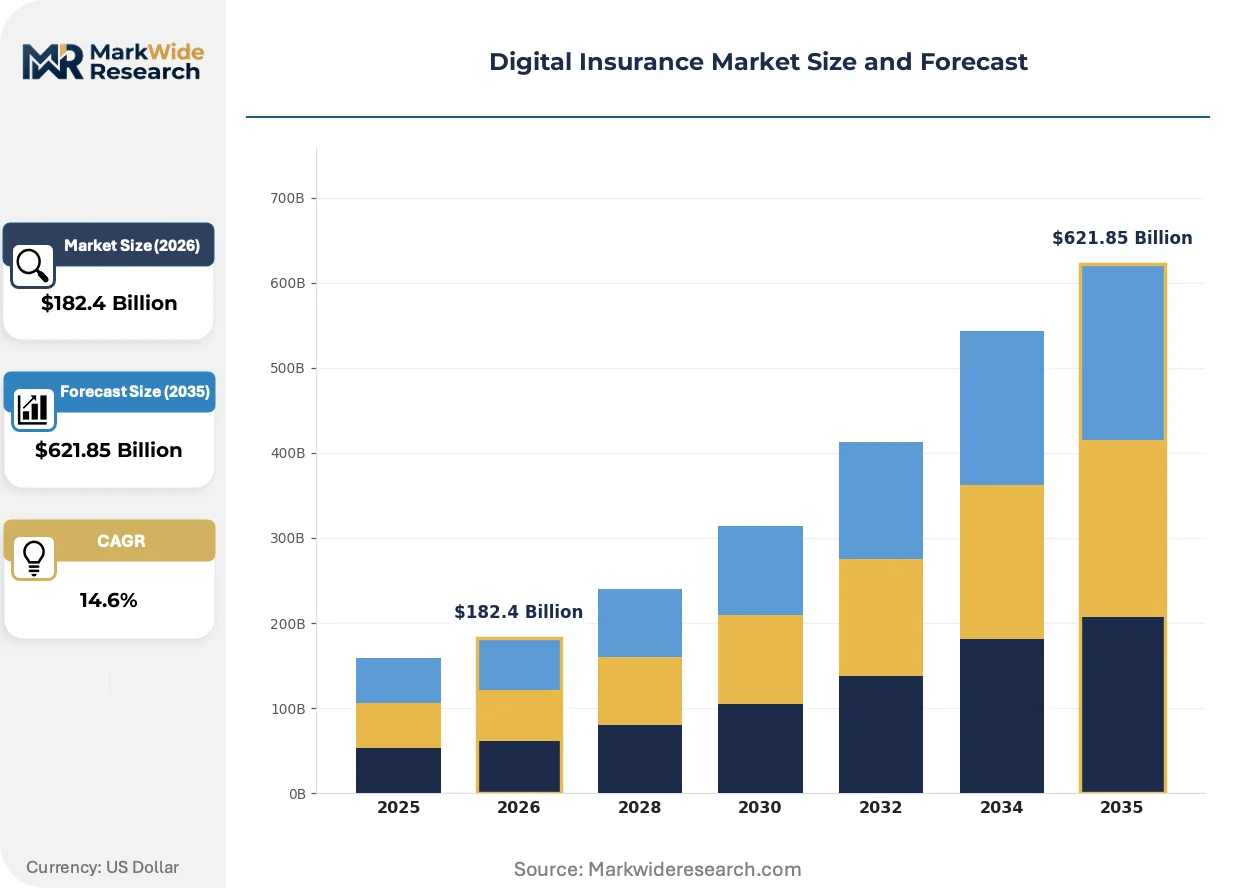
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $621.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Property Insurance, Casualty Insurance, Health Coverage, Travel Insurance, Pet Insurance Technology: Blockchain, Artificial Intelligence, Data Analytics, Cloud Computing, Internet of Things, Robotic Process Automation Application: Policy Management, Claims Processing, Customer Engagement, Risk Assessment, Fraud Detection, Underwriting Customer Type: Individual Policyholders, Small-Medium Enterprises, Corporate Clients, Independent Agents, Brokers, Insurtech Startups |
| Companies Covered | Salesforce, Microsoft, Google, Oracle, SAP, Guidewire Software, Oscar Health, Next Insurance, Root Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Insurance Market Trends and Innovations
Real-time data ingestion is collapsing the boundary between risk assessment and policy binding, enabling continuous pricing adjustments that replace static annual contracts with fluid coverage terms.
Telematics hardware combined with edge computing is modularizing auto insurance into discrete, event-triggered coverage components. Fleet operators now purchase separate modules for collision liability, cargo protection, and downtime reimbursement based on actual vehicle utilization patterns. This architecture allows logistics firms in Germany and the United States to scale coverage up or down within hours rather than policy renewal cycles.
The EU AI Act's risk classification framework is forcing carriers to restructure algorithmic decision systems across all 27 member states. High-risk underwriting applications must now maintain human-in-the-loop review protocols and algorithmic impact assessments. French and Dutch carriers are consolidating vendor relationships to ensure unified compliance across their European portfolios.
Commercial buyers are unbundling traditional broker relationships in favor of direct API connections to underwriting engines. Large manufacturing firms in Ohio and Texas now maintain direct data feeds from factory sensors to carrier pricing models, eliminating intermediary quote negotiation. This pattern is compressing sales cycles and compressing commission structures that historically sustained independent agent networks.
Digital Insurance Market Segmentation
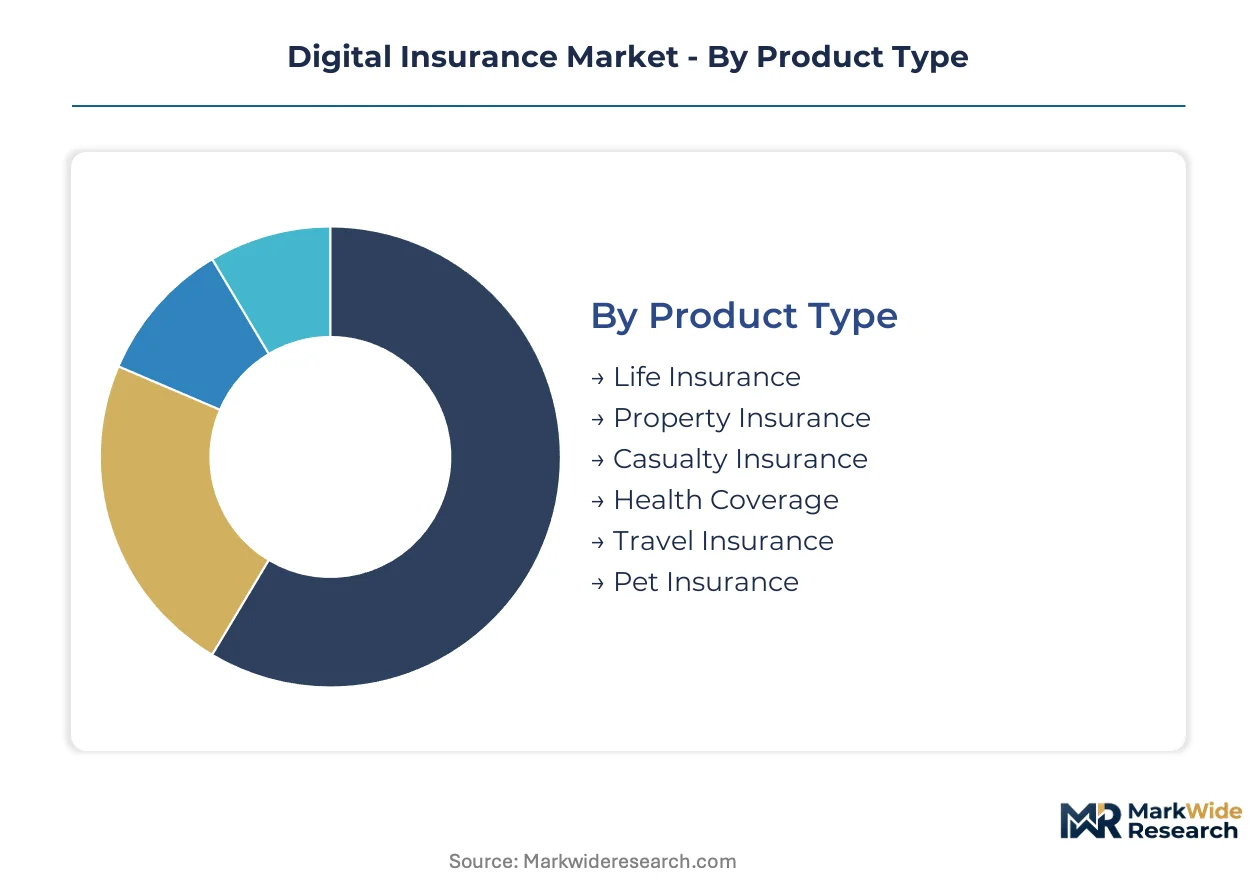
Digital insurance segmentation reveals how technology investment priorities diverge across risk categories and buyer sophistication levels. Carriers configure their platform architectures differently when serving individual policyholders versus corporate risk managers, creating distinct competitive arenas within the same market.
Product Type:
Commercial buyers prioritize coverage modules that integrate with operational data streams rather than standardized annual contracts.
- Life Insurance:Term and permanent products now embed biometric data from wearables for dynamic mortality scoring. US carriers leverage continuous health monitoring to adjust premium loads monthly rather than at policy anniversaries.
- Property Insurance:Commercial real estate policies incorporate IoT sensor networks for water leak and fire detection, shifting from indemnity to prevention-focused contracts. German industrial facilities mandate such monitoring for coverage placement.
- Casualty Insurance:Liability coverage for commercial fleets increasingly binds to telematics-verified driver behavior rather than historical loss experience.
- Health Coverage:Full-stack digital carriers control provider networks and claims processing through proprietary platforms, bypassing traditional payer intermediation.
- Travel Insurance:Embedded point-of-sale distribution through airline and booking platforms now dominates direct-to-consumer channels.
- Pet Insurance:Veterinary practice management software integrations enable real-time claims adjudication at point of treatment.
Volume sits with Property and Casualty lines; growth tilts toward Health Coverage as employer-sponsored plans migrate to digital-first administration.
Technology:
Infrastructure choices determine which carriers can support embedded distribution partnerships and real-time pricing.
- Blockchain:Smart contract architectures automate parametric payouts for weather-indexed agricultural and catastrophe coverage. Indian and Brazilian crop insurers deploy these systems where traditional loss adjustment remains prohibitively expensive.
- Artificial Intelligence:Natural language models triage first-notice-of-loss claims and flag fraud patterns across unstructured documents. EU AI Act compliance now requires auditable decision trails for high-risk underwriting applications.
- Data Analytics:Predictive models aggregate third-party behavioral and asset data to refine risk segmentation beyond traditional actuarial classes.
- Cloud Computing:API-first core platforms enable mid-market carriers to launch embedded insurance partnerships without legacy system overhaul.
- Internet of Things:Vehicle telematics and industrial sensor networks generate continuous risk signals that replace annual exposure estimates.
- Robotic Process Automation:Back-office policy administration bots handle data entry and document processing for high-volume personal lines.
Cloud Computing anchors current infrastructure spending; AI commands the steepest expansion trajectory as carriers rebuild core systems for algorithmic underwriting.
Application:
Functional priorities shift based on whether carriers target operational efficiency or revenue growth through new distribution channels.
- Policy Management:Core administration platforms migrate from on-premise mainframes to microservices architectures that support real-time rating and binding.
- Claims Processing:Automated triage routes low-complexity claims to straight-through settlement while escalating exceptions to specialized adjusters.
- Customer Engagement:Mobile-first policyholder portals and chatbot interfaces reduce call center dependency for routine service requests.
- Risk Assessment:External data ingestion pipelines combine credit, property, and behavioral signals to refine pricing granularity.
- Fraud Detection:Network analysis algorithms identify collusion patterns across claimants, providers, and repair vendors.
- Underwriting:Algorithmic decision engines compress quote turnaround from days to minutes for standard commercial risks.
Claims Processing absorbs the largest technology budgets; Underwriting platforms are expanding most quickly as carriers compete for mid-market commercial business.
Customer Type:
Channel strategy determines platform architecture requirements and data integration complexity.
- Individual Policyholders:Direct-to-consumer platforms compete on quote speed and self-service policy management. Mobile-native interfaces now dominate acquisition for personal auto and renters coverage.
- Small-Medium Enterprises:Commercial package policies require simplified data collection through pre-filled applications using public business registry and credit bureau feeds.
- Corporate Clients:Large manufacturing and logistics firms maintain direct API connections to carrier pricing engines, bypassing traditional broker intermediation for standard risks.
- Independent Agents:Legacy agency management system integrations remain essential for personal lines distribution in US suburban and rural markets.
- Brokers:Commercial intermediaries demand multi-carrier quoting platforms and policy lifecycle management tools.
- Insurtech Startups:Full-stack digital carriers require end-to-stack technology control rather than reliance on incumbent infrastructure.
Corporate Clients generate the highest premium per relationship; Insurtech Startups are gaining share fastest as venture-backed entrants capture niche segments with specialized coverage designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dubai Internet City concentrate InsurTech venture deployment, drawing cross-border capital into digital insurance infrastructure development.
United States
Enterprise brokers in Ohio and Texas digitize legacy policy administration through direct API connections to carrier pricing engines. The SEC mandates climate exposure disclosure for listed carriers, forcing predictive analytics adoption. Silicon Valley and New York City clusters host full-stack digital carriers controlling proprietary provider networks.
Germany
Industrial facilities in Bavaria mandate IoT sensor networks for property coverage placement, shifting contracts toward prevention. The EU AI Act requires auditable decision trails for algorithmic underwriting across all 27 member states. Frankfurt's financial district anchors carrier investment in explainable AI infrastructure.
United Kingdom
Commercial buyers in London bypass traditional broker intermediation for standard risks through direct data feeds. The FCA's Consumer Duty rules tighten algorithmic transparency and disclosure obligations. Lloyd's of London and the City cluster drive embedded insurance API development for e-commerce distribution.
India
Agricultural markets in Maharashtra and Karnataka deploy blockchain-based parametric smart contracts for crop coverage where traditional loss adjustment remains costly. The RBI and IRDAI regulate digital distribution channels and data localization requirements. Mumbai's financial district concentrates InsurTech startup funding for micro-insurance products.
Brazil
Telematics-linked fleet policies expand among logistics operators in São Paulo and Rio de Janeiro states. ANVISA and SUSEP oversee health and general insurance digital distribution standards. The São Paulo metropolitan area anchors regional carrier investment in cloud-native core platforms.
Digital Insurance Market Competitive Landscape
Top-tier vendors anchor cloud-native infrastructure and embedded distribution, while mid-tier specialists compete through vertical coverage designs and regional broker relationships. The market structures around three archetypes: legacy core platform modernizers, full-stack digital carriers, and enterprise software/API providers. Consolidation pressures favor carriers with captive data pipelines over those dependent on third-party vendor networks. Dominant competitive moves include strategic partnerships for embedded distribution and M&A to acquire actuarial data science capabilities.
Among enterprise software providers, Salesforce and Microsoft exemplify the API-first archetype weaving quoting into existing CRM workflows. Guidewire Software occupies a position representing legacy core platform transition specialists. Oscar Health anchors the full-stack digital carrier model controlling end-to-end health coverage delivery rather than traditional broker channels.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft |
| Oracle |
| SAP |
| Guidewire Software |
| Oscar Health |
| Next Insurance |
| Root Insurance |
| Others |
Pricing and Supply Chain Analysis
Enterprise brokers digitizing legacy policy administration in the United States concentrate procurement power and drive pricing toward subscription-based SaaS tiers with embedded usage metering. This buyer archetype's consolidation around cloud-native core platforms compresses margins for legacy system vendors while rewarding API-first architectures with volume commitments.
Pricing Analysis
Short lead-time deployment premiums of 15-30% apply to carriers requiring sub-90-day core system transitions, while spot inventory of pre-configured modules trades at discounts. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and regulatory jurisdiction coverage. Pricing pressure stems from mid-market carriers demanding modular procurement rather than monolithic enterprise licenses. Small-regional carriers exhibit highest price sensitivity due to capital constraints; large national carriers with captive IT budgets show lowest.
Supply Chain Analysis
India's data localization mandates under RBI and IRDAI directives reshape sourcing for cloud infrastructure and analytics talent pools. Technology development concentrates in the United States, India, and Germany, drawing from actuarial science labor markets, open-source machine learning frameworks, and semiconductor hardware for edge computing devices. Single-source vulnerability runs through hyperscaler cloud platforms that host carrier core systems. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital insurance market sits in a technology-transition phase where algorithmic underwriting engines displace rules-based legacy rating systems. Cloud-native core platforms are replacing COBOL-based policy administration mainframes across mid-market carriers.
For Market Incumbents: Deploy explainable AI infrastructure investments to preempt EU AI Act compliance penalties and capture European carrier modernization budgets. Consolidate vendor relationships to reduce integration complexity. Defensive moves must address full-stack digital carriers bypassing traditional broker channels through direct API connections.
For New Entrants and Emerging Players: Enter via embedded insurance APIs for e-commerce and ride-sharing platforms where incumbent carriers lack direct consumer relationships. Target agricultural parametric coverage in India and Brazil where traditional loss adjustment costs create white-space opportunity. Go-to-market should emphasize blockchain-based automatic payout architectures.
For Investors and Strategic Acquirers: The window for entry favors full-stack digital carriers with captive provider networks and proprietary claims processing platforms. Long-term viability hinges on data pipeline ownership rather than third-party vendor dependence. Watch MLOps infrastructure investments as the inflection signal for algorithmic underwriting maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | Guidewire Software anchors mid-market carriers transitioning off legacy mainframes. |
| Embedded Insurance API Partnership | Salesforce weaves quoting into CRM workflows for enterprise broker digitization. |
| Explainable AI Infrastructure Buildout | Frankfurt carriers consolidate vendor relationships for EU AI Act compliance. |
| Parametric Smart Contract Deployment | Indian crop insurers automate payouts where traditional loss adjustment remains costly. |
| Telematics-Linked Fleet Platform | German logistics operators mandate GPS-verified mileage for coverage placement. |
Research Methodology
Multi-period observation of cloud infrastructure spending, API transaction volumes, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with carrier CTOs, InsurTech founders, insurance commissioner staff, and systems integrator partners. Secondary validation drew from SEC climate disclosure filings, EIOPA algorithmic transparency guidance, IRDAI digital distribution circulars, and carrier earnings call transcripts. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Segment-weighting across technology type, customer tier, and application function determined value allocation throughout the forecast period. CAGRs derived from fitted growth curves against historical adoption rates for comparable enterprise software transitions. Industry-specific inputs included telematics device penetration curves and cloud-native core platform implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fragmented state-level compliance escalation or hyperscaler service disruption scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Global Fine Art Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
China Liability Insurance Market
Insurance
Travel Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Endowment Insurances Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
EV Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Takaful Insurance Market
Insurance
Cyber Insurance Market