
 New Zealand Property and Casualty Insurance Market | 2026-2036
New Zealand Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Property and Casualty Insurance Market Insights
The capital-intensity divergence between large incumbents and mid-tier challengers is collapsing as cloud-native core systems slash technology deployment costs. IAG New Zealand leverages its scale across home and motor portfolios to sustain pricing power in cyclone-exposed regions. Tower differentiates through digital-first distribution, while FMG Insurance anchors its position in rural and agribusiness lines where specialized risk assessment creates durable barriers.
Property and casualty insurance constitutes a contractual risk-transfer mechanism where insurers assume financial liability for specified losses in exchange for premium payments, with reserves held against claims obligations and reinsurance treaties capping catastrophic exposure. The primary commercial purpose centers on enabling capital deployment by shielding asset holders from liquidity-destroying events. Home insurance dominates premium volume across direct and broker channels, while commercial property insurance generates the thickest margin pools due to complex risk engineering requirements. Online platforms represent the fastest-expanding distribution vector, though insurance brokers retain control over corporate placements where coverage customization demands technical intermediation.
The Reserve Bank of New Zealand governs solvency standards and prudential capital requirements under the Insurance (Prudential Supervision) Act, while the Financial Markets Authority enforces conduct obligations through the Financial Markets Conduct Act. The country's national insurance regulator mandates climate-related disclosure frameworks that force insurers to embed flood and seismic risk into pricing models. Stakeholders must monitor how the RBNZ's impending capital adequacy recalibration reshapes competitive economics for regional underwriters.
Market Dynamics
Climate risk disclosure mandates under the Reserve Bank of New Zealand's prudential framework are forcing insurers to rebuild pricing models around flood and seismic exposure, compressing underwriting cycles and elevating capital requirements for regional carriers.
Growth Catalysts
- Building Act enforcement:Stricter compliance requirements in Auckland and Canterbury are compelling residential property owners to expand coverage limits, directly lifting premium volumes across home insurance lines.
- Parametric insurance platforms:Satellite-triggered payout mechanisms for agricultural and commercial property risks are reducing claims settlement friction and attracting Wellington government corridor contracts.
- Cloud-native core systems:Technology deployment cost compression is eroding the historical capital-intensity advantage of large incumbents, enabling mid-tier challengers to match operational scale.
Market Restraints
- Reinsurance cost volatility:Catastrophic exposure capping through international treaty markets exposes New Zealand underwriters to hardening global reinsurance pricing cycles.
- Seismic risk concentration:Wellington's geographic fault-line exposure creates correlated loss potential that limits diversification options for domestic carriers.
- Climate model uncertainty:Flood frequency projections carry wide confidence intervals, forcing conservative reserve allocations that compress return on equity for property-focused portfolios.
Strategic Opportunities
- South Island rural expansion:Canterbury and Otago agribusiness lines remain underpenetrated relative to North Island density, offering premium growth in specialized livestock and crop coverage.
- Embedded insurance distribution:Integration with digital mortgage platforms and property settlement services creates direct policy placement at point of asset transaction.
- Climate adaptation incentives:Resilience retrofit subsidies under national disaster preparedness programs could expand insurable asset bases through risk-quality improvement.
Industry Challenges
- Actuarial talent scarcity:Climate risk modeling specialization requires quantitative skills that outpace domestic university pipeline output, forcing recruitment from Australian and UK markets.
- Legacy system migration:Policy administration platforms built on 1990s architectures resist real-time data integration with IoT sensor networks and satellite imagery feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Property and Casualty Insurance Market |
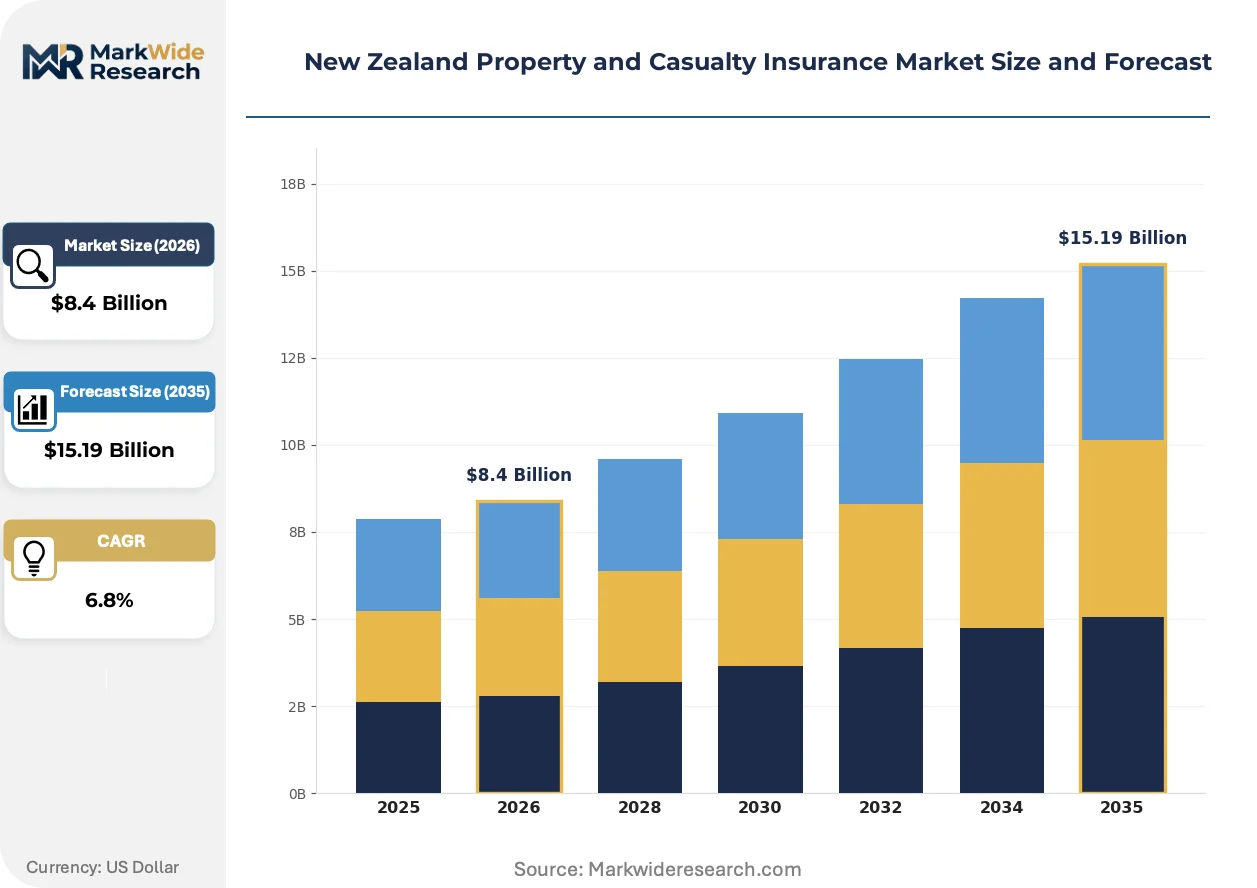
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Home Insurance, Auto Insurance, Liability Insurance, Commercial Property Insurance Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Agents Customer Type: Individuals, Small Businesses, Corporates, Non-Profit Organizations Coverage Type: Comprehensive, Third-Party Liability, Named Perils, Unspecified Risks |
| Companies Covered | IAG New Zealand, Suncorp Group (Vero Insurance NZ), Tower, FMG Insurance, AA Insurance, Zurich New Zealand, Allianz New Zealand, AIG New Zealand, QBE Insurance (NZ), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Property and Casualty Insurance Market Trends and Innovations
Digital distribution infrastructure and predictive risk analytics are converging to compress policy issuance timelines and enable dynamic pricing adjustments based on real-time environmental monitoring.
Satellite-based property monitoring combined with machine learning damage assessment is fragmenting traditional loss-adjusting workflows. Commercial property underwriters in Auckland are adopting these platforms to accelerate claims resolution. The technology is fragmenting the historical dominance of field-based adjusters in catastrophe response.
The Reserve Bank of New Zealand's climate-related disclosure framework mandates granular exposure reporting against flood and seismic scenarios. Insurers must now embed scenario analysis into capital adequacy submissions. Property portfolios in Wellington and Christchurch face the steepest compliance recalibration as regulators stress-test concentration limits.
Broker channel preference among small-to-medium commercial buyers is eroding as direct digital platforms enable self-service coverage customization. Corporate risk managers in government and finance sectors increasingly bypass intermediaries for standard property placements. This behavioral pivot is most pronounced in Wellington's central business district where procurement cycles have compressed from weeks to hours.
New Zealand Property and Casualty Insurance Market Segmentation
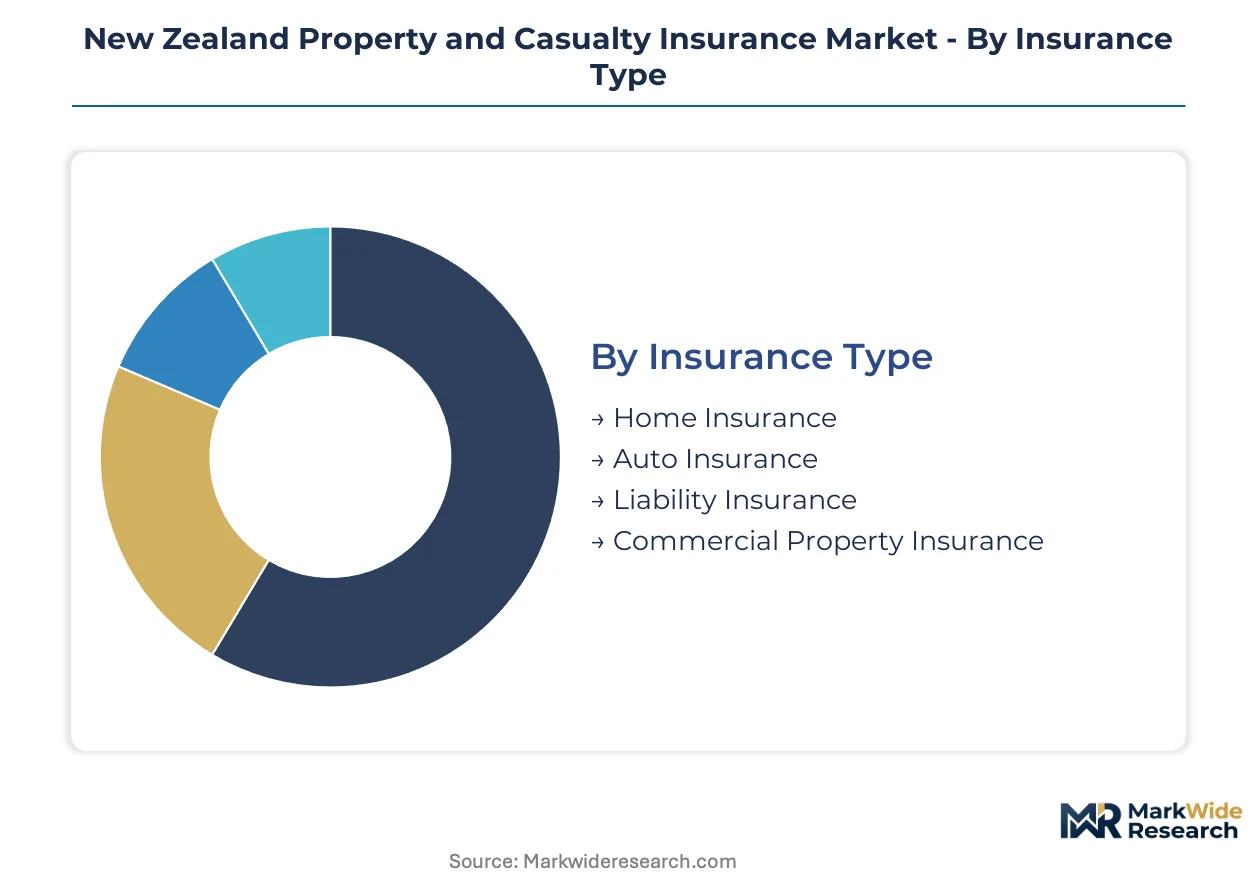
Segmentation in New Zealand's property and casualty insurance market reveals how regulatory pressure and climate risk reshape product design and channel economics. Each dimension exposes distinct capital allocation patterns and compliance burdens across underwriters.
Insurance Type:
The Reserve Bank of New Zealand's solvency standards and climate disclosure mandates create divergent capital treatment across coverage categories, with seismic and flood exposure driving reserve requirements.
- Home Insurance:Residential dwelling coverage incorporates Earthquake Commission levies and climate-adjusted premiums for flood-prone Auckland and Canterbury postcodes. Auckland and Canterbury homeowners are expanding coverage limits amid stricter Building Act enforcement, lifting premium volumes across direct and broker channels.
- Commercial Property Insurance:Complex risk engineering for Wellington government and finance corridor assets generates the thickest margin pools due to bespoke coverage terms and technical underwriting requirements. Wellington's central business district concentration creates correlated loss potential that demands reinsurance treaty layering.
- Auto Insurance:Motor vehicle coverage spans third-party liability and comprehensive damage with premium pricing tied to vehicle age, driver history, and regional theft rates.
- Liability Insurance:Professional and public liability coverage protects against legal claims arising from bodily injury or property damage to third parties.
Home Insurance handles the majority of throughput; Commercial Property Insurance is the fastest mover on share.
Distribution Channel:
Cost tier differentiation separates high-touch intermediation from automated placement, with technology deployment economics reshaping channel viability for regional underwriters.
- Insurance Brokers:Technical intermediaries retain control over corporate placements where coverage customization demands risk engineering expertise and claims advocacy. Wellington government and finance sector risk managers rely on broker networks for complex property placements despite procurement cycle compression elsewhere.
- Online Platforms:Digital-first distribution enables self-service coverage customization with policy issuance timelines compressed from weeks to hours. Tower Insurance anchors its competitive position through cloud-native core systems that slash customer acquisition costs relative to legacy-dependent rivals.
- Direct Sales:Insurer-controlled channels bypass intermediary commissions for standardized home and motor coverage with straightforward risk profiles.
- Agents:Tied representative networks provide localized service presence in rural Canterbury and Otago territories where relationship-based placement persists.
Insurance Brokers retain the largest premium flow; Online Platforms are expanding most quickly on volume contribution.
Customer Type:
Application complexity separates retail placement from commercial underwriting, with each segment demanding distinct actuarial resources and claims handling infrastructure.
- Corporates:Large enterprise accounts require dedicated risk engineering and captive insurance structuring with premium pools justifying in-house claims teams. Wellington government corridor contracts attract parametric insurance platforms that reduce settlement friction through satellite-triggered payout mechanisms.
- Small Businesses:Commercial package policies bundle property, liability, and business interruption coverage for owner-operated enterprises with limited risk management staff.
- Individuals:Standardized home and motor coverage dominates premium volume across direct and broker channels with price-sensitive switching behavior.
- Non-Profit Organizations:Specialized coverage addresses volunteer liability, event cancellation, and property protection for community service entities.
Corporates command the highest premium per account; Small Businesses are climbing the fastest on policy count expansion.
Coverage Type:
Margin structure differentiates comprehensive protection from limited peril coverage, with pricing precision varying by risk information availability and claims predictability.
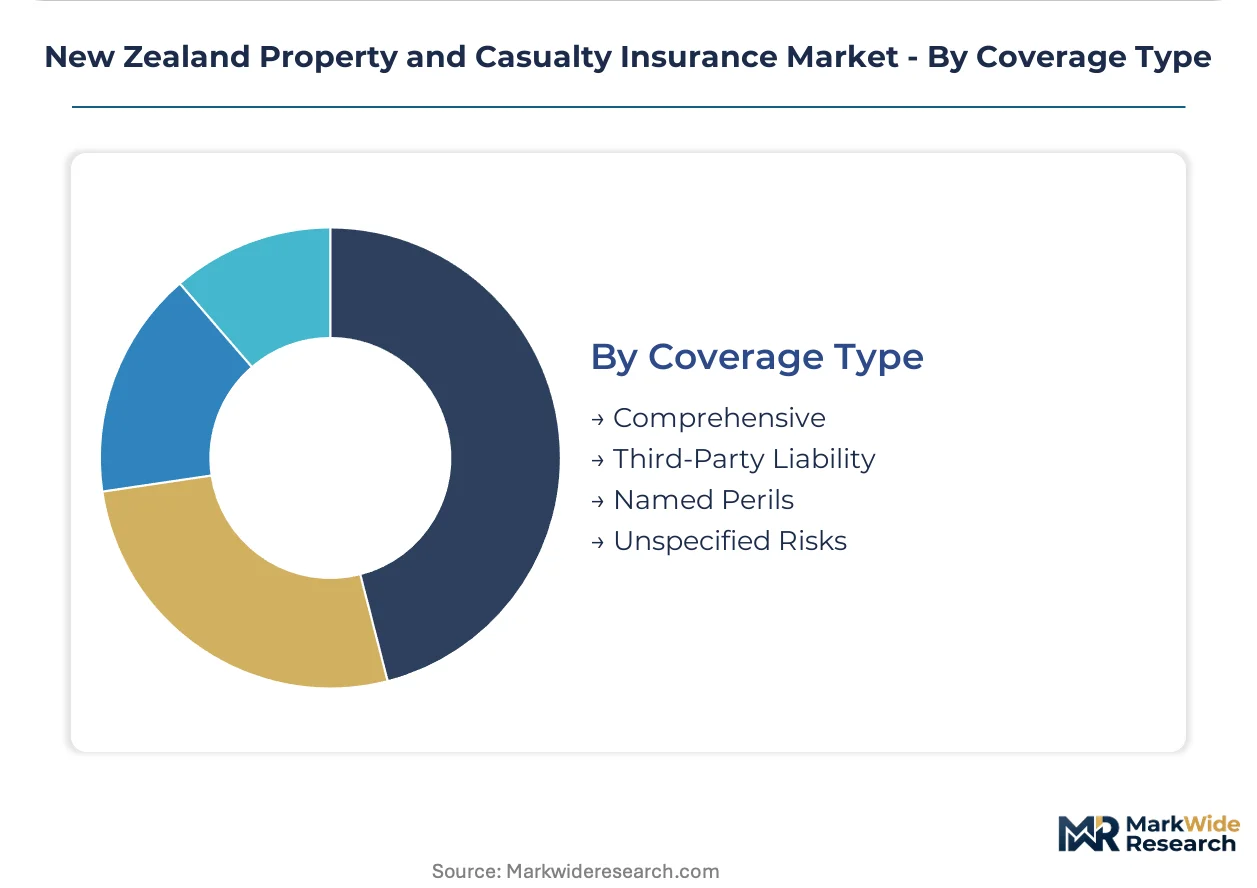
- Comprehensive:All-risk coverage except named exclusions commands premium multiples over limited alternatives, with pricing reflecting granular property characteristics and loss history. IAG New Zealand leverages scale advantages to sustain pricing power in cyclone-exposed regions where comprehensive coverage faces restricted supply.
- Third-Party Liability:Legal obligation coverage for damage to others excludes own-property protection, creating lower premium entry points for cost-constrained buyers.
- Named Perils:Explicitly listed risk coverage limits insurer exposure to specified events such as fire, theft, or flood with corresponding premium reduction.
- Unspecified Risks:Open-ended coverage terms for emerging or unclassified exposures require conservative reserve allocation and regulatory scrutiny.
Comprehensive coverage generates the thickest margin contribution; Third-Party Liability is gaining share fastest among price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's property and casualty insurance sector operates as a net importer of reinsurance capacity, with domestic underwriters ceding catastrophic exposure to international treaty markets while retaining premium flow from Auckland's dense residential corridors and Wellington's government-centric commercial property clusters.
Auckland Region
Auckland's residential property density drives the highest premium volume concentration nationally, with homeowners expanding coverage limits amid stricter Building Act enforcement. The Earthquake Commission levy structure shapes policy pricing across the region's flood-prone postcodes. Commercial property underwriters concentrate in the central business district where complex risk engineering generates the thickest margin pools.
Canterbury
Canterbury's post-earthquake reconstruction legacy continues reshaping coverage requirements, with residential owners maintaining elevated limits following seismic code upgrades. The Reserve Bank of New Zealand's climate disclosure mandates force granular exposure reporting against flood scenarios. Rural and agribusiness lines in Canterbury and Otago remain underpenetrated relative to North Island density, offering specialized livestock and crop coverage expansion.
Wellington
Wellington's government and finance corridors anchor commercial property demand, with risk managers increasingly bypassing intermediaries for standard placements through direct digital platforms. The city's geographic fault-line exposure creates correlated loss potential that demands layered reinsurance treaties. Parametric insurance platforms targeting satellite-triggered payouts attract government contracts seeking reduced settlement friction.
North Island Provincial Centers
North Island regional towns sustain relationship-based placement through tied agent networks, particularly in rural territories where FMG Insurance anchors agribusiness specialization. Climate adaptation incentives under national disaster preparedness programs could expand insurable asset bases through resilience retrofit subsidies. Digital distribution penetration lags metropolitan centers, preserving intermediary commission structures.
New Zealand Property and Casualty Insurance Market Competitive Landscape
Concentration sits with diversified national incumbents whose scale across home and motor portfolios sustains pricing power in cyclone-exposed regions. The market exhibits tiered structure with large established players, mid-tier digital challengers, and specialized rural operators. Three archetypes dominate: scale-driven generalists leveraging cloud-native core systems, digital-first distributors compressing customer acquisition costs, and niche specialists commanding agribusiness lines through technical risk assessment. Competitive moves center on technology deployment for operational parity and embedded distribution partnerships with mortgage platforms.
Among New Zealand-based underwriters, IAG New Zealand and Tower occupy positions at opposing ends of the technology spectrum, while FMG Insurance anchors the rural specialization tier. IAG New Zealand exemplifies the scale-driven archetype with diversified portfolio breadth. Tower represents digital-native challengers eroding historical capital-intensity advantages. FMG Insurance demonstrates how specialized risk assessment creates durable barriers in agribusiness lines where relationship depth outweighs price competition.
| Leading Market Players |
|---|
| IAG New Zealand |
| Suncorp Group (Vero Insurance NZ) |
| Tower |
| FMG Insurance |
| AA Insurance |
| Zurich New Zealand |
| Allianz New Zealand |
| AIG New Zealand |
| QBE Insurance (NZ) |
| Others |
Pricing and Supply Chain Analysis
Ninety-day reinsurance treaty renewal cycles anchor pricing power for domestic carriers, compressing margins when international markets harden and amplifying capital efficiency for those with diversified geographic ceding arrangements across Lloyd's of London, Bermuda, and Singapore treaty markets.
Pricing Analysis
The customization-premium spread between bespoke commercial property placements and standardized home coverage widens as Wellington government corridor contracts demand satellite-triggered parametric mechanisms while Auckland residential lines compete on price comparison platforms. Three-tier pricing structure across premium, standard, and economy levels reflects seismic zone ratings and flood frequency projections mandated by the Reserve Bank of New Zealand's climate disclosure framework. Price differentiation hinges on risk engineering depth for commercial assets versus algorithmic pricing for residential portfolios. Cost compression in direct digital channels is intensifying because cloud-native core systems slash customer acquisition expenses, eroding the historical scale advantage of legacy-dependent incumbents. Small business commercial package buyers exhibit highest price sensitivity, while corporate risk managers in government and finance sectors prioritize claims advocacy and coverage customization over premium minimization.
Supply Chain Analysis
Inbound logistics costs for claims settlement infrastructure spike when satellite imagery providers face constellation deployment delays, creating settlement friction that parametric platforms bypass through automated trigger mechanisms. Reinsurance capacity concentrates in Bermuda, London, and Singapore, with domestic New Zealand carriers ceding catastrophic exposure to international treaty markets while retaining premium flow from underwriting margins. Capital reserves draw from policyholder premiums, investment income on float, and equity injections for solvency compliance. Single-source vulnerability sits with concentrated seismic risk modeling platform providers, where actuarial talent scarcity limits domestic alternatives. Distribution runs through broker networks for complex commercial placements, direct digital platforms for standardized residential coverage, and tied agent networks for rural Canterbury and Otago territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as climate risk disclosure mandates splinter uniform pricing models, creating specialized niches for parametric innovators and rural specialists alongside scale-driven generalists.
For Market Incumbents: Fortify pricing power in cyclone-exposed regions through proprietary climate risk data accumulation, while embedding distribution partnerships with digital mortgage platforms to capture policy placement at asset transaction points. The threat of cloud-native mid-tier challengers eroding operational scale advantages demands accelerated legacy system migration to match customer acquisition cost profiles. Capacity addition in South Island rural territories offers defensive positioning against FMG Insurance's agribusiness specialization. For New Entrants and Emerging Players: Differentiate on parametric insurance architecture for agricultural and commercial property risks, where satellite-triggered payout mechanisms reduce claims settlement friction and attract Wellington government contracts. The most penetrable white space sits in Canterbury and Otago agribusiness lines, where livestock and crop coverage remains underpenetrated relative to North Island density. A digital-first go-to-market angle through embedded distribution with property settlement services bypasses established broker channel control. For Investors and Strategic Acquirers: Carve-out targets emerge from Australian parent groups seeking to divest non-core New Zealand operations, particularly mid-tier challengers with cloud-native infrastructure but subscale distribution reach. Long-term viability favors specialized rural operators with technical risk assessment capabilities that create durable barriers against price competition. The signal to watch is Reserve Bank of New Zealand capital adequacy recalibration, which would reshape competitive economics for regional underwriters and trigger consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Platform Deployment | Satellite-triggered mechanisms reduce settlement friction for Wellington government corridor contracts. |
| Cloud-Native Core Migration | Legacy system replacement matches operational scale of digital-first challengers like Tower. |
| Embedded Distribution Partnership | Integration with digital mortgage platforms captures policy placement at asset transaction points. |
| South Island Rural Expansion | Canterbury and Otago agribusiness lines offer premium growth in specialized livestock coverage. |
| Climate Adaptation Incentive Alignment | Resilience retrofit subsidies under national disaster preparedness programs expand insurable asset bases. |
Research Methodology
The analysis maps home insurance, commercial property coverage, auto insurance, and liability lines, each validated through underwriting executives, actuarial directors, broker network heads, and regulatory affairs specialists at the Reserve Bank of New Zealand and Financial Markets Authority. Primary interviews with claims operations leaders and reinsurance treaty negotiators combined with secondary validation through Insurance (Prudential Supervision) Act filings, Earthquake Commission levy data, climate disclosure submissions, and industry association statistics. Bottom-up policy count and premium volume aggregation triangulates against top-down macroeconomic and demographic projections.
Consistency checks validated model outputs against external benchmarks including regulatory capital adequacy reports and reinsurance market pricing indices. The analytical framework segments by insurance type, distribution channel, customer type, and coverage type across the projection horizon, with CAGRs derived from historical premium growth patterns adjusted for regulatory intervention scenarios and climate risk model evolution. Forecast inputs incorporate seismic frequency projections, flood zone remapping under updated building codes, and digital distribution penetration curves.
Decision-makers should treat outputs as directional under assumptions of stable reinsurance market access and incremental regulatory tightening; material deviation through catastrophic event clustering or capital adequacy shock would warrant model refresh. Forecasts reflect base-case assumptions of climate disclosure compliance timelines and technology deployment cost curves. Specific risk factors that could revise projections include hardening global reinsurance pricing, Wellington fault-line activation, or accelerated digital platform adoption compressing broker channel economics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Endowment Insurances Market
Insurance
China Liability Insurance Market
Insurance
Horse Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Extended Warranty Agreement Market
Insurance
IoT Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Crime Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
Engineering Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Global Sports Insurance Market
Insurance
India Online Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Microinsurance Market