
 Auto Compulsory Insurance Market | 2026-2036
Auto Compulsory Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Compulsory Insurance Market Insights
Multi-source data partnerships between insurers and telematics providers is restructuring how risk gets priced and underwritten in the auto compulsory insurance sector. State Farm leverages its captive agency force to sustain direct distribution dominance across North American personal auto lines. Progressive competes through proprietary usage-based pricing algorithms that anchor its market position in data-driven underwriting. Allstate controls significant brand strength in the independent agent channel, where it extends product reach through differentiated claims service capabilities.
Auto compulsory insurance constitutes a legally mandated risk-transfer mechanism that pools premiums from vehicle owners to cover third-party bodily injury and property damage liabilities arising from traffic incidents. The instrument functions through actuarial pricing models that incorporate vehicle type, driver history, geographic risk density, and real-time telematics inputs to establish premium obligations. Third-party liability coverage dominates policy type volumes across mature markets, though usage-based plans represent the fastest-growing coverage duration segment as connected vehicle data streams enable dynamic pricing. Fleet operators command disproportionate attention from commercial underwriters, where account scale and loss control programs generate concentrated margin pools. Online platforms and mobile applications now capture expanding distribution channel share, displacing traditional agent networks among digitally native customer segments.
The National Association of Insurance Commissioners coordinates state-level reserve and rate-filing standards across the United States, while the EU Motor Insurance Directive harmonizes minimum coverage floors throughout Europe. China's Banking and Insurance Regulatory Commission enforces solvency and product filing rules that shape market access for domestic and foreign underwriters. Stakeholders must monitor how telematics data ownership disputes between automakers and insurers will reshape competitive boundaries in compulsory coverage pricing.
Market Dynamics
Telematics data ownership disputes between automakers and insurers are restructuring risk assessment protocols across compulsory auto coverage markets, forcing underwriters to renegotiate data access terms and pricing model foundations.
Growth Catalysts
- EU Motor Insurance Directive mandates:Tightened minimum coverage requirements for ride-hailing fleets across Germany, France, and Spain expand addressable premium pools for commercial underwriters.
- Connected vehicle penetration:Real-time driving behavior streaming from OEM-installed sensors enables dynamic premium adjustment and loss ratio improvement.
- Fleet operator consolidation:Large-scale commercial vehicle operators in the United States concentrate purchasing power and demand sophisticated loss control programs.
Market Restraints
- Silicon chip supply volatility:Telematics device manufacturing faces input cost swings from concentrated semiconductor foundry capacity in Taiwan.
- Data access fragmentation:Automakers restrict API availability to proprietary insurance partners, creating walled gardens that limit third-party underwriting.
- Legacy system technical debt:Established insurers maintain decades-old policy administration platforms that resist real-time telematics integration.
Strategic Opportunities
- Usage-based insurance white space:Pay-per-mile products remain underdeveloped in Italy and Poland relative to saturation in the United Kingdom.
- Embedded distribution partnerships:Direct integration with automotive point-of-sale platforms at dealerships captures policyholders at vehicle acquisition.
- AI-driven claims automation:Computer vision damage assessment converges with automated liability determination to compress loss adjustment expense.
Industry Challenges
- Actuarial talent scarcity:Shortages of data scientists with both statistical modeling and insurance domain expertise constrain telematics product development.
- Cross-border regulatory complexity:Divergent data localization requirements between EU GDPR and state-level US privacy laws complicate multinational underwriting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Compulsory Insurance Market |
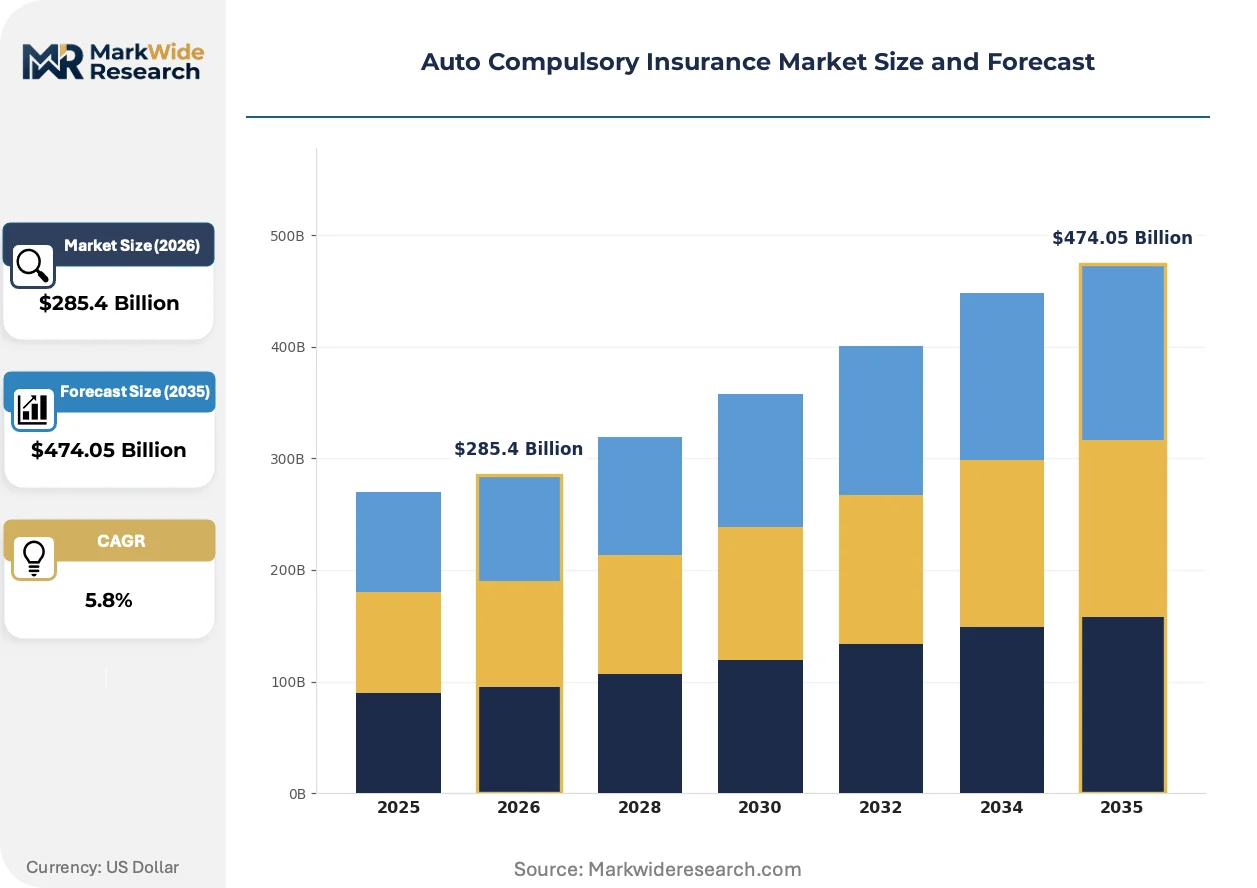
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $474.05 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Third-Party Liability, Personal Injury Protection, Property Damage, No-Fault Coverage, Comprehensive Insurance Customer Type: Individual Policyholders, Fleet Operators, Rental Agencies, Ride-Hailing Drivers, Leasing Companies Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Agent Networks, Mobile Applications Coverage Duration: Short-Term, Annual, Multi-Year, Pay-As-You-Go, Usage-Based Plans |
| Companies Covered | State Farm, Progressive, Allstate, USAA, Geico, Liberty Mutual, Farmers, Travelers, AXA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Compulsory Insurance Market Trends and Innovations
Telematics infrastructure, regulatory harmonization efforts, and distribution channel digitization are simultaneously compressing traditional underwriting cycles and expanding addressable risk pools across compulsory auto insurance markets.
Usage-based insurance platforms is converging with smartphone-based telematics to eliminate hardware installation barriers. Mid-market personal auto insurers in Germany and the United States are piloting app-only driving behavior monitoring. This convergence is compressing customer acquisition costs and accelerating policyholder onboarding velocity.
The EU Motor Insurance Directive's 2023 amendments established uniform minimum coverage floors and claims handling timelines across member states. Insurers operating in France, Italy, and Spain must now maintain harmonized reserve standards. Fleet underwriters with cross-border operations face simplified compliance but reduced rate differentiation leverage.
Digital-native buyers now expect instantaneous quote-to-bind completion through mobile interfaces. Traditional agency networks in the United States and United Kingdom are losing share to direct-to-consumer platforms and embedded dealership partnerships. This channel rotation is most pronounced among first-time vehicle purchasers aged 25-35 in urban centers.
Auto Compulsory Insurance Market Segmentation
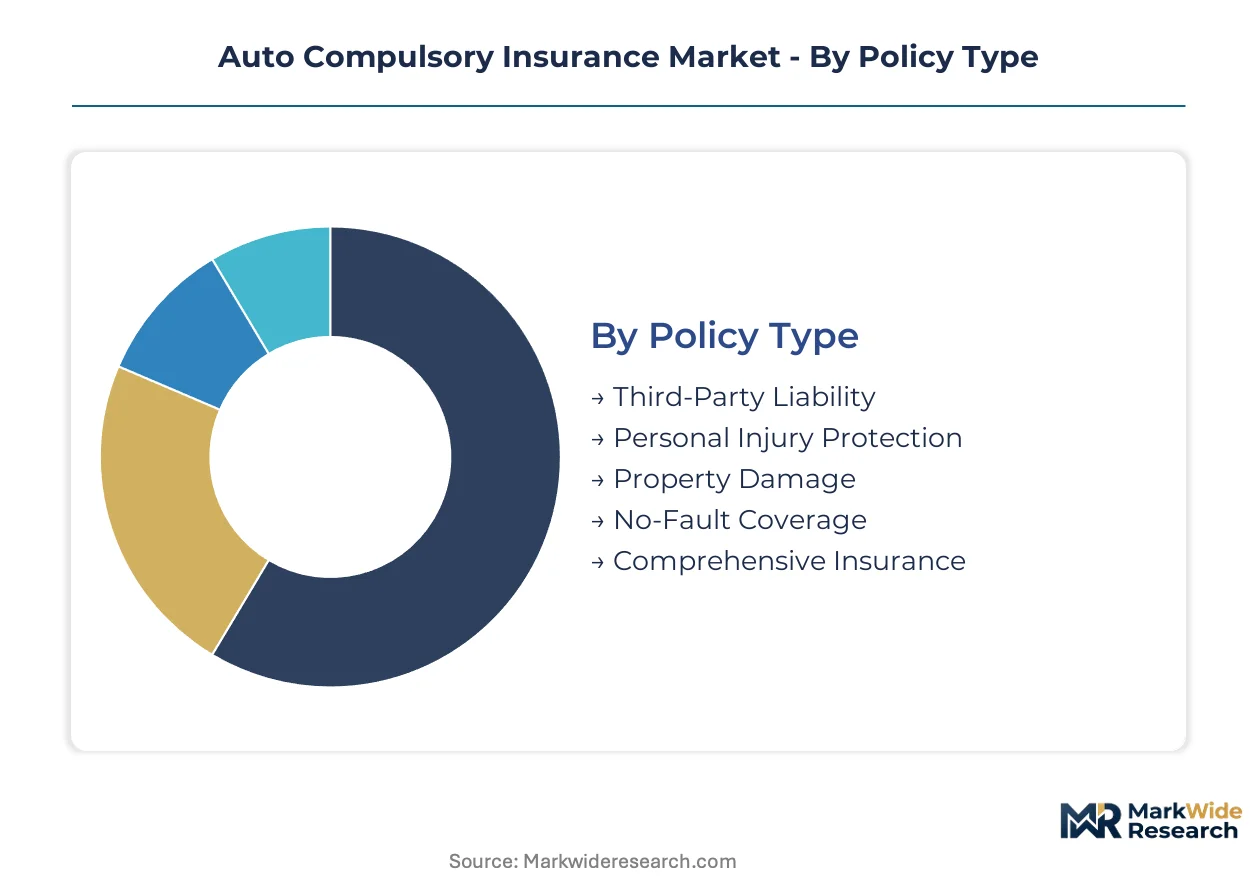
Segmentation in auto compulsory insurance reveals how regulatory mandates, vehicle ownership patterns, and distribution technology reshape premium pools. Underwriters calibrate product design and channel investment around distinct risk profiles and purchasing behaviors.
Policy Type:
Upgrade cycles in policy type reflect shifting liability exposures and regulatory floor adjustments across jurisdictions.
- Third-Party Liability:Statutorily mandated coverage protecting against bodily injury and property damage claims from third parties. Demand concentrates in Germany and France where EU Motor Insurance Directive mandates drive fleet operator compliance.
- Personal Injury Protection:First-party medical coverage regardless of fault, prevalent in no-fault jurisdictions. Florida and Michigan policyholders generate concentrated volume where state statutes require this layer.
- Property Damage:Coverage for physical damage to third-party vehicles and structures. Standard inclusion in minimum coverage packages across all regulated markets.
- No-Fault Coverage:Streamlined claims processing through restricted litigation rights. Pennsylvania and New York maintain significant policyholder bases under state no-fault frameworks.
- Comprehensive Insurance:Protection against theft, fire, and non-collision damage. Optional in compulsory markets but bundled frequently in premium tiers.
Third-Party Liability sits at the top of the volume ranking, with Usage-Based Plans climbing the fastest across personal auto segments.
Customer Type:
Customer concentration patterns track commercial vehicle utilization intensity and regulatory scrutiny depth.
- Individual Policyholders:Private vehicle owners purchasing standard annual coverage. Urban centers in Spain and Italy show accelerating digital channel migration among this base.
- Fleet Operators:Commercial vehicle pools with centralized risk management programs. German logistics companies command premium attention from underwriters offering loss control services.
- Rental Agencies:Short-term vehicle lessors requiring blanket coverage structures. Airport-based operations in France and the United Kingdom drive specialized product demand.
- Ride-Hailing Drivers:Platform-based commercial operators with hybrid personal-commercial exposure. EU regulatory tightening on minimum coverage creates expanding addressable premium pools.
- Leasing Companies:Long-term asset financiers bundling insurance with vehicle contracts. Embedded distribution partnerships with dealerships capture this segment at point-of-sale.
Fleet Operators generate the deepest premium per account, while Ride-Hailing Drivers expand most quickly under regulatory pressure.
Distribution Channel:
Channel economics diverge sharply between legacy agent infrastructure and digitally native acquisition platforms.
- Direct Sales:Insurer-controlled channels including call centers and proprietary websites. Progressive and State Field deploy captive forces sustaining dominant positions.
- Insurance Brokers:Independent intermediaries comparing multiple carrier offerings. Commercial accounts in the United Kingdom rely heavily on broker expertise for complex placements.
- Online Platforms:Aggregator websites enabling multi-quote comparison. German price comparison portals capture significant share among digitally fluent demographics.
- Agent Networks:Tied or multi-tied representatives with local market knowledge. Allstate extends reach through differentiated claims service in independent agent channels.
- Mobile Applications:Smartphone-native quote-to-bind experiences. Italian and Polish markets show underdeveloped penetration relative to United Kingdom saturation.
Agent Networks retain the largest policy count, though Mobile Applications gain share fastest among first-time purchasers aged 25-35.
Coverage Duration:
Duration selection reflects vehicle utilization variability and telematics infrastructure maturity.
- Short-Term:Temporary coverage for seasonal or transitional vehicle use. Rental agency partnerships and ride-hailing platform onboarding generate episodic demand.
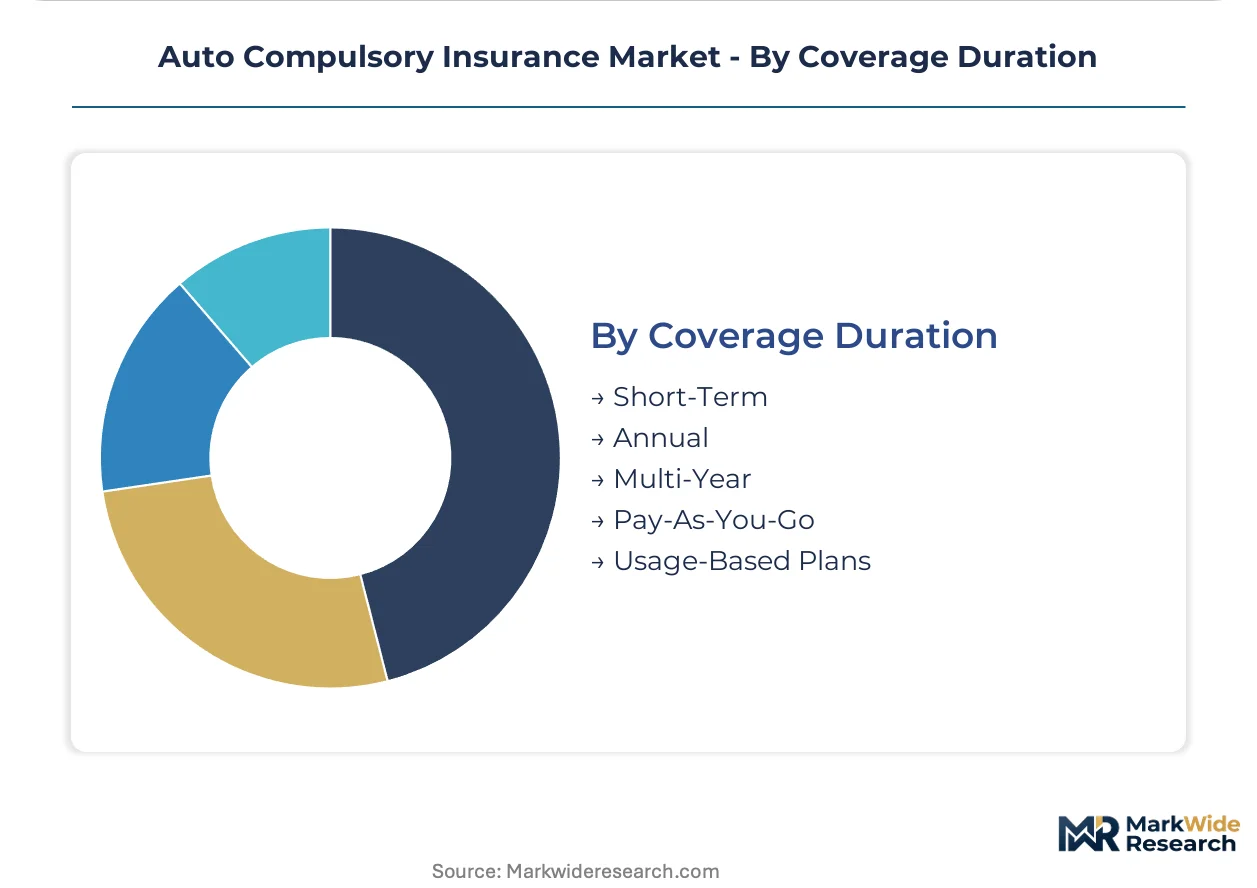
- Annual:Standard twelve-month policy terms with fixed premiums. Remains the default structure across mature compulsory insurance markets.
- Multi-Year:Extended terms locking premium rates across multiple periods. Fleet operators with stable vehicle counts favor this structure for budget certainty.
- Pay-As-You-Go:Mileage-linked premium calculation without behavioral monitoring. Appeals to low-mileage commuters in urban Germany and the Netherlands.
- Usage-Based Plans:Dynamic pricing incorporating real-time driving behavior via telematics. Connected vehicle penetration enables expansion beyond United Kingdom saturation into Italy and Poland.
Annual coverage dominates policy volumes, with Usage-Based Plans showing the steepest expansion trajectory as OEM sensor integration spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshuffling premium flows as fleet operators migrate coverage procurement toward jurisdictions with harmonized compliance costs. Germany's tightened liability thresholds and the EU Motor Insurance Directive's unified mandates create compliance gravity that pulls underwriting capacity toward centralized European markets.
United States
State-level rate-filing autonomy under NAIC coordination generates pricing heterogeneity that rewards data-rich underwriters. Florida and Michigan no-fault statutes sustain concentrated personal injury protection volumes. Texas and California metropolitan corridors anchor telematics-enabled usage-based expansion among digitally native demographics.
Germany
Fleet operator consolidation in logistics and ride-hailing segments drives demand for sophisticated loss control programs. KBA enforcement of commercial auto liability thresholds compels coverage upgrades across commercial vehicle pools. The Rhine-Ruhr industrial corridor concentrates underwriting expertise and claims service infrastructure.
United Kingdom
Price comparison portal saturation has compressed acquisition costs to European lows while accelerating mobile-native policyholder onboarding. FCA conduct rules govern claims handling timelines and reserve adequacy. London's Lloyd's syndicates and Edinburgh's regional underwriter clusters compete for commercial fleet accounts.
France
ANSM and CNIL oversight of health data in telematics streams creates compliance complexity for behavior-based pricing models. The EU Motor Insurance Directive's 2023 amendments simplified cross-border fleet coverage but reduced rate differentiation leverage. Lyon and Marseille logistics hubs generate concentrated commercial auto premium pools.
China
CBIRC solvency requirements and product filing rules shape market access for domestic underwriters competing with foreign joint ventures. Connected vehicle penetration from domestic OEMs enables real-time telematics integration at scale. The Yangtze River Delta manufacturing corridor concentrates fleet operator risk management demand.
Auto Compulsory Insurance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded distribution partnerships and AI-driven claims automation. The market structure consolidates around three archetypes: captive agency networks with proprietary distribution control, direct-to-consumer platforms with algorithmic pricing, and independent agent channel specialists with differentiated service capabilities. Dominant competitive moves include telematics data partnerships with automakers and vertical integration into embedded point-of-sale coverage at vehicle acquisition.
Among North American personal auto specialists, State Farm, Progressive, and Allstate anchor distinct competitive positions. State Farm exemplifies the captive agency archetype with exclusive distribution control. Progressive represents algorithmic pricing leadership through proprietary usage-based models. Allstate occupies the independent agent channel tier with claims service differentiation. These three structures illustrate how distribution economics and data access stratify competitive boundaries in compulsory coverage markets.
| Leading Market Players |
|---|
| State Farm |
| Progressive |
| Allstate |
| USAA |
| Geico |
| Liberty Mutual |
| Farmers |
| Travelers |
| AXA |
| Others |
Pricing and Supply Chain Analysis
Telematics platform migration from hardware-dependent to smartphone-native architectures is compressing both customer acquisition costs and supplier concentration across the auto compulsory insurance value chain. This shift simultaneously reduces OEM sensor dependency for pricing models while fragmenting device manufacturing leverage toward software development clusters.
Pricing Analysis
Direct-to-consumer channel margins dominate premium economics in personal auto lines, while captive agency networks extract higher per-policy revenue through bundled service fees. Pricing stratifies across premium, standard, and economy tiers based on telematics data granularity and claims service bundling. Cost compression in the standard tier is intensifying because smartphone-based monitoring eliminates hardware installation overhead. Individual policyholders aged 25-35 show highest price sensitivity, whereas fleet operators prioritize loss control program sophistication over premium minimization.
Supply Chain Analysis
EU Motor Insurance Directive harmonization and GDPR data localization mandates are reshaping telematics provider sourcing toward European software development centers. Semiconductor fabrication draws from Taiwan, South Korea, and Germany for telematics device components. Legacy policy administration system dependencies create single-source vulnerability for established insurers modernizing real-time data integration. Distribution runs through embedded dealership partnerships, direct digital platforms, and traditional agent networks in varying regional combinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory tightening on ride-hailing coverage minimums creates premium pool expansion unavailable in less prescriptive jurisdictions.
For Market Incumbents: Hedge telematics data access erosion by securing exclusive OEM partnership terms before automaker walled gardens solidify. State Farm and Progressive archetypes should deepen backward integration into proprietary sensor data streams. Captive agency networks must accelerate digital onboarding velocity to match direct-channel customer acquisition economics. For New Entrants and Emerging Players: Capture usage-based insurance white space in Italy and Poland where smartphone-native telematics penetration lags United Kingdom saturation. The most penetrable segment combines first-time vehicle purchasers with embedded dealership distribution at point-of-sale. Go-to-market positioning should emphasize instantaneous quote-to-bind completion through mobile-first interfaces. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional underwriters lacking telematics data partnerships or embedded distribution capabilities. Long-term viability across the analysis window hinges on securing automaker data access agreements before competitive moats harden. Monitor EU Motor Insurance Directive enforcement intensity as the primary inflection indicator for commercial auto premium pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | Exclusive OEM agreements with Volkswagen or BMW secure proprietary risk assessment inputs. |
| Embedded Distribution Integration | Direct point-of-sale partnerships with dealership networks capture policyholders at vehicle acquisition. |
| AI Claims Automation | Computer vision damage assessment compresses loss adjustment expense for Progressive-type underwriters. |
| Usage-Based Product Launch | Pay-per-mile offerings in underpenetrated Italian and Polish markets accelerate premium growth. |
| Regulatory Compliance Scale-Up | Harmonized EU Motor Insurance Directive reserve standards simplify cross-border fleet underwriting. |
Research Methodology
Bottom-up policyholder segmentation modeling reconciled against top-down premium pool tracking forms the analytical core. Primary interviews with auto insurance product managers, telematics platform engineers, fleet risk management directors, and EU regulatory affairs specialists combined with secondary validation from NAIC rate filings, EU Motor Insurance Directive amendments, CBIRC solvency disclosures, and vehicle registration databases. Triangulation between distribution channel economics and connected vehicle penetration rates calibrated market sizing.
Historical trendline analysis of premium growth, loss ratio evolution, and telematics adoption velocity informed projection frameworks. Segmentation dimensions modeled include policy type, customer archetype, distribution channel, and coverage duration across the projection horizon. CAGRs derived from regression analysis against regulatory mandate implementation schedules and OEM sensor integration roadmaps. Forecast inputs incorporated EU Motor Insurance Directive enforcement timelines and smartphone telematics platform deployment curves.
Regulatory mandate delays, automaker data access restriction escalation, and actuarial talent scarcity are the dominant revision risks. Forecasts reflect assumptions around telematics infrastructure maturation and channel migration velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United Kingdom Parametric Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Digital Innovation in Insurance Market
Insurance
Global Boats and Yacht Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Earthquake Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
IoT Insurance Market
Insurance
Property and Casualty Insurance Market
Insurance
Travel Insurance Market
Insurance
Embedded Insurance Market
Insurance
Bancassurance Market
Insurance
GCC Bancassurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market