
 North America Internet of Things Devices Market | 2026-2036
North America Internet of Things Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Internet of Things Devices Market Analytics
Edge-native computing architectures is reconfiguring how IoT devices process data locally rather than routing everything through centralized cloud infrastructure. Amazon leverages its AWS IoT Greengrass platform to anchor edge workloads for enterprise customers requiring low-latency inference. Cisco Systems dominates industrial networking layers with hardened switches and gateways purpose-built for factory-floor deployments. Qualcomm Technologies specializes in cellular modem integration, sustaining its position as the preferred silicon supplier for asset-tracking modules requiring wide-area connectivity.
North America Internet of Things Devices encompass networked physical objects embedded with sensors, actuators, and microcontrollers that transmit data over protocols such as Bluetooth Low Energy with sub-50 mW power draw or LTE-M with extended discontinuous reception cycles up to 2.56 seconds. These devices serve commercial and industrial purposes including predictive maintenance, environmental monitoring, and automated inventory reconciliation. Wearables and home automation product categories currently occupy the largest revenue pools, while industrial sensors command premium pricing due to IP67 ingress protection and hazardous-location certification requirements. Cellular technology segments are expanding fastest as private 5G networks enable deterministic latency for smart city traffic management and precision agriculture drone coordination.
The FCC governs radio-frequency spectrum assignments for unlicensed IoT operation in the 902-928 MHz and 2.4 GHz bands, while NIST publishes cybersecurity frameworks that shape procurement requirements for federal IoT deployments. Health Canada and the FDA jointly influence connected medical device standards through harmonized software-as-a-medical-device guidance, creating compliance complexity for cross-border healthcare monitoring shipments. Stakeholders must monitor evolving NIST post-quantum cryptography standards, as algorithm transitions will force hardware refresh cycles across installed utility and government sensor networks.
Market Dynamics
Edge-native computing architectures are compressing latency requirements for IoT deployments, forcing hardware vendors to integrate local inference capabilities directly into sensor modules rather than relying on cloud round-trips for real-time decision-making.
Growth Catalysts
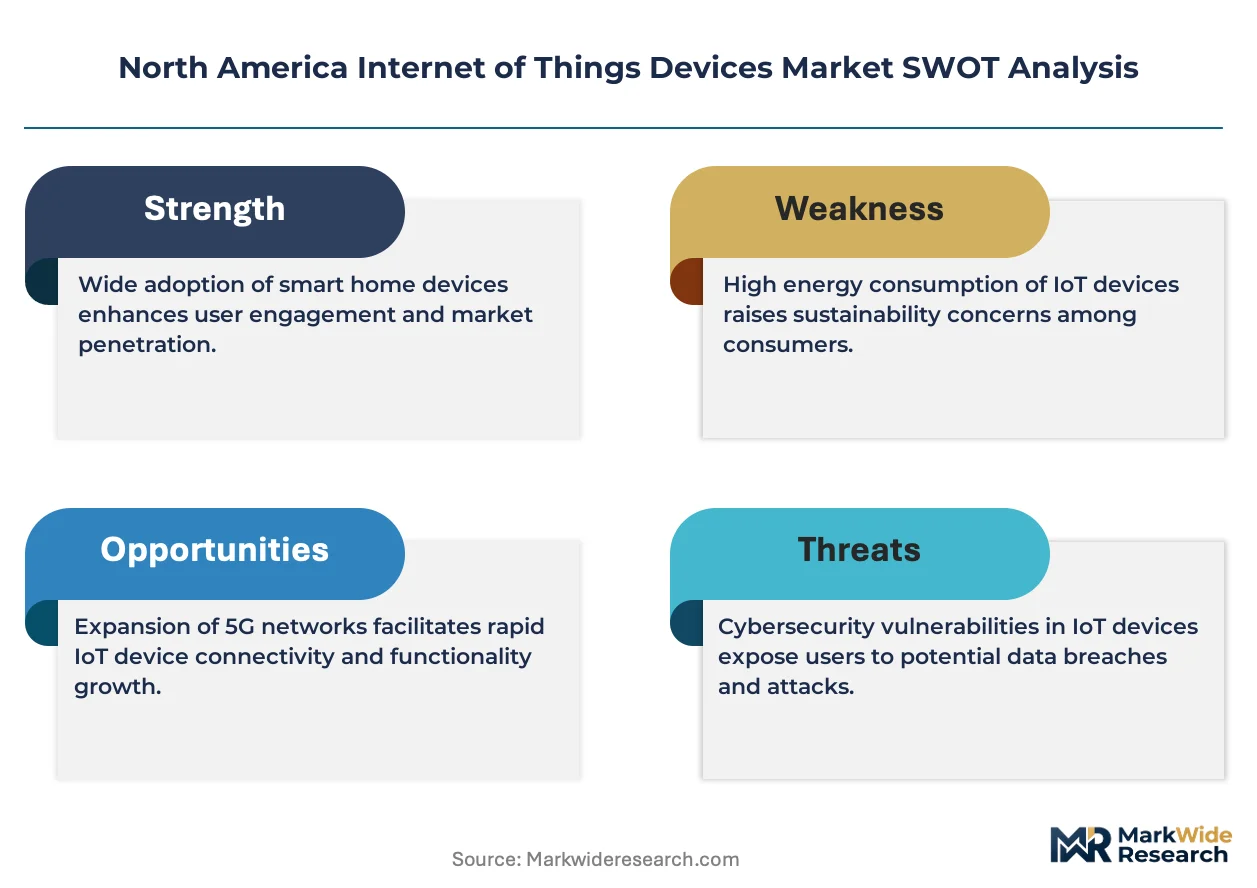
- Private 5G network deployment:Industrial facilities across Texas and Michigan are installing dedicated cellular infrastructure to support deterministic latency for automated guided vehicles and robotic process automation.
- FCC spectrum allocation for unlicensed bands:Expanded 902-928 MHz access enables longer-range agricultural sensors without licensed spectrum costs, accelerating precision farming adoption in the Great Plains.
- Healthcare monitoring mandate expansion:Medicare reimbursement codes now cover remote patient monitoring devices, driving hospital system procurement of connected cardiac and glucose monitoring hardware.
Market Restraints
- Semiconductor foundry concentration:Advanced microcontroller fabrication depends heavily on Taiwan-based capacity, exposing IoT module suppliers to geopolitical supply disruption risks.
- NIST post-quantum cryptography transition:Upcoming algorithm standardization will force hardware refresh cycles across federal and utility sensor networks before end-of-life.
- Cellular modem cost structure:Integrated LTE-M and NB-IoT chipsets carry premium pricing that compresses margins on sub-dollar sensor nodes for mass-market consumer applications.
Strategic Opportunities
- Canadian agricultural automation:Prairie provinces present underpenetrated demand for soil moisture and yield-monitoring sensors as grain operations consolidate and digitize.
- IRA clean energy incentives:Tax credits for grid modernization are accelerating utility deployments of connected transformers and distribution automation equipment.
- Matter protocol convergence:Cross-platform smart home standardization is collapsing fragmentation between Zigbee, Z-Wave, and proprietary ecosystems, enabling single-SKU retail distribution.
Industry Challenges
- Embedded systems security engineering scarcity:Firmware development talent with cryptographic implementation expertise commands premium compensation, constraining vendor scaling.
- IP67 certification timeline compression:Industrial sensor vendors face extended validation cycles for hazardous-location ratings required by oil and gas operators in the Permian Basin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Internet of Things Devices Market |
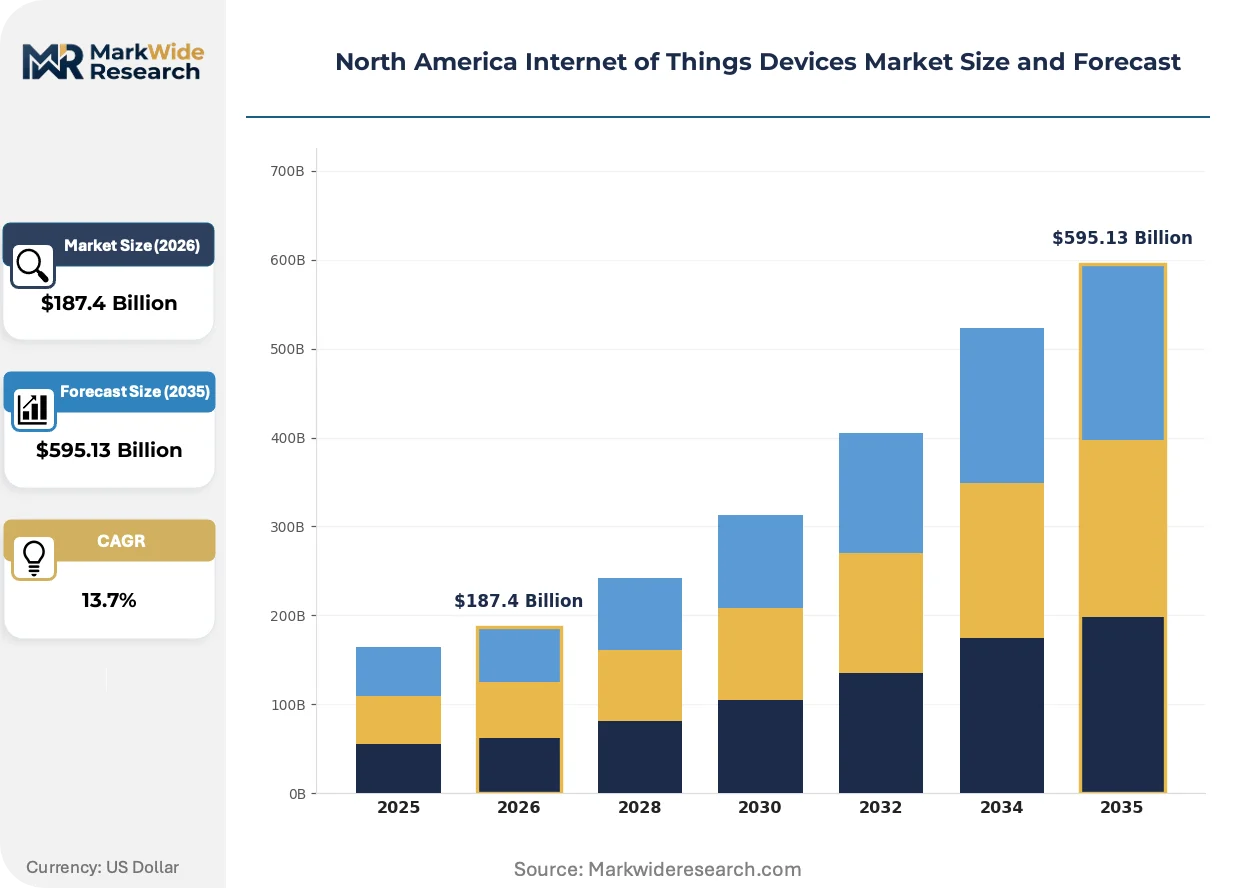
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $595.13 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearables, Home Automation, Industrial Sensors, Asset Tracking Technology: Bluetooth, Zigbee, Wi-Fi, Cellular Application: Smart Home, Healthcare Monitoring, Smart Cities, Agriculture End User: Consumers, Enterprises, Utilities, Government |
| Companies Covered | Amazon, Apple, Google, Intel, Cisco Systems, Microsoft, IBM, Qualcomm Technologies, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Internet of Things Devices Market Evolving Landscape
Compute migration toward sensor endpoints is redefining hardware specifications, while regulatory pressure on data sovereignty and device security is reshaping procurement criteria across federal and healthcare verticals.
On-device machine learning inference is migrating from cloud-dependent architectures to microcontroller-class platforms with sub-100 milliwatt power envelopes. Precision agriculture operators in California's Central Valley are piloting soil nutrient sensors with local anomaly detection to eliminate cellular data transmission costs. This compression of the compute stack is enabling battery-operated deployments in cellular dead zones previously requiring wired infrastructure.
The FDA's software-as-a-medical-device guidance harmonization with Health Canada is creating dual-compliance pathways for connected diagnostic hardware. Manufacturers must now submit unified pre-market documentation covering both jurisdictions, reducing time-to-market for cross-border healthcare shipments. Cardiovascular monitoring wearables represent the segment most affected, with vendors restructuring quality management systems to satisfy simultaneous FDA and Health Canada software validation requirements.
Hospital procurement departments are consolidating vendor relationships around integrated platform providers rather than point-solution hardware suppliers. Health systems in the Northeast corridor are awarding multi-year enterprise contracts to vendors offering combined device fleets, data analytics, and clinical workflow integration. This concentration pattern is most visible in academic medical centers, where capital committees prioritize interoperability over specialized single-function devices.
North America Internet of Things Devices Market Segmentation
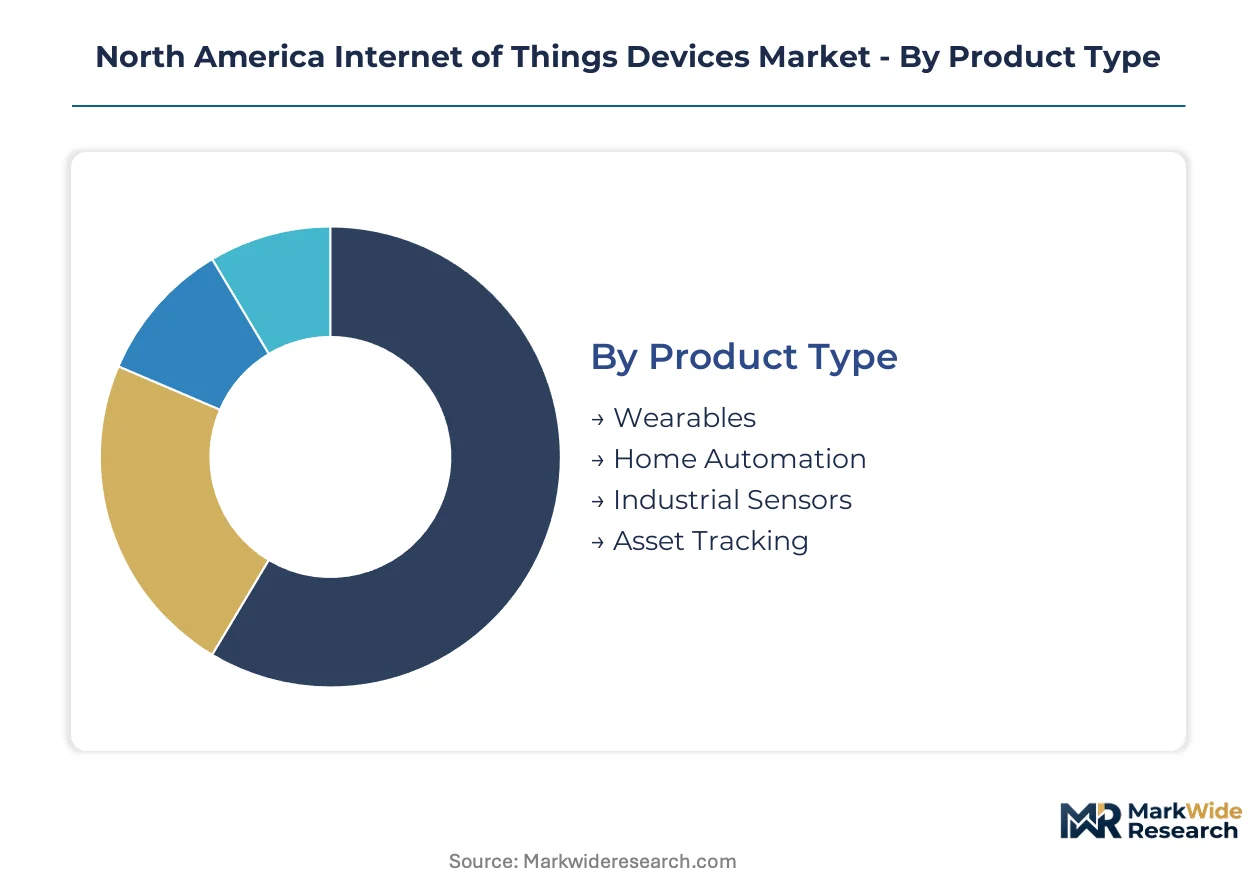
Segmentation in North America Internet of Things Devices reveals how hardware specifications, connectivity protocols, and procurement authority shape vendor positioning. Procurement committees in Texas hospitals and Michigan factories apply divergent evaluation criteria that fragment addressable markets. Understanding these fault lines enables targeted product roadmaps and channel strategies.
Product Type:
Maturity varies sharply across this dimension, with consumer-facing categories exhibiting commoditization pressure while industrial variants command sustained premium positioning.
- Wearables:Wrist-worn and body-worn sensors integrate photoplethysmography and accelerometry for continuous biometrics. Medicare reimbursement expansion in Florida and Arizona hospital systems is accelerating clinical-grade wearable procurement for remote cardiac monitoring programs.
- Industrial Sensors:Hardened devices with IP67 ingress protection and hazardous-location certifications monitor vibration, temperature, and pressure in refinery and pipeline infrastructure. Permian Basin operators require extended validation cycles that stretch supplier cash conversion timelines.
- Home Automation:Connected thermostats, lighting controllers, and security cameras dominate retail shelf space through big-box electronics channels.
- Asset Tracking:Battery-powered modules with cellular or Bluetooth Low Energy radios locate fleet vehicles, shipping containers, and high-value equipment across distributed supply chains.
Home Automation retains volume leadership; Industrial Sensors holds the steepest expansion curve.
Technology:
Cost tier stratification dominates vendor selection, with unlicensed protocols serving price-sensitive mass markets while cellular carries premium positioning for wide-area, mission-critical deployments.
- Cellular:LTE-M and NB-IoT modems with extended discontinuous reception cycles enable multi-year battery life for asset-tracking modules. Private 5G network buildouts in Texas industrial parks are displacing Wi-Fi for automated guided vehicle coordination.
- Bluetooth:Low Energy variants with sub-50 mW power draw anchor wearable and proximity-sensing applications. Silicon Valley health-tech startups leverage Bluetooth 5.3's improved range for hospital patient-tracking badges.
- Wi-Fi:High-throughput connectivity supports video-streaming doorbells and multi-camera security systems in residential installations.
- Zigbee:Mesh networking protocol with sub-GHz and 2.4 GHz variants underpins smart lighting and sensor networks in commercial building automation.
Bluetooth commands installed-base dominance; Cellular is expanding most quickly through industrial private network deployments.
Application:
Customer type fragmentation creates distinct sales motions, with consumer applications flowing through retail channels while enterprise and government verticals require consultative solution selling.
- Healthcare Monitoring:Connected cardiac, glucose, and pulse-oximetry devices transmit patient data to clinical decision-support systems. FDA and Health Canada harmonized software-as-a-medical-device guidance is restructuring quality management systems for cross-border cardiovascular wearable vendors.
- Smart Cities:Traffic sensors, environmental monitors, and connected streetlight infrastructure generate municipal operational data. California municipalities are consolidating vendor relationships around integrated platform providers offering combined device fleets and analytics.
- Smart Home:Voice-controlled entertainment, climate, and security systems target residential consumer spending through electronics retail and direct-to-consumer channels.
- Agriculture:Soil moisture, yield-monitoring, and precision-spray drones digitize grain operations across the Great Plains and Canadian prairie provinces.
Smart Home captures consumer revenue concentration; Healthcare Monitoring is climbing the fastest on reimbursement tailwinds.
End User:
Procurement authority and security certification requirements segment this dimension, with federal and utility deployments imposing NIST cybersecurity frameworks that consumer markets ignore.
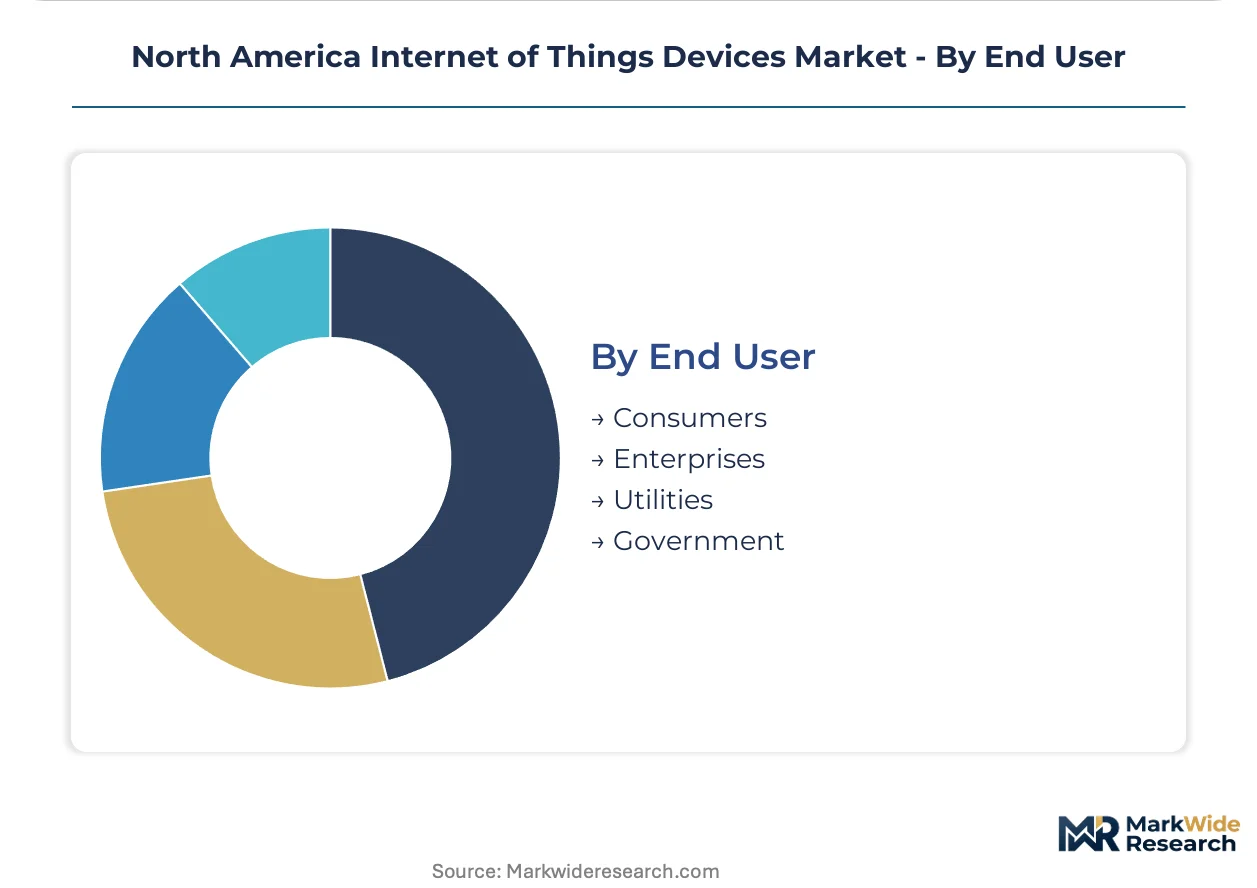
- Enterprises:Manufacturing, logistics, and healthcare organizations procure connected device fleets with enterprise-grade management platforms. Northeast corridor academic medical centers are awarding multi-year contracts prioritizing interoperability over specialized point solutions.
- Utilities:Grid operators deploy connected transformers, distribution automation equipment, and demand-response endpoints. IRA clean energy tax credits are accelerating procurement timelines for grid modernization programs.
- Consumers:Individual purchasers acquire wearables and home automation through retail and e-commerce channels with minimal integration requirements.
- Government:Federal agencies and defense contractors require NIST-compliant devices with post-quantum cryptography migration pathways.
Enterprises dominate current revenue pools; Utilities are gaining share fastest on federal incentive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in IoT devices, exporting cellular modules and industrial sensors to Mexico and Canada while importing consumer wearables from Asian contract manufacturers. Canada and Mexico serve as critical assembly and testing corridors for U.S.-designed hardware. Regional supply chains concentrate in technology corridors where engineering talent and venture funding cluster.
United States
FCC spectrum allocations for unlicensed 902-928 MHz and 2.4 GHz bands determine device interoperability standards across the country. Medicare reimbursement expansion for remote patient monitoring drives hospital procurement of connected cardiac and glucose devices. Silicon Valley anchors hardware engineering talent density, with venture-funded startups clustering around San Jose and San Francisco for connected device development.
Canada
Prairie provinces present underpenetrated demand for soil moisture and yield-monitoring sensors as grain operations consolidate. Health Canada harmonizes software-as-a-medical-device guidance with FDA standards, creating dual-compliance pathways for cardiovascular wearable vendors. Toronto and Vancouver host growing IoT engineering clusters serving cross-border healthcare and smart city deployments.
Mexico
Maquiladora assembly plants near the U.S. border manufacture cellular modules and industrial sensors for re-export to American markets. PROFECO consumer protection standards shape warranty and data privacy requirements for connected home devices sold domestically. Baja California and Chihuahua concentrate electronics manufacturing infrastructure, with Tijuana emerging as a testing hub for LTE-M and NB-IoT hardware.
North America Internet of Things Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers that combine device hardware, cloud infrastructure, and analytics software. Tiered competition separates hyperscale cloud operators from specialized silicon vendors and industrial networking specialists. Strategic archetypes include edge-native platform builders, cellular modem integrators, and hardened industrial gateway manufacturers. Dominant competitive moves encompass strategic partnerships between cloud and hardware vendors, plus vertical integration into semiconductor design.
Within the cloud-platform archetype, Amazon and Microsoft occupy positions as anchor tenants for enterprise IoT deployments. Qualcomm Technologies exemplifies the cellular-specialist tier, supplying wide-area connectivity modules for asset-tracking applications. Cisco Systems represents the industrial-networking vector, with hardened switches and gateways purpose-built for factory-floor environments.
| Leading Market Players |
|---|
| Amazon |
| Apple |
| Intel |
| Cisco Systems |
| Microsoft |
| IBM |
| Qualcomm Technologies |
| Texas Instruments |
| Others |
Value Network & Pricing Analysis
The I-35 freight corridor linking Texas manufacturing hubs to Mexican maquiladora assembly plants transmits cost volatility from diesel fuel surcharges directly into cellular module pricing tiers, concentrating margin pressure on vendors lacking captive production while enabling premium positioning for those with integrated border facilities.
Pricing Analysis
LTE-M and NB-IoT modem pricing maintains a three-generation spread, with current-generation 5G RedCap modules commanding substantial premiums over mature LTE-M variants and legacy 2G fallback units facing accelerated depreciation. Pricing stratifies across premium, standard, and economy tiers based on FCC certification tier and volume commitment scale, with industrial sensor vendors bearing cost compression from foundry capacity constraints while healthcare monitoring hardware retains pricing power through FDA clearance requirements. Consumer wearables exhibit the highest buyer price sensitivity, whereas utilities demonstrate minimal elasticity due to IRA-mandated procurement timelines.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment to Chinese fabs have redirected microcontroller sourcing toward Taiwan, South Korea, and domestic U.S. foundries, tightening availability for sub-28nm process nodes. Supply chains draw from silicon wafers, rare-earth magnet components, and lithium-ion cell supplies, with single-source vulnerability concentrated in Taiwan-based advanced packaging capacity. Distribution runs through tier-one electronics distributors serving industrial OEMs alongside direct procurement relationships with hospital systems and utility cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive positioning through regulatory entrenchment, where FDA and NIST compliance histories create switching costs that lock hospital systems and federal agencies into established vendor relationships.
For Market Incumbents: Insulate market position by deepening backward integration into secure microcontroller design and expanding captive testing capacity in Baja California to circumvent tariff exposure. Prioritize NIST post-quantum cryptography certification investment ahead of algorithm standardization to capture federal refresh cycles before competitors achieve compliance. For New Entrants and Emerging Players: Establish a beachhead in Canadian prairie agricultural automation, where soil moisture sensor penetration remains sparse and grain operation consolidation creates concentrated account opportunities. Pursue white-label partnerships with established industrial distributors rather than direct enterprise sales to bypass lengthy vendor qualification processes. For Investors and Strategic Acquirers: Edge-native platform builders with integrated device-to-cloud stacks represent the most attractive acquisition archetype, as hospital procurement consolidation favors end-to-end solution providers over point-product vendors. Monitor private 5G network deployment velocity in Texas and Michigan industrial parks as the signal indicating whether cellular module demand will sustain premium pricing or face commoditization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Platform Integration | AWS IoT Greengrass and Azure IoT Edge deployments enable sub-100ms latency for automated guided vehicle coordination. |
| Private 5G Network Deployment | Texas and Michigan industrial facilities build dedicated cellular infrastructure to replace Wi-Fi for deterministic robotics control. |
| Post-Quantum Cryptography Certification | NIST algorithm standardization forces hardware refresh cycles across federal and utility sensor networks. |
| Cross-Border Healthcare Compliance | FDA-Health Canada harmonization creates dual-market pathways for cardiovascular wearable vendors. |
| Matter Protocol Convergence | Cross-platform smart home standardization collapses fragmentation between Zigbee, Z-Wave, and proprietary ecosystems. |
Research Methodology
Desk research of FCC spectrum allocation filings, NIST cybersecurity framework publications, and hospital procurement database records preceded structured interviews with biomedical engineering directors, utility grid modernization planners, and industrial IoT platform architects. Primary fieldwork with semiconductor distribution channel partners and maquiladora operations managers cross-validated secondary trade flow data and customs records. Bottom-up unit economics modeling triangulated against top-down addressable market sizing from venture funding disclosures and federal incentive program allocations.
Assumptions held fixed across the modeling period include sustained IRA clean energy tax credit availability, stable Taiwan-based foundry capacity access, and continued Medicare reimbursement code coverage for remote patient monitoring devices. Variable conditions encompassed private 5G network deployment velocity, NIST post-quantum cryptography standardization timing, and FCC spectrum reallocation decisions for unlicensed IoT bands. Segmentation modeling incorporated product type, connectivity protocol, application vertical, and end-user procurement authority dimensions. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable technology markets.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, cross-border tariff regimes, or federal healthcare reimbursement policy would shift the trajectory. Material shifts in FCC spectrum allocation priorities or Taiwan-based foundry capacity availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
North America IoT Node and Gateway Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
Europe IoT in Smart Cities Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
5G Internet of Things Market
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market