
 IoT Cellular Market | 2026-2036
IoT Cellular Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Cellular Market Intelligence
The substitution of legacy 2G and 3G connectivity with low-power wide-area networks (LPWAN) like NB-IoT is broadening the economic viability of massive IoT deployments. Qualcomm Technologies leverages its extensive patent portfolio in cellular standards to influence chipset design and functionality. Quectel specializes in a wide array of cellular modules, catering to diverse application needs from smart metering to asset tracking. Thales Group differentiates through its focus on security and embedded SIM (eSIM) solutions for trusted connectivity.
IoT Cellular technology provides wireless connectivity for Internet of Things devices over mobile carrier networks. It utilizes licensed spectrum and established protocols like LTE-M and 5G to ensure reliable, secure data transmission for devices often deployed in remote or mobile environments. Among network technologies, NB-IoT and LTE-M dominate deployments requiring low power consumption and deep coverage for static assets. The Transportation end-user industry, particularly for fleet management and asset tracking applications, represents a high-value segment due to its stringent uptime and mobility requirements.
Regulatory bodies like the FCC in the United States and China's MIIT govern spectrum allocation and device certification, directly impacting market access. In Europe, GDPR compliance for data handling and CE marking for device safety are critical considerations for all IoT solution providers. Stakeholders must now decide on investment strategies that balance the long-term potential of 5G with the immediate scale offered by established LTE-M and NB-IoT networks.
Market Dynamics
The fundamental dynamic shaping the IoT cellular market is the network transition from legacy 2G and 3G systems to low-power, wide-area technologies. This shift, driven by industrial policy in China and 5G rollouts, is redefining the economic and technical feasibility of massive-scale deployments.
Growth Catalysts
- 5G Network Deployment:The expansion of 5G infrastructure provides the ultra-reliable low-latency communication required for advanced applications in telematics, connected vehicles, and remote surgery, creating new high-value service tiers.
- Government Industrial Policy:Initiatives like China's 'dual carbon goals' mandate efficiency improvements in energy and manufacturing, spurring large-scale deployments of cellular-connected sensors for industrial process monitoring and optimization.
- Connected Healthcare Expansion:Demand for remote patient monitoring and telehealth services, particularly for chronic disease management, drives adoption of cellular-enabled medical devices that require reliable, secure connectivity outside of clinical settings.
Market Restraints
- Spectrum Fragmentation:The lack of globally harmonized spectrum for LPWAN technologies like NB-IoT and LTE-M complicates device design and certification, increasing costs for manufacturers aiming for a worldwide market.
- Security Vulnerabilities:The immense scale of IoT deployments creates a vast attack surface, with device and network security concerns acting as a primary barrier to adoption, especially in critical infrastructure sectors.
- Substitution from Unlicensed Spectrum:Technologies like Wi-Fi HaLow and LoRaWAN offer competitive, low-cost connectivity alternatives for localized, private IoT networks in settings like smart buildings or factory floors, limiting cellular's addressable market.
Strategic Opportunities
- Non-Terrestrial Networks:Integrating cellular IoT with satellite constellations opens a new frontier for ubiquitous connectivity, enabling asset tracking and remote monitoring for agriculture, maritime, and logistics industries in areas without terrestrial coverage.
- Edge Computing Integration:Combining on-device processing with cellular connectivity allows for real-time analytics and decision-making without reliance on cloud backhaul, creating value in latency-sensitive applications like industrial robotics and video surveillance.
- Smart City Projects in India:Government-led initiatives to build smart cities across India create substantial opportunities for cellular IoT in traffic management, public safety, smart lighting, and waste management systems.
Industry Challenges
- Device Lifecycle Management:The operational complexity of managing firmware updates, security patches, and end-of-life decommissioning for millions of devices deployed over long lifecycles presents a significant logistical and financial challenge for solution providers.
- Interoperability Across Platforms:Ensuring seamless data flow between diverse IoT devices, connectivity management platforms, and enterprise applications from different vendors remains a major hurdle, hindering the creation of cohesive, end-to-end solutions.
- IP Licensing Complexity:Navigating the intricate and often contentious landscape of standard essential patents (SEPs) for cellular technologies adds significant cost and legal risk for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Cellular Market |
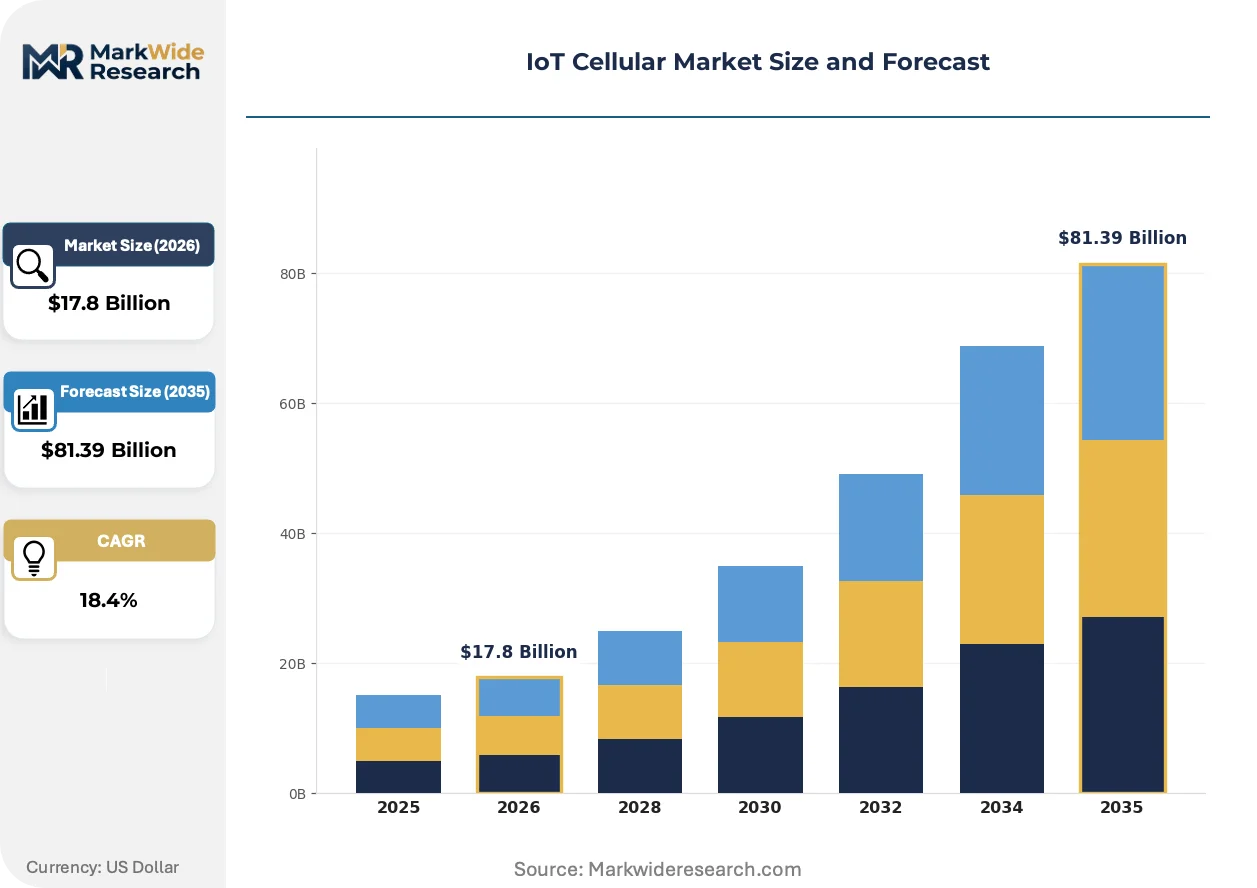
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $81.39 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Network Technology: NB-IoT, LTE-M, 5G, Cat-M1, eMTC, GPRS Application: Smart Metering, Fleet Management, Asset Tracking, Environmental Monitoring, Smart Agriculture, Connected Healthcare Device Type: Wearables, Smart Sensors, Connected Vehicles, Industrial Controllers, Security Systems, Smart Appliances End User Industry: Manufacturing, Transportation, Energy & Utilities, Agriculture Technology, Consumer Electronics, Public Safety |
| Companies Covered | Quectel, Thales Group, Fibocom Wireless, Telit Cinterion, u-blox Holding, Qualcomm Technologies, Sierra Wireless, AT&T, Verizon Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Cellular Market Strategic Shifts & Innovations
The market's evolution is defined by a move from providing basic connectivity to delivering integrated, secure, and intelligent solutions. This transition is evident in how devices are provisioned, how data is governed, and how services are procured by enterprise customers.
Embedded SIM (eSIM) and integrated SIM (iSIM) technologies embed subscriber profiles directly onto a device's processor. Device manufacturers in the automotive and industrial sectors are rapidly adopting this approach to streamline manufacturing and simplify global logistics. This software-based provisioning is overtaking the traditional physical SIM card, reducing operational complexity and enabling remote carrier management over the device's lifetime.
Data privacy mandates, such as Europe's GDPR and California's CCPA, are setting stringent rules for personal data handling in IoT ecosystems. This regulatory pressure is forcing a redesign of IoT platform architectures to incorporate privacy-by-design principles. The connected health and consumer electronics segments are most affected, compelling vendors to implement stronger encryption and transparent consent management tools.
A notable shift in enterprise buying behavior is the move from acquiring individual components to procuring comprehensive, bundled IoT solutions. This model bypasses traditional component distribution channels in favor of managed service providers or module vendors offering a single package. This trend is most prominent in asset tracking and smart utility verticals, where total cost of ownership and operational simplicity are the primary decision drivers.
IoT Cellular Market Segmentation
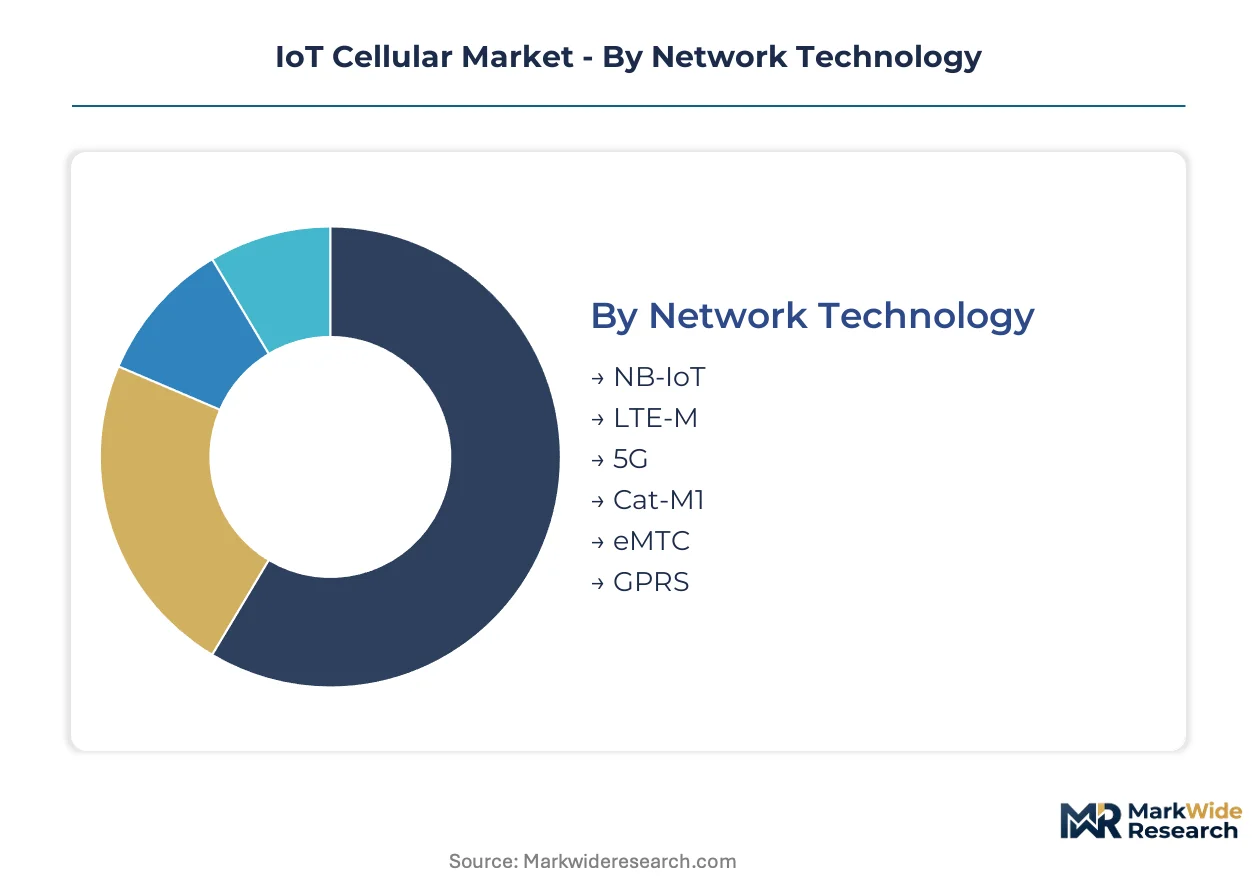
Understanding the segmentation of the IoT Cellular market reveals how diverse technological capabilities and application needs drive adoption across various industries. This granular view highlights where specific innovations are gaining traction and which segments present the most significant growth opportunities for solution providers.
Network Technology:
Network technologies differentiate based on their suitability for deeply embedded, long-lifecycle devices versus more complex, standalone applications requiring higher bandwidth.
- NB-IoT:Narrowband IoT provides highly efficient, low-power connectivity for static devices, optimizing battery life for years in challenging environments. Demand concentrates in smart metering and environmental monitoring in China, driven by government efficiency mandates and widespread infrastructure deployment.
- 5G:Fifth-generation cellular technology offers ultra-reliable low-latency communication and high bandwidth essential for mission-critical applications and real-time data processing. Connected vehicles and industrial automation in Germany are driving 5G adoption, requiring rapid data exchange for safety and operational control.
- LTE-M:LTE-M provides a balance of power efficiency and moderate bandwidth, supporting mobile IoT devices with voice capabilities and broader use cases than NB-IoT.
- Cat-M1:This category is largely synonymous with LTE-M, offering enhanced machine-type communication for mobile asset tracking and wearable devices.
- eMTC:Enhanced Machine-Type Communication, often used interchangeably with LTE-M and Cat-M1, supports diverse IoT use cases with moderate data requirements and extended battery life.
- GPRS:General Packet Radio Service, a legacy 2G technology, still serves basic tracking and remote monitoring in cost-sensitive markets with established 2G infrastructure.
NB-IoT leads volumes today; 5G is gaining share fastest.
Application:
Applications vary significantly by the type of customer they serve, ranging from municipal utilities requiring large-scale data collection to individual patients needing continuous health monitoring.
- Fleet Management:This application involves real-time monitoring and optimization of vehicle fleets, including route planning, driver behavior analysis, and predictive maintenance. Logistics companies in the United States prioritize fleet management for operational efficiency and stringent regulatory compliance in freight transport.
- Connected Healthcare:Connected healthcare utilizes cellular IoT for remote patient monitoring, telehealth services, and secure medical device connectivity outside traditional clinical settings. Demand in Europe is driven by aging populations and the need for chronic disease management, adhering to strict GDPR data privacy regulations.
- Smart Metering:Enables remote collection of utility consumption data for electricity, gas, and water, facilitating accurate billing and demand-side management for utility providers.
- Asset Tracking:Provides location and status monitoring for valuable mobile or static assets across diverse industries, from logistics containers to construction equipment.
- Environmental Monitoring:Deploys cellular-connected sensors to track air quality, water levels, and soil conditions for regulatory compliance, resource management, and climate change studies.
- Smart Agriculture:Integrates cellular sensors for precision farming, monitoring crop health, irrigation systems, and livestock management in remote agricultural areas.
Smart Metering applications currently represent the largest installed base, while Connected Healthcare exhibits the steepest expansion trajectory.
Device Type:
Device types span a wide range of technological maturity, from established industrial components with long lifecycles to rapidly evolving consumer electronics requiring frequent updates.
- Connected Vehicles:These devices integrate cellular connectivity directly into automobiles for telematics, infotainment, over-the-air updates, and advanced driver-assistance systems. Automotive manufacturers in Japan are investing heavily in connected vehicle platforms for safety enhancements and future autonomous driving features.
- Smart Sensors:Smart sensors are compact, low-power devices embedded with cellular modules for collecting environmental or operational data across various industries. Industrial automation projects in South Korea extensively deploy smart sensors for predictive maintenance and process optimization within manufacturing facilities.
- Wearables:Includes smartwatches, fitness trackers, and specialized health monitors using cellular for standalone connectivity, emergency services, and real-time data synchronization.
- Industrial Controllers:Cellular-enabled devices managing machinery and processes in factories, energy infrastructure, and other industrial environments for remote operation and monitoring.
- Security Systems:Cellular backup and primary connectivity for alarms, surveillance cameras, and access control systems, ensuring continuous operation even during power outages.
- Smart Appliances:Home devices like refrigerators, washing machines, and HVAC systems leveraging cellular for remote control, diagnostics, and energy management.
Smart Sensors form the foundational volume for IoT deployments, with Connected Vehicles driving significant revenue growth.
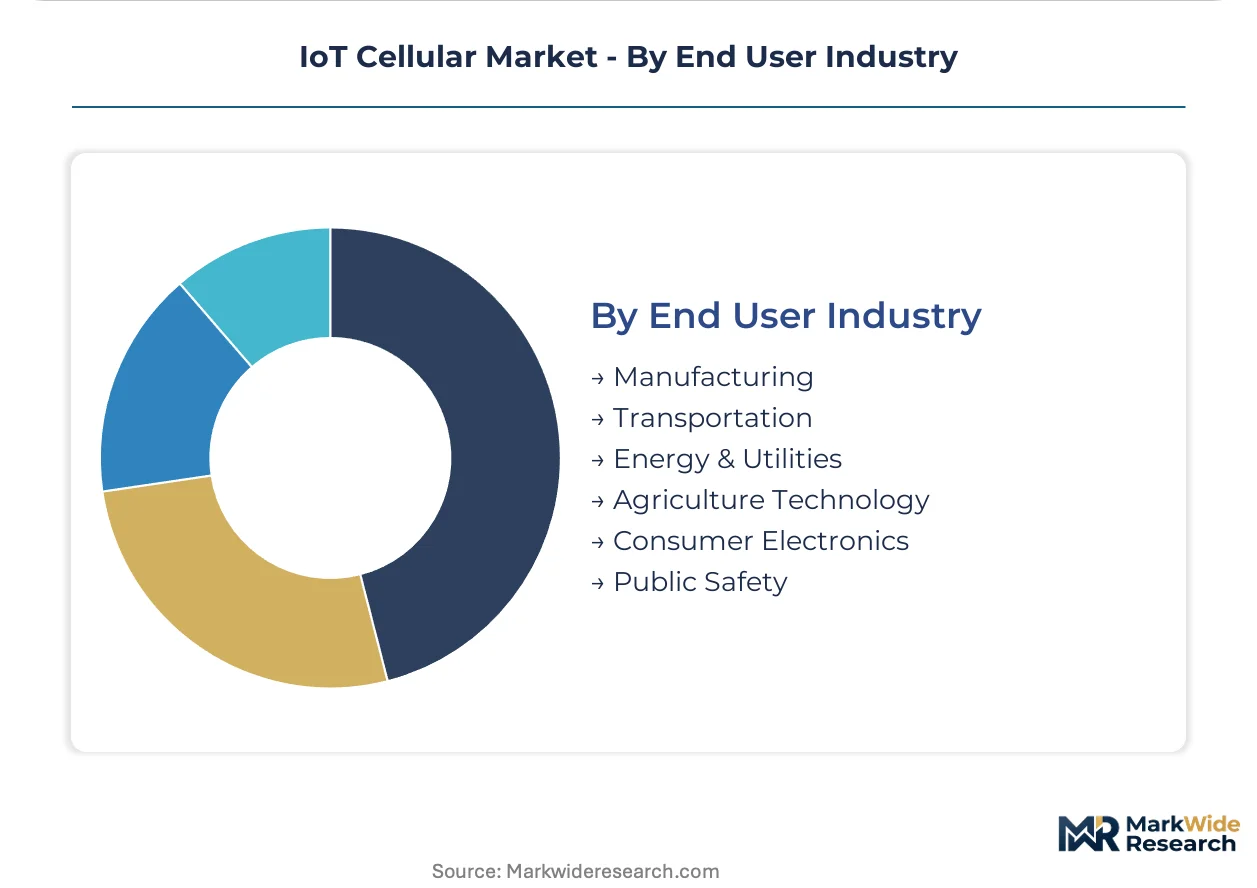
End User Industry:
The volume and scale of IoT cellular deployments vary dramatically across end-user industries, reflecting diverse operational needs and regulatory landscapes.
- Transportation:This industry segment leverages cellular IoT for fleet management, asset tracking, and smart logistics across road, rail, and maritime operations. Significant investments in transportation IoT are observed in the United States, driven by supply chain efficiency and safety regulations.
- Manufacturing:Manufacturing utilizes cellular connectivity for industrial automation, predictive maintenance, and supply chain visibility within smart factories. China's industrial policy and 'dual carbon goals' are accelerating cellular IoT adoption in its vast manufacturing sector for efficiency and sustainability.
- Energy & Utilities:Implements cellular for smart grids, remote meter reading, and infrastructure monitoring, enhancing operational efficiency and reliability for utility providers.
- Agriculture Technology:Uses cellular for precision farming, livestock tracking, and environmental monitoring in rural areas, optimizing resource use and improving yields.
- Consumer Electronics:Integrates cellular into devices like smartwatches, tablets, and home appliances for enhanced functionality, remote management, and user convenience.
- Public Safety:Deploys cellular IoT for emergency services, surveillance, and disaster response communications, enhancing situational awareness and coordination for first responders.
Transportation represents a high-value segment with critical uptime requirements, while Manufacturing drives broad-based industrial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast industrial base drives significant IoT cellular adoption globally. Government policies and expanding 5G networks foster widespread deployment. This creates diverse regional concentrations across key economic zones.
China
China's industrial automation initiatives and smart metering drive substantial cellular IoT demand. The country's 'dual carbon goals' and MIIT policies accelerate efficient technology adoption. Yangtze River Delta manufacturing hubs are integrating cellular-connected sensors for process optimization and energy management.
United States
United States demand for fleet management and connected healthcare services fuels cellular IoT growth. FCC regulations govern spectrum allocation, impacting device certification and market access. Silicon Valley tech companies are developing advanced edge computing solutions for real-time data processing in critical applications.
Germany
Germany's connected vehicles and advanced industrial automation generate high 5G adoption. CE marking ensures device safety and compliance for IoT solutions deployed across Europe. The automotive manufacturing region around Stuttgart is accelerating 5G-enabled telematics deployments for enhanced safety and efficiency.
India
India's smart city projects and agricultural technology applications present significant cellular IoT opportunities. The PLI scheme encourages local manufacturing of IoT components, fostering domestic innovation. Bengaluru's tech ecosystem is piloting cellular IoT solutions for traffic management and public safety systems.
Japan
Japan's connected vehicle platforms and smart sensor deployments are key demand drivers. METI actively promotes digital transformation across industries, including advanced IoT applications. The Kanto region, including Tokyo, is a center for advanced automotive and industrial IoT research and development initiatives.
IoT Cellular Market Key Industry Players
Global majors compete with regional champions across cellular IoT connectivity solutions. This market structure features both highly consolidated segments, such as chipset design, and more fragmented areas like module integration. Foundational technology providers, specialized module manufacturers, and end-to-end solution integrators represent key strategic archetypes. Companies frequently engage in strategic partnerships to broaden their offerings and pursue portfolio diversification to address diverse application needs.
Specialized module manufacturers, such as Quectel, occupy a significant position in providing a wide array of cellular modules. Thales Group, a global entity, exemplifies a focus on security and embedded SIM solutions for trusted connectivity. Qualcomm Technologies, Inc., anchors the foundational technology tier, leveraging its extensive patent portfolio in cellular standards to influence chipset design. These players collectively shape the market by offering distinct value propositions, from volume module supply to secure connectivity and core intellectual property.
| Leading Market Players |
|---|
| Quectel |
| Thales Group |
| Fibocom Wireless |
| Telit Cinterion |
| u-blox Holding |
| Qualcomm Technologies |
| Sierra Wireless |
| AT&T |
| Verizon Communications |
| Others |
Cost & Logistics Intelligence
Government industrial policies, particularly China's 'dual carbon goals', necessitate rapid deployment of cellular IoT solutions, driving demand for cost-effective and energy-efficient modules. This demand pressure forces module manufacturers to optimize production and streamline logistics, influencing pricing structures across the value chain.
Pricing Analysis
Input-cost pass-through from semiconductor foundries significantly influences pricing for cellular IoT modules and chipsets. Hybrid subscription and per-unit transactional models dominate the market, reflecting diverse customer needs for connectivity and managed services. Price differentiation stems from factors like module quality grade, specific regulatory certifications such as CE marking, and the volume scale of deployment. Pricing softness runs through basic LPWAN modules due to increasing competition from unlicensed spectrum alternatives. Smart Metering applications are generally more price-sensitive than high-value segments like Connected Vehicles, which prioritize reliability and advanced features.
Supply Chain Analysis
Semiconductor chipset manufacturing largely rests on a concentrated base of specialized foundries in Taiwan, while cellular module assembly is heavily concentrated in China. The supply chain relies heavily on the availability of advanced semiconductor chipsets and specialized eSIM components. Single-source vulnerability for critical components presents a structural risk, particularly for proprietary technologies. Downstream distribution runs primarily through direct sales to large enterprise integrators and dedicated channel partners for smaller, localized deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT Cellular market presents a late-cycle quality story, with a demand-shift toward premium specifications driven by mission-critical 5G applications in industrial automation and connected healthcare.
For Market Incumbents: Anchor existing market share by deepening vertical integration into secure eSIM and iSIM solutions, addressing the threat from fragmented unlicensed spectrum alternatives. Expand patent portfolios in 5G RedCap and ultra-reliable low-latency communication standards. Invest significantly in obtaining global regulatory certifications like FCC and CE marking to maintain market access and differentiate offerings. Develop advanced R&D in edge computing capabilities to support real-time data processing for high-value applications.
For New Entrants and Emerging Players: Begin with targeting underpenetrated segments such as Non-Terrestrial Networks for remote asset tracking in agriculture and maritime sectors. Focus on developing specialized bundled IoT solutions for specific verticals, like smart city projects in India, offering a comprehensive managed service. A go-to-market strategy centered on operational simplicity and lower total cost of ownership can appeal to segments like environmental monitoring in emerging markets.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized module manufacturers possessing strong intellectual property in security and advanced connectivity protocols. Long-term viability hinges on companies capable of delivering integrated, secure, and intelligent solutions over a multi-year horizon. Identify acquisition targets with proven expertise in edge computing integration or satellite IoT connectivity. The accelerated deployment of 5G standalone networks represents a critical signal to watch as an inflection indicator for market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| eSIM/iSIM Technology Development | Streamlines device provisioning and enhances security for global IoT deployments. |
| 5G RedCap Module Launch | Expands 5G applicability to power-constrained IoT devices, broadening market reach. |
| Edge AI Integration | Enables real-time data processing and decision-making for latency-sensitive applications. |
| Satellite IoT Partnership | Extends cellular IoT coverage to remote areas without terrestrial network access. |
| Regulatory Compliance Investment | Ensures market access and builds trust for IoT solutions across diverse geographies. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. This approach integrates insights from primary interviews with industry stakeholders such as telecom operators, IoT solution architects, device manufacturers, and regulatory bodies. Secondary validation draws from comprehensive sources including MIIT reports, FCC filings, company financial disclosures, and industry association publications.
Historical trendline analysis informs future growth projections across the modeling period. The analytical framework segments the market across network technology, application, device type, end-user industry, and geographic region. Compound annual growth rates were derived through a weighted average of segment-specific growth rates. Key forecast inputs include 5G network rollout schedules and cellular module shipment data.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or rapid shifts in global economic conditions. Forecasts reflect assumptions regarding stable regulatory environments and continued technological advancements. A small set of named triggers, such as major cybersecurity breaches or significant spectrum policy changes, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Cellular M2M Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Internet of Things (IoT) in Manufacturing Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
IoT Integration Services Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
IoT Lpwans Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Global 5G Industrial IOT Market
Internet of Things (IoT)
IoT Utilities Market