
 Smart Pool Systems Market | 2026-2036
Smart Pool Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pool Systems Market Insights
UL 1081 certification for permanently connected swimming pool pumps is unwinding competitive access for smaller hardware vendors. Pentair plc leverages captive distribution through pool-builder networks to sustain premium positioning. Fluidra S.A. anchors European demand with specialized automation controllers. Hayward Holdings, Inc. competes on R&D intensity in salt-chlorination integration.
Smart pool systems encompass networked electromechanical equipment that automates water circulation, chemical balancing, temperature management, and filtration through sensor feedback loops operating at 120V-240V single-phase supply. These systems reduce manual intervention and optimize energy consumption through variable-speed pump algorithms. Automation Devices and Monitoring Systems command the dominant share of current product revenue as pool owners prioritize remote visibility. IoT Solutions and Artificial Intelligence represent the fastest-expanding technology layers, with cloud-based predictive analytics creating new margin pools for platform providers. Hotels and Resorts drive commercial-grade demand for integrated multi-pool management dashboards.
FCC Part 15 governs wireless emissions from connected pool controllers in the United States, while EPA ENERGY STAR specifications shape pump efficiency benchmarks. ETL and CSA certifications create parallel compliance tracks for North American market entry. Stakeholders must monitor how evolving cybersecurity standards for consumer IoT devices reshape product liability and insurance requirements for connected outdoor equipment.
Market Dynamics
Variable-speed pump algorithms mandated under EPA ENERGY STAR specifications are compressing margins for single-speed hardware incumbents while accelerating platform consolidation around cloud-connected automation stacks.
Growth Catalysts
- EPA ENERGY STAR pump efficiency mandates:Tightening federal benchmarks force equipment replacement cycles, creating pull-through demand for integrated automation controllers in Sun Belt states.
- Suburban residential electrification:Homeowner investment in outdoor living infrastructure is concentrating in Texas, Florida, and Arizona metropolitan clusters.
- Salt-chlorination integration:Convergence of mineral sanitation with variable-speed circulation reduces chemical handling labor and extends equipment replacement intervals.
Market Restraints
- UL 1081 certification barriers:Third-party safety testing requirements for permanently connected pumps impose fixed compliance costs that disadvantage smaller hardware entrants.
- Semiconductor supply concentration:Microcontroller shortages originating in East Asian fabrication facilities delay controller board production for North American pump OEMs.
- Copper and rare-earth magnet volatility:Permanent-magnet motor materials expose variable-speed pump manufacturers to commodity price swings without pass-through mechanisms.
Strategic Opportunities
- Canadian provincial rebate programs:British Columbia and Ontario utility incentives for high-efficiency pool equipment remain underpenetrated relative to US Sun Belt saturation.
- Commercial multi-pool management:Hotels and resorts require centralized dashboards for chemical monitoring across dispersed aquatic facilities.
- FCC Part 15 unlicensed spectrum expansion:Sub-GHz wireless protocol adoption enables lower-cost connectivity modules for entry-tier automation controllers.
Industry Challenges
- Cybersecurity liability exposure:Connected outdoor equipment lacks hardened firmware standards, exposing installers and platform operators to insurance coverage gaps.
- Legacy 120V infrastructure incompatibility:Older residential electrical panels require costly upgrades to support 240V variable-speed pump installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pool Systems Market |
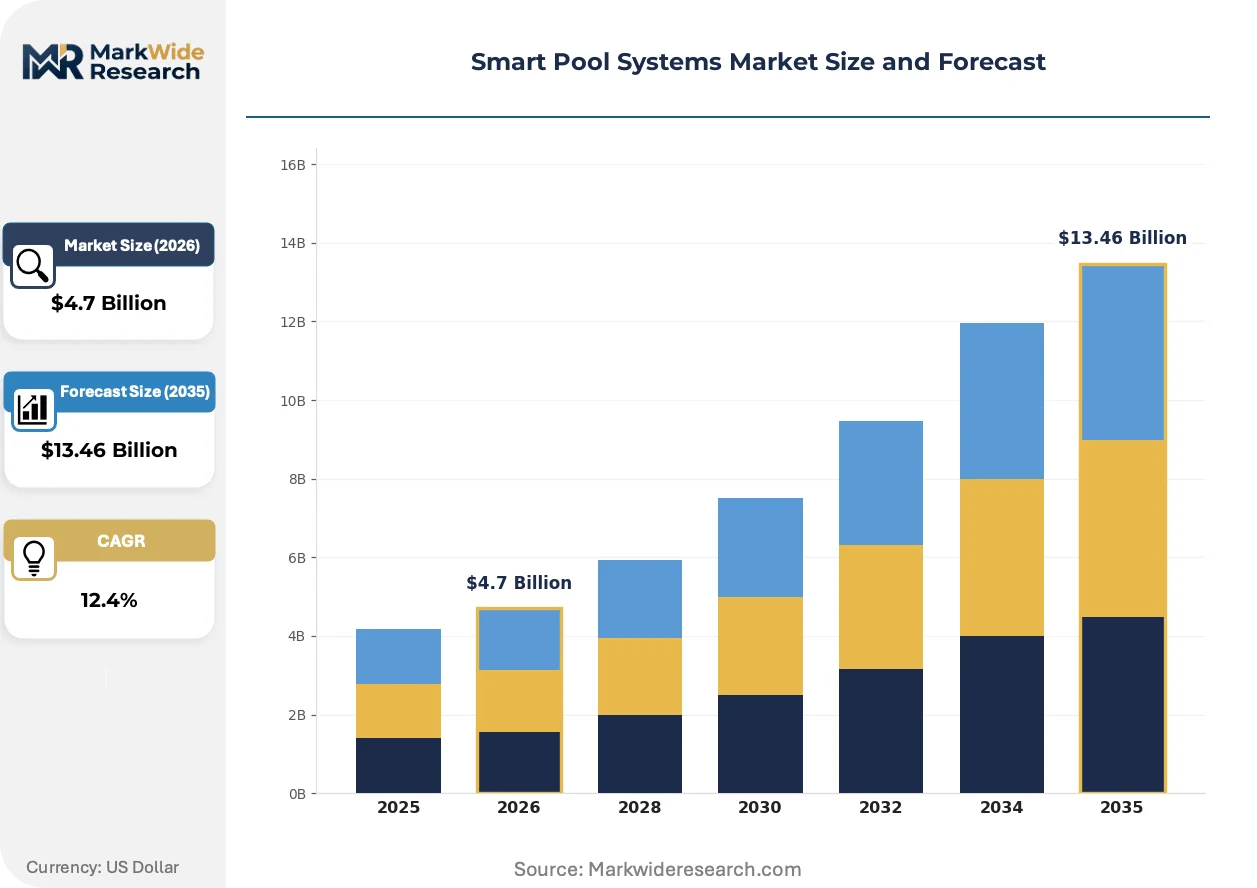
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $13.46 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automation Devices, Monitoring Systems, Water Treatment Solutions, Heating Controllers Technology: IoT Solutions, Cloud Computing, Artificial Intelligence, Mobile Applications End User: Residential Users, Commercial Establishments, Pool Maintenance Companies, Hotels & Resorts Installation: New Installations, Retrofit Solutions, Smart Equipment Upgrades, DIY Systems |
| Companies Covered | Pentair plc, Fluidra S.A., Hayward Holdings, Inc., Zodiac Pool Systems, LLC, Waterco Limited, Maytronics, Sutro, Inc., WaterGuru, Inc., Ondilo SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pool Systems Market Trends and Innovations
Cloud-based predictive analytics are migrating from industrial HVAC applications into residential pool automation, compressing service technician dispatch frequencies and enabling subscription revenue models for platform providers.
Machine-learning water chemistry algorithms are displacing scheduled manual testing routines. Residential homeowners in Phoenix and Miami metropolitan areas are adopting smartphone-enabled chemical dosing at the fastest clip. This capability is displacing traditional pool service contractor relationships and concentrating chemical consumption decisions within OEM-controlled digital ecosystems.
EPA ENERGY STAR Version 4.0 pump specifications tighten hydraulic efficiency testing protocols. Equipment manufacturers must redesign impeller geometries and motor windings to maintain certification eligibility. The specification revision most acutely affects mid-tier pump OEMs lacking captive R&D infrastructure for rapid design iteration.
Subscription-based remote monitoring is unbundling from equipment purchase bundles. Pool builders in Florida and Texas are pivoting from margin-rich installation contracts toward recurring platform fees. This shift is most visible in new suburban developments where homebuilder volume agreements pre-install automation-ready infrastructure during construction phases.
Smart Pool Systems Market Segmentation

Segmentation in smart pool systems reveals how automation hardware, connectivity layers, and customer procurement modes create distinct margin profiles. Substitution pressures from adjacent home automation categories reshape competitive boundaries across each dimension.
Product Type:
Automation Devices face the sharpest substitute threat from general-purpose home automation controllers that pool owners repurpose for aquatic equipment.
- Automation Devices:Electromechanical controllers orchestrate pump scheduling, valve actuation, and lighting sequences through programmable relay logic. Demand concentrates in Florida and Texas suburban developments where homebuilders pre-wire automation-ready infrastructure during construction phases. EPA ENERGY STAR pump efficiency mandates accelerate bundled controller sales.
- Monitoring Systems:Sensor arrays track pH, chlorine, temperature, and flow rates with cloud telemetry. Arizona and Nevada residential clusters adopt smartphone-enabled chemical visibility fastest, displacing traditional weekly pool service contractor relationships.
- Water Treatment Solutions:Salt-chlorination cells and mineral sanitation modules integrate with circulation systems.
- Heating Controllers:Heat pump and solar thermal regulators manage energy transfer efficiency.
Automation Devices retain volume leadership; Monitoring Systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates enterprise-grade cloud infrastructure from entry-tier connectivity modules.
- IoT Solutions:Sub-GHz and Wi-Fi connectivity modules enable remote equipment command through FCC Part 15 unlicensed spectrum. Texas and Florida metropolitan areas show fastest adoption of low-cost wireless controllers in new pool construction.
- Cloud Computing:Predictive analytics platforms process sensor telemetry to compress service technician dispatch frequencies. Hotels and resorts in Arizona and Nevada deploy multi-pool management dashboards to centralize chemical monitoring across dispersed aquatic facilities.
- Artificial Intelligence:Machine-learning algorithms optimize chemical dosing schedules based on usage patterns and weather data.
- Mobile Applications:Smartphone interfaces provide homeowner visibility into pool status and equipment alerts.
IoT Solutions dominate unit shipments; Cloud Computing commands the highest revenue per installation.
End User:
Application maturity varies sharply between residential convenience-seekers and commercial compliance-driven operators.
- Residential Users:Suburban homeowners in Sun Belt states prioritize remote visibility and reduced chemical handling labor. Phoenix and Miami metropolitan clusters lead smartphone-enabled chemical dosing adoption.
- Commercial Establishments:Multi-tenant properties and fitness centers require automated compliance documentation for health department inspections.
- Pool Maintenance Companies:Service contractors deploy remote monitoring to optimize route efficiency and reduce truck rolls.
- Hotels & Resorts:Integrated property management systems demand centralized dashboards spanning multiple aquatic facilities.
Residential Users generate the largest installed base; Hotels & Resorts show the fastest software subscription attach rates.
Installation:
Customer type determines whether procurement flows through builder channels or retail self-service.
- New Installations:Homebuilder volume agreements in Florida and Texas pre-install automation-ready infrastructure during construction, locking in OEM-controller pairings before homeowner purchase decisions.
- Retrofit Solutions:Electrical panel upgrades to 240V variable-speed compatibility create installation friction in older Arizona and Nevada housing stock.
- Smart Equipment Upgrades:Component-level controller replacements extend legacy pump lifecycles.
- DIY Systems:Consumer-configurable kits bypass professional installer networks.
New Installations anchor manufacturer revenue; Retrofit Solutions face the steepest electrical infrastructure barriers.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal energy-efficiency mandates and provincial rebate programs are accelerating equipment replacement cycles across residential pool markets. Sun Belt states anchor North American demand concentration. European regulatory frameworks emphasize automated water quality compliance for commercial facilities.
United States
EPA ENERGY STAR Version 4.0 specifications are forcing pump redesigns among equipment manufacturers. FCC Part 15 governs wireless emissions from connected controllers nationwide. Texas and Florida metropolitan clusters show fastest adoption of pre-wired automation infrastructure in new suburban developments.
Canada
British Columbia and Ontario utility rebate programs for high-efficiency pool equipment remain underpenetrated relative to US saturation levels. Natural Resources Canada administers parallel efficiency certification tracks for pump imports. Toronto and Vancouver residential markets are accelerating salt-chlorination integration with variable-speed circulation systems.
Germany
CE marking requirements and EU energy labeling directives shape automation controller import compliance. REACH regulations constrain chemical sensor material composition for connected monitoring devices. Bavaria and Baden-Württemberg hotel chains are deploying centralized multi-pool management dashboards across dispersed wellness facilities.
Australia
State-level building efficiency codes in New South Wales and Queensland mandate minimum pump performance standards for new pool construction. The country's national communications regulator oversees wireless spectrum allocation for IoT-enabled controllers. Sydney and Melbourne metropolitan areas show fastest residential uptake of smartphone-enabled chemical dosing systems.
Spain
Coastal tourism infrastructure investments are driving commercial-grade demand for integrated property management systems. EU F-Gas Regulation affects heat pump refrigerant specifications for pool heating controllers. Barcelona and Málaga resort clusters are centralizing chemical monitoring across multiple aquatic facilities through cloud-based platforms.
Smart Pool Systems Market Competitive Landscape
Player mix skews toward diversified electromechanical conglomerates with captive distribution networks. Market structure exhibits tiered consolidation with premium positioning sustained through builder-channel lock-in. Three archetypes dominate: full-stack automation providers, specialized sensor manufacturers, and platform-agnostic connectivity module suppliers. Competitive moves center on backward integration into semiconductor sourcing and geographic expansion through homebuilder volume agreements.
Among North American-listed entities, Pentair plc and Hayward Holdings, Inc. occupy positions within the full-stack automation tier, while Fluidra S.A. represents European specialist concentration in controller hardware. These three exemplify divergent strategic postures: captive distribution leverage, R&D intensity in salt-chlorination convergence, and regional demand anchoring through specialized automation portfolios.
| Leading Market Players |
|---|
| Pentair plc |
| Fluidra S.A. |
| Hayward Holdings, Inc. |
| Zodiac Pool Systems, LLC |
| Waterco Limited |
| Maytronics |
| Sutro, Inc. |
| WaterGuru, Inc. |
| Ondilo SAS |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at East Asian microcontroller foundries directly shapes price floors for North American pump OEMs, compressing margins when wafer allocation tightens while concentrating supply leverage among vertically integrated automation providers. EPA ENERGY STAR compliance tiers create natural segmentation between certified premium controllers and uncertified economy alternatives, with UL 1081 testing costs acting as fixed barriers that protect incumbent pricing power.
Pricing Analysis
Certification level creates the primary spread between UL 1081-listed premium controllers and uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects bundling depth: premium tiers embed cloud analytics subscriptions, standard tiers cover hardware-only automation, and economy tiers address basic pump replacement. Pricing pressure stems from semiconductor cost pass-through limitations that prevent OEMs from recovering input volatility. Residential retrofit buyers show highest price sensitivity due to electrical upgrade friction, while homebuilder volume purchasers accept premium positioning for pre-wired new construction.
Supply Chain Analysis
Strategic stockpiling of rare-earth magnets and copper windings dominates inventory strategy among variable-speed pump manufacturers facing commodity volatility. Component sourcing draws from Taiwan and South Korea for microcontrollers, China for PCB assembly, and domestic US facilities for final controller integration. Permanent-magnet motor materials expose manufacturers to commodity price swings without contractual pass-through mechanisms. Distribution runs through pool-builder networks for new construction and specialty distributors for retrofit replacement.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA ENERGY STAR Version 4.0 specifications are compressing replacement cycles and forcing R&D-intensive redesigns, creating a high-growth disruption window where platform consolidation favors cloud-connected automation stacks over hardware-only incumbents.
For Market Incumbents: Secure captive semiconductor allocation through long-term foundry agreements to buffer against East Asian fabrication bottlenecks. Deepen backward integration into salt-chlorination cell production to capture recurring chemical revenue streams and defend against emerging sensor-only entrants. Channel control through pool-builder volume agreements remains the critical defensive lever.
For New Entrants and Emerging Players: ETL certification fast-track through parallel North American safety tracks offers lower-cost market entry than UL 1081 testing. Canadian provincial rebate programs in British Columbia and Ontario represent the most penetrable geography, with utility incentives for high-efficiency equipment still underexploited relative to US Sun Belt saturation. Target commercial multi-pool management dashboards for hotels and resorts, where centralized chemical monitoring commands software subscription attach rates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-agnostic connectivity module suppliers over full-stack hardware manufacturers, as cloud-based predictive analytics migrate from industrial HVAC into residential pool automation. Five-to-ten year viability hinges on subscription revenue model durability and firmware security hardening. The signal to watch is cybersecurity insurance coverage gaps for connected outdoor equipment, which would trigger regulatory intervention and reshape product liability structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Enables subscription revenue migration from hardware margins for OEMs serving Florida and Texas homebuilders. |
| Salt-Chlorination Backward Integration | Captures recurring chemical revenue and extends equipment replacement intervals through mineral sanitation convergence. |
| Sub-GHz Connectivity Module Launch | Leverages FCC Part 15 unlicensed spectrum expansion for lower-cost entry-tier automation controllers. |
| Canadian Rebate Program Partnership | Exploits underpenetrated British Columbia and Ontario utility incentives relative to US Sun Belt saturation. |
| Commercial Multi-Pool Dashboard Development | Addresses hotels and resorts requiring centralized chemical monitoring across dispersed aquatic facilities. |
Research Methodology
Initial hypotheses were tested against primary input from pool equipment OEM product managers, pool-builder procurement directors, and commercial facility maintenance supervisors and refined through secondary validation. Regulatory filings with EPA ENERGY STAR certification databases, FCC Part 15 equipment authorization records, and UL safety listing directories provided compliance benchmarking. Trade flow analysis through customs records and pump import statistics complemented SEC 10-K disclosures from listed automation providers. Bottom-up equipment shipment modeling and top-down construction spending allocation were triangulated for demand estimation.
Variance decomposition across technology layers, end-user segments, and installation modes shaped the analytical framework over the projection horizon. Segmentation dimensions included product type, connectivity protocol, customer procurement channel, and regional regulatory cluster. CAGRs were derived from replacement cycle acceleration under efficiency mandates and new construction penetration rates in Sun Belt metropolitan clusters. Semiconductor lead times and copper price trajectories fed directly into cost-side modeling.
Decision-makers should treat outputs as directional under assumptions of steady EPA enforcement intensity and stable wireless spectrum allocation; material deviation would warrant model refresh. Revision becomes warranted when cybersecurity liability rulings for consumer IoT devices cross litigation thresholds or when provincial rebate programs in Canada achieve US-equivalent penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Europe Cellular IoT Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
IoT Operating System Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
Global Pervasive Computing Technology Market
Internet of Things (IoT)
Industrial IoT Market
Internet of Things (IoT)
Global IoT in Automobile Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
IoT in BFSI Market