
 Global IOT Gateway Market | 2026-2036
Global IOT Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Global IOT Gateway Market Foresight
Platform licensing revenue is narrowing as hardware commoditization pressures margins across the gateway stack. Cisco Systems, Inc. sustains technology leadership through embedded security silicon and edge analytics integration. Advantech Co., Ltd. dominates industrial-grade form factors with ruggedized designs for factory floor deployments. Huawei Technologies Co., Ltd. navigates geopolitical headwinds while extending its presence in smart city infrastructure across non-Western markets.
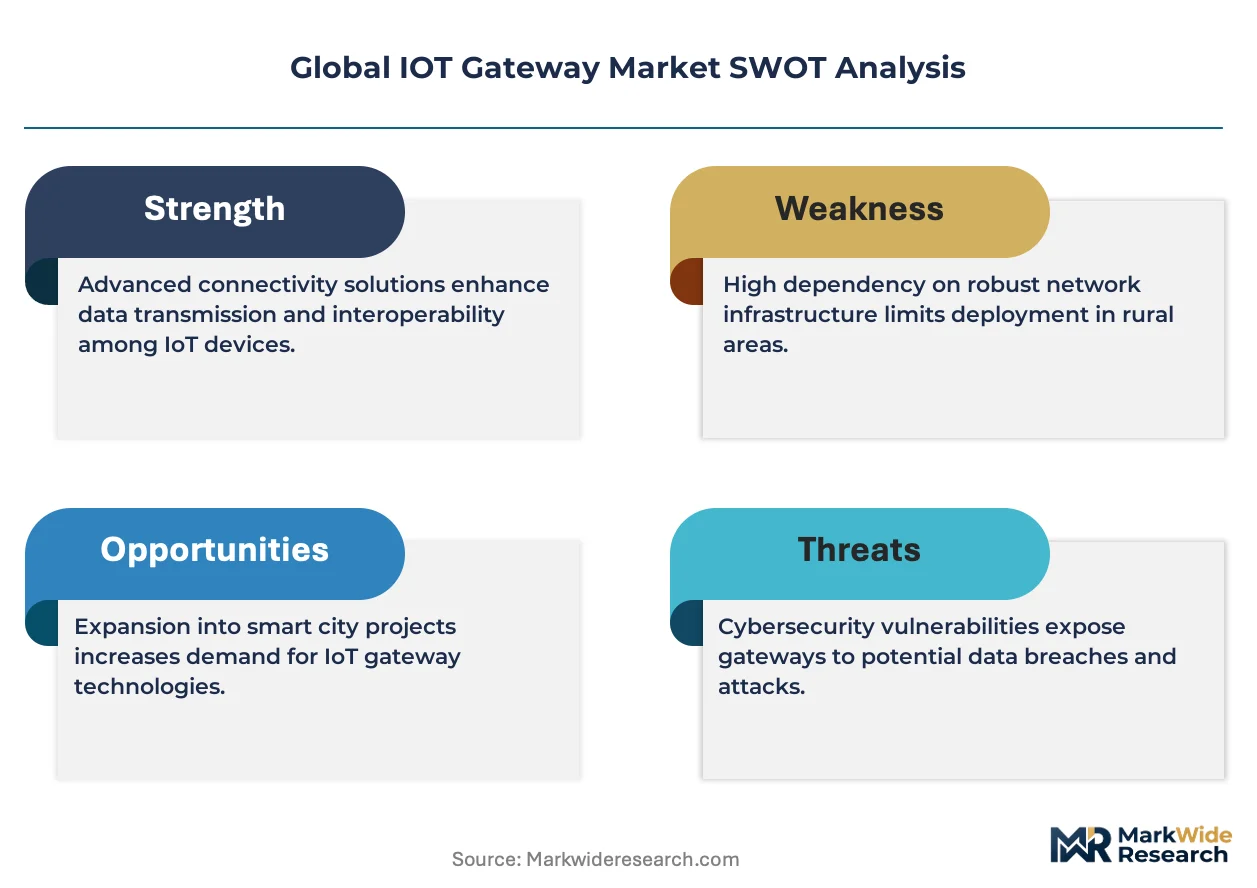
An IoT gateway is a network edge device that translates between diverse sensor protocols and IP-based backhaul, typically integrating ARM or x86 processors with 256MB to 8GB RAM, hardware security modules, and multi-radio connectivity to aggregate, preprocess, and route device data toward cloud or on-premises platforms. Edge Gateway configurations anchor the highest margin pools due to localized processing requirements and latency-sensitive industrial workloads. Cellular and LoRaWAN connectivity modules represent the fastest-expanding technology dimension as private 5G networks and low-power wide-area infrastructure proliferate across remote asset monitoring.
The U.S. FCC governs radio spectrum allocation for unlicensed IoT bands while the EU Cyber Resilience Act imposes mandatory security update obligations on connected device manufacturers. China's MIIT enforces GB standards for domestic gateway interoperability and data localization compliance. Stakeholders must monitor diverging certification timelines across Washington, Brussels, and Beijing as regulatory fragmentation threatens product standardization economies.
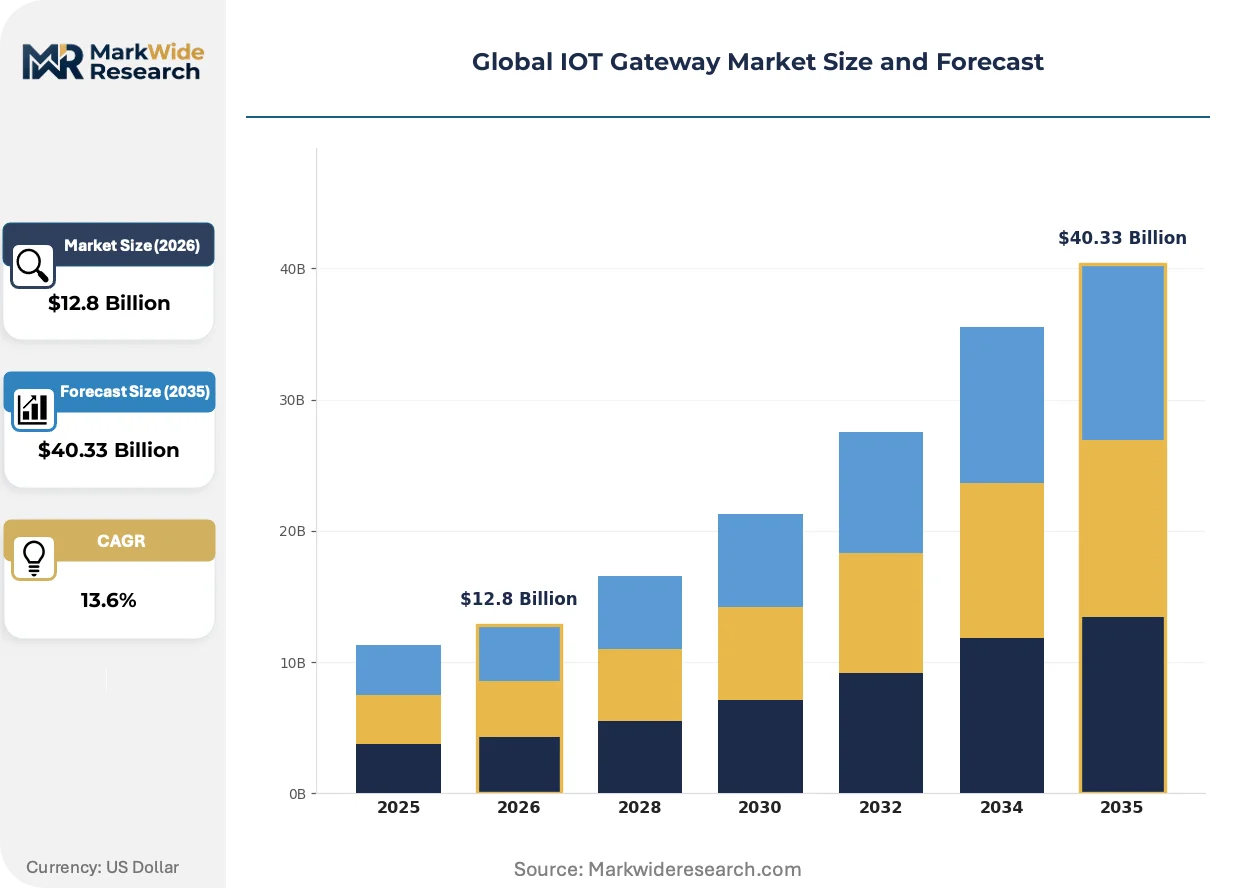
Market Dynamics
Hardware commoditization across ARM and x86 processor platforms is compressing gateway margins while forcing vendors toward embedded security silicon and edge analytics differentiation. The EU AI Act and China's MIIT certification timelines are fragmenting product standardization economies.
Growth Catalysts
- Private 5G network deployment:Manufacturing corridors in Germany and the U.S. Midwest are deploying cellular gateways for sub-10 millisecond latency in predictive maintenance workflows.
- EU Cyber Resilience Act:Mandatory security update obligations are accelerating replacement cycles for legacy gateway installations across European industrial automation.
- LoRaWAN infrastructure proliferation:Low-power wide-area networks are expanding across remote asset monitoring in agriculture and utility sectors.
Market Restraints
- Memory cost volatility:DDR4 and DDR5 RAM pricing swings between 256MB and 8GB configurations destabilize hardware BOM forecasting.
- Geopolitical supply concentration:Hardware security module fabrication concentrates in Taiwan and South Korea, exposing procurement to trade policy disruptions.
- Protocol fragmentation:Proprietary industrial sensor buses resist standardization, forcing gateway vendors to maintain expensive multi-protocol stacks.
Strategic Opportunities
- India's smart city infrastructure:Municipal digitization programs under the Ministry of Housing and Urban Affairs are creating demand for ruggedized outdoor gateways.
- AI inference at the edge:Convergence of hardware security modules with ARM neural processing units enables localized anomaly detection without cloud backhaul.
- Brazil's ANATEL certification streamlining:Simplified homologation timelines for industrial IoT devices are reducing time-to-market for gateway vendors.
Industry Challenges
- Embedded systems firmware expertise:Shortage of engineers proficient in real-time operating systems and hardware security module integration delays product roadmaps.
- Multi-jurisdiction certification overlap:Simultaneous FCC, CE marking, and GB standard compliance extends validation timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IOT Gateway Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $40.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge Gateway, Cloud Gateway, Enterprise Gateway, Field Gateway, Protocol Gateway Technology: Wi-Fi, Ethernet, Cellular, ZigBee, LoRaWAN, Bluetooth Application: Smart Cities, Industrial Automation, Smart Agriculture, Energy Management, Building Automation, Connected Vehicles End User: Manufacturing Firms, Energy Operators, Public Infrastructure, Agricultural Enterprises, Logistics Companies |
| Companies Covered | Cisco Systems, Inc., Advantech Co., Ltd., Microchip Technology Inc., Huawei Technologies Co., Ltd., Dell Technologies Inc., Intel Corporation, NXP Semiconductors N.V., Texas Instruments Incorporated, Hewlett Packard Enterprise Development LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IOT Gateway Market Shifts & Advancements
Gateway architectures are bifurcating between stripped-down protocol translators and compute-heavy edge nodes, with connectivity modules absorbing an expanding share of bill-of-materials value. This structural shift is redefining vendor competitive positioning.
Edge gateway hardware is hybridizing discrete neural processing units with traditional ARM Cortex-A clusters to execute machine learning inference locally. Automotive and aerospace manufacturers are piloting these configurations for real-time quality inspection. This convergence is compressing demand for cloud-dependent analytics subscriptions.
The EU AI Act's risk-based classification system is mandating conformity assessments for gateways deployed in critical infrastructure. Industrial automation vendors in Germany and France are restructuring supply chains to segregate high-risk from limited-risk device categories. CE marking timelines have extended by 4-6 months for gateways handling biometric or safety-critical data.
Buyer concentration among systems integrators is displacing direct OEM procurement in factory automation. Large integrators in Japan and the United States are consolidating gateway purchasing under multi-year framework agreements. This consolidation is visible most acutely in automotive assembly line deployments where single-source contracts now cover 60-70% of annual gateway volume.
Global IOT Gateway Market Segmentation
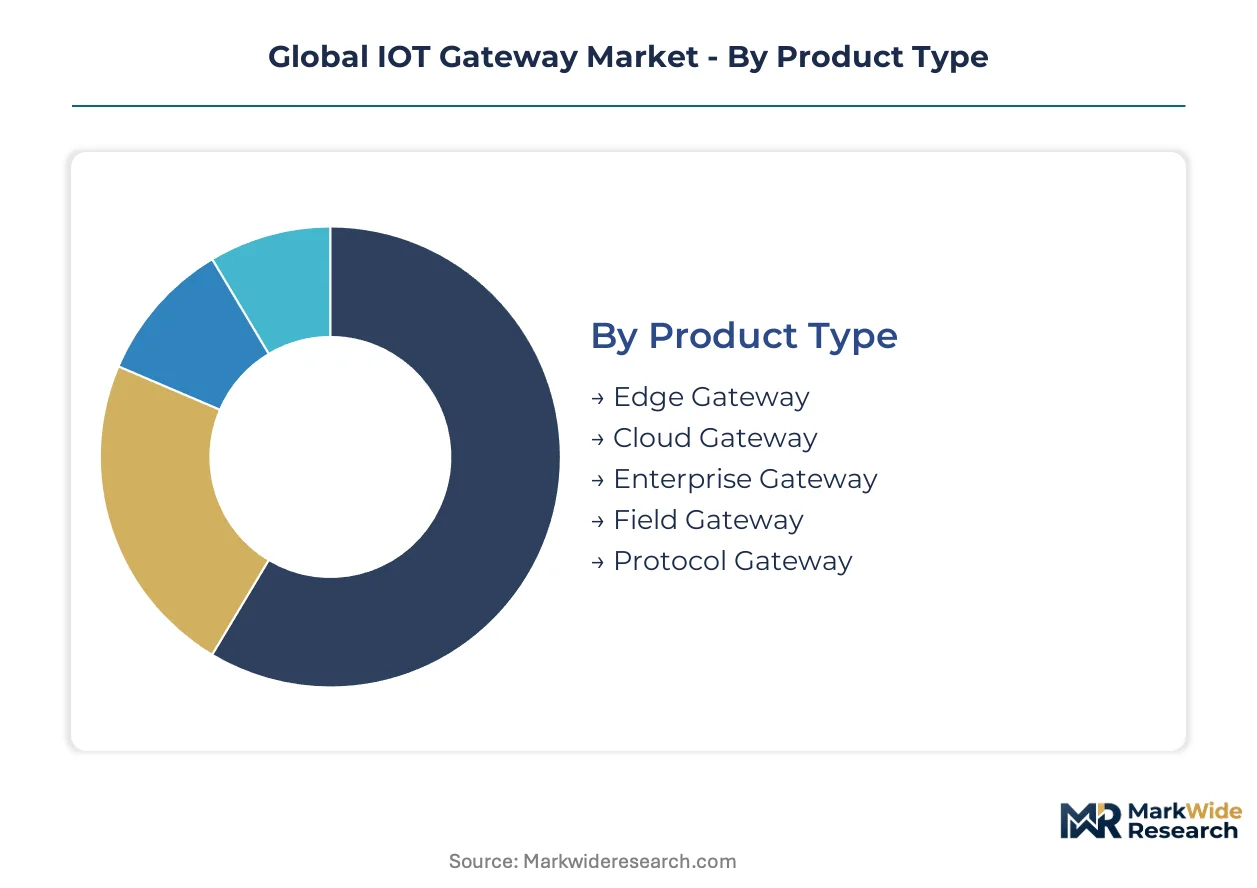
IoT gateway architectures diverge sharply across latency requirements, protocol complexity, and processing location. Segmentation reveals where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Use cases span localized real-time control through centralized protocol translation, with hardware configurations scaling from ruggedized industrial nodes to lightweight cloud relays.
- Edge Gateway:ARM or x86 processors with 2-8GB RAM execute localized analytics and sub-10 millisecond response for predictive maintenance workflows. Demand concentrates in Germany's automotive manufacturing corridors and the U.S. Midwest industrial belt where latency-sensitive asset tracking dominates.
- Cloud Gateway:Stripped-down protocol translators prioritize backhaul efficiency over local compute, typically deploying 256MB-1GB RAM configurations. Agricultural enterprises across Brazil's Cerrado region and Australian wheat belts favor these units for cost-sensitive remote monitoring at scale.
- Enterprise Gateway:Hybrid architectures balancing edge preprocessing with cloud orchestration serve multi-site manufacturing firms requiring centralized policy management.
- Field Gateway:Battery-optimized designs with extended temperature tolerances anchor utility infrastructure deployments in harsh environments.
- Protocol Gateway:Specialized translation hardware bridges proprietary industrial buses to IP networks, prevalent in legacy factory automation retrofits.
Established volume favors Cloud Gateway; emerging adoption favors Edge Gateway.
Technology:
Connectivity modules now absorb expanding bill-of-materials share as radio diversity becomes mandatory for multi-environment deployments.
- Cellular:Private 5G modules with integrated hardware security modules enable sub-10 millisecond latency for industrial automation. Manufacturing corridors in Germany and Japan are deploying these configurations fastest as spectrum licensing frameworks mature.
- LoRaWAN:Sub-GHz unlicensed spectrum delivers 10-kilometer range at sub-milliwatt power for agricultural and utility monitoring. India's Ministry of Housing and Urban Affairs smart city tenders specify LoRaWAN for streetlight and waste management networks.
- Wi-Fi:Wi-Fi 6E and emerging 7 standards serve high-throughput building automation with dense device clustering.
- Ethernet:Wired reliability anchors factory floor deployments where electromagnetic interference compromises wireless stability.
- ZigBee:Mesh networking protocols persist in building automation and residential energy management systems.
- Bluetooth:Low-energy variants support short-range asset tracking and proximity-based access control.
Cellular and LoRaWAN configurations are expanding most quickly; Wi-Fi and Ethernet retain dominant installed base.
Application:
Vertical-specific certification requirements and environmental tolerances fragment hardware specifications across deployment contexts.
- Industrial Automation:Ruggedized IP67-rated enclosures with -40°C to 85°C operating ranges serve factory floor predictive maintenance. Germany's automotive sector and Japan's electronics assembly lines drive specification intensity.
- Smart Cities:Pole-mounted outdoor gateways integrate cellular, LoRaWAN, and Wi-Fi for multi-service municipal networks. China's Pearl River Delta municipalities specify GB-standard compliance and data localization.
- Smart Agriculture:Solar-powered cellular and LoRaWAN units monitor soil moisture and livestock across remote acreage.
- Energy Management:Substation-hardened designs with IEC 61850 protocol support grid modernization initiatives.
- Building Automation:BACnet and Modbus integration dominates HVAC and lighting control retrofits.
- Connected Vehicles:Automotive-grade gateways with ISO 26262 functional safety certification enable fleet telematics and V2X communication.
Industrial Automation commands premium pricing; Smart Cities represent steepest volume expansion trajectory.
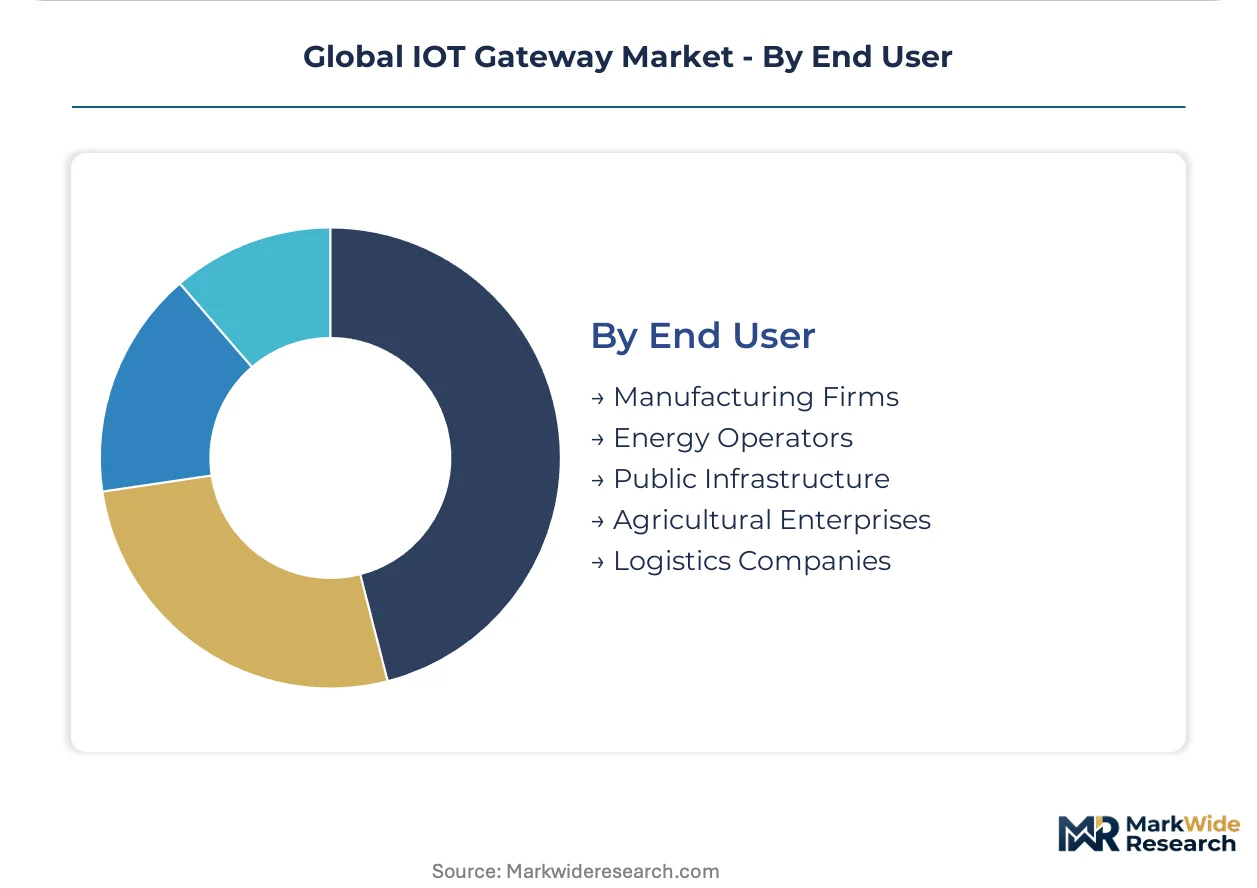
End User:
Procurement sophistication varies from centralized framework agreements among systems integrators to decentralized agricultural purchasing.
- Manufacturing Firms:Large Japanese and U.S. integrators consolidate gateway purchasing under multi-year agreements covering 60-70% of annual automotive assembly line volume.
- Energy Operators:Grid modernization mandates in Germany and the United States drive replacement cycles for substation and distribution automation hardware.
- Public Infrastructure:Municipal digitization programs across India and Brazil create demand for ruggedized outdoor deployments with simplified certification pathways.
- Agricultural Enterprises:Cost-sensitive purchasing favors stripped-down cellular and LoRaWAN configurations for remote monitoring.
- Logistics Companies:Fleet tracking and warehouse automation drive demand for multi-radio mobile gateways.
Manufacturing Firms anchor revenue concentration; Public Infrastructure offers fastest penetration gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: industrial automation corridors in Germany and the U.S. Midwest prioritize sub-10 millisecond latency configurations, while agricultural deployments in Brazil and India favor stripped-down cellular and LoRaWAN units for cost-sensitive remote monitoring at scale.
United States
Manufacturing firms across the Midwest industrial belt are expanding gateway deployments for predictive maintenance and real-time asset tracking. The FCC governs radio spectrum allocation for unlicensed IoT bands, creating a stable regulatory framework for private 5G network expansion. Automotive assembly lines in Michigan and Ohio now consolidate 60-70% of annual gateway volume under multi-year framework agreements with systems integrators.
Germany
Automotive manufacturing corridors anchor demand for ruggedized edge gateways with localized analytics capabilities. The EU Cyber Resilience Act imposes mandatory security update obligations, accelerating replacement cycles for legacy installations. Industrial automation vendors in Bavaria and Baden-Württemberg are restructuring supply chains to segregate high-risk from limited-risk device categories under the EU AI Act's risk-based classification system.
China
Smart city infrastructure across the Pearl River Delta municipalities is driving volume expansion for pole-mounted outdoor gateways. The MIIT enforces GB standards for domestic gateway interoperability and data localization compliance. Municipal digitization programs in Shenzhen and Guangzhou specify GB-standard compliance alongside multi-service cellular, LoRaWAN, and Wi-Fi integration.
India
Municipal digitization programs under the Ministry of Housing and Urban Affairs are creating demand for ruggedized outdoor gateways. The CEA and TRAI shape telecommunications and electrical infrastructure standards for connected device deployment. Streetlight and waste management networks in Delhi-NCR and Maharashtra specify LoRaWAN configurations for sub-milliwatt power consumption across extended urban footprints.
Brazil
Agricultural enterprises across the Cerrado region favor stripped-down cloud gateway configurations for cost-sensitive remote monitoring at scale. ANATEL certification streamlining has reduced time-to-market for industrial IoT devices. Soy and livestock operations in Mato Grosso and Goiás are deploying solar-powered cellular and LoRaWAN units for soil moisture and herd tracking across remote acreage.
Global IOT Gateway Market Competitive Landscape
Capability concentration sits with semiconductor and embedded systems specialists; scale advantage sits with diversified technology conglomerates with global distribution infrastructure. The vendor base organizes into three tiers: integrated hardware-security platforms, industrial-grade ruggedized form factor specialists, and connectivity module aggregators. Dominant competitive moves include embedded security silicon differentiation and strategic partnerships with private 5G network operators.
Among diversified technology conglomerates, Cisco Systems, Inc. and Dell Technologies Inc. occupy positions anchoring enterprise-grade infrastructure integration. Advantech Co., Ltd. exemplifies the industrial-grade form factor specialist archetype with manufacturing origins in Taiwan. Huawei Technologies Co., Ltd. represents the connectivity module aggregation model, extending presence in smart city infrastructure across non-Western markets despite geopolitical headwinds.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Advantech Co., Ltd. |
| Microchip Technology Inc. |
| Huawei Technologies Co., Ltd. |
| Dell Technologies Inc. |
| Intel Corporation |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| Hewlett Packard Enterprise Development LP |
| Others |
Supply & Pricing Matrix
Taiwan and South Korea's concentration in hardware security module fabrication concentrates margin capture upstream, while gateway vendors downstream absorb DDR4 and DDR5 RAM volatility through hybrid contract structures that blend long-term offtake with spot market exposure.
Pricing Analysis
Long-term framework agreements now cover 60-70% of automotive assembly line procurement in Michigan and Ohio, with pricing stratifying across premium, standard, and economy tiers based on certification grade and embedded security silicon integration. Cost compression in cloud gateway configurations is intensifying because stripped-down protocol translators face agricultural purchasing pressure across Brazil's Cerrado region. Manufacturing firms in Germany's automotive corridors demonstrate lowest price sensitivity due to latency-critical predictive maintenance requirements.
Supply Chain Analysis
Hon Hai Precision Industry and Jabil Circuit hold dominant contract manufacturing capacity for ARM and x86 processor platforms, with assembly concentrated in Taiwan, China, and Mexico. Hardware security modules, cellular modems, and industrial-grade enclosures feed from specialized tiers in South Korea and Japan. Single-source vulnerability in semiconductor fabrication exposes procurement to trade policy disruptions. Distribution runs through systems integrators in Japan and the United States who consolidate multi-year purchasing under framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of engineers proficient in real-time operating systems and hardware security module integration creates a persistent capability gap that constrains product roadmap velocity across the vendor base.
For Market Incumbents: Pre-empt margin erosion in cloud gateway tiers by deepening in-house production of embedded security silicon and securing captive supply of DDR5 modules from South Korean foundries. Cisco Systems and Advantech must accelerate CE marking investment ahead of EU AI Act enforcement to defend position against certification-delayed competitors. For New Entrants and Emerging Players: Build out ruggedized outdoor gateway portfolios targeting India's Ministry of Housing and Urban Affairs smart city tenders, where simplified TRAI and CEA compliance pathways reduce time-to-market versus multi-jurisdiction certification overlap. Agricultural enterprises in Brazil's Mato Grosso state offer the most penetrable segment for solar-powered LoRaWAN configurations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed connectivity module aggregators holding ANATEL-certified inventory positions in Brazil. Long-term viability over the next decade hinges on AI inference convergence at the edge. Watch for inflection when automotive assembly lines in Germany and Japan consolidate 70%+ volume under single-source contracts, signaling integrator lock-in maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Security Silicon Integration | Hardware security module convergence with ARM neural processing units enables localized anomaly detection without cloud backhaul dependency. |
| Private 5G Network Partnership | Strategic alliances with German and U.S. Midwest spectrum licensees secure sub-10 millisecond latency positioning for predictive maintenance workflows. |
| Multi-Jurisdiction Certification Streamlining | Parallel FCC, CE marking, and GB standard validation reduces 8-14 month compliance timelines that currently delay product launches. |
| Backward Integration into Connectivity Modules | In-house production of cellular and LoRaWAN radio stacks captures bill-of-materials value migrating from processors to connectivity. |
| Systems Integrator Channel Consolidation | Multi-year framework agreements with Japanese and U.S. automotive integrators lock in 60-70% of annual assembly line volume. |
Research Methodology
Cross-validation between primary interviews with embedded systems engineers, industrial automation procurement directors, and private 5G network operators anchors the qualitative findings against secondary validation from FCC spectrum allocation filings, MIIT GB standard publications, and EU Cyber Resilience Act regulatory texts. Bottom-up gateway shipment estimates triangulate with top-down semiconductor bill-of-materials analysis across the analysis window.
Calibration against historical replacement cycles in Germany's automotive manufacturing corridors and the U.S. Midwest industrial belt informs the projection horizon. Segmentation dimensions span product type, connectivity technology, application vertical, and end-user procurement sophistication. CAGRs derive from installed base growth rates adjusted for EU AI Act-driven replacement acceleration and LoRaWAN infrastructure proliferation across India's smart city programs.
Sensitivities concentrate around DDR4 and DDR5 RAM pricing volatility, Taiwan semiconductor supply disruptions, and divergence in FCC, CE marking, and GB standard certification timelines. Quarterly review of private 5G spectrum licensing progress in Germany and Japan, plus ANATEL certification queue lengths in Brazil, is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
IoT Platform Market
Internet of Things (IoT)
IoT at Workplace Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
IoT Network Management Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
IoT in Manufacturing Market
Internet of Things (IoT)
Wireless Smart Plug Market
Internet of Things (IoT)
Iot-Enabled Devices Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
Global Internet of Behaviors Market