
 Europe Massive IoT Market | 2026-2036
Europe Massive IoT Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Massive IoT Market Insights
The EU Cybersecurity Act is consolidating the cost-of-entry calculus for device vendors seeking CE marking under harmonized standards. Siemens leverages its industrial software stack to anchor factory-floor sensor networks across German manufacturing zones. STMicroelectronics sustains R&D intensity in ultra-low-power microcontrollers that dominate European LPWAN module supply. NXP Semiconductors N.V. competes through secure-element integration that meets ETSI EN 303 645 baseline requirements for IoT cybersecurity certification.
Massive IoT denotes large-scale deployments of low-complexity, low-power connected devices transmitting small data payloads at extended intervals over wide-area networks, typically operating on battery life exceeding ten years and unit costs below five euros. Its primary commercial purpose is enabling pervasive monitoring and control across distributed physical infrastructure without dedicated local computing. LPWAN technology leads European connectivity adoption for smart metering and agricultural soil monitoring where cellular power budgets prove prohibitive. Cloud-based deployment captures margin pools from municipal buyers seeking centralized fleet management, while edge computing segments gain traction in industrial automation requiring sub-second actuator response.
ETSI develops harmonized standards under the EU Radio Equipment Directive that govern spectrum efficiency and interoperability for unlicensed IoT devices. ECHA tracks restricted substances under REACH that influence printed circuit board material selection and battery chemistry compliance across European supply chains. The EU AI Act introduces risk-classification obligations for IoT systems incorporating automated decision-making that will reshape product liability and insurance structures. Stakeholders must monitor whether the European Commission extends cybersecurity certification from consumer devices to industrial sensor classes, as this would force retrofit investments across installed bases.
Market Dynamics
The EU Cybersecurity Act is compressing vendor economics by mandating third-party certification for CE marking, forcing sensor manufacturers to absorb compliance costs or exit unlicensed spectrum segments entirely.
Growth Catalysts
- Smart Metering Mandates:France and Italy have enacted binding deployment targets for next-generation electricity meters, creating guaranteed offtake for LPWAN module suppliers through 2030.
- REACH Compliance Innovation:ECHA restrictions on lead and cadmium in batteries are accelerating solid-state lithium primary cell adoption, extending device lifecycles beyond fifteen years in agricultural monitoring applications.
- German Industrial Corridors:Manufacturing clusters across Bavaria and Baden-Württemberg are standardizing on sensor-to-cloud architectures for predictive maintenance, generating concentrated demand for ultra-low-power connectivity.
Market Restraints
- Spectrum Fragmentation:Unlicensed sub-GHz band plans diverge between Germany, France, and the Netherlands, forcing module vendors to maintain multiple regional SKUs and inflating inventory carrying costs.
- Cellular Module Substitution:NB-IoT price erosion by Asian semiconductor houses is squeezing European LPWAN pure-plays in smart parking and environmental sensing where latency tolerance permits cellular alternatives.
- ETSI Certification Bottlenecks:Harmonized standard EN 303 645 testing capacity at notified bodies remains constrained, extending time-to-market for new device introductions by four to six months.
Strategic Opportunities
- Polish Agricultural Expansion:Large-scale farming cooperatives in Greater Poland Voivodeship remain undersupplied with soil moisture and livestock tracking systems, presenting first-mover advantages for LPWAN deployers.
- EU Green Deal Integration:Carbon accounting requirements under the Corporate Sustainability Reporting Directive are compelling industrial buyers to install energy monitoring sensors, creating regulatory-tied demand.
- Edge-AI Convergence:TinyML inference on microcontrollers is converging with LPWAN backhaul to enable localized anomaly detection in Nordic district heating networks without cloud dependency.
Industry Challenges
- Embedded Security Engineering Scarcity:European universities produce insufficient firmware developers proficient in ETSI EN 303 645 implementation, forcing vendors to recruit from automotive cybersecurity pools at premium compensation.
- Legacy SCADA Integration:Industrial automation buyers in Belgium and northern Italy require protocol translation layers between Modbus-based plant systems and modern MQTT-over-LPWAN architectures, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Massive IoT Market |
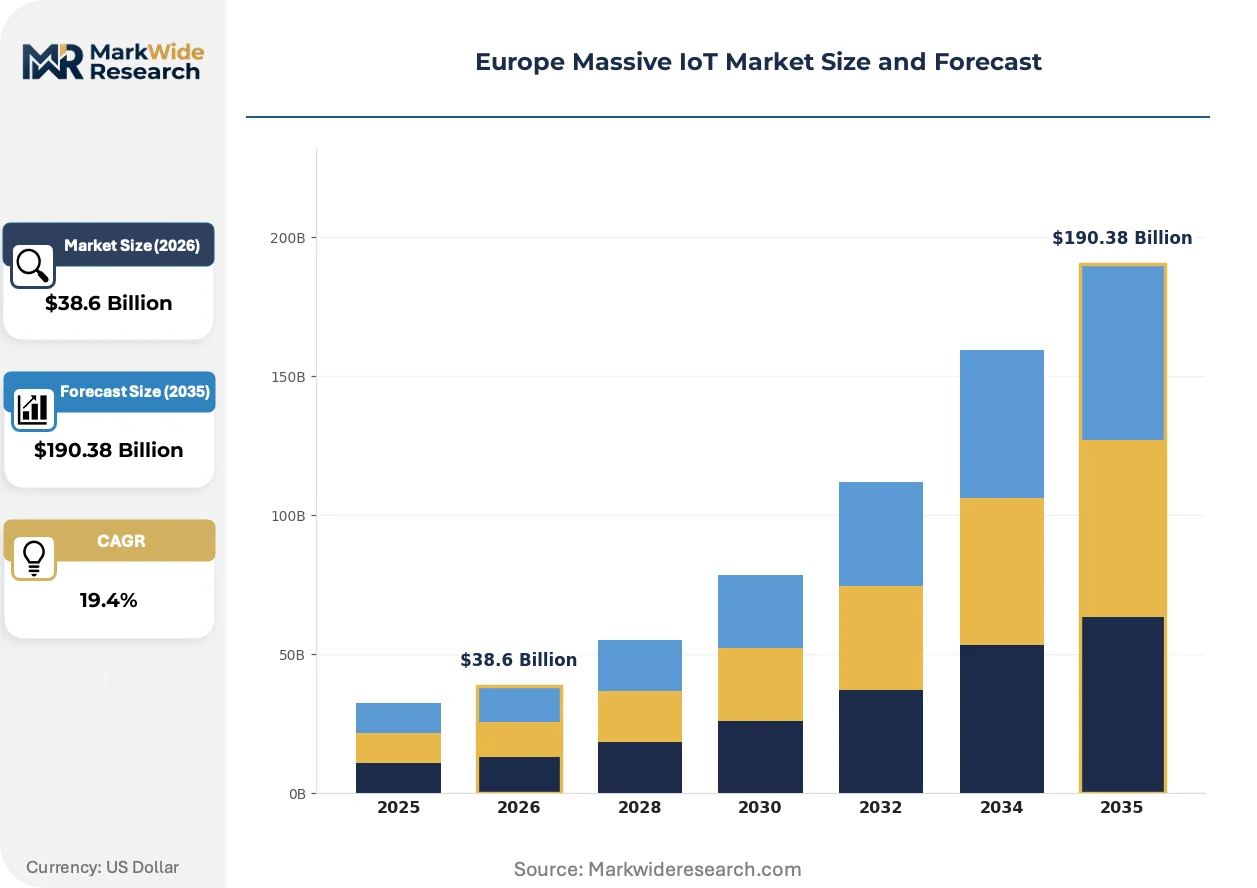
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $190.38 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, Industrial Automation, Connected Vehicles, Wearable Devices End User: Manufacturers, Transport, Healthcare, Agriculture Technology: LPWAN, Cellular, Wi-Fi, Bluetooth Deployment: On-premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Siemens, STMicroelectronics, SAP SE, Robert Bosch GmbH, Schneider Electric, NXP Semiconductors N.V., Vodafone Group, Atos SE, Deutsche Telekom, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Massive IoT Market Trends and Innovations
Radio hardware, power management silicon, and cryptographic modules are fusing into single-chip solutions that slash bill-of-materials complexity while satisfying the EU Cybersecurity Act's baseline requirements.
Ultra-low-power system-on-chip designs are converging with integrated secure elements to eliminate discrete component count in sensor nodes. German smart city integrators are adopting these monolithic platforms for streetlight monitoring deployments. The structural consequence is converging with margin compression for module assemblers who previously differentiated through firmware customization.
The EU AI Act's risk-classification framework is imposing documentation obligations on IoT systems with automated decision-making capabilities. Industrial sensor vendors must now maintain technical files demonstrating human oversight mechanisms for factory-floor deployments. Belgian and Dutch manufacturing technology buyers are demanding pre-certified edge devices to avoid liability exposure.
Municipal procurement departments are consolidating sensor fleet management under centralized cloud platforms rather than siloed departmental contracts. French water utilities and Spanish waste management authorities are leading this aggregation, displacing fragmented purchasing that previously favored regional system integrators. The shift is most visible in German smart city tenders where single-vendor platform mandates now predominate.
Europe Massive IoT Market Segmentation
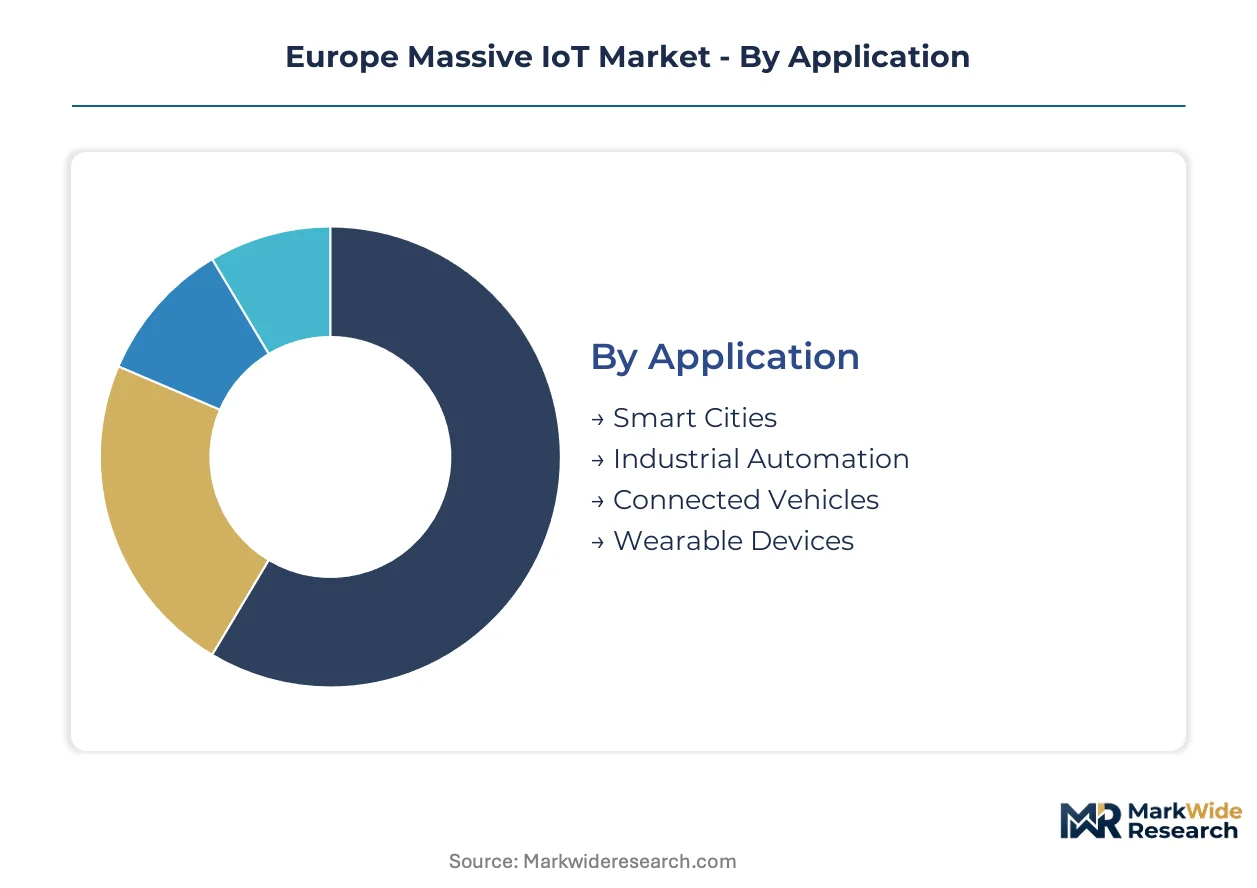
Massive IoT deployments across Europe exhibit divergent technical requirements based on payload frequency, power constraints, and regulatory exposure. Buyers select technology stacks and deployment architectures that align with ETSI certification obligations and the EU Cybersecurity Act's risk-classification tiers.
Application:
Municipal and industrial procurement teams prioritize use-case-specific latency tolerance and sensor density when allocating connectivity budgets.
- Smart Cities:Streetlight control, waste bin fill-level monitoring, and parking occupancy detection dominate municipal RFPs. French water utilities and German transport authorities are consolidating multi-service sensor fleets under single-vendor platform contracts to reduce interoperability overhead.
- Industrial Automation:Predictive maintenance vibration sensors and energy monitoring nodes absorb the majority of LPWAN module shipments in Bavarian and Baden-Württemberg manufacturing corridors. REACH-compliant battery chemistries are extending maintenance intervals beyond fifteen years in these deployments.
- Connected Vehicles:Fleet telematics and cold-chain monitoring for pharmaceutical distribution rely on cellular fallback where LPWAN coverage gaps persist on cross-border routes.
- Wearable Devices:Occupational safety tags in Dutch logistics hubs and Belgian construction sites incorporate ETSI EN 303 645-certified secure elements for workforce location tracking.
Smart Cities leads on scale; Industrial Automation leads on momentum.
End User:
Customer sophistication varies sharply across sectors, with industrial buyers demanding pre-certified edge devices while agricultural purchasers prioritize unit economics.
- Manufacturers:German automotive suppliers and Italian machinery producers are standardizing sensor-to-cloud architectures for OEE monitoring, driving concentrated demand for ultra-low-power microcontrollers with integrated secure elements.
- Transport:Dutch port authorities and Spanish rail operators deploy environmental monitoring and asset tracking across multimodal corridors, requiring hybrid connectivity that switches between LPWAN and cellular based on location.
- Healthcare:Remote patient monitoring and medical cold-chain tracking in France and Belgium face GDPR and MDR compliance layers that elongate procurement cycles.
- Agriculture:Polish and Romanian farming cooperatives are adopting soil moisture and livestock tracking systems where fifteen-year battery life offsets higher upfront module costs.
Manufacturers captures the largest addressable spend; Agriculture climbs the fastest as EU Green Deal carbon accounting mandates propagate.
Technology:
Spectrum allocation and certification cost structures determine technology selection, with unlicensed bands facing mounting regulatory scrutiny under the Radio Equipment Directive.
- LPWAN:LoRaWAN and Sigfox deployments dominate smart metering in France and Italy, where binding installation targets guarantee module offtake through 2030. ETSI harmonized standards for sub-GHz spectrum efficiency are tightening interoperability requirements.
- Cellular:NB-IoT price erosion by Asian semiconductor houses is compressing margins for European module vendors in smart parking and environmental sensing where latency tolerance permits licensed spectrum alternatives.
- Wi-Fi:High-throughput indoor applications in Belgian and Dutch industrial facilities leverage existing enterprise infrastructure for non-critical sensor backhaul.
- Bluetooth:Short-range mesh networks serve asset tracking in German automotive assembly plants where device density exceeds LPWAN gateway capacity.
LPWAN leads on installed base; Cellular gains share fastest as operators bundle connectivity with cloud platform subscriptions.
Deployment:
Architecture choice reflects data sovereignty requirements and response-time constraints, with the EU AI Act imposing documentation obligations on systems with automated decision-making.
- On-premises:Belgian and northern Italian industrial automation buyers retain SCADA-integrated sensor networks for sub-second actuator response, requiring protocol translation layers between Modbus plant systems and modern MQTT architectures.
- Cloud-based:French water utilities and Spanish waste management authorities are aggregating fleet management under centralized platforms, displacing fragmented departmental purchasing that previously favored regional system integrators.
- Hybrid:German smart city tenders increasingly mandate edge preprocessing with cloud analytics, balancing latency requirements against municipal IT resource constraints.
- Edge Computing:TinyML inference on microcontrollers is converging with LPWAN backhaul in Nordic district heating networks, enabling localized anomaly detection without cloud dependency.
Cloud-based deployment leads on new contract volume; Edge Computing shows the steepest expansion trajectory as the EU AI Act's risk-classification framework drives on-device processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massive IoT infrastructure first achieved commercial scale in European industrial corridors, where German manufacturing automation and French utility networks established the template for sensor-to-cloud architectures that now propagate across the continent.
Germany
Bavarian and Baden-Württemberg manufacturing clusters drive concentrated demand for predictive maintenance sensors and energy monitoring nodes. The EU Cybersecurity Act's CE marking requirements under harmonized standards compress vendor economics, forcing compliance investments or market exit. Siemens anchors factory-floor sensor networks across these zones through its industrial software stack integration.
France
Binding smart metering mandates for next-generation electricity meters guarantee LPWAN module offtake through 2030. ETSI EN 303 645 certification bottlenecks at notified bodies extend time-to-market by four to six months. Paris-based water utilities consolidate multi-service sensor fleets under single-vendor platform contracts to reduce interoperability overhead.
Netherlands
Port authorities and logistics hubs deploy environmental monitoring and asset tracking across multimodal corridors requiring hybrid connectivity. REACH restrictions on lead and cadmium accelerate solid-state lithium primary cell adoption. Rotterdam and Amsterdam smart city integrators adopt monolithic radio-power-crypto chip platforms for streetlight monitoring.
Italy
Northern industrial automation corridors in Lombardy and Emilia-Romagna standardize on sensor-to-cloud architectures for OEE monitoring. The Radio Equipment Directive governs spectrum efficiency for unlicensed sub-GHz deployments. Legacy Modbus-based plant systems require protocol translation layers to modern MQTT-over-LPWAN architectures, complicating deployment timelines.
Poland
Greater Poland Voivodeship farming cooperatives remain undersupplied with soil moisture and livestock tracking systems, presenting first-mover advantages. EU Green Deal carbon accounting under the Corporate Sustainability Reporting Directive compels agricultural buyers toward energy monitoring installations. Fifteen-year battery life offsets higher upfront module costs in these deployments.
Europe Massive IoT Market Competitive Landscape
The competitive structure tilts toward industrial conglomerates with captive software ecosystems. Semiconductor specialists and telecommunications operators occupy secondary tiers. Three archetypes dominate: diversified industrial technology groups with vertical software stacks, pure-play connectivity module vendors, and carrier-led platform integrators. M&A activity concentrates on firmware competency acquisition, while strategic partnerships between sensor manufacturers and cloud hyperscalers reshape municipal procurement channels.
Within the industrial technology tier, Siemens and Robert Bosch GmbH exemplify conglomerates leveraging factory automation heritage to anchor sensor network deployments. STMicroelectronics and NXP Semiconductors N.V. occupy positions in the semiconductor specialist tier, with the latter representing secure-element integration approaches that meet baseline cybersecurity certification requirements. Among carrier-led platform integrators, Vodafone Group and Deutsche Telekom sit within the telecommunications operator archetype, bundling connectivity with centralized fleet management subscriptions.
| Leading Market Players |
|---|
| Siemens |
| STMicroelectronics |
| SAP SE |
| Robert Bosch GmbH |
| Schneider Electric |
| NXP Semiconductors N.V. |
| Vodafone Group |
| Atos SE |
| Deutsche Telekom |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon accounting mandates under the Corporate Sustainability Reporting Directive gate qualified supply for premium-tier LPWAN module vendors while excluding uncertified competitors from municipal procurement channels. Buyers in German industrial corridors and French utility networks now demand REACH-compliant battery chemistries and ETSI EN 303 645-certified secure elements, bifurcating the supplier base into compliance-qualified tiers with corresponding pricing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates module procurement, with differentiation driven by certification grade (ETSI EN 303 645 baseline versus enhanced tier) and volume scale. Cost compression in the economy tier is intensifying because Asian semiconductor houses erode NB-IoT pricing. Agricultural cooperatives in Poland and Romania exhibit highest price sensitivity, while German automotive suppliers prioritize certified secure-element integration over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Siemens and Robert Bosch GmbH, while distributor networks serve fragmented municipal purchasers. Manufacturing concentrates in Germany, the Netherlands, and Taiwan for radio-frequency silicon and secure-element integration. Supply chains rest on lithium primary cells, sub-GHz transceiver silicon, and cryptographic modules. Single-source vulnerability in ETSI-certified testing capacity at notified bodies extends procurement lead times. Distribution runs through specialized industrial automation distributors and carrier-led platform integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polish agricultural IoT deployment lags German industrial adoption by approximately five years on certification compliance, creating a geographic-arbitrage window for vendors with pre-certified module platforms.
For Market Incumbents: Anticipate NB-IoT price erosion from Asian semiconductor houses by accelerating backward integration into secure-element silicon design. Consolidate firmware engineering capacity through targeted recruitment from automotive cybersecurity pools to defend against ETSI EN 303 645 certification bottlenecks that constrain competitor time-to-market.
For New Entrants and Emerging Players: Begin with Polish Greater Poland Voivodeship farming cooperatives, where soil moisture and livestock tracking systems remain undersupplied relative to EU Green Deal carbon accounting requirements. Partner with carrier-led platform integrators like Deutsche Telekom or Vodafone Group to bypass fragmented municipal procurement channels.
For Investors and Strategic Acquirers: Roll-up economics work for firmware-specialist acquisition targets because ETSI certification complexity creates durable competitive moats around embedded security engineering capability. Monitor whether the European Commission extends cybersecurity certification from consumer devices to industrial sensor classes as the signal for forced retrofit investment cycles across installed bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Integration | ETSI EN 303 645 certification locks in premium-tier pricing for module vendors supplying German automotive corridors. |
| Backward Integration into Silicon | In-house production of ultra-low-power microcontrollers defends margin position against Asian NB-IoT price erosion. |
| Carrier Platform Partnership | Vodafone Group and Deutsche Telekom bundle LPWAN connectivity with cloud fleet management, displacing regional system integrators. |
| Polish Agricultural Expansion | First-mover deployment in Greater Poland Voivodeship captures EU Green Deal-mandated carbon accounting sensor demand. |
| ETSI Certification Pre-Investment | Early compliance with harmonized standards under the Radio Equipment Directive accelerates time-to-market for French smart metering mandates. |
Research Methodology
Multiple input streams — executive interviews with industrial automation procurement leads, regulatory affairs specialists at semiconductor vendors, and municipal IoT program managers — were reconciled against ETSI standard documentation, ECHA REACH restriction updates, and EU Cybersecurity Act implementation guidance. Secondary validation drew from SEC filings of listed connectivity module vendors, customs data on LPWAN component trade flows, and notified body certification registers. Bottom-up module shipment estimates were triangulated with top-down connectivity revenue analysis across the analysis window.
Data-stream reconciliation anchored the analytical framework across technology, application, end user, and deployment architecture dimensions, with additional segmentation by regulatory compliance tier. CAGRs were derived from installed base growth curves and replacement cycle assumptions for battery-powered sensor nodes. Forecast inputs incorporated ETSI certification capacity constraints, EU AI Act risk-classification implementation timelines, and NB-IoT pricing trajectory assumptions from Asian semiconductor competitive dynamics.
Several conditions sit outside the modeled scope, including potential extension of cybersecurity certification to industrial sensor classes, unanticipated spectrum reallocation under the Radio Equipment Directive, and geopolitical disruption of lithium primary cell supply chains. Forecasts reflect assumptions about regulatory implementation pace and technology substitution thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
IoT Device Management Market
Internet of Things (IoT)
North America Narrowband-Internet of Things (NB-IoT) Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
5G IIOT Market
Internet of Things (IoT)
Internet of Things in BFSI Market
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
IoT in Energy Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Internet of Everything Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Global IoT in Smart Cities Market