
 North America Smart Factory Market | 2026-2036
North America Smart Factory Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Factory Market Analytics
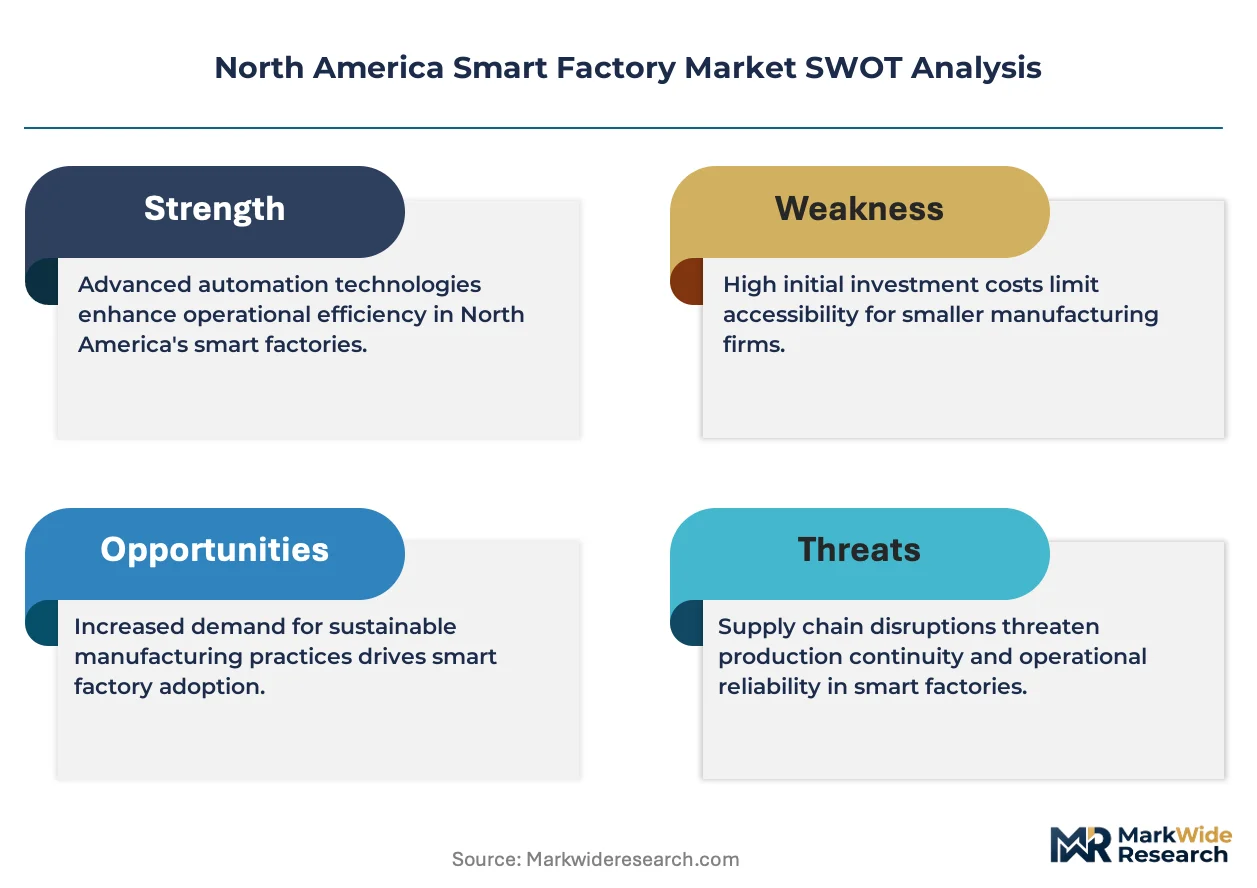
The North America smart factory landscape is recalibrating around a stark divergence between premium AI-native architectures and commodity automation retrofits. Siemens AG leverages deep vertical integration in digital twin software to anchor premium positioning across automotive OEMs. Rockwell Automation Inc. competes through dense distributor networks and PLC-to-cloud connectivity stacks that dominate mid-tier food and beverage plants. Honeywell International Inc. specializes in process safety layers that differentiate its offering for chemical and pharmaceutical batch operations.
A smart factory integrates cyber-physical production systems where IoT sensors, edge computing nodes, and AI-driven analytics orchestrate real-time manufacturing decisions with sub-millisecond latency requirements. Its primary purpose is to minimize unplanned downtime, optimize energy intensity per unit output, and enable lot-size-one customization without throughput sacrifice. Robotics and automation technologies currently lead capital deployment as labor scarcity forces tangible substitution investments across metal fabrication and electronics assembly. Predictive maintenance applications are expanding fastest in process industries where sensor density on rotating equipment already exceeds threshold levels for algorithmic failure prediction. Quality control segments in pharmaceuticals retain the deepest margin pools because FDA validation requirements create sticky switching costs for vision inspection and track-and-trace systems.
NIST's Cybersecurity Framework and the EPA's Greenhouse Gas Reporting Program shape smart factory demand by mandating secure data architectures and emissions monitoring granularity that legacy plants cannot satisfy without digital overhaul. Canada's Standards Council and Mexico's CONAMER coordinate cross-border equipment certification that determines market access for integrated line builders serving North American automotive final assembly. Stakeholders must monitor how OSHA's evolving machine guarding standards for collaborative robots will alter workstation design specifications and retrofit timelines.
Market Dynamics
Automotive OEMs across Michigan, Ohio, and Ontario are forcing capital reallocation toward digital twin architectures as NIST interoperability standards and Canadian Supercluster funding compress deployment timelines for legacy plant retrofits.
Growth Catalysts
- NIST Cybersecurity Framework:Mandatory secure data architectures for federal contractors are accelerating OT/IT convergence investments across Great Lakes metal fabrication facilities.
- Edge computing nodes:Sub-millisecond latency requirements for collaborative robotics are driving sensor density upgrades in Detroit-Windsor automotive assembly corridors.
- EPA Greenhouse Gas Reporting Program:Emissions monitoring granularity mandates are compelling chemical processors in Texas and Louisiana to deploy predictive maintenance stacks on rotating equipment.
Market Restraints
- Semiconductor supply concentration:PLC and edge controller chip sourcing bottlenecks from East Asian foundries are extending lead times for mid-tier retrofit projects.
- Legacy protocol fragmentation:Proprietary fieldbus standards from 1990s-era installations create integration friction that inflates engineering costs by 30-40% for brownfield deployments.
- Cyber insurance exclusions:Underwriters are carving out coverage for ransomware events originating in unpatched industrial control systems, transferring residual risk to plant operators.
Strategic Opportunities
- Mexico's CONAMER harmonization:Cross-border equipment certification alignment is opening integrated line-builder opportunities for automotive final assembly in Querétaro and Guanajuato.
- Pharmaceutical track-and-trace:FDA validation requirements for vision inspection systems are creating sticky switching costs that deepen margin pools for compliant vendors.
- 5G private networks:Convergence with time-sensitive networking is enabling wireless AGV fleets that eliminate cable tray infrastructure in Chicago-area food and beverage plants.
Industry Challenges
- OT cybersecurity skill scarcity:Plant engineering departments lack personnel capable of configuring secure zones per IEC 62443 standards, forcing reliance on external system integrators.
- OSHA collaborative robot guarding:Evolving machine safety standards for human-robot workstations are delaying retrofit timelines as manufacturers await final rule clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Factory Market |
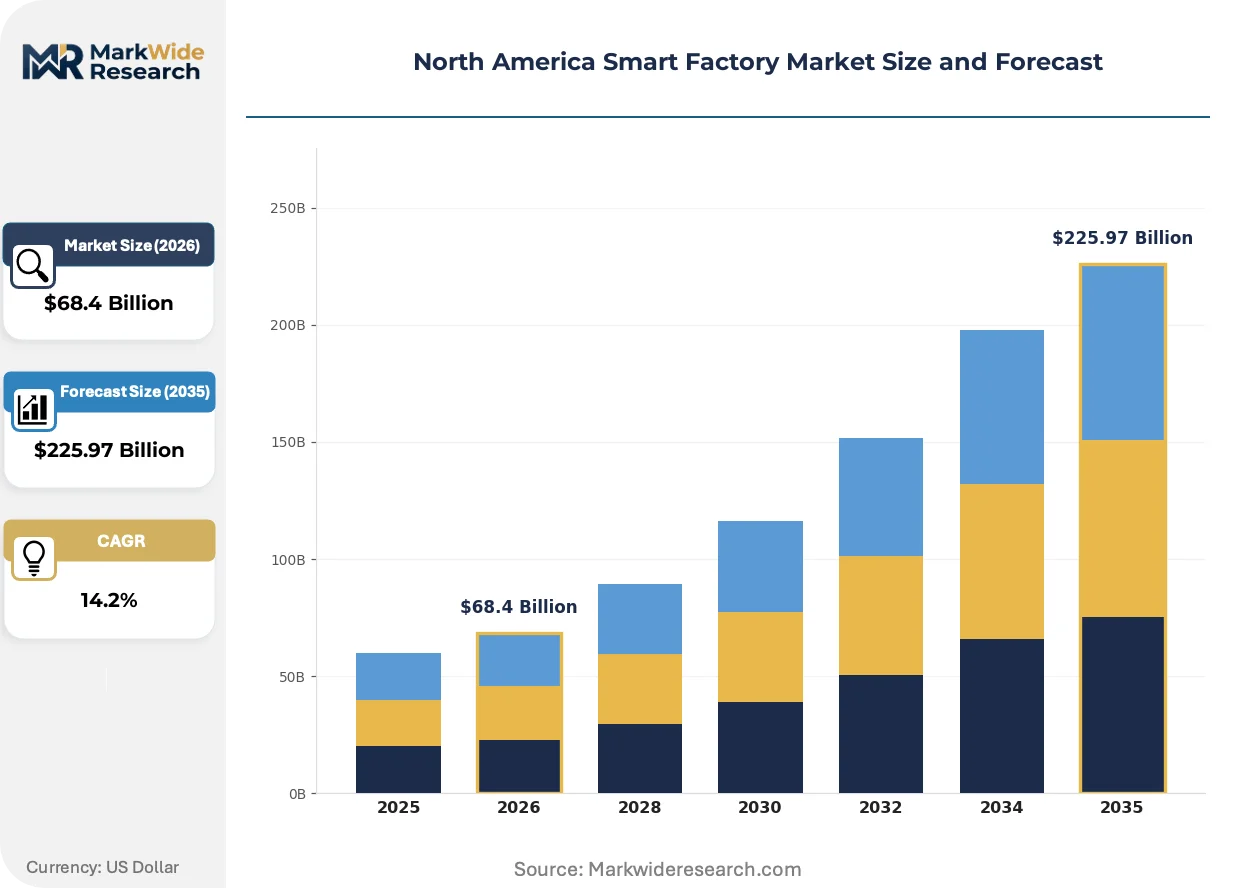
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $225.97 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Robotics, Automation Industry Vertical: Automotive, Electronics, Food & Beverage, Pharmaceuticals Application: Process Automation, Predictive Maintenance, Quality Control, Inventory Management End User: Manufacturers, OEMs, System Integrators, Solution Providers |
| Companies Covered | ABB Ltd, Siemens AG, Rockwell Automation Inc., Schneider Electric SE, Honeywell International Inc., Emerson Electric Co., General Electric Co., Cognex Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Factory Market Evolving Landscape
Digital twin software is absorbing capital allocation from traditional SCADA upgrades as automotive and aerospace OEMs prioritize virtual commissioning over physical prototyping cycles.
Digital twin platforms are absorbing engineering workflows previously executed through physical pilot lines. Tier 1 suppliers in the Cleveland-Toledo corridor are adopting these tools at 18-month replacement cycles for legacy simulation software. The technology is absorbing upfront design costs while compressing time-to-market for new vehicle platforms by enabling parallel process validation.
Canada's Advanced Manufacturing Supercluster funding is mandating interoperability compliance for grant recipients. This industrial consequence is forcing equipment vendors to adopt OPC UA over proprietary protocols. Pharmaceutical batch operations in Ontario are responding fastest, using the funding to replace isolated unit operations with integrated manufacturing execution systems.
Outcome-based service contracts are displacing traditional capex-plus-maintenance purchasing in process industries. Chemical operators in the Gulf Coast are now procuring uptime guarantees rather than owning predictive analytics infrastructure. This shift is most visible in Texas refineries, where Honeywell and Siemens now compete on guaranteed availability metrics rather than software license fees.
North America Smart Factory Market Segmentation
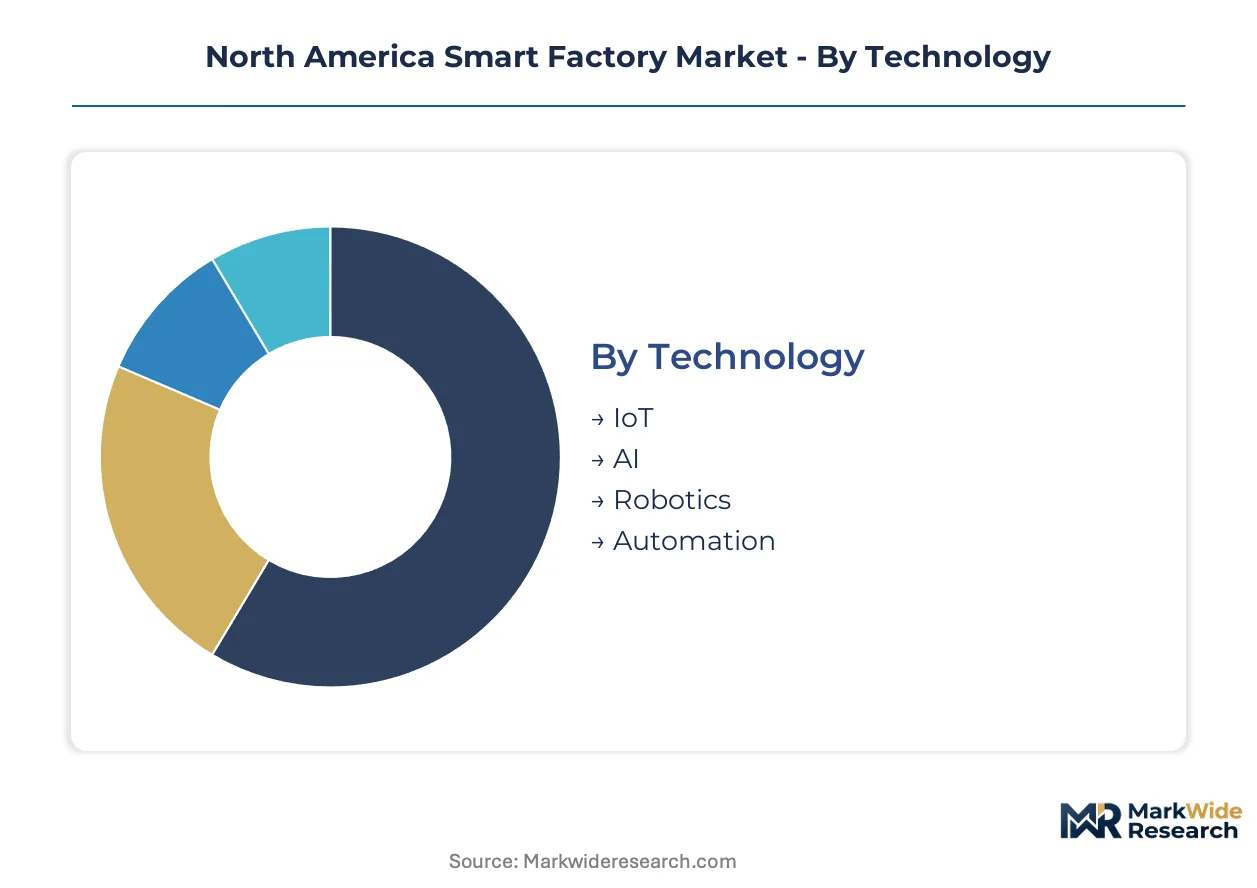
Smart factory deployments fragment across integration depths, from standalone point solutions to deeply embedded cyber-physical architectures. Understanding these segment boundaries clarifies where capital concentrates versus where interoperability challenges inflate project costs.
Technology:
Standalone sensor networks and edge nodes operate independently in legacy retrofits, while AI and robotics demand tight integration with existing control systems.
- IoT:Sensor networks and edge gateways collect real-time operational data from legacy equipment through protocol translation layers. Demand clusters in Detroit-Windsor automotive corridors where brownfield plants retrofit assembly lines without production halts. NIST interoperability standards are compressing deployment timelines for these brownfield integrations.
- AI:Machine learning models for process optimization and anomaly detection run on edge clusters or cloud-hybrid architectures. Pharmaceutical manufacturers in Ontario prioritize these deployments for batch consistency validation under Health Canada guidelines.
- Robotics:Collaborative and industrial robotic systems execute physical manufacturing tasks with programmable precision. OSHA's evolving machine guarding standards are delaying workstation retrofits pending final rule clarity.
- Automation:Programmable logic controllers, distributed control systems, and SCADA platforms orchestrate production workflows. Food and beverage processors in Chicago rely on these systems for hygienic design compliance with USDA regulations.
Volume placements concentrate in IoT sensor networks; the faster expansion belongs to AI-driven optimization layers.
Industry Vertical:
Cost tiers separate premium validation-grade deployments from standard automation retrofits across end-use sectors.
- Automotive:Digital twin architectures and flexible assembly systems enable lot-size-one production for electric vehicle platforms. Michigan and Ohio OEMs absorb the majority of capital allocation in this vertical.
- Electronics:Precision robotics and vision systems handle miniaturized component assembly with micron-level tolerances. Mexican maquiladoras in Baja California and Chihuahua drive cross-border equipment certification harmonization through CONAMER.
- Food & Beverage:Washdown-compatible automation and track-and-trace systems balance throughput with safety compliance. EPA Greenhouse Gas Reporting Program mandates are accelerating energy monitoring upgrades in this sector.
- Pharmaceuticals:Validated manufacturing execution systems and vision inspection platforms satisfy FDA 21 CFR Part 11 requirements. FDA validation requirements create sticky switching costs that deepen margin pools for compliant vendors.
Capital deployment concentrates in automotive; pharmaceuticals capture the steepest expansion trajectory due to regulatory compliance premiums.
Application:
Maturity curves separate established process control from emerging predictive capabilities in deployment patterns.
- Process Automation:Real-time control loops and recipe management systems govern continuous and batch manufacturing operations. Chemical processors in Texas and Louisiana deploy these systems under EPA emissions monitoring mandates.
- Predictive Maintenance:Vibration analysis, thermal imaging, and oil analysis algorithms forecast rotating equipment failures before unplanned downtime occurs. Gulf Coast refineries procure these capabilities through outcome-based uptime guarantees rather than capital ownership.
- Quality Control:Machine vision and spectroscopic inspection systems detect defects with automated rejection protocols. FDA validation requirements for pharmaceutical vision systems create defensive moats for established vendors.
- Inventory Management:Automated storage and retrieval systems coupled with RFID tracking optimize material flow and reduce working capital. 5G private networks are enabling wireless AGV fleets that eliminate cable infrastructure in Midwest distribution centers.
Installed base concentrates in process automation; predictive maintenance is climbing the fastest as sensor density thresholds enable algorithmic deployment.
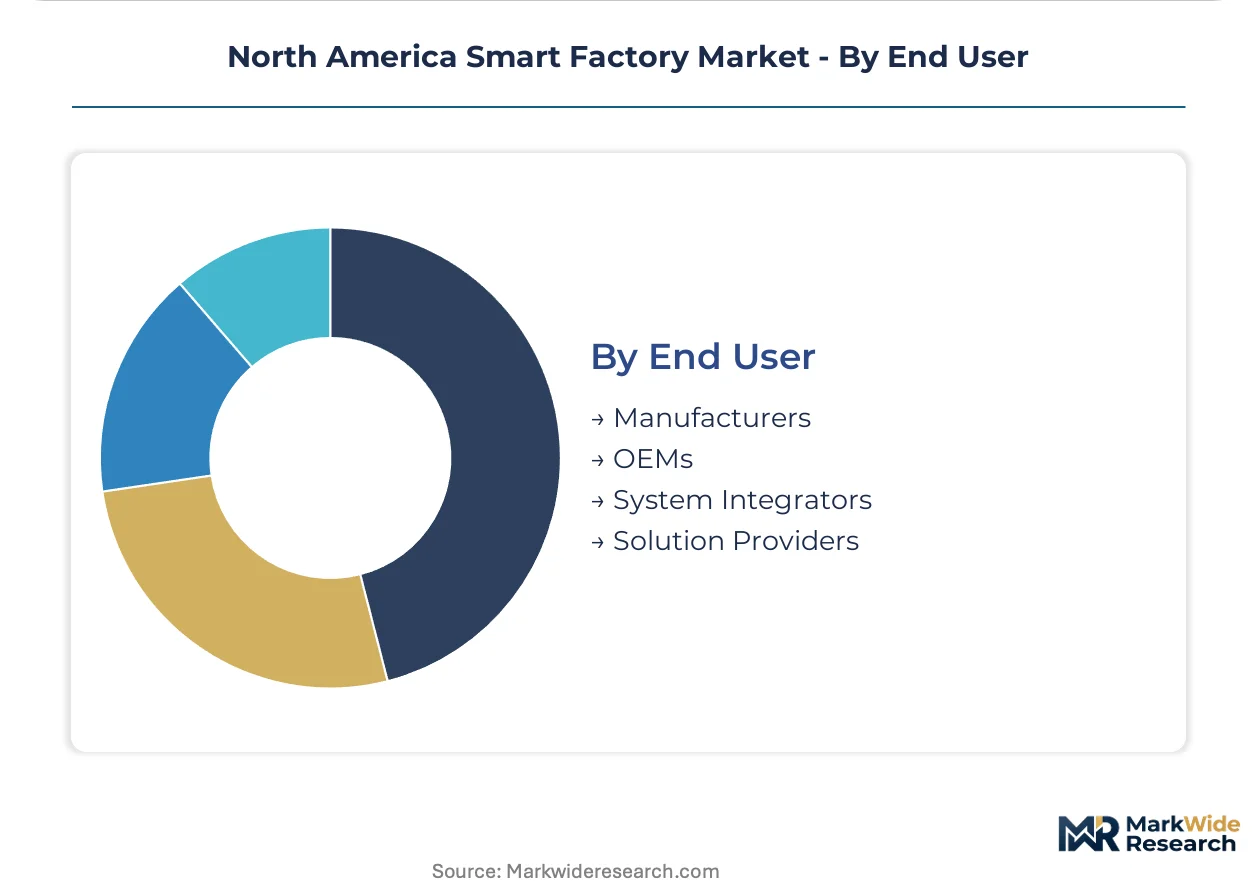
End User:
Customer type determines procurement authority and integration complexity in deployment structures.
- Manufacturers:Operating companies that own production assets and bear direct responsibility for throughput and quality outcomes. Great Lakes metal fabricators represent the core demand base for mid-tier retrofit projects.
- OEMs:Original equipment manufacturers that specify smart factory architectures for their supplier networks. Automotive OEMs across Michigan, Ohio, and Ontario are mandating digital twin compliance for Tier 1 suppliers.
- System Integrators:Engineering firms that design, deploy, and commission integrated automation solutions. OT cybersecurity skill scarcity is forcing manufacturers into reliance on these external specialists for IEC 62443 zone configuration.
- Solution Providers:Technology vendors that deliver software platforms, edge hardware, or managed services on subscription models. Outcome-based contracts are displacing traditional capex-plus-maintenance purchasing in process industries.
Procurement volume concentrates in direct manufacturers; solution providers are gaining share fastest through servitization and guaranteed outcome models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor corridor anchors North American smart factory deployment, with automotive OEMs and Tier 1 suppliers commanding capital allocation across Michigan and Ontario assembly networks.
United States
Automotive OEMs in Michigan and Ohio are mandating digital twin compliance for supplier networks while chemical processors in Texas and Louisiana face EPA emissions monitoring mandates. OSHA's evolving collaborative robot guarding standards are delaying workstation retrofits pending final rule clarity. The Great Lakes manufacturing belt spanning Detroit, Cleveland, and Chicago concentrates brownfield retrofit demand.
Canada
Advanced Manufacturing Supercluster funding is forcing equipment vendors toward OPC UA interoperability over proprietary protocols. Health Canada guidelines are accelerating AI-driven batch consistency validation in Ontario pharmaceutical operations. Toronto-Waterloo tech corridors are absorbing grant capital for integrated manufacturing execution systems.
Mexico
Automotive final assembly expansion in Querétaro and Guanajuato is driving cross-border equipment certification harmonization through CONAMER. Maquiladoras in Baja California and Chihuahua are demanding precision robotics for electronics miniaturization. The Bajío Region is emerging as the primary beneficiary of integrated line-builder opportunities.
North America Smart Factory Market Competitive Landscape
Premium-margin players sit above commodity-margin players across digital twin depth and vertical integration intensity. The vendor base stratifies into three tiers: full-stack automation conglomerates, specialized robotics and vision vendors, and regional system integrators. Two dominant competitive moves are reshaping positioning: outcome-based servitization contracts displacing traditional capex sales, and strategic partnerships bridging OT cybersecurity capability gaps.
Within the full-stack tier, Siemens AG and Rockwell Automation Inc. exemplify divergent geographic anchoring strategies. ABB Ltd occupies a position spanning industrial robotics and process automation archetypes. Honeywell International Inc. sits within the process safety specialization vector, representing defensive margin capture in validated pharmaceutical environments. Emerson Electric Co. anchors the hybrid automation-services positioning that Gulf Coast chemical operators increasingly favor.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Rockwell Automation Inc. |
| Schneider Electric SE |
| Honeywell International Inc. |
| Emerson Electric Co. |
| General Electric Co. |
| Cognex Corporation |
| Yokogawa Electric Corporation |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement committees across Michigan and Ontario anchor pricing power through outcome-based servitization contracts that displace traditional capex-plus-maintenance purchasing. Tier 1 suppliers face compressed margins as full-stack vendors compete on guaranteed uptime metrics rather than software license fees.
Pricing Analysis
Outcome-based pricing tied to equipment uptime and throughput yield anchors vendor revenue models across process industries. Three-tier pricing structure across premium validation-grade, standard interoperability-compliant, and economy retrofit tiers separates pharmaceutical batch operations from food and beverage plants. Cost compression in mid-tier PLC and edge controller segments is intensifying because semiconductor sourcing bottlenecks extend hardware delivery timelines. Small-to-mid metal fabricators in the Great Lakes corridor exhibit highest price sensitivity, while FDA-validated pharmaceutical manufacturers accept premium positioning for compliant vision inspection systems.
Supply Chain Analysis
Regional distribution centers in Detroit, Cleveland, and Chicago operate hub-and-spoke patterns for spare parts and edge hardware fulfillment. East Asian foundries in Taiwan, South Korea, and China supply the majority of industrial semiconductor content for PLCs and motion controllers. The ecosystem rests on rare earth magnet supply for servo motors, precision optical components for vision systems, and specialized aluminum extrusions for collaborative robot frames. Single-source vulnerability in advanced node chip fabrication creates exposure for vendors serving brownfield retrofit timelines. Distribution runs through authorized distributor networks anchored by Rockwell Automation's PartnerNetwork and Siemens' Solution Partner program.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors capable of delivering IEC 62443-compliant cybersecurity architectures, forcing smaller system integrators into acquisition or exit. OT cybersecurity skill scarcity transfers procurement authority to full-stack vendors with captive integration capabilities.
For Market Incumbents: Deploy outcome-based servitization contracts to lock in chemical and pharmaceutical operators through guaranteed availability metrics. Acquire regional system integrators in the Great Lakes corridor to internalize IEC 62443 zone configuration capabilities currently bottlenecking deployment timelines. Consolidate distributor relationships to control channel access for mid-tier retrofit projects threatened by commodity automation vendors. For New Entrants and Emerging Players: Launch via 5G private network integration partnerships targeting Chicago-area food and beverage plants seeking wireless AGV fleet deployment. Target Mexico's Bajío Region automotive final assembly expansion where CONAMER harmonization creates first-mover certification advantages. Focus on edge computing node hardware optimized for sub-millisecond collaborative robotics latency requirements in Detroit-Windsor corridors. For Investors and Strategic Acquirers: The window for entry favors vertically integrated automation vendors with captive digital twin software and process safety layers. Long-term viability hinges on exposure to pharmaceutical validation-grade margins and automotive OEM digital twin mandates. Monitor NIST interoperability standard adoption velocity as the inflection signal for vendor consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Servitization Contract | Shifts revenue from license fees to guaranteed uptime metrics in Texas refineries. |
| OPC UA Interoperability Certification | Unlocks Canada's Advanced Manufacturing Supercluster grant funding for equipment vendors. |
| 5G Private Network Deployment | Enables wireless AGV fleets eliminating cable infrastructure in Midwest distribution centers. |
| Digital Twin Platform Acquisition | Accelerates virtual commissioning adoption across Michigan and Ohio automotive OEMs. |
| IEC 62443 Cybersecurity Compliance | Addresses OT skill scarcity forcing reliance on external system integrators. |
Research Methodology
Document review covered SEC 10-K filings, NIST technical publications, and Canadian Supercluster grant disclosures, complemented by interviews with plant engineering directors, OT cybersecurity specialists, automotive Tier 1 procurement leads, and system integrator principals. Secondary validation drew from EPA emissions monitoring databases, OSHA regulatory dockets, and CONAMER certification records. Bottom-up deployment estimates across technology segments were triangulated against top-down capital expenditure tracking from industrial automation vendors.
Cross-referencing historical retrofit cycle patterns with panel input from Great Lakes manufacturing operators anchored the analytical framework. Segmentation modeling incorporated technology integration depth, industry vertical validation requirements, application maturity curves, and end-user procurement authority across the projection horizon. CAGRs were derived from deployment velocity differentials between greenfield automotive facilities and brownfield chemical plant retrofits, with sensor density thresholds and regulatory compliance deadlines as primary forecast inputs.
Semiconductor supply disruptions, OSHA collaborative robot rule finalization delays, and cross-border tariff adjustments are the dominant revision risks to deployment timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Grippers Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Intralogistics Market
Industrial Automation
Digital Rotator Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Modular High-Bay Solutions Market