
 IIOT Gateway for Utility Market | 2026-2036
IIOT Gateway for Utility Market Size, Share, and Industry Trends Forecast 2026-2036
IIOT Gateway for Utility Market Foresight
Buyer concentration among electric utilities is recalibrating procurement dynamics across the IIOT gateway supply base. Large integrated utilities now consolidate vendor relationships, while municipal co-ops and distributed energy resource aggregators fragment the mid-market. Cisco Systems leverages its networking heritage to anchor enterprise-grade security architectures for transmission operators. Advantech Co., Ltd. specializes in ruggedized edge computing platforms purpose-built for substation environments. Moxa Inc. competes through hardened industrial Ethernet portfolios that sustain long operational lifecycles in remote telemetry applications.
An IIOT gateway for utility applications is a hardened network appliance that bridges operational technology protocols such as DNP3, IEC 61850, and Modbus with IP-based enterprise and cloud systems, typically operating across temperature extremes from minus forty to plus seventy degrees Celsius with electromagnetic immunity certification. Its primary purpose is to enable real-time visibility, predictive maintenance, and automated control across geographically dispersed generation, transmission, and distribution infrastructure. Edge Gateway deployments dominate current utility capital expenditure due to latency requirements for protective relay coordination and localized outage response. Cloud Gateway configurations represent the fastest-growing installation category as water utilities modernize aging infrastructure with centralized SCADA integration. Protocol Converter units retain stable replacement demand within legacy brownfield substations where full gateway replacement remains economically prohibitive.
FERC Order 2222 in the United States accelerates distributed energy resource aggregation, directly expanding addressable gateway demand for grid-interactive behind-the-meter assets. The EU Cybersecurity Act and IEC 62443 standards frameworks mandate certified secure-by-design architectures, reshaping product development roadmaps and creating compliance barriers for uncertified suppliers. NERC CIP requirements in North America enforce continuous monitoring and encrypted communications for critical cyber assets, elevating procurement specifications toward hardware with integrated hardware security modules. Stakeholders must monitor evolving certification reciprocity between regional frameworks to anticipate which gateway architectures will transfer across multinational utility portfolios without redundant engineering.
Market Dynamics
Utility grid modernization is compressing procurement cycles as transmission operators and distribution utilities simultaneously deploy protective relay upgrades, distributed energy resource interfaces, and centralized SCADA overlays. This overlapping capital intensity is forcing gateway vendors to architect multi-protocol platforms that satisfy divergent latency, security, and environmental specifications without engineering redundancy.
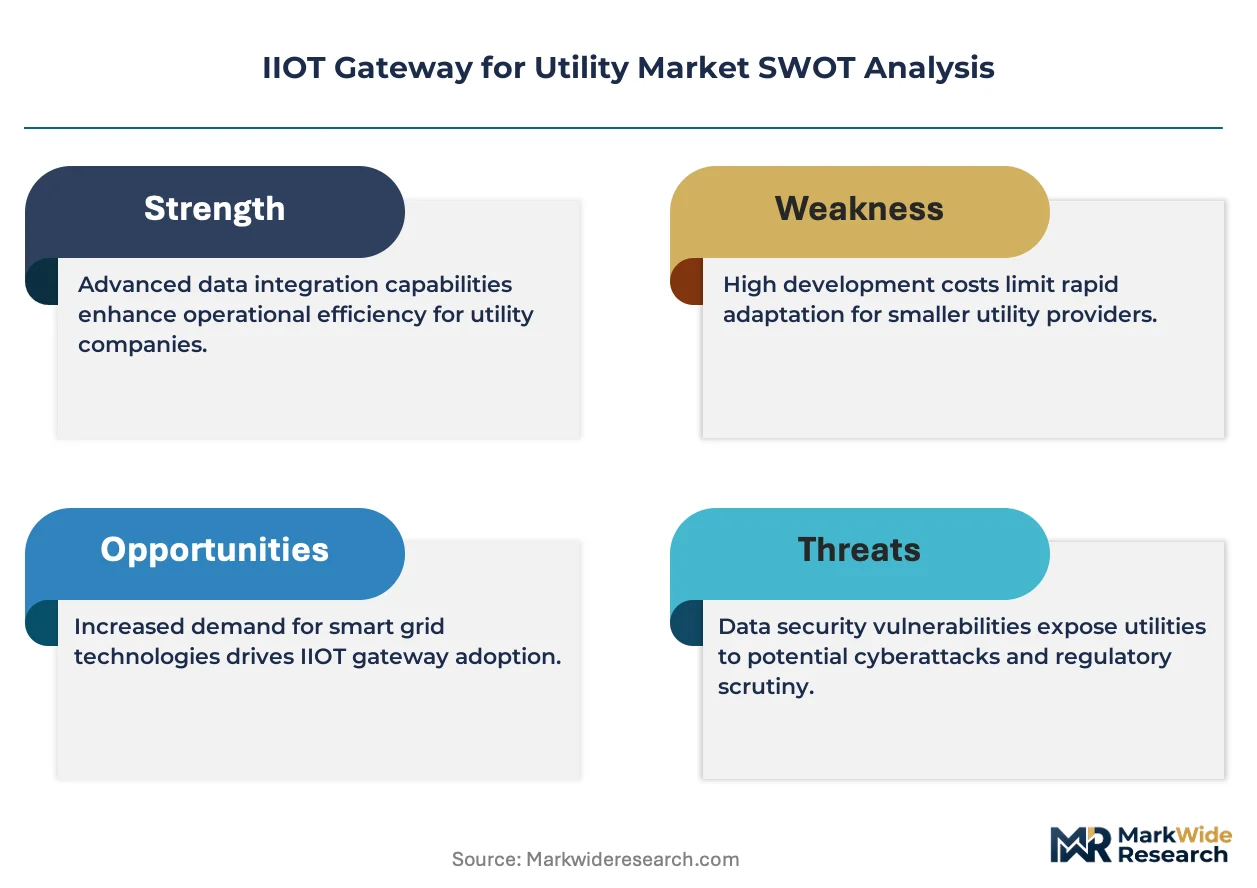
Growth Catalysts
- FERC Order 2222:The US Federal Energy Regulatory Commission's mandate for distributed energy resource aggregation is expanding gateway addressable demand for grid-interactive behind-the-meter assets.
- Edge computing convergence:Real-time protective relay coordination requirements are accelerating edge gateway deployments that process telemetry locally rather than routing through centralized cloud infrastructure.
- Germany:Utility digitization mandates and industrial cluster density are creating concentrated procurement pull for hardened gateway hardware and analytics platforms.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate industrial-grade processor and FPGA fabrication, exposing gateway lead times to geopolitical disruption.
- IEC 62443 certification friction:The EU Cybersecurity Act's secure-by-design mandates are extending product development timelines and elevating engineering costs for uncertified suppliers.
- Protocol fragmentation:Persistent reliance on legacy Modbus and DNP3 in brownfield substations limits full-gateway replacement economics and caps premium product penetration.
Strategic Opportunities
- Water utility cloud migration:Aging centralized SCADA infrastructure in North American and European water networks is opening fastest-growing installation category for cloud gateway configurations.
- 5G private network integration:Convergence of cellular radio access with time-sensitive networking is enabling new low-latency telemetry architectures for remote distribution automation.
- EU Green Deal tailwind:Tightening emissions monitoring requirements across European energy networks are mandating sensor densification that gateway infrastructure must aggregate.
Industry Challenges
- OT-IT security skill scarcity:Protective relay engineers with IEC 62443 implementation experience command premium compensation and extended recruitment timelines.
- Brownfield integration complexity:Electromagnetic immunity certification gaps between legacy substation equipment and modern IP-native gateways are forcing costly site-specific engineering.
- NERC CIP compliance velocity:North American critical infrastructure protection requirements are compressing patch deployment windows and elevating operational technology maintenance burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IIOT Gateway for Utility Market |
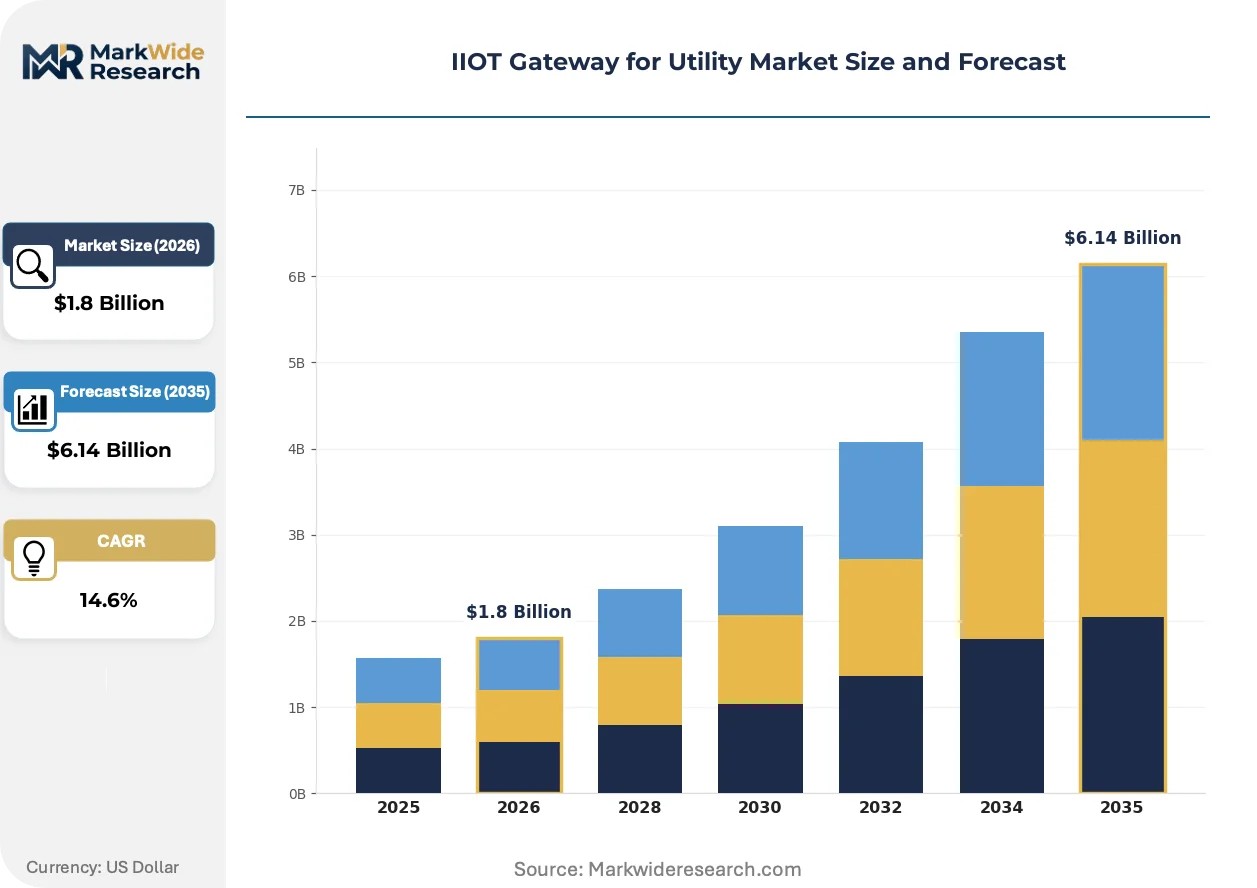
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge Gateway, Cloud Gateway, Protocol Converter, Data Logger Installation: On-Premise, Cloud-Based, Hybrid, Remote End User: Water Utilities, Electric Utilities, Gas Providers, Telecommunication Companies Technology: Wireless, Wired, LoRaWAN, NB-IoT |
| Companies Covered | Cisco Systems, Inc., Advantech Co., Ltd., Moxa Inc., Sierra Wireless, Inc., Digi International Inc., Huawei Technologies Co., Ltd., Intel Corporation, Texas Instruments Incorporated, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IIOT Gateway for Utility Market Shifts & Advancements
Gateway architectures are bifurcating between ultra-low-latency edge processing for protective systems and cloud-native aggregation for resource planning, with software-defined protocol translation emerging as the bridge technology. This duality is reshaping vendor R&D allocation and partnership strategies.
Time-sensitive networking over Ethernet is absorbing deterministic traffic that previously required dedicated fieldbus infrastructure. Transmission operators in Germany and Texas are deploying TSN-capable gateways for synchronized phasor measurement. The technology is absorbing legacy serial protocol traffic while maintaining sub-millisecond jitter guarantees for protective relay coordination.
The EU F-Gas Regulation is accelerating sensor gateway deployments for sulfur hexafluoride leak detection in high-voltage switchgear. Industrial gas monitoring mandates are expanding addressable hardware demand beyond traditional electrical telemetry. European transmission operators are retrofitting substations with integrated environmental sensing gateways to satisfy reporting thresholds.
Consolidated vendor relationships among large integrated utilities are fragmenting procurement access for mid-tier gateway suppliers. Municipal co-ops and distributed energy resource aggregators are building alternative supplier rosters through cooperative purchasing agreements. This pattern is most visible in US Midwest markets where rural electric membership corporations pool specification development.
IIOT Gateway for Utility Market Segmentation
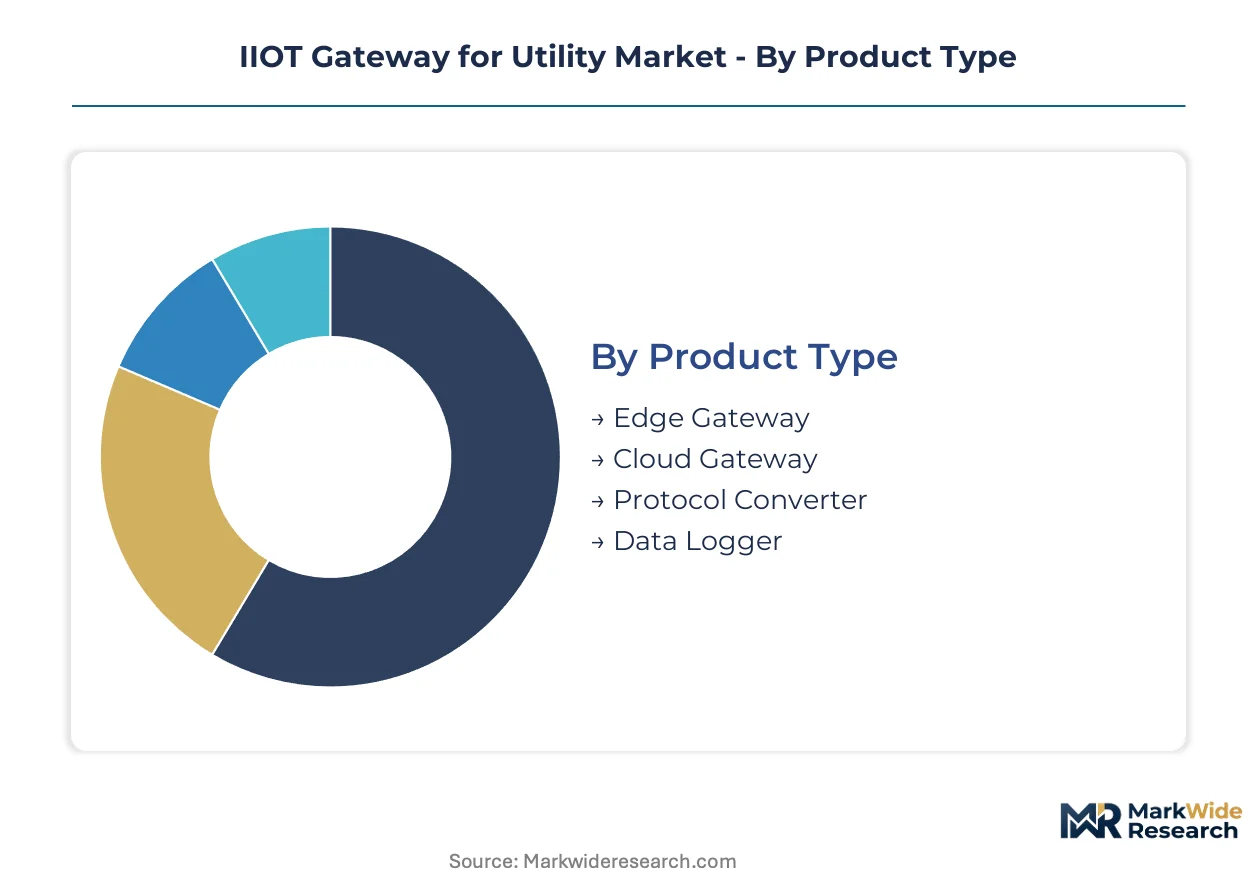
Procurement specifications for IIOT gateways diverge sharply across utility operational contexts. Edge-hardened platforms for protective relay coordination bear little resemblance to cloud-native aggregation nodes for water SCADA modernization. Understanding these segment boundaries clarifies where engineering investment concentrates versus where price competition dominates.
Product Type:
Utility buyers select gateway architectures based on latency tolerance and existing protocol infrastructure rather than feature breadth alone.
- Edge Gateway:Hardened appliances process DNP3 and IEC 61850 telemetry locally within minus forty to plus seventy degree Celsius thermal envelopes. Electric utilities in Germany deploy these for protective relay coordination where millisecond response windows preclude cloud routing. Procurement specifications prioritize electromagnetic immunity certification and hardware security module integration under EU Cybersecurity Act mandates.
- Cloud Gateway:IP-native aggregation nodes centralize telemetry from geographically dispersed sensors for SCADA overlay integration. Water utilities across North America and Europe represent concentrated demand as aging infrastructure modernization accelerates. These configurations gain preference where latency requirements relax and centralized analytics deliver operational cost reductions.
- Protocol Converter:Legacy bridging devices translate Modbus and DNP3 serial traffic to Ethernet without full gateway replacement. Brownfield substations with amortized capital equipment drive stable replacement demand.
- Data Logger:Local storage-capable units buffer telemetry during communication outages for later batch transmission. Remote distribution automation sites with intermittent connectivity specify these for compliance data retention.
Volume sits with Edge Gateway; growth tilts toward Cloud Gateway.
Installation:
Deployment topology determines capital expenditure phasing and operational technology integration complexity for utility engineering teams.
- On-Premise:Physical gateway hardware installed within substation control houses or meter data management facilities. Electric transmission operators specify these for NERC CIP critical cyber asset compliance with encrypted local processing.
- Cloud-Based:Fully virtualized gateway functions hosted in utility-managed or third-party cloud infrastructure. Water utilities with limited on-site IT staffing prefer this model for centralized patch management and scalability.
- Hybrid:Split architectures process time-critical telemetry at the edge while aggregating historical data in cloud repositories. FERC Order 2222 distributed energy resource aggregators favor this topology for behind-the-meter asset coordination.
- Remote:Solar-powered or battery-backed units deployed at unmanned distribution endpoints without permanent communication infrastructure. Rural electric membership corporations in the US Midwest specify these for feeder automation extension.
On-Premise retains the largest installed base; Hybrid configurations are climbing the fastest.
End User:
Regulatory velocity and infrastructure age create divergent procurement calendars across utility sectors.
- Water Utilities:Municipal and regional water authorities modernizing centralized SCADA systems generate fastest-expanding gateway demand. EPA lead and copper rule revisions are mandating sensor densification that gateway infrastructure must aggregate.
- Electric Utilities:Transmission and distribution operators deploy the highest-specification platforms for grid modernization and distributed energy resource integration. EU Green Deal emissions monitoring requirements are tightening procurement specifications.
- Gas Providers:Pipeline operators and distribution utilities specify intrinsically safe gateways for hazardous area telemetry. Leak detection regulatory mandates are expanding addressable hardware demand.
- Telecommunication Companies:Tower and facility power monitoring applications represent secondary demand with less stringent environmental certification requirements.
Electric Utilities dominate capital deployment; Water Utilities are gaining share fastest.
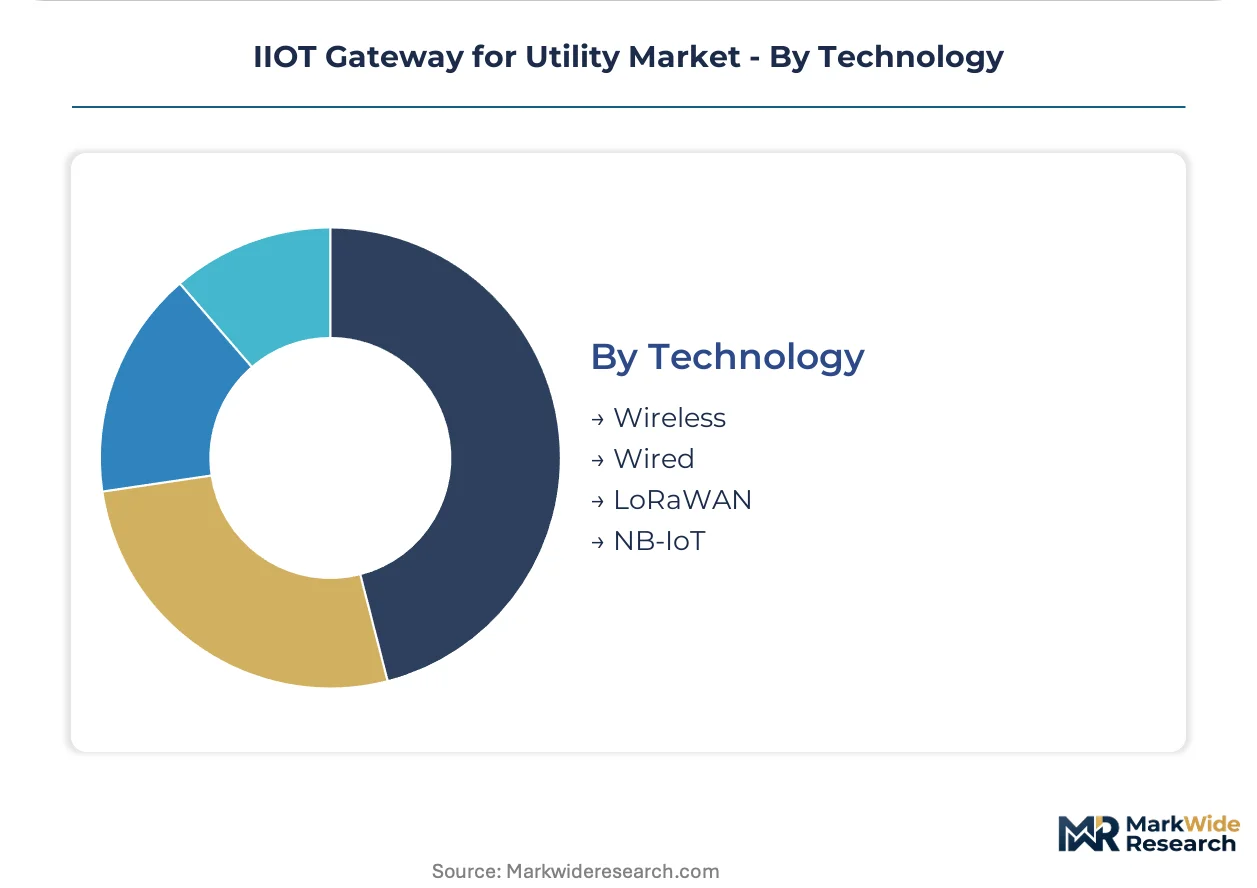
Technology:
Connectivity selection balances coverage economics against deterministic latency guarantees for specific telemetry applications.
- Wireless:Cellular and unlicensed radio technologies enable rapid deployment without trenching for fiber. Remote distribution automation and mobile workforce applications favor this flexibility.
- Wired:Fiber and copper Ethernet deliver guaranteed bandwidth for protective systems and substation automation. Time-sensitive networking over Ethernet is absorbing deterministic traffic previously routed through dedicated fieldbus infrastructure.
- LoRaWAN:Unlicensed wide-area networks support low-bitrate sensor aggregation across sprawling distribution territories. Smart metering and environmental monitoring applications specify these for battery longevity.
- NB-IoT:Licensed cellular narrowband technology penetrates indoor and underground environments where conventional cellular fails. Water utility smart meter deployments in Germany leverage this for deep indoor coverage.
Wired maintains reliability preference; NB-IoT is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility digitization mandates and industrial cluster density concentrate procurement pull in Germany, while FERC Order 2222 and NERC CIP requirements shape North American deployment patterns. Water utility modernization across North America and Europe is expanding cloud gateway demand fastest.
United States
FERC Order 2222 accelerates distributed energy resource aggregation, expanding gateway demand for grid-interactive behind-the-meter assets. NERC CIP requirements enforce continuous monitoring and encrypted communications for critical cyber assets. Texas transmission operators deploy time-sensitive networking gateways for synchronized phasor measurement.
Germany
Utility digitization mandates and industrial cluster density create concentrated procurement pull for hardened gateway hardware. The EU F-Gas Regulation tightens emissions monitoring requirements across energy networks. Bavarian transmission operators retrofit substations with integrated environmental sensing gateways for sulfur hexafluoride leak detection.
China
State Grid Corporation accelerates smart grid infrastructure deployment across provincial transmission networks. National dual carbon goals mandate sensor densification for emissions monitoring in high-voltage switchgear. Yangtze River Delta industrial zones specify ruggedized edge platforms for substation automation integration.
United Kingdom
Ofgem's RIIO-2 price control framework incentivizes distribution network operators to deploy advanced monitoring infrastructure. The UK Cyber Security Strategy mandates secure-by-design architectures for critical national infrastructure. London and Southeast England utilities consolidate vendor relationships for multi-protocol gateway platforms.
Japan
METI's Green Growth Strategy drives grid modernization investments for renewable energy integration. JIS standards frameworks specify electromagnetic immunity certification for substation equipment. Tokyo Electric Power and Kansai regional utilities deploy edge gateways for protective relay coordination in earthquake-resilient infrastructure.
IIOT Gateway for Utility Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native virtualization and 5G private network integration. Large integrated utilities consolidate vendor relationships, fragmenting procurement access for mid-tier suppliers. Two archetypes dominate: networking heritage players anchoring enterprise-grade security architectures, and industrial computing specialists delivering ruggedized edge platforms. Competitive moves center on multi-protocol platform development and IEC 62443 certification acceleration.
Within the networking heritage tier, Cisco Systems, Inc. exemplifies enterprise-grade security architecture positioning for transmission operators. Advantech Co., Ltd. and Moxa Inc. represent the ruggedized industrial computing archetype, with the former specializing in edge platforms and the latter competing through hardened Ethernet portfolios for remote telemetry applications.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Advantech Co., Ltd. |
| Moxa Inc. |
| Sierra Wireless, Inc. |
| Digi International Inc. |
| Huawei Technologies Co., Ltd. |
| Intel Corporation |
| Texas Instruments Incorporated |
| NXP Semiconductors N.V. |
| Others |
Supply & Pricing Matrix
Large integrated utilities concentrate procurement volume across Germany, the United States, and China, forcing a project-based pricing model with volume-scaled discounts for multi-year framework agreements. This buyer concentration elevates negotiation leverage while IEC 62443 certification requirements fragment supplier tiers into premium-certified and uncertified economy segments.
Pricing Analysis
Volume concentrates in Edge Gateway deployments for protective relay coordination, while margins compress in Protocol Converter replacement cycles where brownfield economics cap premium penetration. Three-tier pricing structure across premium-certified, standard-compliant, and economy-unverified levels separates vendors by IEC 62443 SL-2/SL-3 attainment. Cost compression in mid-tier Cloud Gateway configurations intensifies because water utility procurement favors centralized SCADA integration over edge-hardened specifications. Municipal co-ops and distributed energy resource aggregators exhibit highest price sensitivity, whereas German transmission operators prioritize electromagnetic immunity certification over unit cost.
Supply Chain Analysis
Industrial-grade processor and FPGA fabrication rests on Taiwan and South Korea, with secondary packaging and subsystem integration anchored in China and Germany. Gateway hardware draws from silicon foundry output, conformal coating materials for thermal tolerance, and hardware security module chipsets. Single-source vulnerability concentrates in 7nm and 5nm industrial processor supply, exposing lead times to geopolitical disruption. Distribution runs through authorized industrial automation distributors and direct utility framework agreements, with co-op purchasing pools gaining share in US Midwest markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity for industrial-grade processors operates at effective utilization ceilings, propping hardware pricing power for certified suppliers while extending delivery timelines for uncertified entrants.
For Market Incumbents: Anchor enterprise-grade security architectures through accelerated IEC 62443 SL-3 certification timelines to defend against cloud-native virtualization entrants. Deepen backward integration into hardware security module sourcing to secure captive supply of critical cryptographic components. Consolidate vendor relationships with German transmission operators through multi-protocol platform bundling that spans Edge and Cloud Gateway configurations. For New Entrants and Emerging Players: Cloud-native SaaS delivery models open procurement access among North American water utilities with limited on-site IT staffing for centralized patch management. Municipal co-op purchasing pools in the US Midwest represent the most penetrable buyer segment, fragmented from large integrated utility frameworks. Target hybrid deployment topologies for FERC Order 2222 distributed energy resource aggregators seeking behind-the-meter asset coordination without full edge hardware replacement. For Investors and Strategic Acquirers: The window for entry favors industrial computing specialists with existing ruggedized edge platforms and electromagnetic immunity certification libraries. Long-term viability centers on vendors bridging OT-IT security skill scarcity through automated compliance tooling. Watch IEC 62443 certification reciprocity negotiations between EU and North American frameworks as the inflection signal for multinational portfolio transferability without redundant engineering.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 SL-3 Certification Acceleration | EU Cybersecurity Act mandates secure-by-design architectures for critical infrastructure procurement eligibility. |
| 5G Private Network Integration | German transmission operators deploy time-sensitive networking gateways for synchronized phasor measurement. |
| Water Utility Cloud Migration | EPA lead and copper rule revisions mandate sensor densification that gateway infrastructure must aggregate. |
| Backward Integration into HSM Sourcing | NERC CIP requirements elevate procurement specifications toward hardware with integrated hardware security modules. |
| Environmental Sensing Gateway Retrofit | EU F-Gas Regulation tightens emissions monitoring requirements across European high-voltage switchgear networks. |
Research Methodology
Document review covered FERC orders, EU regulatory filings, and NERC CIP standards documentation, complemented by interviews with utility planning officers, substation automation engineers, industrial cybersecurity consultants, and procurement leads at transmission operators. Secondary validation drew from IEC standards publications, EIA grid modernization databases, and utility capital expenditure disclosures. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment forecasts across the analysis window.
Installed base projections and revenue estimates were generated across product type, installation topology, end-user sector, and connectivity technology dimensions. CAGRs were derived from regression analysis of historical deployment velocity against regulatory mandate timelines and infrastructure replacement cycles. Forecast inputs incorporated FERC Order 2222 implementation pace, EU Green Deal sensor densification requirements, and semiconductor supply lead time assumptions.
The model holds under stable regulatory enforcement and foundry capacity allocation; deviation in IEC 62443 certification reciprocity agreements or Taiwan Strait logistics disruption would shift deployment timelines. Forecasts reflect assumptions regarding utility capital expenditure continuity and cybersecurity standard harmonization. A small set of named triggers—geopolitical supply disruption, accelerated EU emissions enforcement, and NERC CIP patch velocity requirements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market
Internet of Things (IoT)
IoT Data Management Market
Internet of Things (IoT)
Industrial Internet of Things (Iiot) Market
Internet of Things (IoT)
Intelligent IoT Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Global Residential Smart Thermostats Market
Internet of Things (IoT)
Europe IoT Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Global IoT in Smart Cities Market
Internet of Things (IoT)
IoT Smart Poles Market
Internet of Things (IoT)
Smart Connected Device Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Smart Tracker Market