
 South Africa IoT Market | 2026-2036
South Africa IoT Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa IoT Market Analytics
Enterprise buyers is collapsing as the dominant procurement archetype while municipal and utility purchasers gain share in South Africa's IoT landscape. Cisco Systems leverages its networking heritage to anchor large-scale industrial deployments across the country's mining belt. MTN Group competes aggressively on cellular connectivity packages tailored for low-power wide-area applications. Huawei Technologies extends its equipment reach through base station and module supply relationships with local operators.
The Internet of Things in South Africa encompasses networked physical devices embedding sensors, actuators, and connectivity modules that collect and exchange data across IP-based infrastructure, typically operating through edge computing gateways that process telemetry locally before cloud transmission. Smart Sensors dominate product type revenues through their integration into predictive maintenance systems for capital-intensive industries, while Asset Tracking applications capture expanding margin pools as logistics operators digitize fleet and cargo monitoring. Cellular connectivity leads the access layer due to existing tower density, though LoRaWAN networks are gaining fastest in agricultural and remote metering deployments.
ICASA governs spectrum allocation and device certification, while the South African Bureau of Standards (SBS) and ISO/IEC frameworks shape interoperability mandates for connected equipment entering critical infrastructure. The Protection of Personal Information Act (POPIA) imposes data governance requirements that elevate compliance costs for health monitoring and smart home platforms handling consumer biometric information. Stakeholders must monitor pending critical infrastructure protection regulations that could mandate domestic data residency for operational technology networks.
Market Dynamics
ICASA's spectrum licensing reforms for IoT-specific bands are accelerating network buildouts while mining operators expand sensor deployments for predictive maintenance, creating a dual-engine expansion pattern concentrated in Gauteng's industrial corridors.
Growth Catalysts
- Smart Sensors:Integration into predictive maintenance systems for capital-intensive industries drives hardware demand as mining operators digitize asset monitoring.
- Cellular Connectivity:Existing tower density enables rapid deployment of low-power wide-area networks across logistics and agricultural monitoring applications.
- POPIA Compliance Infrastructure:Data governance mandates elevate platform requirements for health monitoring and biometric handling systems, expanding addressable service revenue pools.
Market Restraints
- Module Import Dependency:Concentrated supply of cellular modems and edge processors from Asian manufacturing clusters exposes local integrators to currency volatility and shipping disruptions.
- Spectrum Auction Timelines:ICASA's procedural delays for sub-1 GHz band assignments postpone rural network densification projects.
- Power Infrastructure Gaps:Unreliable grid supply in Eastern Cape and Limpopo provinces limits always-on sensor deployments without costly solar-battery backup systems.
Strategic Opportunities
- Eastern Cape Agriculture:Underpenetrated citrus and wine farming regions present white space for LoRaWAN-based irrigation and soil monitoring networks.
- Critical Infrastructure Protection:Pending domestic data residency mandates for operational technology networks would create captive demand for local cloud and edge hosting providers.
- Edge-AI Convergence:On-device inference chips combined with 5G slicing enable real-time anomaly detection in platinum and gold extraction operations.
Industry Challenges
- Embedded Systems Engineering Talent:Scarce firmware development and RF optimization skills constrain local product engineering capacity.
- ISO/IEC 27001 Certification Timelines:Extended audit queues for information security management delay enterprise contract awards.
- Legacy SCADA Integration:Proprietary protocols in existing industrial control systems complicate gateway deployment and data normalization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa IoT Market |
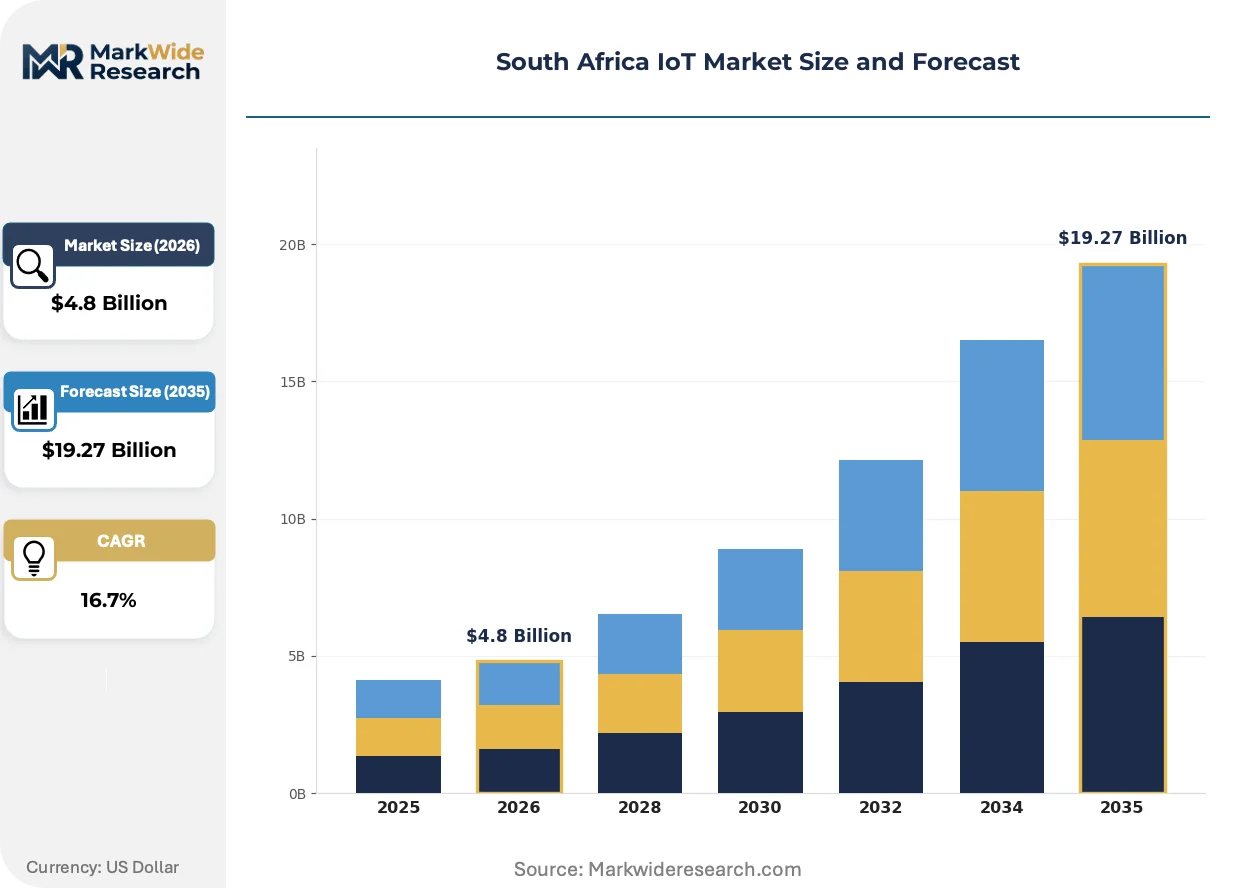
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Sensors, Smart Meters, Wearable Devices, Connected Appliances End User: Manufacturing, Healthcare, Agriculture, Transportation Connectivity: Wi-Fi, Zigbee, Cellular, LoRaWAN Application: Smart Home, Industrial Automation, Health Monitoring, Asset Tracking |
| Companies Covered | IBM Corporation, Cisco Systems, MTN Group, SAP SE, Telkom SA Limited, Vodacom Group, Huawei Technologies, Dimension Data, Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa IoT Market Evolving Landscape
Telemetry processing architectures are migrating toward distributed edge nodes as connectivity economics reshape deployment patterns across South Africa's capital-intensive sectors.
Edge computing gateways with local inference capabilities are supplanting raw cloud transmission models in mining and manufacturing environments. Anglo American and Sasol operations are deploying NVIDIA Jetson and Arm-based platforms at scale. This shift compresses bandwidth costs while enabling sub-100 millisecond response times for safety-critical equipment shutdowns.
POPIA's biometric data handling restrictions are tightening compliance requirements for health monitoring and smart home platforms. Device manufacturers must implement encryption-by-default and consent management frameworks. Consumer-facing IoT vendors in Johannesburg and Cape Town are restructuring data flows to minimize cross-border storage exposure.
Municipal procurement departments are consolidating vendor relationships through framework agreements rather than project-by-project sourcing. Single-source contracts with integrated connectivity-hardware-software stacks are displacing multi-vendor integration approaches. This concentration is most visible in Gauteng's smart city pilots and Western Cape water utility digitization programs.
South Africa IoT Market Segmentation
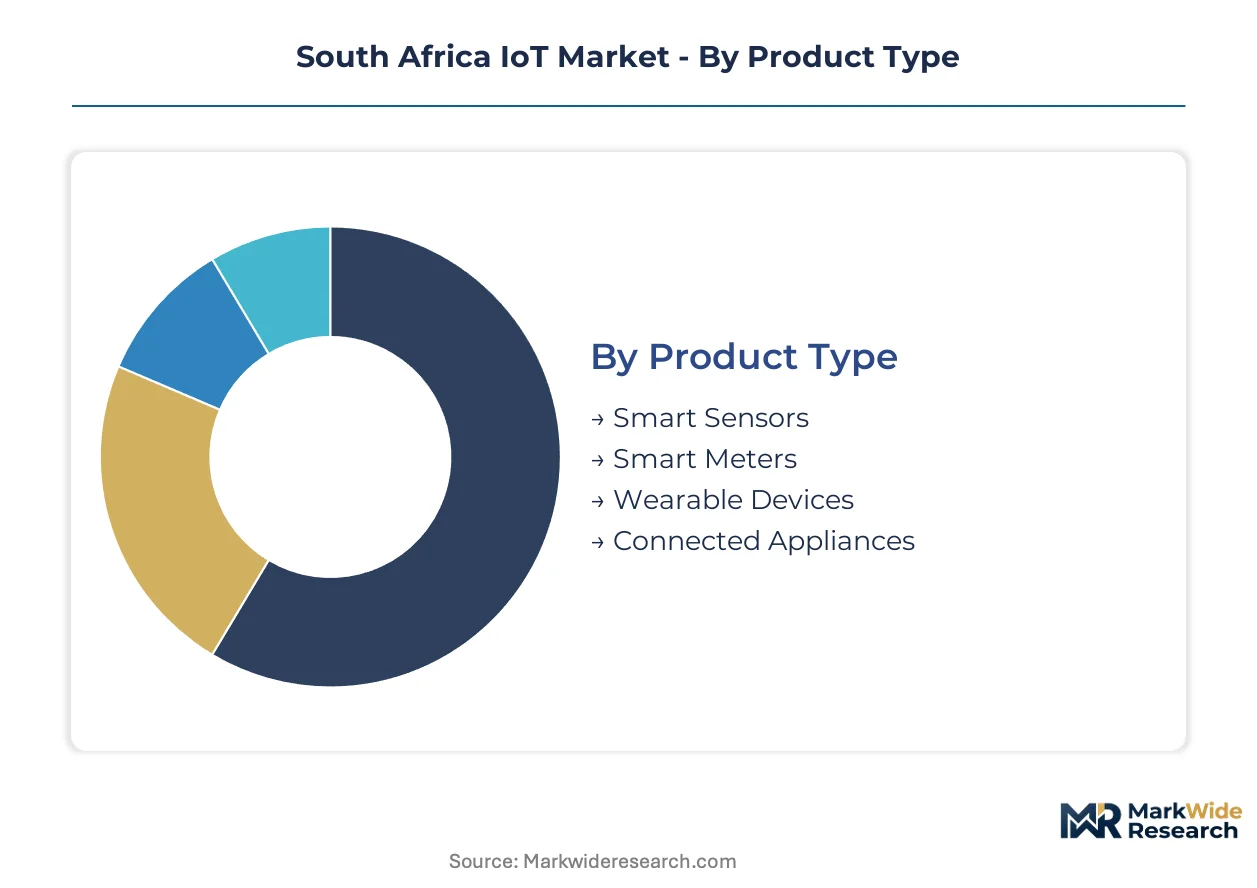
Segmentation in South Africa's IoT market reveals how procurement power concentrates across industrial buyers while connectivity economics reshape deployment patterns. Understanding these divisions exposes where substitution pressures and margin compression threaten incumbent positions.
Product Type:
Substitute technologies threaten Smart Sensors most acutely as edge-AI chips and computer vision systems displace discrete sensing hardware in mining and manufacturing environments.
- Smart Sensors:Devices integrating microelectromechanical systems with wireless transceivers for temperature, vibration, and pressure telemetry. Mining operators in Gauteng's platinum belt deploy these for predictive maintenance of haul trucks and processing equipment, though edge-AI cameras now compete for anomaly detection tasks.
- Smart Meters:Bi-directional communication endpoints measuring electricity, water, or gas consumption with remote disconnect capabilities. Eskom and municipal utilities in Johannesburg-Pretoria corridors drive procurement volumes as load-shedding necessitates granular demand-side management.
- Wearable Devices:Body-worn sensors tracking location, biometrics, or environmental exposure for workforce safety.
- Connected Appliances:White goods and HVAC equipment with IP connectivity for remote monitoring and energy optimization.
Smart Sensors anchors the volume base while Smart Meters gains share at the steepest rate as utility digitization accelerates.
End User:
Cost tier stratification separates capital-intensive sectors willing to bear upfront hardware costs from budget-constrained segments demanding subscription-based service models.
- Manufacturing:Automotive and process industries deploying shop-floor connectivity for OEE optimization and quality traceability. Smart factory investments concentrate in Gauteng's industrial corridors where Volkswagen, BMW, and Sasol operations anchor demand.
- Healthcare:Hospitals and clinics adopting remote patient monitoring and medical asset tracking. POPIA compliance costs elevate platform requirements for biometric data handling, constraining smaller facility adoption.
- Agriculture:Citrus and wine farming operations in Western Cape and Eastern Cape adopting precision irrigation and livestock monitoring.
- Transportation:Fleet operators and logistics hubs digitizing cargo tracking, cold chain verification, and route optimization.
Manufacturing commands the premium tier while Agriculture climbs fastest as LoRaWAN coverage expands into underpenetrated farming regions.
Connectivity:
Application requirements dictate protocol selection, with latency-sensitive use cases forcing trade-offs between coverage economics and real-time performance.
- Cellular:LTE-M and NB-IoT modems leveraging MTN and Vodacom tower density for wide-area coverage. Existing infrastructure enables rapid deployment across logistics and agricultural monitoring without greenfield network investment.
- LoRaWAN:Unlicensed sub-GHz mesh networks optimized for low-bitrate, battery-powered endpoints. Agricultural deployments in remote Eastern Cape citrus groves favor this technology where cellular backhaul remains uneconomical.
- Wi-Fi:High-throughput local area connectivity for in-building and campus environments.
- Zigbee:Mesh networking for smart home and building automation with low power requirements.
Cellular dominates revenue contribution while LoRaWAN expands most quickly in rural and agricultural white space.
Application:
Customer maturity separates established industrial automation from emerging consumer-facing platforms still navigating regulatory compliance.
- Industrial Automation:SCADA integration, predictive maintenance, and process control systems for mining and manufacturing. Anglo American and Sasol operations deploy NVIDIA Jetson-based edge gateways at scale for sub-100 millisecond safety shutdowns.
- Asset Tracking:Real-time location systems for fleet, cargo, and high-value equipment monitoring. Logistics operators digitizing Johannesburg-Durban freight corridors drive hardware and platform demand.
- Smart Home:Residential automation platforms for security, climate, and energy management.
- Health Monitoring:Consumer and clinical biometric tracking devices subject to POPIA data residency and consent management requirements.
Industrial Automation captures the largest revenue pool while Asset Tracking demonstrates the steepest expansion trajectory as logistics digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's IoT equipment and services flow predominantly into Sub-Saharan African markets, with Johannesburg-Pretoria industrial corridors serving as the regional distribution hub for connected infrastructure deployments.
Gauteng Province
Smart factory investments from Volkswagen, BMW, and Sasol operations drive hardware procurement volumes. ICASA's spectrum licensing reforms for IoT-specific bands accelerate network buildouts across the Johannesburg-Pretoria corridor. Mining operators in the platinum belt expand sensor deployments for predictive maintenance of haul trucks and processing equipment.
Western Cape
Citrus and wine farming operations adopt precision irrigation systems as LoRaWAN coverage expands into agricultural white space. The Protection of Personal Information Act imposes data governance requirements that elevate compliance costs for Cape Town-based health monitoring platforms. Municipal procurement departments consolidate vendor relationships through framework agreements for smart city pilots.
KwaZulu-Natal
Logistics operators digitizing Johannesburg-Durban freight corridors drive asset tracking hardware and platform demand. Cellular connectivity leveraging MTN and Vodacom tower density enables rapid deployment across port and warehousing operations. The province's manufacturing base anchors demand for SCADA integration and predictive maintenance systems.
Eastern Cape
Underpenetrated citrus farming regions present expansion opportunities for LoRaWAN-based irrigation and soil monitoring networks. Unreliable grid supply limits always-on sensor deployments without costly solar-battery backup systems. Remote metering deployments gain traction as utilities seek granular demand-side management capabilities.
Limpopo Province
Power infrastructure gaps constrain dense sensor networks in mining and agricultural applications. Mining operators deploy edge computing gateways with local inference capabilities to compress bandwidth costs and enable sub-100 millisecond safety shutdowns. Provincial utilities pilot smart meter rollouts to manage load-shedding impacts on rural consumers.
South Africa IoT Market Competitive Landscape
Player mix skews toward telecommunications operators and enterprise technology conglomerates with established infrastructure footprints. Market structure exhibits moderate consolidation around vertically integrated providers capable of delivering connectivity-hardware-software stacks. Three archetypes dominate: network operators bundling cellular IoT connectivity, industrial technology vendors anchoring mining and manufacturing deployments, and systems integrators bridging legacy SCADA with modern telemetry platforms. Competitive dynamics center on spectrum access negotiations and strategic partnerships with provincial utilities.
Among telecommunications operators, MTN Group and Vodacom Group occupy positions as connectivity backbone providers, while Cisco Systems exemplifies the industrial technology archetype through large-scale deployments across the mining belt. Huawei Technologies sits within the equipment supply tier through base station and module supply relationships with local operators.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems |
| MTN Group |
| SAP SE |
| Telkom SA Limited |
| Vodacom Group |
| Huawei Technologies |
| Dimension Data |
| Microsoft Corporation |
| Others |
Value Network & Pricing Analysis
ICASA's device certification regime gates both supply qualification and price differentiation simultaneously, as uncertified modules face market exclusion while ISO/IEC 27001 compliance elevates platform pricing tiers for enterprise buyers in Johannesburg-Pretoria corridors.
Pricing Analysis
Next-generation edge-AI chip pricing runs at multiples above prior-generation discrete sensors, compressing hardware margins for legacy telemetry vendors. Three-tier pricing structure across premium, standard, and economy levels separates POPIA-compliant health monitoring platforms from basic asset tracking hardware. Cost compression in cellular modem procurement is intensifying because currency volatility against Asian manufacturing clusters erodes local integrator margins. Municipal utility buyers exhibit highest price sensitivity, demanding subscription-based service models, while mining operators in the platinum belt accept upfront capital expenditure for sub-100 millisecond safety systems.
Supply Chain Analysis
Singapore-Johannesburg shipping lane congestion elevates lead time risk for NVIDIA Jetson and Arm-based edge processors sourced from Taiwanese semiconductor foundries. South African IoT hardware draws from Chinese cellular module manufacturers, South Korean memory suppliers, and German industrial sensor specialists. Single-source vulnerability concentrates in sub-1 GHz radio frequency components where Qualcomm and MediaTek dominate baseband supply. Distribution runs through Johannesburg-based systems integrators who bundle connectivity-hardware-software stacks for provincial utility framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LoRaWAN-5G interoperability standardization creates platform-economics inflection across South Africa's IoT landscape, as municipal procurement departments consolidate around single-vendor framework agreements.
For Market Incumbents: Compound MTN and Vodacom's tower density advantage through exclusive spectrum partnerships with ICASA for IoT-specific bands. Acquire Eastern Cape-based systems integrators to capture LoRaWAN agricultural white space before cellular densification reaches citrus groves. Edge-AI camera systems threaten discrete smart sensor margins; anchor predictive maintenance contracts through software-defined service tiers. For New Entrants and Emerging Players: ISO/IEC 27001 fast-track certification enables rapid entry into healthcare and critical infrastructure segments where audit queues delay incumbent contract renewals. Target underpenetrated Eastern Cape citrus farming regions with solar-powered LoRaWAN irrigation kits bundled with soil monitoring analytics. Partner with provincial municipalities on smart meter pilots to bypass multi-vendor integration complexity. For Investors and Strategic Acquirers: ICASA's pending domestic data residency mandates reshape the acquisition landscape toward local cloud and edge hosting providers with operational technology network certifications. Five-to-ten-year viability hinges on captive demand from mining operators digitizing predictive maintenance. Signal to watch: sub-1 GHz spectrum auction timeline announcements as inflection indicator for rural network densification capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Platform Integration | Anglo American and Sasol operations deploy NVIDIA Jetson gateways for sub-100 millisecond safety shutdowns. |
| LoRaWAN Network Expansion | Eastern Cape citrus groves gain coverage where cellular backhaul remains uneconomical for remote metering. |
| POPIA Compliance Certification | Health monitoring vendors in Cape Town restructure data flows to minimize cross-border biometric storage exposure. |
| Municipal Framework Consolidation | Gauteng smart city pilots displace multi-vendor integration through single-source connectivity-hardware-software contracts. |
| Spectrum Partnership Negotiation | MTN and Vodacom anchor competitive positioning through exclusive ICASA licensing for NB-IoT and LTE-M bands. |
Research Methodology
A standing panel of mining operations technology directors, municipal utility procurement managers, cellular network planning engineers, and agricultural systems integrators provided ongoing calibration across primary interviews combined with secondary validation. ICASA spectrum allocation records, Eskom smart meter deployment disclosures, MTN and Vodacom infrastructure capex filings, and ISO/IEC certification audit queues anchored bottom-up and top-down triangulation.
Consistency checks validated volume and value outputs against MTN Group's disclosed IoT connectivity subscriber metrics and Vodacom's reported machine-to-machine revenue trajectories across the analysis window. Segmentation dimensions modeled include product type, end-user industry, connectivity protocol, and application maturity tier. CAGRs derived from equipment procurement patterns in Gauteng's industrial corridors and utility digitization timelines in Western Cape and KwaZulu-Natal.
Decision-makers should treat outputs as directional under assumptions of ICASA spectrum auction progression and sustained mining capital expenditure; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
Solar Based Internet of Things (IoT) Market
Internet of Things (IoT)
North America IoT Software Market
Internet of Things (IoT)
AI in IoT Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Connected Bottles Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
Global Agile IoT Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
LPWAN in the Consumer IoT Market
Internet of Things (IoT)
IoT Services Market