
 Gutter and Downspout Market | 2026-2036
Gutter and Downspout Market Size, Share, and Industry Trends Forecast 2026-2036
Gutter and Downspout Market Insights
Big-box and pro-dealer distribution is tilting toward contractor-direct fulfillment models with faster lead times. Ply Gem Industries leverages its national fabrication network to sustain same-day availability for seamless aluminum profiles. Amerimax Building Products anchors its position through private-label partnerships with major home improvement retailers. OmniMax competes on coastal-grade vinyl formulations engineered for UV stability in subtropical zones.
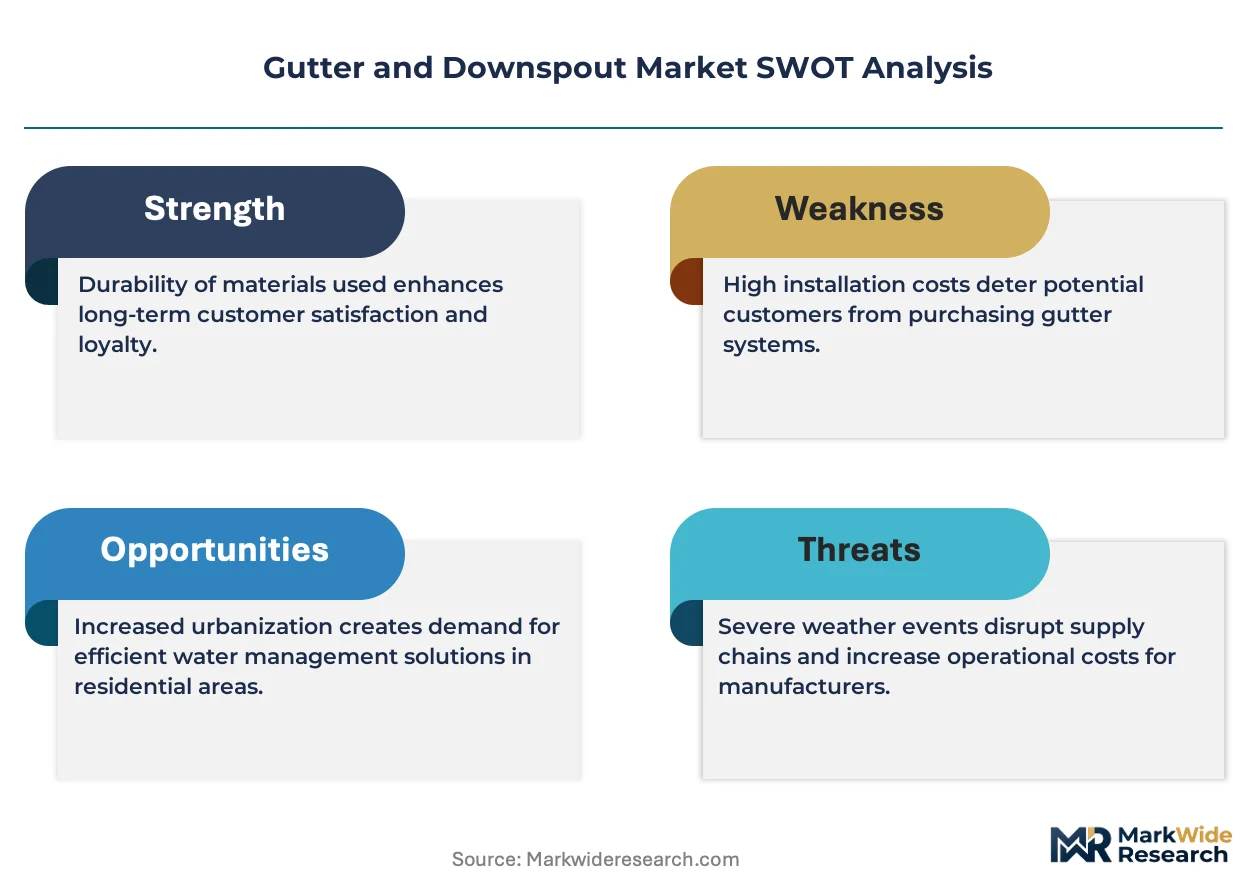
Gutters and downspouts constitute engineered rainwater collection and conveyance systems, typically fabricated from aluminum sheet stock between 0.027 and 0.032 inches thick, designed to intercept roof runoff and discharge it at controlled points away from building foundations. Residential application dominates volume, though commercial specifications command premium pricing through custom copper and built-in gutter configurations. Seamless aluminum leads product type share due to on-site roll-forming efficiency that eliminates leak-prone joints across long rooflines. DIY installation methods are gaining traction through snap-fit vinyl systems, while professionally installed seamless systems retain margin concentration in replacement markets.
EPA stormwater management guidelines and ICC building code provisions in flood-prone jurisdictions are mandating larger-diameter downspouts and splash-block integration for new construction. ASTM B209 material standards and AAMA 2604 coating specifications govern aluminum substrate performance, creating compliance barriers for imported commodity products. Stakeholders must monitor evolving municipal green infrastructure mandates that may shift specifications toward permeable discharge and rainwater harvesting compatibility.
Market Dynamics
Residential retrofit demand is compressing traditional distribution timelines as hurricane-prone jurisdictions mandate larger-capacity systems under updated ICC building codes, forcing manufacturers to reconfigure fabrication networks for same-day seamless aluminum fulfillment.
Growth Catalysts
- ICC Building Code Provisions:Flood-prone municipalities in the southeastern United States now require splash-block integration and oversized downspout diameters, accelerating replacement cycles for aging stock.
- Climate-Adaptive Specifications:Subtropical coastal zones specify UV-stabilized vinyl formulations engineered for intensifying rainfall patterns, creating material upgrade pull-through.
- Seamless Roll-Forming Efficiency:On-site fabrication eliminates leak-prone joints across extended rooflines, driving contractor preference in residential replacement markets.
Market Restraints
- Aluminum Sheet Volatility:Input cost swings for 0.027-0.032 inch coil stock squeeze margin predictability for fabricators serving price-sensitive retrofit segments.
- Import Compliance Barriers:ASTM B209 substrate standards and AAMA 2604 coating specifications block low-cost offshore commodity products from specification-grade projects.
- DIY Vinyl Substitution:Snap-fit homeowner systems capture entry-level volume, compressing addressable market for professionally installed seamless configurations.
Strategic Opportunities
- Rainwater Harvesting Integration:Municipal green infrastructure mandates in stormwater-managed jurisdictions open specification pathways for gutter-to-cistern connectivity.
- Contractor-Direct Fulfillment:Pro-dealer channels pivot to faster lead-time models, rewarding regional fabricators with distributed coil inventory.
- Copper Premium Segments:Built-in gutter configurations for custom residential and commercial specifications command pricing separation from commodity aluminum.
Industry Challenges
- Seamless Equipment Calibration:Mobile roll-forming fleets require skilled technicians for field-based profile consistency, constraining contractor scaling.
- Code Fragmentation:Jurisdiction-specific amendments to EPA stormwater guidelines create specification complexity for national distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gutter and Downspout Market |
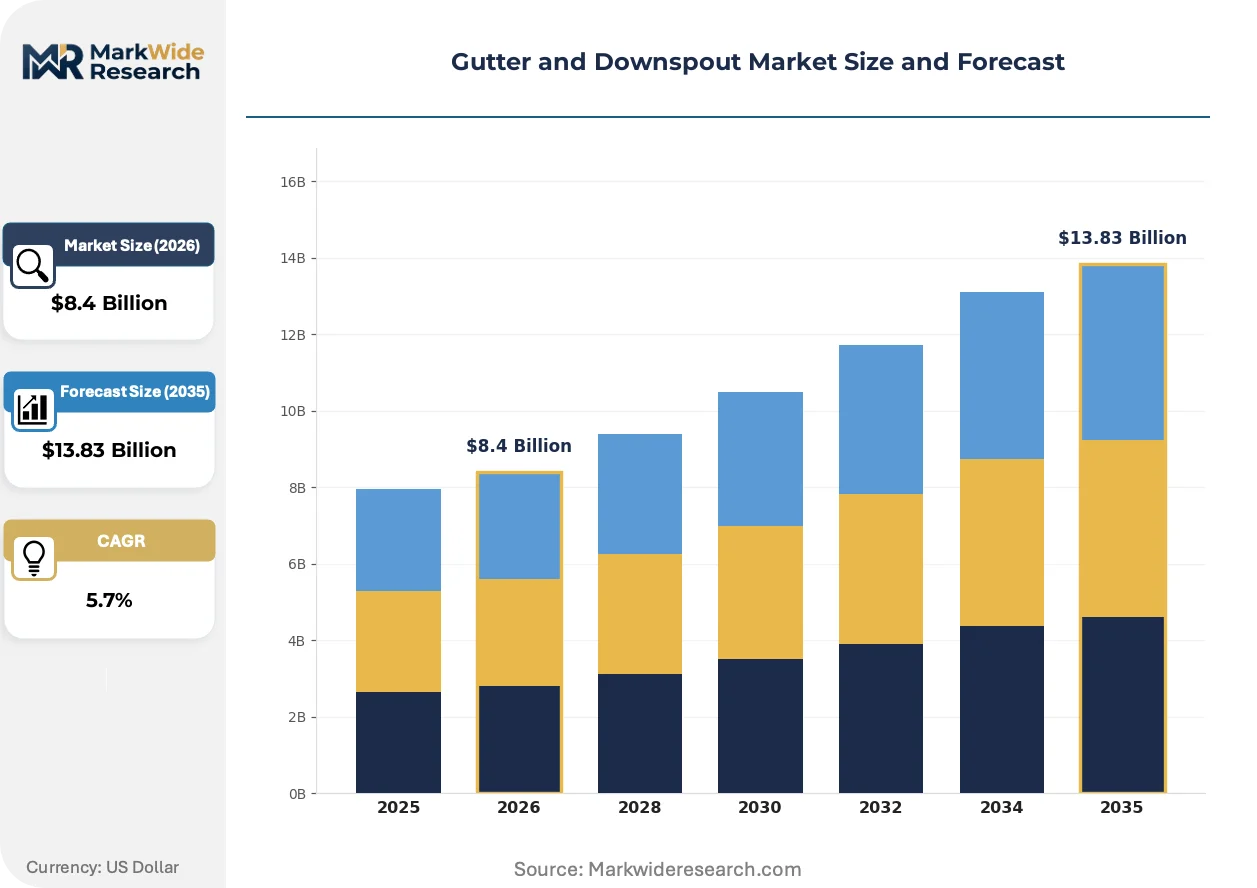
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Vinyl, Aluminum, Copper Application: Residential, Commercial, Industrial, Agricultural Installation Method: Professionally Installed, DIY, Prefabricated, Custom Component: Elbow, Hanger, Leader, Downspout Filter |
| Companies Covered | Alcoa Corporation, Ply Gem Industries, Spectra Metals, ABC Seamless, OmniMax, LeafGuard, Amerimax Building Products, Gibraltar Industries, Berger Building Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gutter and Downspout Market Trends and Innovations
Digital measurement and remote specification tools are compressing the design-to-installation cycle, while material science advances and procurement model evolution reshape competitive positioning across residential and commercial segments.
Drone-based roof measurement software is virtualizing the traditional manual surveying process that historically required on-site contractor visits. Large regional installers now adopt aerial dimensioning platforms to generate seamless gutter quotes within hours rather than days. This capability is virtualizing the competitive moat of established contractors with deep local market knowledge.
EPA stormwater management guidelines now mandate permeable discharge compatibility for new construction in designated flood zones. These provisions force gutter system designers to engineer integrated splash-block and infiltration trench interfaces. Commercial specifications in coastal Florida and Louisiana respond fastest, prioritizing systems with modular downspout extensions.
Homeowner buying patterns now favor bundled water-damage prevention packages over standalone gutter replacements. Insurance carriers in high-risk counties increasingly require documented gutter maintenance for policy renewal, shifting contractor sales conversations toward annual service contracts. This behavioral pivot concentrates in southeastern states where intensifying rainfall correlates directly with claims frequency.
Gutter and Downspout Market Segmentation
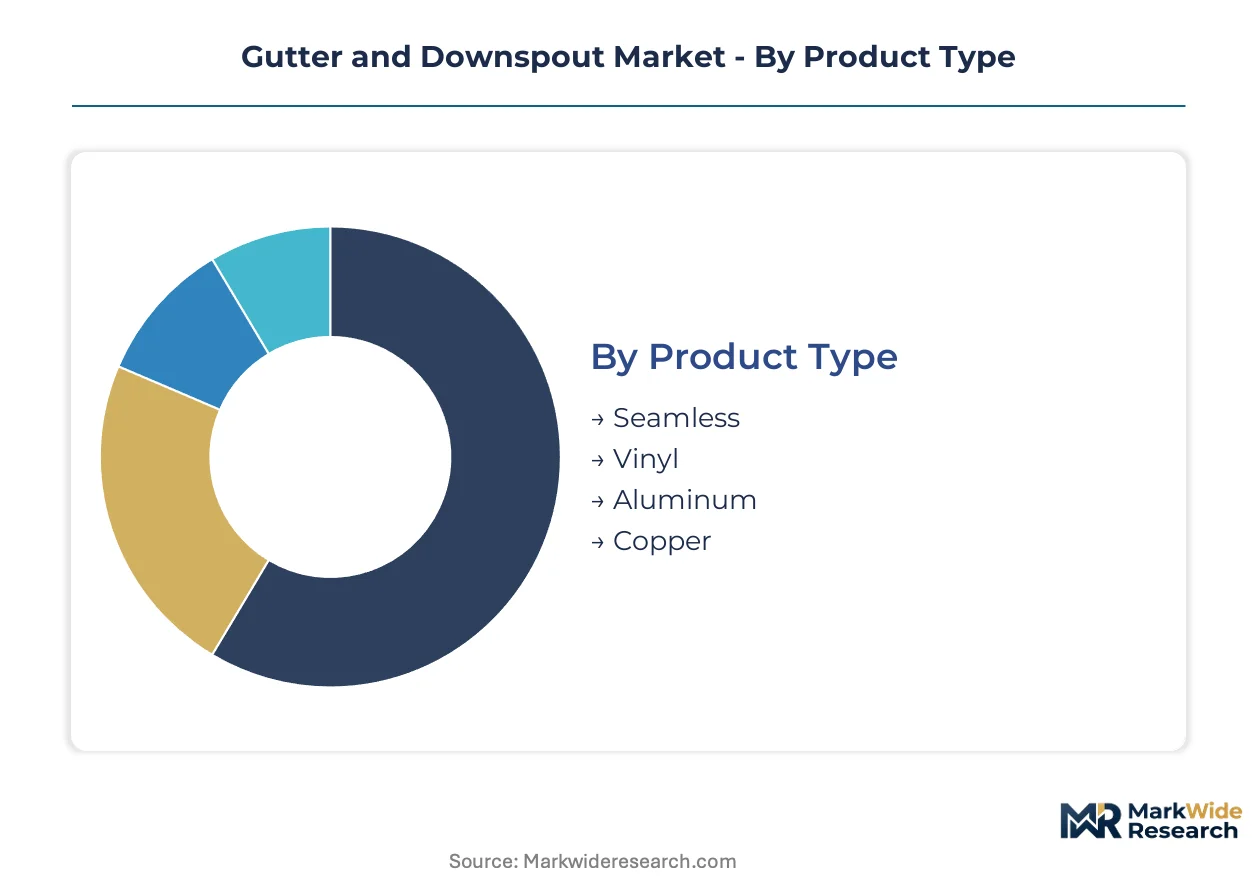
Gutter and downspout segmentation reveals divergent margin structures across material technologies and installation modalities. Product type and application splits determine fabrication network requirements, while installation method shapes channel economics and customer acquisition costs.
Product Type:
Mature aluminum and vinyl formats dominate volume, while copper and seamless configurations occupy distinct premium and efficiency positions respectively.
- Seamless:Fabricated on-site from continuous aluminum coil stock between 0.027 and 0.032 inches thick, eliminating longitudinal joints that concentrate leaks across extended rooflines. Demand concentrates in southeastern United States residential replacement markets where ICC building code upgrades force capacity expansion.
- Aluminum:Sectional profiles predominate in new construction specifications governed by ASTM B209 substrate standards and AAMA 2604 coating requirements, creating compliance barriers for import substitution.
- Vinyl:Snap-fit systems engineered for UV stability in subtropical coastal zones capture price-sensitive homeowner segments through big-box retail distribution.
- Copper:Built-in configurations for custom residential and historic restoration projects command substantial pricing separation through material scarcity and specialized installation craft.
Seamless retains volume leadership; copper holds the steepest expansion curve.
Application:
Residential retrofit volumes exceed new construction, while commercial specifications extract premium pricing through engineered performance requirements.
- Residential:Aging housing stock in hurricane-prone counties drives replacement cycles as insurance carriers mandate documented gutter maintenance for policy renewal eligibility.
- Commercial:Built-in gutter configurations and oversized downspout diameters respond to EPA stormwater management guidelines requiring permeable discharge compatibility in designated flood zones.
- Industrial:Heavy-gauge steel and stainless specifications address chemical exposure and structural loading requirements absent in standard residential formats.
- Agricultural:Large-capacity systems for barn and equipment storage structures prioritize functional durability over aesthetic integration.
Residential commands absolute volume; commercial delivers the highest margin per linear foot.
Installation Method:
Professional installation concentrates margin capture, while DIY formats expand addressable market through channel accessibility.
- Professionally Installed:Mobile roll-forming fleets and skilled technician deployment enable same-day seamless aluminum fulfillment, compressing traditional distribution timelines.
- DIY:Snap-fit vinyl systems reduce barrier to entry for homeowners in price-sensitive segments, though leakage risk rises with amateur slope calibration.
- Prefabricated:Modular sectional components ship to job sites for rapid assembly in multi-unit residential and light commercial applications.
- Custom:Site-fabricated copper and built-in configurations require specialized craft labor for historic preservation and architect-specified projects.
Professional installation captures the majority of replacement value; DIY is gaining share fastest in entry-level vinyl segments.
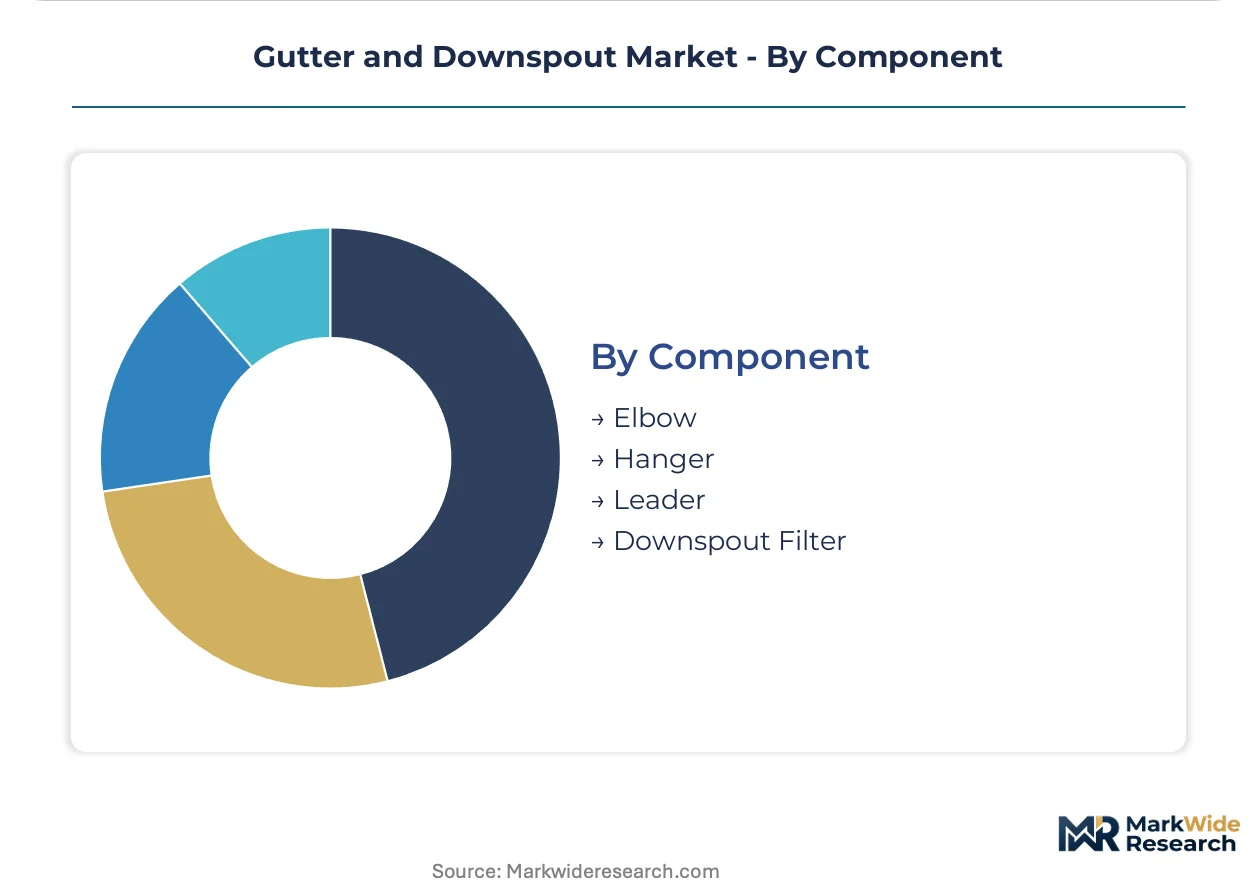
Component:
Downstream hardware specifications increasingly integrate with stormwater management infrastructure requirements.
- Elbow:Directional fittings at gutter-to-downspout transitions, with expanding diameters mandated by ICC code provisions in flood-prone municipalities.
- Downspout:Vertical conveyance elements now specified with splash-block integration and modular extension compatibility for infiltration trench interfaces.
- Hanger:Structural attachment hardware spacing determines system load capacity under intensifying rainfall patterns.
- Filter:Debris exclusion devices reduce maintenance frequency, with specification pull-through from insurance carrier maintenance documentation requirements.
Downspout dominates component value; filter attachments are climbing fastest as maintenance-contract bundling expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor supplies aluminum coil stock to fabrication networks across the Gulf Coast, underwriting southeastern US dominance in seamless gutter production capacity.
United States
Hurricane-prone counties from Florida to Louisiana drive replacement demand as ICC building codes mandate splash-block integration and oversized downspout diameters. EPA stormwater management guidelines in flood-designated zones force permeable discharge compatibility into new construction specifications. Atlanta anchors the southeastern fabrication cluster, where mobile roll-forming fleets compress same-day fulfillment timelines for residential retrofits.
Canada
Provincial building codes in Ontario and British Columbia emphasize rainwater harvesting integration for green infrastructure compliance. Natural Resources Canada efficiency standards shape material specifications for cold-climate durability. The Greater Toronto Area concentrates distribution networks serving cross-border demand from the US Northeast.
Germany
REACH chemical regulations and CE marking requirements govern coating formulations for aluminum substrates entering the European market. The country's national building energy efficiency programs incentivize stormwater management upgrades in existing housing stock. The Rhine-Ruhr industrial corridor hosts precision metalworking clusters supplying sectional gutter components.
China
GB standards for construction materials and MIIT industrial policy directives shape domestic manufacturing quality tiers. Dual carbon goals accelerate specification shifts toward recyclable aluminum systems in municipal green building projects. The Yangtze River Delta manufacturing belt concentrates coil stock production for both domestic consumption and export fabrication.
Australia
State-level plumbing codes in New South Wales and Queensland mandate debris exclusion devices for bushfire-prone construction zones. The country's national building regulator enforces stormwater detention requirements that integrate gutter-to-tank rainwater harvesting. Sydney anchors the southeastern distribution hub serving intensifying rainfall adaptation projects.
Gutter and Downspout Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and precision fabrication. The vendor base stratifies across three tiers: national roll-forming networks with distributed coil inventory, regional fabricators serving contractor-direct channels, and import-dependent distributors of commodity sectional products. Strategic archetypes include climate-adaptive material innovators, same-day fulfillment specialists, and rainwater harvesting integration engineers. Capacity expansion and private-label partnerships represent the dominant competitive moves reshaping channel economics.
Among North American fabricators, Ply Gem Industries and Amerimax Building Products exemplify the national platform tier, while OmniMax occupies a position within the coastal-grade specialization segment. Alcoa Corporation anchors the upstream aluminum supply tier as a coil stock provider rather than a downstream system integrator. These three named entities represent distinct strategic positions without implying specific market share or operational claims beyond their evident industry roles.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Ply Gem Industries |
| Spectra Metals |
| ABC Seamless |
| OmniMax |
| LeafGuard |
| Amerimax Building Products |
| Gibraltar Industries |
| Berger Building Products |
| Others |
Pricing and Supply Chain Analysis
Aluminum sheet coil volatility between 0.027 and 0.032 inch gauges compresses margin predictability for fabricators while simultaneously forcing tiered pricing spreads that separate ASTM B209-certified domestic producers from import-dependent commodity distributors. This input cost instability rewards backward-integrated manufacturers with captive coil supply while squeezing price-sensitive retrofit segments.
Pricing Analysis
Volume-discount tiering structures stratify across premium copper configurations, standard seamless aluminum systems, and economy vinyl snap-fit segments. Price differentiation rests on AAMA 2604 coating certification and ICC code compliance grade, with certified contractors commanding premium positioning over uncertified installers. Cost compression in the vinyl tier intensifies because big-box retail channel consolidation concentrates buying power among price-sensitive homeowners. DIY segments exhibit highest price sensitivity; custom copper and built-in gutter specifications demonstrate lowest elasticity due to scarcity of specialized craft labor.
Supply Chain Analysis
Upstream aluminum coil feedstock draws from primary smelting capacity concentrated in the United States, Canada, and China, with the Port of Houston's petrochemical corridor anchoring Gulf Coast fabrication networks. Secondary dependencies include vinyl resin formulations for UV-stabilized subtropical grades and copper sheet for premium architectural specifications. Tariff exposure on imported aluminum coil creates margin vulnerability for distributors lacking domestic mill relationships. Distribution runs through contractor-direct fulfillment models with regional fabricators maintaining distributed inventory for same-day seamless roll-forming deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gutter and downspout market sits at a code-driven inflection where ICC building code mandates for oversized downspouts and splash-block integration are compressing replacement cycles and rewarding climate-adaptive material innovators.
For Market Incumbents: Pre-empt DIY vinyl substitution by accelerating certification investment in AAMA 2604 coating compliance and ICC code-grade capacity expansion across southeastern fabrication clusters. Vertical control over aluminum coil inventory buffers margin pressure from spot price volatility while securing same-day fulfillment positioning against regional competitors. For New Entrants and Emerging Players: Rainwater harvesting integration for municipal green infrastructure mandates in stormwater-managed jurisdictions represents the most penetrable entry point, with gutter-to-cistern connectivity specifications still undersupplied by incumbent fabricators. Coastal Florida and Louisiana commercial specifications offer concentrated demand density for modular downspout extension systems. A go-to-market angle anchored in drone-based remote measurement platforms collapses design-to-quote timelines and virtualizes the local knowledge moat of established contractors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional fabricators with distributed coil inventory and contractor-direct channel control. Long-term viability across the analysis window rests on exposure to climate-adaptive specification upgrades rather than commodity aluminum volume. The signal to watch is municipal adoption velocity of green infrastructure mandates requiring permeable discharge compatibility, as this regulatory vector determines premium system pull-through rates.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Roll-Forming Fleet Expansion | Same-day seamless aluminum fulfillment compresses contractor acquisition costs in southeastern replacement markets. |
| Coastal-Grade Vinyl Formulation R&D | UV stability engineering for subtropical zones captures ICC code upgrade cycles in hurricane-prone counties. |
| Rainwater Harvesting System Integration | Gutter-to-cistern connectivity opens specification pathways under EPA stormwater management guidelines. |
| Private-Label Retail Partnership | Big-box channel access defends volume position against DIY snap-fit substitution in entry-level segments. |
| Copper Built-In Gutter Capacity | Specialized craft labor scarcity in custom residential commands pricing separation from commodity aluminum. |
Research Methodology
A spread of perspectives from seamless gutter fabricators, mobile roll-forming fleet operators, big-box retail category managers, and municipal building code officials converged on the working assumptions underlying demand projections. Secondary validation drew from ICC building code amendment records, EPA stormwater management guideline publications, ASTM B209 material standard documentation, and AAMA coating specification databases. Bottom-up triangulation across residential retrofit permit data and top-down reconciliation against aluminum coil consumption patterns anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation modeling across product type, installation method, application, and regional climate zone. CAGRs derived from replacement cycle compression analysis under intensifying rainfall patterns and code mandate adoption curves. Industry-specific forecast inputs included insurance carrier maintenance documentation requirements and municipal green infrastructure mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in residential construction activity, aluminum commodity pricing, or municipal infrastructure spending authorization would shift the trajectory. Forecasts reflect documented assumptions regarding ICC code adoption velocity and climate pattern intensification. Cross-checking against regional building permit issuance data and coil stock inventory reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Europe Green Buildings Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
US Commercial Windows Market