
 Water and Wastewater Treatment Technologies Market | 2026-2036
Water and Wastewater Treatment Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Water and Wastewater Treatment Technologies Market Intelligence
The legacy skill base of analog-era plant operators is collapsing under the weight of digitally integrated treatment systems. Xylem Inc. leverages its digital platforms to automate complex processes, reducing reliance on specialized onsite labor. Veolia Water Technologies sustains its market position through comprehensive service contracts that include system operation and maintenance. Ecolab Inc. specializes in providing managed water services for industrial clients, bundling technology with expert support.
Water and wastewater treatment technologies encompass physical, chemical, and biological processes designed to remove contaminants from water sources. These systems often target specific pollutants, achieving removal efficiencies down to parts-per-billion levels to meet quality standards. Membrane filtration technologies lead the market due to their effectiveness in desalination and reuse applications for industrial effluent. Among end users, municipal supply remains the largest segment, while treatment for food & beverage plants represents the fastest-growing opportunity.
Regulatory frameworks from bodies like the US EPA and China's MEE establish strict limits on pollutant discharge, compelling investment in advanced treatment. In Europe, the EU's Urban Wastewater Treatment Directive further mandates nutrient removal and micro-pollutant monitoring, shaping technology choices. Stakeholder decisions now center on balancing the high capital cost of advanced systems against the long-term operational savings and compliance benefits.
Market Dynamics
The central tension shaping the market is the widening gap between stringent regulatory mandates for micropollutant removal and the capital constraints of municipal and industrial operators, forcing a re-evaluation of technology lifecycle costs versus compliance risks.
Growth Catalysts
- Regulatory Mandates:The EU's revised Urban Wastewater Treatment Directive compels investment in tertiary treatment technologies for nutrient and micropollutant removal, directly stimulating demand for advanced filtration and disinfection systems across member states.
- Industrial Effluent Standards:Rapidly expanding food and beverage processing sectors in economies like India and Brazil require advanced biological and membrane-based treatment systems to meet strict local pollution control board discharge limits.
- Water Scarcity:Increasing water stress in arid regions is driving large-scale investment in desalination and water reuse infrastructure, particularly for reverse osmosis and ultrafiltration membranes in municipal and agricultural applications.
Market Restraints
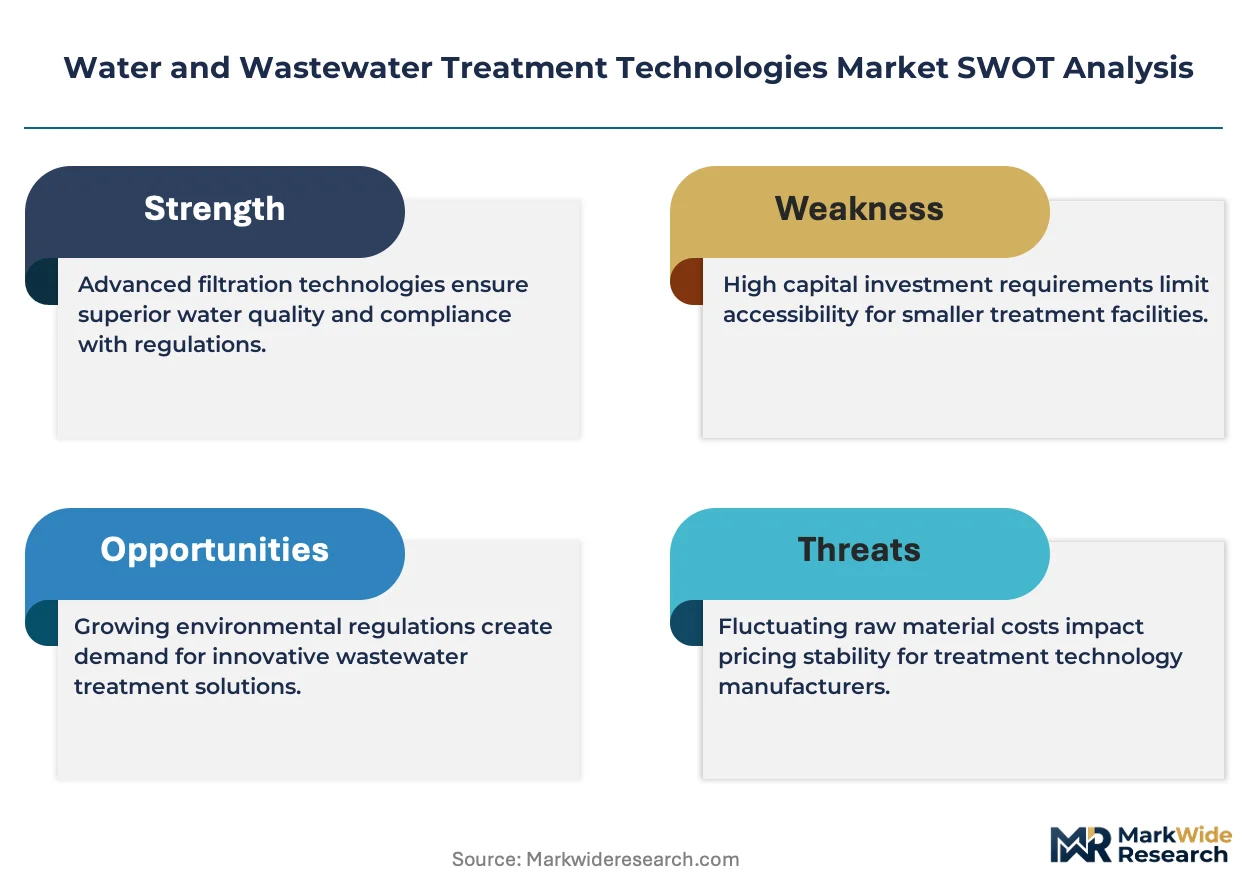
- High Capital Costs:The significant upfront investment required for advanced treatment technologies, such as membrane bioreactors or advanced oxidation processes, remains a primary barrier for smaller municipalities and industrial facilities with limited capital budgets.
- Energy Consumption:Energy-intensive processes like reverse osmosis for desalination and aeration in biological treatment represent a substantial operational cost, limiting adoption where electricity prices are high or supply is unreliable.
- Chemical Input Volatility:The operational cost and supply chain stability of essential treatment chemicals, including coagulants, disinfectants, and pH adjusters, present a significant financial and logistical hurdle for plant operators.
Strategic Opportunities
- Resource Recovery:Technologies that recover valuable resources such as phosphorus, nitrogen, and biogas from wastewater streams are creating new revenue opportunities for treatment facilities, shifting their role from cost centers to resource hubs.
- Decentralized Systems:The development of compact, containerized treatment units provides a flexible solution for remote communities, industrial sites, and new real estate developments, bypassing the need for extensive centralized sewer networks.
- Digital Twin Integration:Integrating AI-powered digital twins with physical plant operations enables predictive maintenance, process optimization, and energy reduction, offering a high-value service opportunity for technology providers.
Industry Challenges
- Skills Shortage:A persistent lack of trained operators and technicians proficient in managing automated, digitally controlled treatment systems complicates plant operations and maintenance, particularly for advanced technology deployments.
- Legacy System Integration:Retrofitting new treatment modules into aging infrastructure presents considerable engineering complexity, often leading to extended downtime, cost overruns, and performance compatibility issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water and Wastewater Treatment Technologies Market |
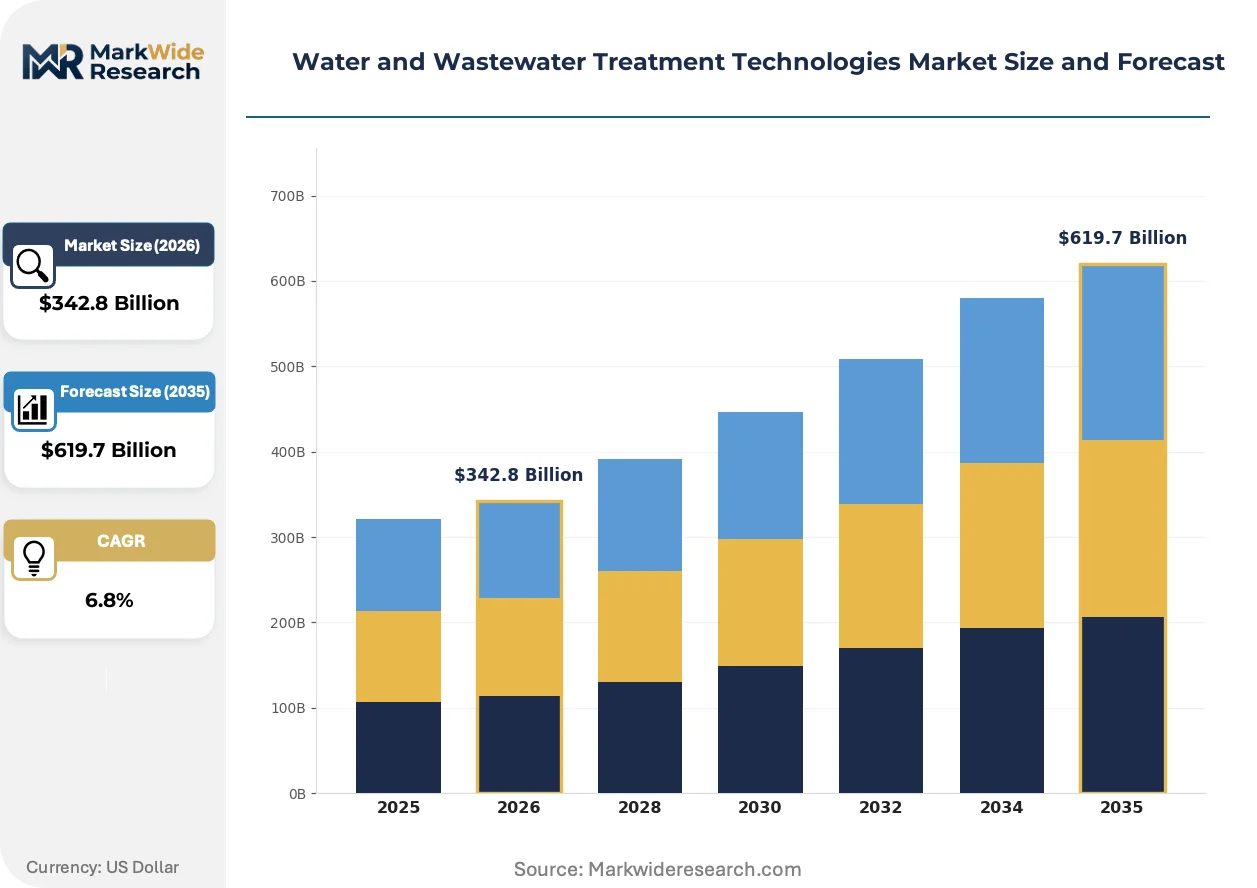
| Market Size in 2026 | $342.8 Billion |
| Market Size in 2035 | $619.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Filtration, Ultraviolet Disinfection, Ion Exchange, Coagulation & Flocculation, Activated Carbon Adsorption, Biofiltration Application: Municipal Supply, Industrial Effluent, Agricultural Runoff, Stormwater Management, Recycled Water, Greywater Treatment End User: Water Utilities, Food & Beverage Plants, Power Generation, Chemical Manufacturers, Textile Processors, Hospitality Facilities Deployment: Centralized Plants, Decentralized Systems, Mobile Units, Onsite Treatment, Modular Units, Bulk Water Stations |
| Companies Covered | Xylem Inc., Aquatech International LLC, Veolia Water Technologies, Ecolab Inc., Culligan International Company, SUEZ Water Technologies & Solutions, Pentair plc, Danaher Corporation, Evoqua Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water and Wastewater Treatment Technologies Market Strategic Shifts & Innovations
Resource recovery is fundamentally altering the value proposition of wastewater treatment. The industry's focus is shifting from simple contaminant disposal to creating circular economy loops, where water, energy, and nutrients are reclaimed and repurposed, transforming treatment facilities into valuable resource generators.
Advanced Oxidation Processes (AOPs) combine agents like ozone, hydrogen peroxide, and UV light to destroy persistent organic pollutants. Industrial facilities, particularly in the pharmaceutical and chemical sectors, are adopting AOPs to meet stringent regulations on micropollutants. This technology's ability to mineralize complex, non-biodegradable compounds is decomposing the traditional boundary between water treatment and hazardous waste destruction.
The US EPA's health advisories and proposed standards for PFAS chemicals are forcing a nationwide technology upgrade cycle. This action compels public water systems to invest in granular activated carbon, ion exchange resins, or high-pressure membrane systems capable of removing these compounds to non-detectable levels. The municipal water segment is most affected, triggering rapid procurement of specialized treatment solutions.
A shift toward mobile and modular treatment solutions is gaining traction among industrial users. These "Water-as-a-Service" models, often provided on a lease or pay-per-volume basis, bypass long capital budget cycles and allow for flexible capacity scaling. This trend is most apparent in sectors like mining and construction, particularly in Latin America, where temporary or remote operational sites require rapid deployment.
Water and Wastewater Treatment Technologies Market Segmentation
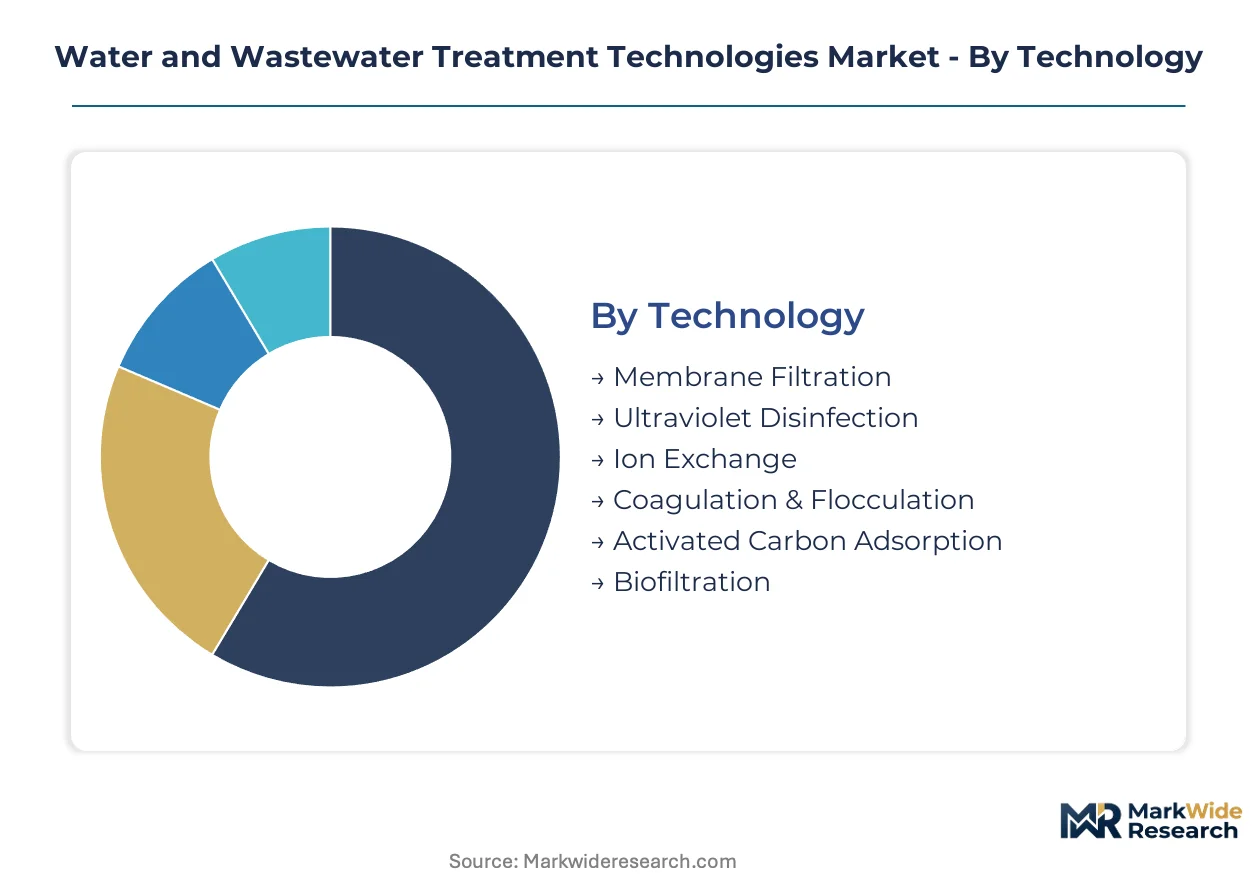
Understanding market segmentation is critical for technology providers to align their solutions with specific operational needs and regulatory compliance requirements. This granular view reveals where investment is concentrating and where specialized expertise can command higher value within the water treatment ecosystem.
Technology:
Margin pools within the technology segment often concentrate around advanced solutions addressing complex contaminants or enabling resource recovery.
- Membrane Filtration:These technologies, including reverse osmosis and ultrafiltration, physically remove suspended solids, dissolved salts, and microorganisms from water. Demand is strong in arid regions like the Middle East for desalination and in industrial sectors for high-purity process water.
- Biofiltration:Utilizing biological processes, biofiltration systems remove organic matter, nitrogen, and phosphorus from wastewater streams. Food & beverage processing plants in India increasingly adopt biofiltration to meet stringent effluent discharge limits.
- Ultraviolet Disinfection:UV systems use germicidal lamps to inactivate pathogens without chemicals, finding application in municipal drinking water and industrial wastewater disinfection.
- Ion Exchange:This process removes dissolved ionic contaminants like hardness, nitrates, and heavy metals, crucial for industrial boiler feed water and specialized purification.
- Coagulation & Flocculation:These chemical processes destabilize and aggregate suspended particles for easier removal, a foundational step in many municipal and industrial treatment trains.
- Activated Carbon Adsorption:Activated carbon effectively removes organic micropollutants, odors, and chlorine, widely used in drinking water purification and industrial chemical removal.
The dominant share belongs to Membrane Filtration, while Biofiltration and Activated Carbon Adsorption represent the fastest-growing opportunities.
Application:
The cost tier of treatment solutions varies significantly across these applications, reflecting differing water quality standards and discharge regulations.
- Municipal Supply:Treatment for municipal drinking water involves comprehensive processes to meet public health standards, often requiring multiple filtration and disinfection stages. Cities across Europe are upgrading infrastructure to comply with stricter EU Urban Wastewater Treatment Directive mandates.
- Industrial Effluent:This segment addresses wastewater from manufacturing processes, demanding tailored solutions to remove specific pollutants before discharge or reuse. Chemical manufacturers in China utilize advanced oxidation processes to manage complex organic compounds.
- Agricultural Runoff:Managing nutrient and pesticide-laden water from agricultural lands requires treatment systems focused on preventing eutrophication and protecting aquatic ecosystems. Solutions often involve natural wetlands or bioreactors.
- Stormwater Management:Systems designed to treat rainwater runoff mitigate pollution from urban surfaces before it enters natural water bodies. These applications typically involve physical filtration and sedimentation.
- Recycled Water:Treating wastewater to a standard suitable for non-potable uses like irrigation or industrial cooling reduces reliance on fresh water sources. This application gains traction in water-stressed areas such as California.
- Greywater Treatment:Processing wastewater from sinks, showers, and laundry for reuse in toilets or irrigation offers localized water savings in residential and commercial buildings.
While Municipal Supply commands the largest volume, Industrial Effluent exhibits the steepest expansion trajectory.
End User:
Different customer types drive distinct technology choices and service models within the water treatment market.
- Water Utilities:These entities manage public water supply and wastewater treatment for municipalities, requiring large-scale, robust, and often digitally integrated systems. Utilities in the US are investing in PFAS removal technologies to meet emerging EPA health advisories.
- Food & Beverage Plants:This sector requires high-purity process water and treats complex organic-rich effluent, often necessitating advanced biological and membrane systems. Brazilian beverage producers are implementing reuse systems to manage water scarcity.
- Power Generation:Power plants demand ultra-pure water for boiler feed and cooling, employing demineralization and membrane technologies to prevent scaling and corrosion. This sector also manages large volumes of cooling tower blowdown.
- Chemical Manufacturers:These facilities produce highly variable and often toxic wastewater streams, driving demand for specialized treatment like advanced oxidation processes and robust filtration. Compliance with MEE standards in China is a key driver.
- Textile Processors:The textile industry generates effluent with high color, organic load, and chemical content, requiring specific treatment for dye removal and chemical breakdown. This sector faces increasing regulatory pressure in Southeast Asian economies.
- Hospitality Facilities:Hotels and resorts often implement compact treatment systems for greywater recycling and on-site wastewater management, especially in remote or water-scarce locations.
The established demand from Water Utilities provides market stability, as Food & Beverage Plants rapidly gain significance.
Deployment:
The maturity of deployment models ranges from traditional large-scale infrastructure to agile, temporary solutions.
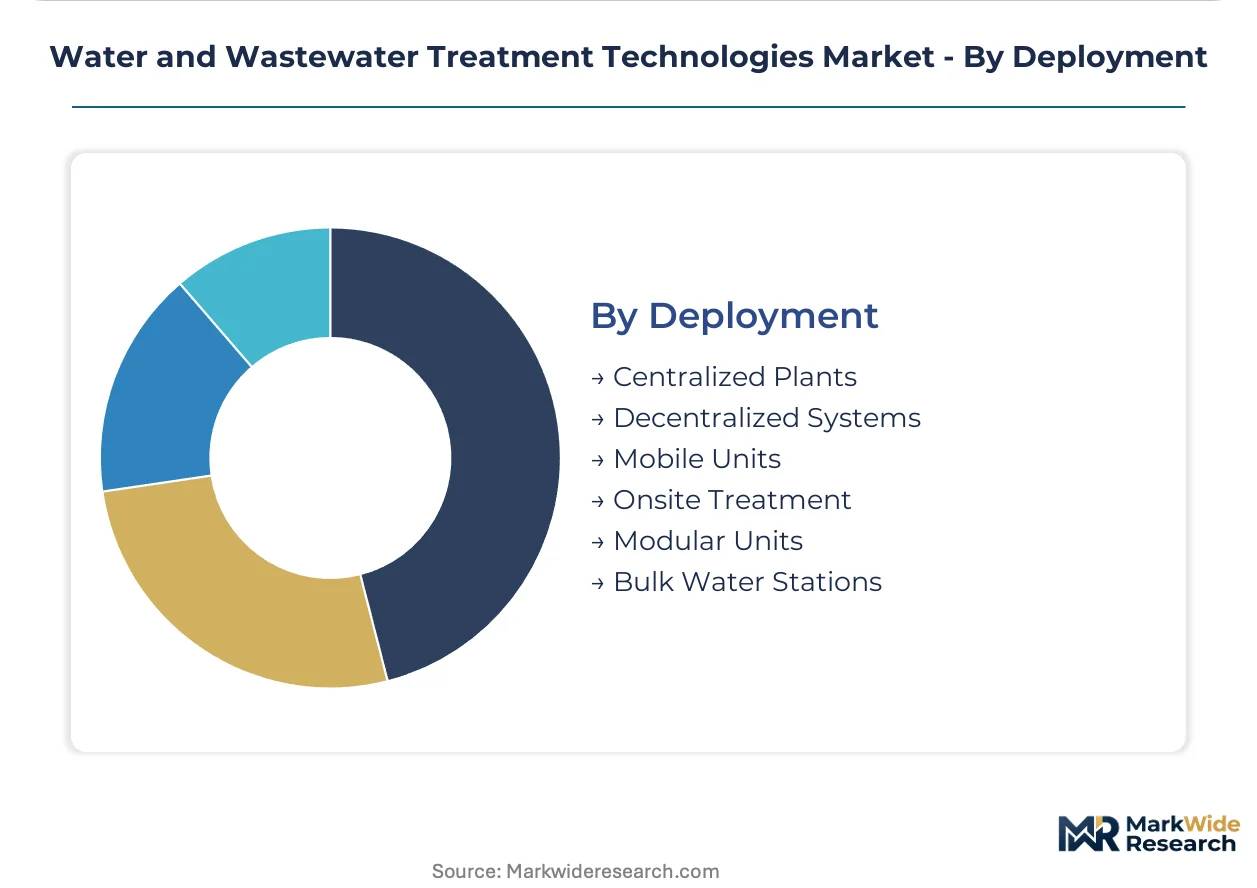
- Centralized Plants:These large-scale facilities serve entire cities or industrial zones, processing vast volumes of water through complex, multi-stage treatment processes. They represent the conventional approach for municipal wastewater management.
- Decentralized Systems:Smaller, distributed treatment units serve specific communities, industrial parks, or remote locations, reducing the need for extensive pipeline networks. These systems are gaining favor in new real estate developments.
- Mobile Units:Containerized, transportable treatment systems provide flexible solutions for temporary needs, disaster relief, or remote industrial operations. Mining sites in Latin America frequently utilize mobile water-as-a-service models.
- Onsite Treatment:Integrated within industrial facilities or commercial buildings, onsite systems treat water at the point of use or discharge. This approach minimizes transport costs and allows for immediate reuse.
- Modular Units:Pre-engineered and factory-assembled components allow for rapid deployment and scalable expansion of treatment capacity. These units are popular for industrial clients seeking quick setup.
- Bulk Water Stations:These facilities provide treated water for distribution to communities or industries, often serving as critical infrastructure in regions with limited local water sources.
Large-scale infrastructure remains foundational, but flexible solutions like Decentralized Systems are gaining considerable traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US EPA's stringent health advisories for contaminants like PFAS compounds are compelling significant investment across municipal water systems. This regulatory pressure, combined with industrial expansion and water scarcity, shapes regional demand for advanced treatment technologies. Diverse economic and environmental factors drive localized market dynamics.
United States
Demand for advanced treatment systems in the United States stems from aging infrastructure and emerging contaminant regulations. The US EPA's health advisories for PFAS chemicals necessitate rapid upgrades in public water systems. Cities like Flint, Michigan, are investing heavily in comprehensive water treatment solutions to address historical contamination issues.
Germany
Germany's market for water treatment technologies is driven by robust industrial output and strict environmental protection standards. The EU's Urban Wastewater Treatment Directive mandates advanced nutrient and micropollutant removal across German municipalities. Industrial clusters in the Ruhr region require sophisticated effluent treatment to manage complex chemical discharges.
China
Rapid industrialization and urbanization in China fuel substantial demand for water and wastewater treatment solutions. The Ministry of Ecology and Environment (MEE) enforces strict discharge limits for industrial effluent, particularly in manufacturing hubs. Chemical manufacturers in the Yangtze River Delta utilize advanced oxidation processes for complex organic compound removal.
India
India's expanding food and beverage processing sectors, alongside growing municipal needs, create significant opportunities for water treatment technologies. Local pollution control boards enforce stringent effluent standards for industrial facilities. Cities such as Chennai face increasing water stress, driving investment in desalination and reuse infrastructure.
Brazil
Water scarcity and agricultural runoff challenges in Brazil are stimulating investment in water treatment and reuse. Strict environmental regulations govern industrial discharge, particularly from the food and beverage industry. Beverage producers in São Paulo are implementing advanced biological and membrane systems for water recycling.
Water and Wastewater Treatment Technologies Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the water and wastewater treatment technologies market. The market structure exhibits a tiered consolidation, with large multinational corporations offering comprehensive solutions alongside specialized technology providers. Strategic partnerships and portfolio diversification represent dominant competitive moves among these players.
Companies focused on comprehensive service offerings and integrated digital platforms, such as Xylem Inc. and Veolia Water Technologies, anchor the premium segment. These entities provide end-to-end solutions spanning design, installation, operation, and maintenance. Ecolab Inc. occupies a position among managed water services providers, bundling technology with expert support for industrial clients.
| Leading Market Players |
|---|
| Xylem Inc. |
| Aquatech International LLC |
| Veolia Water Technologies |
| Ecolab Inc. |
| Culligan International Company |
| SUEZ Water Technologies & Solutions |
| Pentair plc |
| Danaher Corporation |
| Evoqua Water Technologies |
| Others |
Cost & Logistics Intelligence
Average project lead times for advanced membrane systems, often exceeding six months, reflect a complex supply chain and influence project-based pricing, driving higher costs for urgent deployments.
Pricing Analysis
Geographic price spreads for advanced water treatment solutions reveal significant disparities, with higher costs in regions like Europe due to stringent regulations compared to more competitive markets in Asia. Project-based pricing dominates for large infrastructure, while managed water services often use subscription models. After-sales service and high customization levels differentiate offerings. Pricing softness affects commoditized components, while advanced systems command premiums due to R&D. Municipalities exhibit high price sensitivity, balancing capital costs with long-term compliance benefits.
Supply Chain Analysis
Increased inbound logistics costs, particularly for specialized membrane modules and chemical inputs, impact the overall cost structure of water treatment systems. Supply concentrates in China for commodity components and in Germany for advanced filtration technologies. The industry relies on polymers for membranes and specific chemicals like coagulants. Single-source vulnerability for proprietary sensor technology poses a structural supply chain risk. Distribution runs through direct sales for large municipal projects and specialized distributors for industrial chemicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents significant fragmentation opportunities as diverse needs emerge across end-user segments. The imperative for micropollutant removal, driven by evolving regulatory mandates, creates specialized niches for advanced treatment solutions.
For Market Incumbents:Compound existing service contracts with digital twin integration to reduce reliance on onsite labor and mitigate margin pressure from commoditized offerings. Acquire niche technology providers specializing in PFAS removal or advanced oxidation processes to counter emerging regulatory threats. Invest in R&D for next-generation membrane materials, securing long-term intellectual property. Strengthen channel control through comprehensive operation and maintenance agreements.
For New Entrants and Emerging Players:Anchor in specialized niches like decentralized treatment systems or mobile Water-as-a-Service models. The most penetrable segment lies within remote industrial sites and new real estate developments seeking agile, capital-light solutions. Offer outcome-based contracts focused on resource recovery, transforming wastewater from a cost to a revenue stream. Leverage compact, modular designs for rapid deployment and flexible capacity scaling.
For Investors and Strategic Acquirers:Long-term, this sits as an essential infrastructure play because water scarcity and regulatory compliance will drive perpetual demand. Target technology specialists in advanced oxidation processes, digital twin integration, or resource recovery solutions. These firms offer high-value intellectual property and recurring service revenues. A significant inflection indicator is increased government spending on water infrastructure upgrades or expanded mandates for emerging contaminant removal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Membrane Manufacturing | Meeting rising demand for desalination and high-purity industrial process water. |
| Digital Platform Integration | Automating complex processes, reducing reliance on specialized onsite labor for Xylem Inc. |
| Advanced Oxidation Process R&D | Addressing persistent organic pollutants and stringent discharge regulations for chemical manufacturers. |
| Water-as-a-Service Offering Expansion | Providing flexible, capital-light treatment solutions for industrial clients in Latin America. |
| Resource Recovery Technology Investment | Transforming wastewater facilities into revenue-generating resource hubs for municipalities. |
Research Approach
Findings reconcile primary fieldwork against secondary review of US EPA reports, EU Urban Wastewater Treatment Directive documents, and MEE environmental standards. This involved extensive interviews with water utility managers, industrial plant engineers, regulatory compliance officers, and technology R&D leads. Data triangulation occurred through both bottom-up market sizing and top-down validation of segment projections. Industry association publications also provided critical contextual information.
Segmentation dimensions modeled include technology, application, end user, deployment, and specific contaminant types like PFAS compounds. The analytical framework projects market growth across the analysis window, with compound annual growth rates derived from historical trends, identified market drivers, and expert consensus. Key industry-specific forecast inputs include regional water stress indices and industrial output growth rates for sectors like food & beverage.
Material uncertainties — unforeseen geopolitical events, rapid shifts in energy prices, or disruptive technological breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and sustained investment in water infrastructure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market