
 Global Boiler Water Treatment Chemicals Market | 2026-2036
Global Boiler Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boiler Water Treatment Chemicals Market Foresight
Premium oxygen scavenger formulations is decoupling from commodity sulfite chemistry on total cost of ownership metrics. Ecolab leverages integrated digital monitoring platforms to sustain long-term service contracts with electric utilities. Kurita Water Industries Ltd anchors Asian manufacturing scale through localized polymer production. Solenis competes on rapid-response technical service for pulp and paper boiler systems.
Boiler water treatment chemicals comprise oxygen scavengers, scale inhibitors, corrosion inhibitors, pH adjusters, and dispersants formulated to prevent deposition, pitting, and steam contamination in pressurized steam generators. These chemistries typically operate at alkalinities of 200–400 ppm and temperatures exceeding 150°C to maintain heat transfer efficiency and prevent tube failures. Corrosion inhibitors occupy the deepest margin pools due to metallurgical specificity and custom blending requirements. Oxygen scavengers represent the fastest-growing product category as ultra-supercritical power plants adopt catalyzed bisulfite and hydrazine alternatives. Scale inhibitors remain mature in commodity phosphonate applications but evolve toward polymer-based threshold inhibition for high-pressure boilers.
The US EPA enforces effluent limitation guidelines that restrict boiler blowdown discharge of phosphate and heavy metal residuals, forcing facilities toward zero-liquid-disclosure chemistries. The EU REACH regulation and ECHA substance evaluations constrain chromate-based corrosion inhibitor formulations, redirecting R&D toward molybdate and organic film-forming alternatives. China's MEE mandates stricter thermal power plant water recycling rates, accelerating demand for high-performance dispersant packages. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration investments with regional compliance timelines.
Market Dynamics
Ultra-supercritical power plant expansion is compressing chemical specification windows, forcing reformulation of oxygen scavengers and scale inhibitors for 620°C steam temperatures and 300+ bar pressures. This thermal ratchet is restructuring supplier R&D priorities across the value chain.
Growth Catalysts
- China's MEE water recycling mandates:Thermal power operators must achieve closed-loop cooling, accelerating demand for high-performance dispersant packages in retrofit programs.
- EU F-Gas Regulation phase-down:Refrigerant chemistry restrictions are redirecting industrial cooling budgets toward boiler efficiency investments and heat recovery systems.
- Polymer-based threshold inhibition:Advanced copolymer chemistries enable 10–15% higher cycle concentrations in high-pressure boilers, reducing blowdown volumes.
Market Restraints
- Phosphonate input cost volatility:Phosphoric acid and phosphorus pentoxide prices swing with fertilizer sector demand, compressing margins on commodity scale inhibitors.
- Chromate formulation sunset:ECHA substance evaluations and REACH authorization timelines are forcing immediate R&D redirection, straining smaller blenders without molybdate alternatives ready.
- Electrodeionization substitution:High-purity water systems in semiconductor and pharmaceutical plants are displacing chemical treatment in low-pressure steam applications.
Strategic Opportunities
- India's coal fleet modernization:NTPC and state gencos are retrofitting 1970s-era units with automated chemical feed systems, creating greenfield service contract potential.
- Biodegradable film-forming amines:Convergence of corrosion inhibition and environmental compliance is opening premium positioning for oleic acid imidazoline derivatives.
- Digital twin integration:Real-time boiler water chemistry optimization through IoT sensors is enabling subscription-based technical service models.
Industry Challenges
- Certified water chemist scarcity:Power plant retirements are draining experienced operators who understand coordinated phosphate-pH programs, complicating knowledge transfer.
- Legacy DCS integration friction:1990s-era distributed control systems in industrial boilers lack data architecture for modern chemical monitoring platforms, requiring costly middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boiler Water Treatment Chemicals Market |
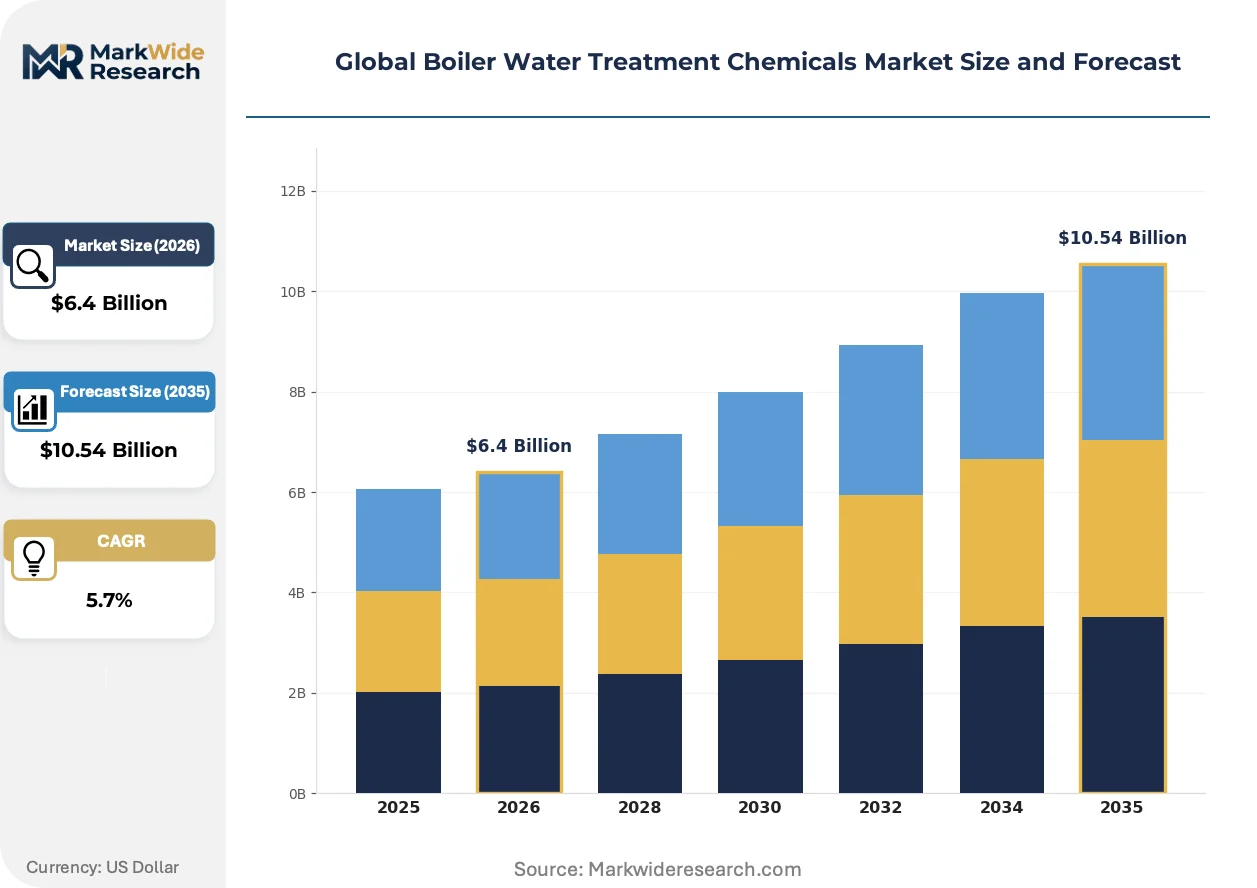
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Scavengers, Scale Inhibitors, Corrosion Inhibitors, pH Adjusters, Dispersants Application: Power Generation, Petrochemical Plants, Paper & Pulp Facilities, Textile Production, Food Processing End User: Electric Utilities, Refining Companies, Manufacturing Plants, Chemical Processors, Water Treatment Facilities Packaging Type: Drums, Bulk Bags, IBC Totes, Fiber Drums, Sachets |
| Companies Covered | Ecolab, SUEZ, Kurita Water Industries Ltd, Solenis, Veolia, BASF SE, ChemTreat, Buckman, Kemira Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boiler Water Treatment Chemicals Market Shifts & Advancements
Formulation science is pivoting from commodity bulk chemicals toward precision-engineered specialty blends synchronized with digital monitoring infrastructure. This convergence is redrawing competitive boundaries between chemical suppliers and automation vendors.
Catalyzed bisulfite oxygen scavengers is overtaking hydrazine derivatives in ultra-supercritical installations. US electric utilities are completing multi-year conversion programs ahead of OSHA exposure limits tightening. The technology is compressing the addressable market for legacy carbohydrazide and diethylhydroxylamine formulations.
REACH substance evaluation timelines are forcing accelerated substitution of chromate-based corrosion inhibitors. ECHA's 2024–2026 review wave targets sodium chromate and strontium chromate in closed cooling systems. European power generators and pulp mills are trialing molybdate-organic hybrid programs, with Nordic district heating networks adopting the fastest.
Integrated chemical-automation procurement is consolidating vendor relationships in electric utilities. Single-source contracts bundling oxygen scavengers, scale inhibitors, and digital monitoring platforms are displacing multi-vendor spot purchasing. This pattern is most pronounced in Germany's municipal energy sector and Japan's regional power cooperatives.
Global Boiler Water Treatment Chemicals Market Segmentation
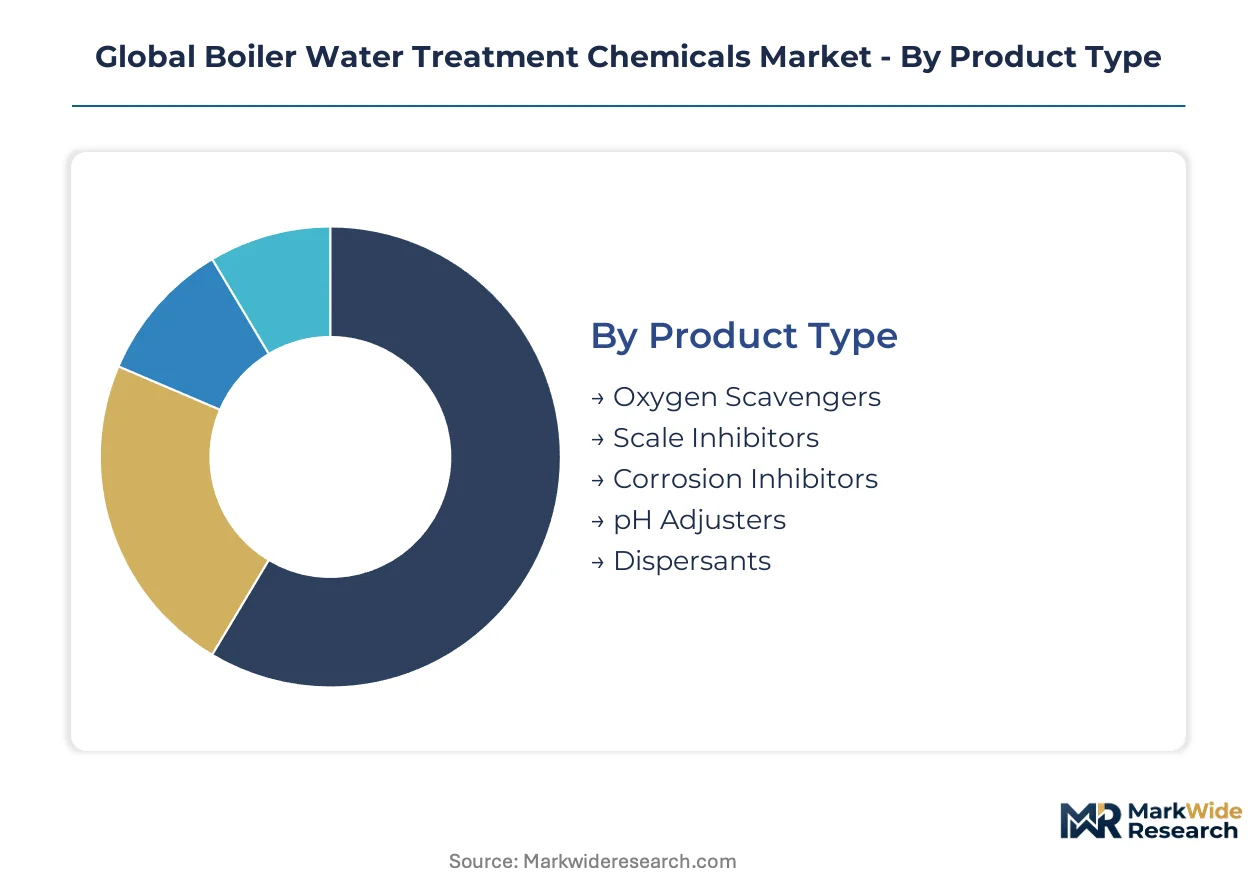
Boiler water treatment chemicals serve distinct operational regimes across pressure ratings, steam purity requirements, and discharge constraints. Segmentation reveals how formulation chemistry, application intensity, and procurement logistics create divergent margin structures and supplier positioning opportunities.
Product Type:
Thermal stress thresholds and metallurgical compatibility drive product selection across subcritical, supercritical, and ultra-supercritical installations.
- Oxygen Scavengers:Catalyzed bisulfite and hydrazine alternatives remove dissolved oxygen to prevent pitting corrosion in high-pressure steam generators. US electric utilities are completing conversion programs ahead of OSHA exposure limit tightening, compressing legacy carbohydrazide demand.
- Corrosion Inhibitors:Film-forming amines and molybdate-organic hybrids protect metal surfaces through adsorption or passivation layers. ECHA substance evaluations are forcing chromate substitution, redirecting European power generators and Nordic district heating networks toward compliant alternatives.
- Scale Inhibitors:Phosphonate and polymer-based chemistries prevent calcium carbonate and silica deposition on heat transfer surfaces.
- pH Adjusters:Caustic soda and ammonia compounds maintain alkalinity between 200–400 ppm to minimize acid corrosion.
- Dispersants:Polymeric dispersant packages suspend particulates for blowdown removal in closed-loop cooling systems mandated by China's MEE.
Mature deployment sits with scale inhibitors in commodity phosphonate applications. Newer deployment is concentrated in oxygen scavengers reformulated for 620°C steam temperatures and 300+ bar pressures.
Application:
Process criticality and steam purity specifications create tiered performance requirements that fragment chemical procurement patterns.
- Power Generation:Ultra-supercritical coal and combined-cycle gas turbines demand oxygen scavengers and corrosion inhibitors capable of maintaining heat transfer efficiency under extreme thermal ratchet conditions. State-owned Chinese power groups are retrofitting aging units with advanced water chemistry programs.
- Petrochemical Plants:Olefin crackers and aromatics complexes require coordinated phosphate-pH programs to prevent tube failures in high-temperature steam crackers.
- Paper & Pulp Facilities:Kraft recovery boilers and lime kilns drive demand for rapid-response technical service and custom-blended chemistries.
- Textile Production:Dyeing and finishing operations utilize low-pressure steam systems with simpler treatment protocols.
- Food Processing:Clean steam applications for sterilization and CIP systems require FDA-compliant formulations with stringent purity documentation.
Volume concentration favors power generation across coal fleet retrofits in India and China. Value capture is steepest in petrochemical applications where metallurgical specificity commands premium blending margins.
End User:
Procurement sophistication and technical staffing levels determine whether customers self-blend or contract integrated chemical-automation packages.
- Electric Utilities:Municipal energy sectors in Germany and regional power cooperatives in Japan are consolidating toward single-source contracts bundling chemistries with digital monitoring platforms.
- Refining Companies:FCC units and hydrocrackers operate complex steam networks requiring corrosion inhibitors tailored to varying metallurgy across unit ages.
- Manufacturing Plants:Discrete manufacturing with intermittent steam demand favors spot purchasing over long-term service agreements.
- Chemical Processors:Captive power and steam generation in integrated sites often maintain in-house water treatment expertise.
- Water Treatment Facilities:Third-party service providers bundle boiler treatment into broader industrial water management contracts.
Contract depth is greatest among electric utilities with automated feed system retrofits. Spot purchasing persists in manufacturing plants with legacy distributed control systems lacking data architecture for modern monitoring platforms.
Packaging Type:
Logistics economics and site storage constraints shape packaging selection across customer scale and geographic density.
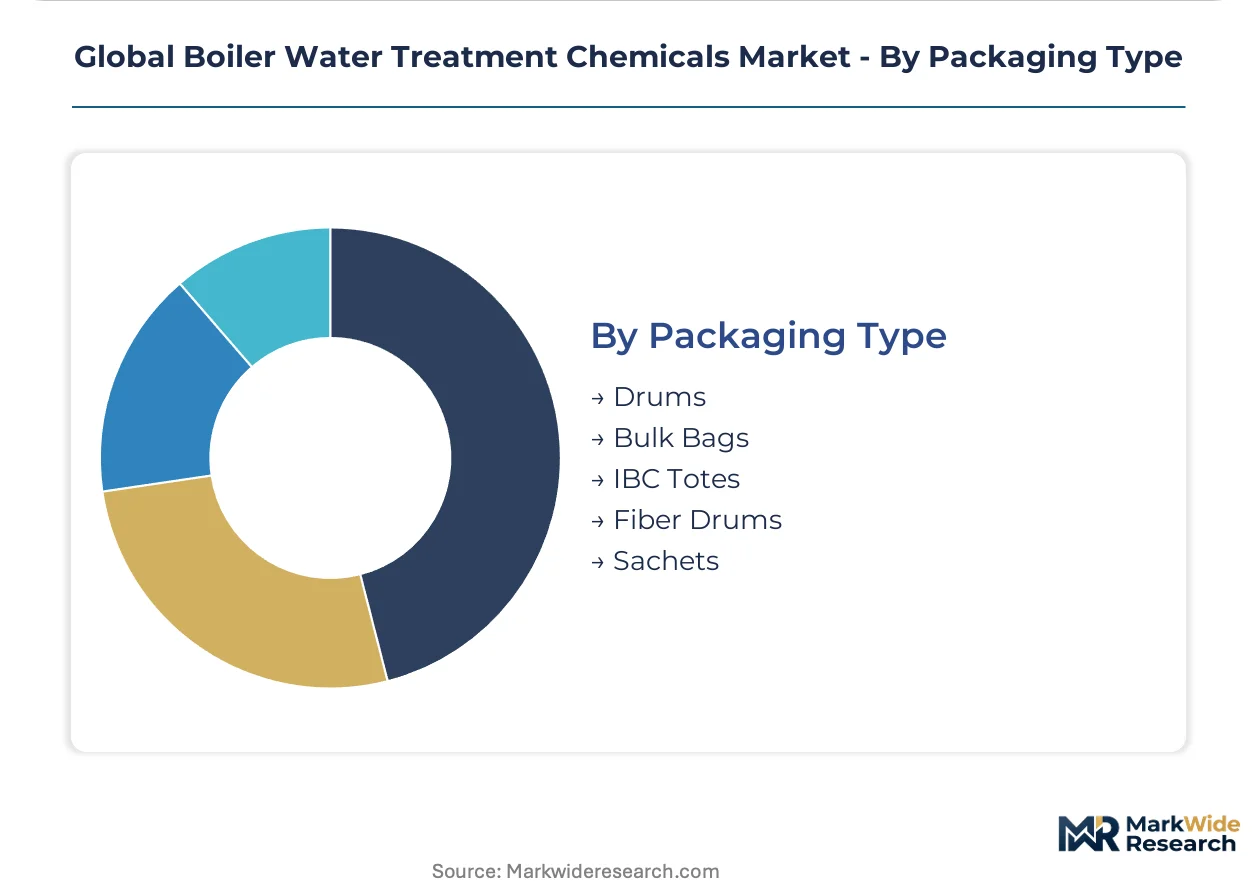
- Bulk Bags:Powdered oxygen scavengers and scale inhibitors move in one-ton flexible intermediate bulk containers for high-volume power plant consumption.
- IBC Totes:Liquid corrosion inhibitors and pH adjusters deploy in 1,000-liter reusable totes for mid-scale industrial boilers.
- Drums:Standard 55-gallon steel drums serve smaller manufacturing sites with limited chemical storage infrastructure.
- Fiber Drums:Moisture-sensitive dispersant powders utilize fiber construction for humidity protection during transport.
- Sachets:Pre-measured water-soluble packets enable precise dosing in remote or technically understaffed installations.
Scale economies concentrate procurement in bulk bags and IBC totes for utility-scale deployment. Sachet formats gain traction where certified water chemist scarcity complicates manual dosing programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tangshan anchors Asia-Pacific boiler chemical demand through its concentration of ultra-supercritical coal units retrofitting with advanced water chemistry programs. State-owned power groups in this Hebei industrial corridor drive regional procurement volumes for oxygen scavengers and corrosion inhibitors.
United States
Electric utilities in the Ohio River Valley and Texas ERCOT grid are completing multi-year hydrazine-to-bisulfite conversion programs ahead of OSHA exposure limit tightening. EPA effluent limitation guidelines restrict phosphate discharge from boiler blowdown, pushing facilities toward zero-liquid-discharge chemistries. Gulf Coast petrochemical clusters around Houston and Lake Charles command premium blending margins for metallurgically specific corrosion inhibitors.
Germany
Municipal energy sectors in the Ruhr industrial belt and Bavarian manufacturing zones consolidate procurement toward single-source contracts bundling chemistries with digital monitoring platforms. ECHA substance evaluations under REACH timelines force accelerated chromate substitution in closed cooling systems. Nordic district heating networks in Hamburg and Berlin are trialing molybdate-organic hybrid programs at the fastest adoption rates in Europe.
China
State-owned power groups retrofit aging coal-fired units across the Yangtze River Delta and Shandong Peninsula with advanced water chemistry programs. MEE mandates stricter thermal power plant water recycling rates, accelerating demand for high-performance dispersant packages. Industrial clusters in Jiangsu and Guangdong provinces lead retrofit program implementation for closed-loop cooling compliance.
India
NTPC and state gencos are retrofitting 1970s-era units with automated chemical feed systems across the National Capital Region and Maharashtra industrial corridors. Central Electricity Authority norms push water conservation targets that elevate polymer-based threshold inhibition demand. Western and southern grid zones around Mumbai and Chennai represent concentrated greenfield service contract potential.
Global Boiler Water Treatment Chemicals Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation specificity and digital integration depth. The vendor base stratifies into three tiers: integrated water management conglomerates with automation platforms, regional specialists with localized polymer production, and commodity blenders competing on phosphonate volume. Consolidation pressure intensifies as single-source procurement contracts displace multi-vendor spot purchasing. Capacity expansion and strategic partnerships represent the dominant competitive vectors.
Within the integrated service tier, Ecolab and Veolia exemplify the convergence of chemical supply with digital monitoring infrastructure. Kurita Water Industries Ltd occupies a position among Asia-Pacific specialists leveraging localized manufacturing scale. Solenis represents the rapid-response technical service archetype for pulp and paper boiler systems. These anchors illustrate how competitive positioning increasingly depends on bundling chemistry with automation rather than standalone product sales.
| Leading Market Players |
|---|
| Ecolab |
| SUEZ |
| Kurita Water Industries Ltd |
| Solenis |
| Veolia |
| BASF SE |
| ChemTreat |
| Buckman |
| Kemira Oyj |
| Others |
Supply & Pricing Matrix
Catalyzed bisulfite oxygen scavenger reformulation for ultra-supercritical steam conditions is compressing cost economics while concentrating supply leverage among polymer producers with captive monomer capabilities. This thermal ratchet simultaneously elevates R&D amortization burdens and rewards backward-integrated suppliers who control phosphorus and organic amine feedstocks.
Pricing Analysis
Value-based pricing anchored to steam system uptime and tube-failure prevention dominates electric utility procurement. Three-tier pricing structure across premium, standard, and economy levels separates film-forming amine packages from commodity phosphonate scale inhibitors. Cost compression in oxygen scavengers is intensifying because US utilities are completing hydrazine-to-bisulfite conversions under OSHA timelines. Manufacturing plants with intermittent steam demand exhibit highest price sensitivity; ultra-supercritical power generators prioritize metallurgical specificity over unit cost.
Supply Chain Analysis
Certified water chemist scarcity in Jiangsu and Shandong provinces is constraining blending capacity expansion despite polymer feedstock availability. Manufacturing concentrates in China, Germany, and the United States, drawing from phosphoric acid, ethylene oxide derivatives, and molybdate ore inputs. Single-source vulnerability runs through Chinese phosphorus pentoxide supply for phosphonate production. Distribution feeds from regional compounding facilities through bulk bag and IBC tote formats to utility-scale storage silos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market occupies a technology-transition phase as catalyzed bisulfite chemistry displaces hydrazine derivatives across ultra-supercritical installations. This substitution wave rewards suppliers who bundle reformulation expertise with digital monitoring infrastructure.
For Market Incumbents: Extend service contract duration through integrated chemical-automation procurement models that bundle oxygen scavengers with IoT sensor platforms. Deepen backward integration into polymer monomer production to offset phosphonate input cost volatility. Chromate formulation sunset under REACH timelines threatens smaller blenders lacking molybdate alternatives; accelerate organic film-forming amine R&D to capture premium positioning. For New Entrants and Emerging Players: Direct-to-utility digital platforms offer low-friction entry into municipal energy sectors consolidating toward single-source contracts. Target India's NTPC retrofit programs for automated chemical feed systems, where greenfield service contract potential exceeds established vendor saturation. Emphasize rapid-response technical service capabilities to differentiate from integrated conglomerates with slower decision chains. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to water management conglomerates seeking regional polymer production assets. Five-to-ten year viability hinges on biodegradable inhibitor formulation readiness ahead of regulatory divergence. Acquisition targets should demonstrate captive supply of organic amine feedstocks or established digital twin integration. Monitor ECHA substance evaluation timelines as inflection indicators for chromate substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive supply of ethylene oxide derivatives insulates margins from fertilizer sector demand swings. |
| Digital Twin Platform Development | Real-time chemistry optimization enables subscription-based technical service models with German municipal utilities. |
| Biodegradable Film-Forming Amine Launch | Oleic acid imidazoline derivatives capture premium positioning under EU REACH compliance timelines. |
| Regional Compounding Facility Expansion | Localized blending in Jiangsu reduces logistics costs for China's MEE-mandated dispersant packages. |
| Long-Term Service Agreement with NTPC | Automated feed system retrofits across Maharashtra industrial corridors lock in decade-long revenue streams. |
Research Methodology
Multi-period observation of ultra-supercritical plant commissioning rates and REACH authorization timelines anchored the trend analysis, supplemented by interviews with power plant water chemists, chemical procurement managers at state-owned utilities, polymer R&D directors, and regional distribution channel partners. Secondary validation drew from EPA effluent limitation guidelines, ECHA substance evaluation databases, China MEE policy circulars, and SEC filings of integrated water management conglomerates. Bottom-up volume modeling across oxygen scavenger, corrosion inhibitor, and scale inhibitor product lines triangulated against top-down power generation capacity expansion forecasts.
Segment-weighting applied pressure-rating tiers, end-use industry concentration, and regional regulatory stringency indices across the projection horizon. CAGRs derived from installed base expansion rates, chemical intensity per megawatt, and substitution elasticities between hydrazine and bisulfite alternatives. Forecast inputs incorporated China's coal fleet modernization pipeline, EU F-Gas Regulation phase-down impacts on industrial cooling budgets, and India's Central Electricity Authority water conservation norms.
The model holds under stable regulatory enforcement trajectories and continued ultra-supercritical plant deployment; deviation in ECHA authorization acceleration or phosphorus feedstock export restrictions would shift supplier margin structures and regional procurement patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market