
 Orchard Tractor Market | 2026-2036
Orchard Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Orchard Tractor Market Analytics
Telematics subscription services is shifting how orchard tractor value gets captured beyond the initial equipment sale. Kubota leverages its precision agriculture platform to sustain recurring revenue from Japanese citrus cooperatives. John Deere dominates North American vineyard and nut-orchard channels through its integrated operations center. AGCO differentiates in European pome-fruit territories with Fendt-branded variable-rate spraying compatibility.
An orchard tractor is a low-clearance, narrow-profile agricultural vehicle engineered with sub-48-inch axle widths, hydrostatic or CVT transmissions, and protective orchard frames to navigate dense tree canopies without branch damage; manufacturers typically employ stamped-steel hoods, rear three-point hitch systems rated to Category I/II, and offset seating for forward-and-reverse visibility during spraying, mowing, and harvesting cycles. Compact tractors lead volume in European olive and vineyard applications where terraced terrain limits machine size, while specialty tractors command the strongest margin pools in high-density apple and almond operations requiring integrated harvesting attachments. Electric engine types are gaining fastest in noise-sensitive peri-urban orchards and zones with renewable energy access, though diesel retains installed-base dominance across remote growing districts.
EPA Tier 4 Final and California Air Resources Board off-road diesel rules are forcing engine redesigns and retrofit timelines for fleets operating in US tree-nut and citrus regions. EU Stage V emissions standards, administered by national type-approval bodies under European Commission framework regulations, restrict diesel particulate output in Italian and Spanish orchard belts and channel R&D spending toward battery-electric architectures. Stakeholders must monitor powertrain certification timelines and charging infrastructure commitments in target growing regions before committing fleet replacement schedules.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are compressing diesel powertrain viability windows while accelerating battery-electric R&D commitments across California's Central Valley and Spain's Valencia citrus belt.
Growth Catalysts
- California Air Resources Board mandates:Off-road diesel rules in US tree-nut regions are forcing fleet turnover and opening procurement windows for cleaner powertrains.
- High-density almond operations:Mechanized harvesting attachment demand in California's Central Valley is pulling specialty tractor volume upward.
- Telematics platforms:Recurring revenue models from precision agriculture subscriptions are extending customer lifetime value beyond equipment sales.
Market Restraints
- Battery cell supply concentration:Asian cathode material processing bottlenecks are constraining electric powertrain production scalability.
- Charging infrastructure gaps:Remote growing districts in Australia's Riverina and South Africa's Western Cape lack grid capacity for fleet electrification.
- Steel and aluminum input volatility:Stamped-steel hood and chassis fabrication costs are exposed to commodity price swings.
Strategic Opportunities
- Peri-urban noise-sensitive zones:Electric tractors bypass sound restrictions in Italy's Po Valley fringe orchards near residential boundaries.
- Variable-rate spraying convergence:Integration of GPS-guided application with Fendt-branded systems opens premium positioning in European pome-fruit territories.
- Japanese citrus cooperative consolidation:Platform subscription models can capture recurring revenue from organized grower associations.
Industry Challenges
- Powertrain certification timeline compression:EPA and EU type-approval processes for new electric architectures are extending product launch cycles.
- Hydrostatic transmission technician scarcity:Specialized repair skills for CVT and hydrostatic systems are aging out of the workforce faster than training programs replace them.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orchard Tractor Market |
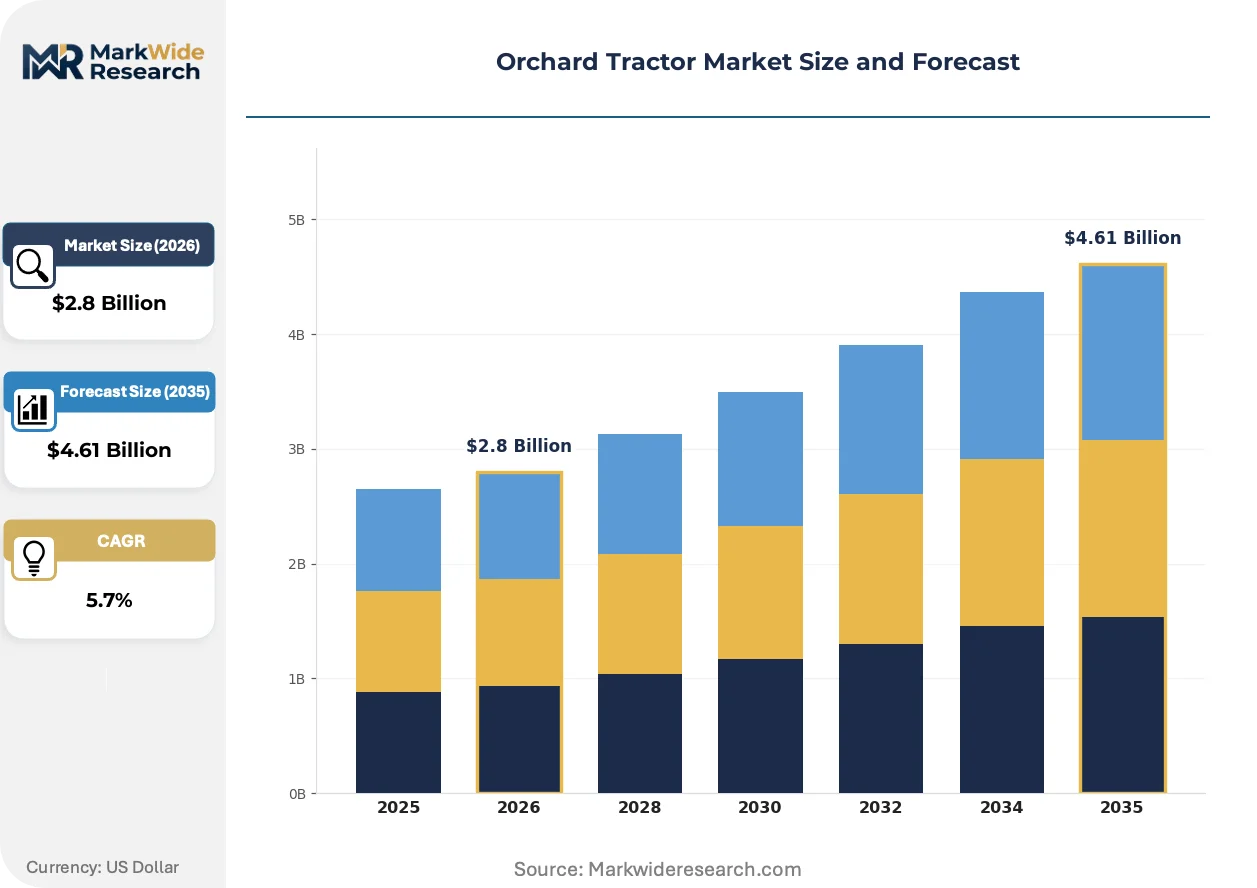
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tractor, Compact Tractor, Utility Tractor, Specialty Tractor Engine Type: Gasoline, Diesel, Electric, Hybrid Application: Farming, Landscaping, Maintenance, Harvesting End User: Commercial Farms, Agricultural Cooperatives, Private Growers, Landscaping Companies |
| Companies Covered | Kubota, SDF, John Deere, Case IH, Yanmar, CNH Industrial, Mahindra, LS Tractor, AGCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orchard Tractor Market Evolving Landscape
Powertrain electrification and precision agriculture platform integration are rewriting value capture mechanisms while emissions compliance deadlines compress technology transition windows.
Battery-electric orchard tractors with sub-48-inch axle widths are decentralizing fleet procurement authority from centralized equipment managers toward individual grower cooperatives. Japanese citrus cooperatives are piloting subscription-based access models rather than capital purchases. This shift is decentralizing manufacturer channel power toward direct digital relationships.
EU Stage V emissions standards administered by Italian and Spanish national type-approval bodies are banning high-particulate diesel engines from olive and citrus belts. Engine redesign costs are diverting R&D budgets from mechanical innovation toward electric architectures. Italian pome-fruit growers are responding by accelerating replacement cycles ahead of enforcement deadlines.
After-sales service unbundling is fragmenting traditional dealer revenue streams. California almond operators are sourcing maintenance parts through direct digital channels rather than authorized service networks. This pattern is most visible in high-volume nut-orchard regions where downtime costs exceed brand loyalty premiums.
Orchard Tractor Market Segmentation
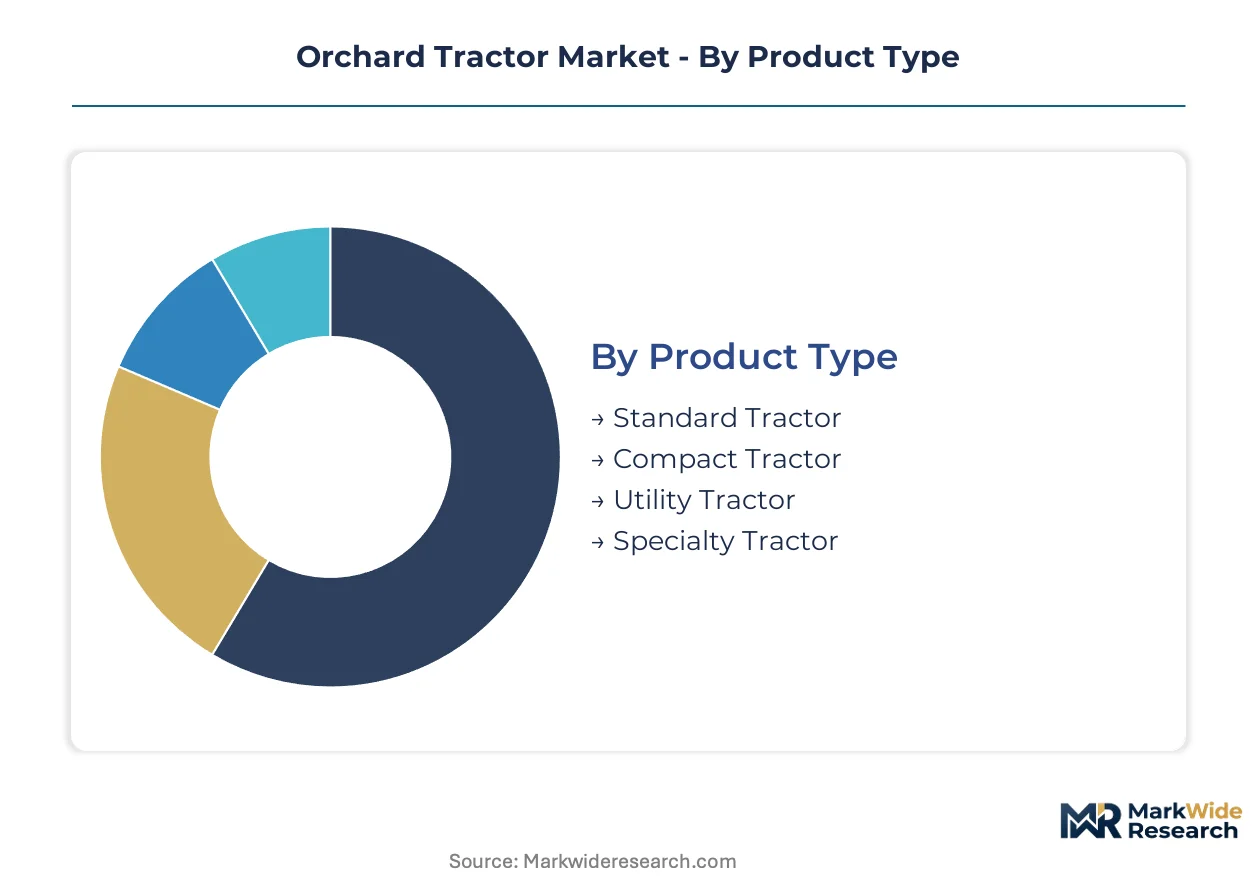
Orchard tractor procurement splits sharply between capital-intensive specialty units for high-density operations and lower-cost compact models for terraced terrain. Equipment managers weigh axle width constraints, powertrain certification timelines, and attachment compatibility when segmenting fleet investments.
Product Type:
Capital intensity escalates from compact units through specialty tractors with integrated harvesting systems.
- Standard Tractor:Mid-range axle configurations serve diversified citrus and nut operations requiring seasonal flexibility between spraying and tillage. California's Central Valley equipment pools favor these units for multi-task fleet efficiency.
- Compact Tractor:Sub-48-inch profiles dominate European olive terraces and Japanese citrus slopes where terrain gradient limits machine dimensions. Italian cooperatives in the Po Valley deploy these for maneuverability in dense pome-fruit canopies.
- Utility Tractor:Crossover designs bridge orchard and open-field applications for mixed-operation growers.
- Specialty Tractor:Purpose-built narrow profiles with Category II hitch ratings command premium positioning in high-density almond harvesting.
Compact tractors absorb the bulk of installed capacity; specialty tractors are expanding most quickly.
Engine Type:
Powertrain selection increasingly hinges on regulatory enforcement calendars rather than fuel economics alone.
- Diesel:EPA Tier 4 Final and EU Stage V particulate limits are compressing viable deployment windows for conventional compression-ignition engines. California Air Resources Board mandates are accelerating fleet turnover timelines in tree-nut regions.
- Electric:Battery architectures with liquid-cooled thermal management bypass noise ordinances in peri-urban Italian orchards near residential boundaries. Charging infrastructure gaps in Australia's Riverina and South Africa's Western Cape constrain rural adoption.
- Gasoline:Spark-ignition units persist in low-hour maintenance applications and hobby-scale operations.
- Hybrid:Range-extended electric designs bridge grid-access limitations for remote growing districts.
Diesel retains the deepest installed base; electric powertrains are climbing the fastest.
Application:
Task-specific attachment integration determines tractor specification more than raw horsepower ratings.
- Farming:Tillage and cultivation cycles in California's Central Valley high-density almond blocks require hydrostatic transmission durability.
- Harvesting:Shaker-head and catch-frame integration in nut-orchard operations pulls specialty tractor specifications toward higher hitch capacity and hydraulic flow rates.
- Landscaping:Mower deck and material-handling attachments dominate peri-urban maintenance contracts.
- Maintenance:Sprayer boom and pruning platform compatibility shapes narrow-profile unit selection.
Farming commands the largest equipment base; harvesting applications are gaining share fastest.
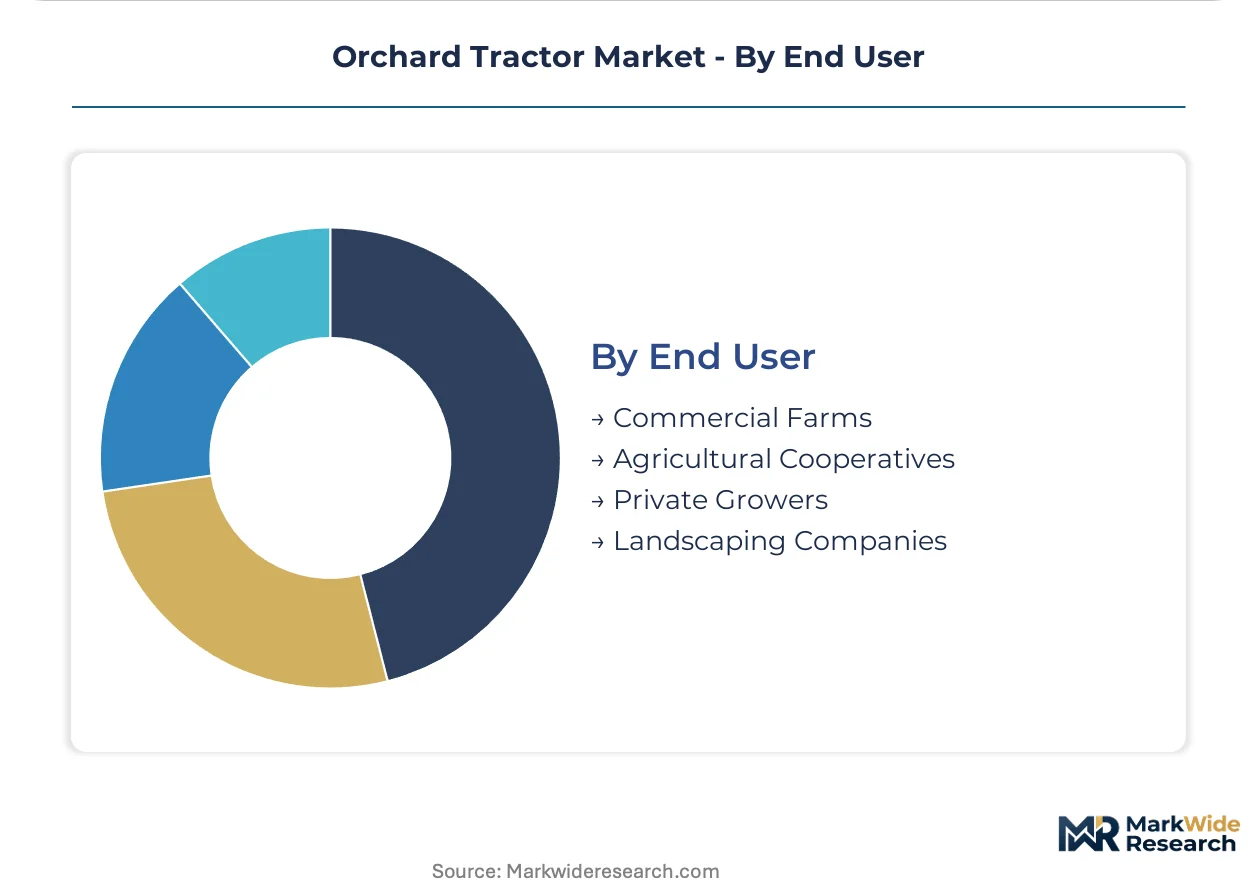
End User:
Procurement authority is fragmenting from centralized cooperatives toward individual grower decisions.
- Commercial Farms:Large-scale California almond and pistachio operators standardize fleets around telematics-integrated platforms for downtime minimization.
- Agricultural Cooperatives:Japanese citrus associations are piloting subscription access models rather than capital purchases, shifting manufacturer relationships toward recurring revenue.
- Private Growers:Individual operators in Spain's Valencia belt prioritize purchase price over precision agriculture compatibility.
- Landscaping Companies:Maintenance contractors demand compact profiles for residential perimeter work.
Commercial farms deploy the heaviest equipment volumes; agricultural cooperatives are restructuring procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresno County anchors orchard tractor deployment density, with California's Central Valley equipment pools absorbing the heaviest specialty tractor volumes for high-density almond and pistachio harvesting systems.
United States
California's Central Valley tree-nut operators drive specialty tractor procurement for mechanized shaker-head integration. EPA Tier 4 Final emissions rules compress diesel fleet viability windows through 2027 enforcement calendars. Fresno and Kern counties concentrate replacement demand ahead of California Air Resources Board deadlines.
Spain
Valencia's citrus belt generates compact tractor demand for terraced orange and mandarin cultivation. EU Stage V type-approval restrictions administered by Spain's national motor vehicle authority ban high-particulate diesel engines from olive and citrus zones. Murcia's lemon-growing districts accelerate electric pilot programs near residential boundaries.
Italy
Po Valley pome-fruit cooperatives deploy narrow-profile units for dense apple and pear canopy navigation. EU Stage V standards channel equipment budgets toward battery-electric architectures ahead of 2026 enforcement. Emilia-Romagna's orchard machinery clusters specialize in variable-rate spraying integration.
Japan
Shizuoka and Ehime prefectures' citrus slopes constrain machine dimensions, favoring sub-48-inch compact designs. METI clean energy subsidies offset electric powertrain premiums for organized grower associations. Subscription access models are consolidating procurement authority within cooperative structures.
Australia
Riverina nut-orchard expansion pulls utility tractor specifications for cross-application flexibility. Grid capacity limitations in New South Wales' remote growing districts constrain fleet electrification timelines. Shepparton machinery dealers serve Victoria's Goulburn Valley fruit belt with hybrid-range-extended options.
Orchard Tractor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across powertrain and precision agriculture platform development. The vendor base concentrates around integrated equipment manufacturers with captive distribution networks and component specialists supplying hydrostatic transmission systems. Three archetypes dominate: full-line agricultural equipment conglomerates with telematics platforms, regional compact tractor specialists serving terraced terrain, and powertrain technology licensors. Strategic moves center on electric architecture R&D partnerships and precision agriculture subscription model expansion.
Among Japanese equipment manufacturers, Kubota occupies a position exemplifying platform-centric recurring revenue capture from cooperative procurement channels. John Deere represents the North American full-line archetype with integrated operations center positioning. AGCO anchors European premium-tier differentiation through variable-rate application compatibility. These three illustrate how geographic specialization and powertrain certification timing shape competitive positioning.
| Leading Market Players |
|---|
| Kubota |
| SDF |
| John Deere |
| Case IH |
| Yanmar |
| CNH Industrial |
| Mahindra |
| LS Tractor |
| AGCO |
| Others |
Value Network & Pricing Analysis
Battery-electric powertrain transitions are simultaneously compressing diesel component demand and concentrating Tier 1 supplier relationships around Asian cathode material processors, reshaping cost economics from stamped-steel fabrication through liquid-cooled thermal management systems. California Air Resources Board enforcement calendars and EU Stage V type-approval deadlines are synchronizing procurement waves, amplifying volume-based pricing leverage for high-density almond operators in Fresno County.
Pricing Analysis
Telematics-enabled uptime guarantees anchor value-based pricing for commercial farm fleets, with subscription tiers scaling by precision agriculture feature depth. Three-tier pricing structure across premium, standard, and economy levels separates integrated harvesting compatibility from basic spraying configurations. Cost compression in compact tractor segments is intensifying because Italian and Spanish cooperatives are consolidating procurement authority. Private growers in Spain's Valencia belt exhibit highest price sensitivity, while Japanese citrus associations demonstrate lowest sensitivity due to METI subsidy offsets.
Supply Chain Analysis
Hydrostatic transmission technician scarcity in Japan's Shizuoka prefecture and Italy's Emilia-Romagna region is constraining final assembly capacity expansion despite component availability. Stamped-steel hood fabrication draws from Chinese and South Korean metal forming clusters, while battery cell assembly rests on South Korean and Japanese cathode processing. Single-source vulnerability in liquid-cooled thermal management modules threatens electric powertrain delivery timelines. Distribution runs through captive dealer networks for full-line manufacturers and direct digital channels for compact tractor specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-centric recurring revenue models, with EPA and EU emissions certification costs forcing sub-scale engine suppliers into exit or acquisition.
For Market Incumbents: Hedge diesel powertrain exposure by accelerating electric architecture R&D partnerships ahead of Tier 4 Final enforcement windows. Secure backward integration into battery thermal management components to defend margin position against Asian cathode processor consolidation. Channel control through telematics platform stickiness represents the critical defensive lever against cooperative procurement decentralization. For New Entrants and Emerging Players: Begin with peri-urban noise-sensitive zones in Italy's Po Valley fringe, where electric tractors bypass sound restrictions with minimal charging infrastructure. Australia's Riverina offers penetrable white-space for hybrid-range-extended utility tractors addressing grid capacity gaps. A direct-to-cooperative subscription model bypasses established dealer networks entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in powertrain technology licensors with EPA Stage V certification assets and precision agriculture platform IP. Long-term viability favors vertically integrated manufacturers with captive battery supply arrangements over component assemblers. Watch California Air Resources Board enforcement acceleration as the inflection signal for diesel fleet replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Certification Investment | EPA Stage V type-approval timelines determine market access windows for California Central Valley fleets. |
| Precision Agriculture Platform Integration | GPS-guided variable-rate spraying compatibility captures premium positioning in European pome-fruit territories. |
| Subscription Access Model Deployment | Japanese citrus cooperatives are piloting recurring revenue structures that displace capital purchase cycles. |
| Charging Infrastructure Partnership | Grid capacity constraints in Australia's Riverina require hybrid-range-extended bridging solutions. |
| Aftermarket Service Network Consolidation | California almond operators are fragmenting dealer revenue through direct digital parts sourcing. |
Research Methodology
Multi-period observation of powertrain certification timelines and cooperative procurement patterns anchored the trend analysis, supplemented by interviews with maintenance directors at California nut-orchard operations, precision agriculture platform engineers at Japanese equipment manufacturers, and aftermarket service heads at Italian dealer networks. Secondary validation drew from EPA engine certification databases, EU type-approval registers, and agricultural machinery trade flow records. Bottom-up equipment shipment tracking and top-down regional fleet size estimates were triangulated to constrain forecast variance.
Input-output matrices modeled tractor deployment across powertrain architecture, axle width configuration, and attachment integration complexity throughout the forecast period. CAGRs were derived from segmented replacement cycle analysis and regulatory enforcement calendar impacts. Forecast inputs incorporated California Air Resources Board mandate phase-ins and METI clean energy subsidy allocation trajectories.
Underlying measurement precision varies by segment; electric powertrain forecasts carry tighter precision than hybrid architectures due to clearer certification pathways. Forecasts reflect documented assumptions regarding enforcement timing and subsidy continuity. Material deviation in EPA or EU regulatory acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Farm Tractor Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
Global Agricultural Sprayer Market
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Hay Making Machinery Market
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Australia Agricultural Machinery Market