
 Europe Agricultural Machinery Market | 2026-2036
Europe Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Machinery Market Analysis
Contract farming enterprises is redrawing procurement patterns across Europe as scale operators displace fragmented smallholder demand. Deere & Company anchors its position through precision agriculture integration across German and French dealer networks. CLAAS KGaA mbH specializes in harvester automation for large cereal operations in Eastern Europe. Kubota Corporation competes in compact tractor segments where Mediterranean horticulture buyers prioritize maneuverability over horsepower.
Europe agricultural machinery encompasses self-propelled and trailed equipment engineered for soil preparation, planting, crop management, and harvesting operations, with power outputs ranging from 20 hp utility tractors to 600 hp articulated machines and working widths exceeding 18 meters for modern seeders. Tractors occupy the largest value share as the universal platform powering implements across all farm sizes, while precision agriculture technology commands expanding margin pools as farmers retrofit GPS guidance and variable-rate application systems. Harvesters lead replacement intensity in grain belts where seasonal utilization rates exceed 800 hours annually.
The EU Green Deal and F-Gas Regulation constrain engine emissions and refrigerant choices, compelling manufacturers to redesign powertrains around Stage V compliance. ECHA REACH protocols govern chemical coatings and hydraulic fluids, raising material certification costs for component suppliers. CE marking and the EU AI Act will shape autonomous equipment deployment as regulators define liability frameworks for unmanned field operations. Stakeholders must track subsidy conditionality under the reformed Common Agricultural Policy, as direct payments increasingly tie to climate-aligned machinery investments.
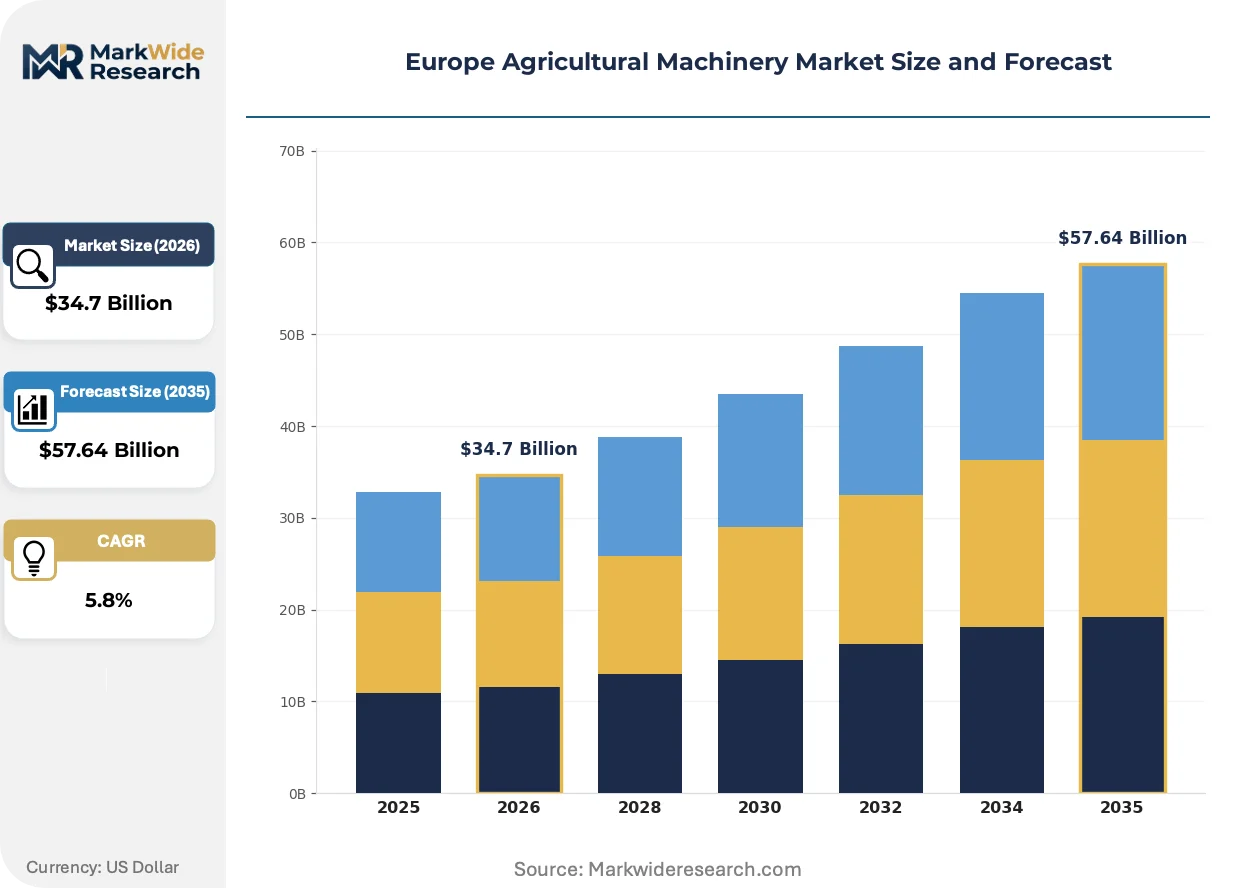
Market Dynamics
The EU Green Deal's machinery subsidy conditionality is redirecting capital flows toward electrified powertrains and precision-enabled equipment, compressing replacement cycles for conventional diesel fleets across consolidated farm holdings.
Growth Catalysts
- CAP Conditionality:The reformed Common Agricultural Policy ties direct payments to climate-aligned machinery investments, compelling large operators in France and Germany to accelerate fleet modernization.
- Precision Agriculture Hardware:GPS guidance and variable-rate application systems are penetrating Eastern European cereal belts where seasonal utilization rates exceed 800 hours annually.
- Contract Farming Consolidation:Scale operators across Poland and Romania are displacing fragmented smallholder demand with centralized procurement of high-horsepower tractors and automated harvesters.
Market Restraints
- Stage V Compliance Costs:Engine redesign requirements under EU emissions protocols are raising powertrain development expenses for manufacturers serving sub-100 hp segments.
- Hydraulic Fluid Certification:ECHA REACH protocols governing chemical coatings and hydraulic fluids are elevating material certification burdens for component suppliers concentrated in Northern Italy.
- Steel Input Volatility:Articulated chassis and implement frames depend on specialized alloy grades subject to energy-cost-driven price swings from German and Austrian mills.
Strategic Opportunities
- Autonomous Field Operations:The EU AI Act's emerging liability frameworks are creating first-mover advantages for equipment makers deploying unmanned tillage systems in Spanish and Portuguese vineyards.
- Horticulture Electrification:Mediterranean olive and citrus producers in Greece and Italy present untapped demand for compact electric tractors where maneuverability outweighs horsepower requirements.
- Retrofit Technology Channels:Precision agriculture aftermarket kits are penetrating existing tractor fleets through dealer networks in Hungary and Czech Republic where new equipment capex faces liquidity constraints.
Industry Challenges
- Telematics Integration Complexity:Legacy mechanical systems in Eastern European farm fleets resist seamless integration with ISOBUS-compatible precision agriculture platforms.
- Stage V Certification Timelines:Exhaust after-treatment validation for sub-40 hp engines is extending product launch cycles beyond traditional agricultural equipment development windows.
- Electrification Skill Gaps:High-voltage powertrain maintenance requires technician retraining that dealer networks in rural France and Poland have not yet operationalized at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Machinery Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Harvesters, Seeders, Plows Technology: Automation, Precision Agriculture, GPS Guidance, IoT Solutions End User: Farmers, Agricultural Cooperatives, Contract Farmers, Large Enterprises Distribution Channel: Online Retail, Direct Sales, Distributors, Dealers |
| Companies Covered | CLAAS KGaA mbH, SDF S.p.A, Deere & Company, Lemken GmbH & Co. KG, Kuhn SAS, CNH Industrial N.V., Kubota Corporation, GRIMME Landmaschinenfabrik GmbH & Co. KG, AGCO Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Machinery Market Emerging Trajectories
Electrification architectures and autonomous control systems are converging to redefine equipment value propositions, shifting competitive advantage from mechanical reliability to software-defined field performance.
High-voltage battery-electric powertrains are supplanting mechanical transmission systems in sub-150 hp utility tractors. German vineyard operators and Dutch greenhouse complexes are piloting these platforms for repetitive cultivation cycles. The technology is compressing total cost of ownership calculations by eliminating diesel logistics and reducing scheduled maintenance intervals.
The EU F-Gas Regulation is constraining refrigerant choices for cab climate systems and grain conditioning equipment. Manufacturers are redesigning thermal management circuits around low-global-warming-potential alternatives. Harvester producers serving French and Danish cooperatives are absorbing compliance costs through platform standardization across model ranges.
Cooperative procurement consortia are aggregating demand from medium-scale holdings in Bavaria and Lombardy. These buying groups are disintermediating traditional dealer networks through direct manufacturer negotiations. The pattern is most visible in precision agriculture technology bundles where volume commitments unlock retrofit kit pricing previously reserved for national fleet operators.
Europe Agricultural Machinery Market Segmentation
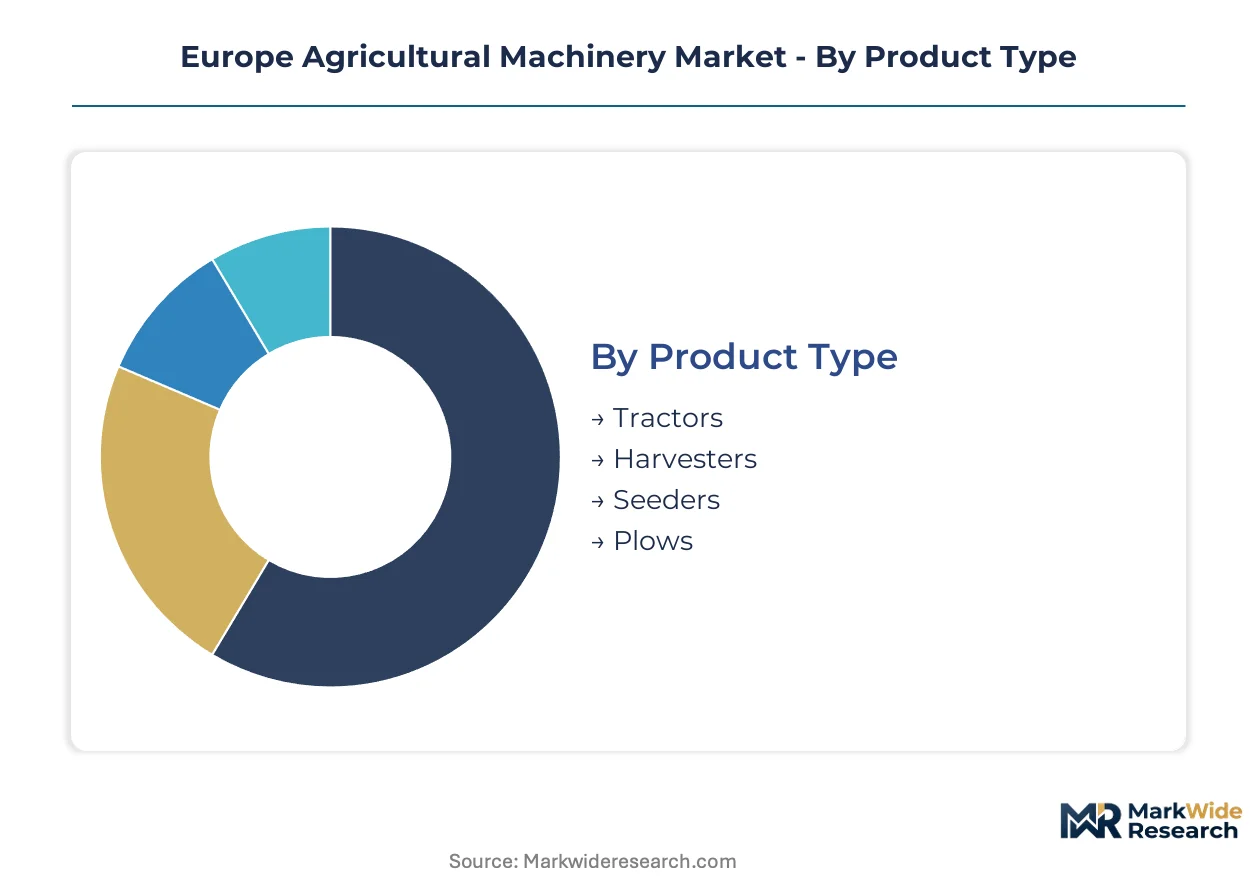
Segmentation reveals how subsidy conditionality and farm consolidation reshape equipment procurement across European markets. Understanding these divisions exposes where precision technology penetrates fastest and which customer tiers drive replacement cycles.
Product Type:
Domestic production clusters in Germany and Italy supply continental demand, while export flows from these manufacturing hubs reach Eastern European cereal belts and Mediterranean horticulture regions.
- Tractors:Self-propelled platforms range from 20 hp utility models to 600 hp articulated machines, serving as the universal power source for implements. French and German large-scale operators dominate demand for high-horsepower segments where Stage V compliance costs concentrate.
- Harvesters:Automated grain and forage systems with seasonal utilization exceeding 800 hours in Polish and Romanian cooperatives. Replacement intensity peaks in Eastern Europe where contract farming consolidation accelerates fleet centralization.
- Seeders:Working widths exceeding 18 meters characterize modern pneumatic drills. Precision agriculture retrofits are expanding fastest in Hungarian and Czech markets where existing tractor fleets limit new equipment capex.
- Plows:Trailed and mounted tillage implements from Italian and Austrian suppliers. Demand concentrates in conservation agriculture transition zones where EU Green Deal conditionality subsidizes reduced-tillage equipment.
Tractors hold the largest share; momentum sits with harvesters as Eastern European contract farming expands replacement intensity.
Technology:
Cost tiers separate premium integrated systems from retrofit kits, with margin structures favoring OEM-embedded solutions in German and French dealer networks.
- Automation:Unmanned tillage and harvesting systems deploying under emerging EU AI Act liability frameworks. Spanish vineyard operators and Portuguese olive producers pilot autonomous platforms where labor scarcity drives adoption.
- Precision Agriculture:Variable-rate application systems and yield mapping hardware penetrating existing fleets through aftermarket channels. Polish and Romanian cereal operations prioritize this tier for immediate productivity gains without full fleet replacement.
- GPS Guidance:RTK correction systems and auto-steering retrofits dominating mid-market penetration. Italian and Greek horticulture buyers favor portable solutions transferable across compact tractor fleets.
- IoT Solutions:Fleet telematics and predictive maintenance platforms. Integration complexity with legacy mechanical systems in Eastern Europe constrains deployment velocity.
Precision Agriculture commands the largest installed base; Automation is gaining share fastest as regulatory frameworks crystallize.
End User:
Customer type determines procurement scale, with centralized purchasing from contract farming enterprises displacing fragmented individual farm demand.
- Farmers:Individual owner-operators managing sub-200 hectare holdings across France, Germany, and Italy. Subsidy conditionality under reformed CAP directs their equipment choices toward climate-aligned machinery investments.
- Agricultural Cooperatives:Member-owned enterprises in Denmark and the Netherlands aggregating demand for shared precision agriculture infrastructure. Cooperative procurement consortia in Bavaria and Lombardy negotiate direct manufacturer pricing.
- Contract Farmers:Scale operators across Poland and Romania managing consolidated land holdings for corporate clients. Centralized procurement of high-horsepower tractors and automated harvesters defines this tier.
- Large Enterprises:Integrated agribusiness groups with captive fleet management and in-house maintenance capabilities. These buyers drive standardization around ISOBUS-compatible platforms and telematics integration.
Contract Farmers represent the most concentrated demand volume; Agricultural Cooperatives are expanding most quickly as medium-scale holdings pool purchasing power.
Distribution Channel:
Supply concentration in manufacturer-direct relationships is compressing traditional dealer margins, particularly for precision agriculture technology bundles.
- Direct Sales:Manufacturer-to-fleet transactions bypassing dealer networks. Cooperative procurement consortia and large enterprises leverage volume commitments for retrofit kit pricing.
- Dealers:Authorized networks providing service integration and financing, dominant in German and French tractor markets. Technician retraining for high-voltage powertrain maintenance remains uneven across rural territories.
- Distributors:Regional wholesalers serving fragmented smallholder demand in Southern and Eastern Europe. Inventory carrying costs and currency exposure constrain their precision agriculture technology stocking.
- Online Retail:E-commerce platforms for parts, consumables, and compact implements. Limited penetration for capital equipment due to service and financing requirements.
Dealers retain the largest transaction share; Direct Sales are climbing the fastest as cooperative procurement aggregates demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European agricultural machinery distribution, connecting Bavarian manufacturing clusters to Black Sea grain ports through Danube barge networks.
Germany
Large-scale farming enterprises in Lower Saxony and Schleswig-Holstein drive replacement cycles for high-horsepower tractors. Stage V emissions protocols from the German KBA constrain powertrain development timelines. Stuttgart industrial basin manufacturers supply precision agriculture platforms to domestic dealers.
France
Contract farming consolidation in the Île-de-France and Grand Est regions concentrates demand for automated harvesters. CAP conditionality redirects subsidy flows toward climate-aligned machinery investments. Claas anchors harvester production in Harsewinkel while serving Eastern European cereal cooperatives.
Italy
Mediterranean horticulture buyers in Emilia-Romagna and Apulia prioritize compact tractor maneuverability over horsepower. ECHA REACH protocols govern hydraulic fluid certification for component suppliers in Northern Italy. Bologna industrial district fabricators specialize in trailed tillage implements.
Poland
Scale operators across Greater Poland and Mazovia displace fragmented smallholder demand with centralized procurement. EU Green Deal machinery subsidy conditionality accelerates fleet modernization. Poznań distribution hubs channel German and Italian equipment to consolidated land holdings.
Romania
Contract farming enterprises in the Romanian Plain manage expanded cereal operations for Western European agribusiness groups. Precision agriculture hardware penetration lags due to legacy mechanical fleet composition. Bucharest logistics corridors connect Black Sea ports to regional equipment depots.
Europe Agricultural Machinery Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized agricultural equipment manufacturers competing across distinct technology tiers. German and Italian engineering clusters anchor premium tractor and implement production. Strategic archetypes divide between full-line manufacturers, harvester specialists, and compact equipment providers. Competitive moves center on precision agriculture platform integration and electrified powertrain development partnerships.
Among Germany-based fabricators, CLAAS KGaA mbH and Lemken GmbH & Co. KG exemplify specialized agricultural equipment archetypes, while Deere & Company anchors the diversified full-line manufacturer tier. SDF S.p.A represents Italian engineering heritage in tractor platforms. Kubota Corporation occupies a position within the compact equipment specialist category. These entities collectively illustrate how geographic clustering around Stuttgart, Bologna, and Osaka industrial basins shapes competitive positioning without requiring uniform strategic approaches.
| Leading Market Players |
|---|
| CLAAS KGaA mbH |
| SDF S.p.A |
| Deere & Company |
| Lemken GmbH & Co. KG |
| Kuhn SAS |
| CNH Industrial N.V. |
| Kubota Corporation |
| GRIMME Landmaschinenfabrik GmbH & Co. KG |
| AGCO Corporation |
| Others |
Supply Flow & Price Mechanics
High-voltage battery systems replacing mechanical transmissions in sub-150 hp tractors are simultaneously shifting component sourcing from Stuttgart gearbox fabricators toward Korean battery cell suppliers and compressing total cost of ownership calculations for German vineyard operators.
Pricing Analysis
Volume-discount tiering structures separate cooperative procurement consortia in Bavaria and Lombardy from individual owner-operators through direct manufacturer negotiations that unlock retrofit kit pricing. Three-tier pricing structure across premium, standard, and economy levels reflects Stage V certification costs, ISOBUS compatibility grades, and bundled telematics subscriptions. Pricing pressure stems from steel input volatility at German and Austrian mills. Contract farming enterprises exhibit lowest price sensitivity due to centralized capex pools, while fragmented smallholders in Southern Europe face acute liquidity constraints.
Supply Chain Analysis
Extended lead times for exhaust after-treatment components and battery management systems are constraining production schedules at Stuttgart and Bologna manufacturing clusters. Supply concentrates in Germany, Italy, and Poland for tractor platforms, harvester assemblies, and precision agriculture electronics. Raw material flows draw from specialized alloy grades, hydraulic fluid formulations governed by ECHA REACH, and semiconductor chips for GPS guidance modules. Single-source vulnerability sits with Korean battery cell suppliers for electrified powertrains. Distribution runs through authorized dealer networks in France and Germany alongside direct manufacturer channels for cooperative consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
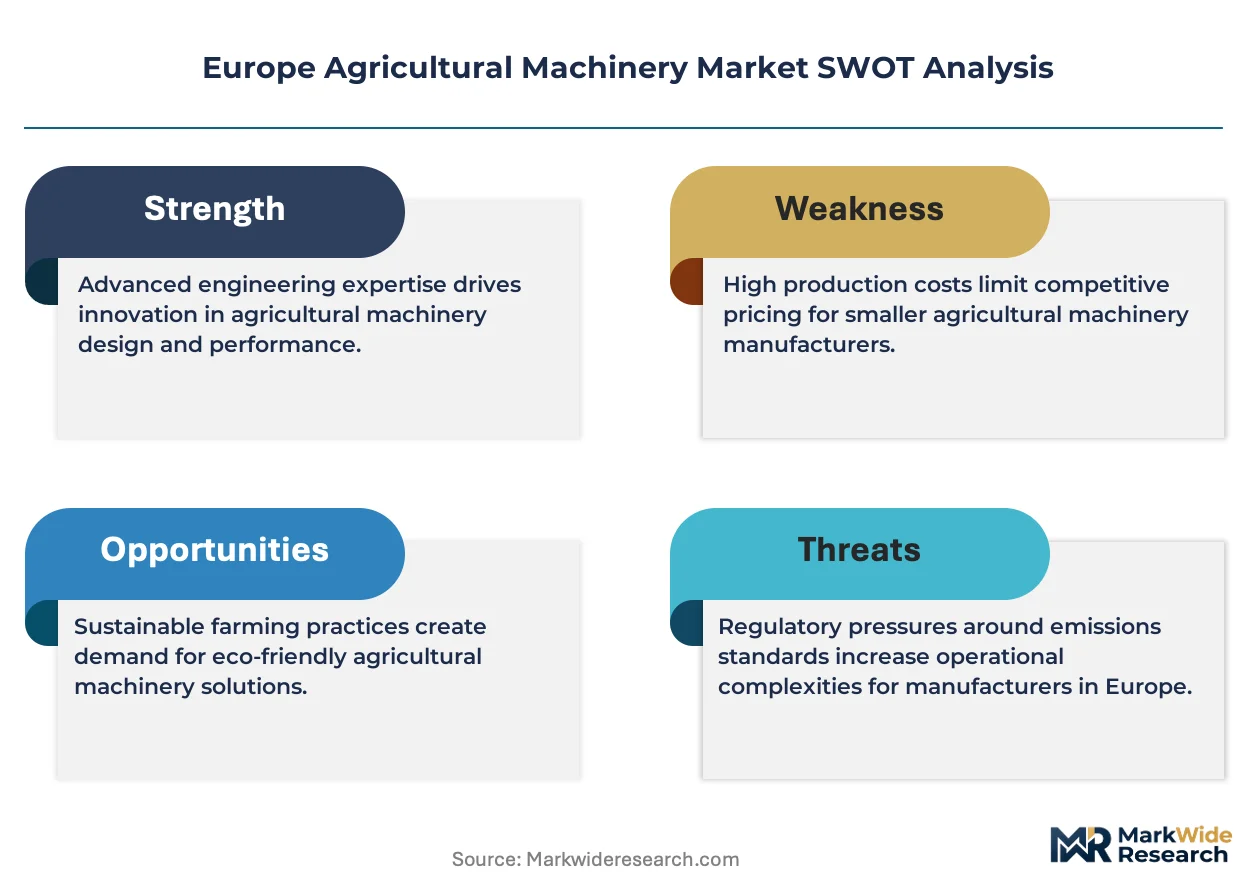
The Europe agricultural machinery market sits at a regulatory inflection where EU Green Deal subsidy conditionality and Stage V emissions protocols are compressing replacement cycles for conventional diesel fleets.
For Market Incumbents: Secure backward integration into battery cell supply through partnerships with Korean suppliers to hedge single-source vulnerability for electrified powertrains. Anchor dealer network loyalty by operationalizing high-voltage technician retraining programs in rural France and Poland before skill gaps widen.
For New Entrants and Emerging Players: Aftermarket precision agriculture retrofit kits represent the most penetrable white-space where existing tractor fleets in Hungary and Czech Republic limit new equipment capex. Target cooperative procurement consortia with portable GPS guidance solutions transferable across compact tractor fleets in Mediterranean horticulture regions.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision agriculture platform specialists with ISOBUS-compatible software stacks. Long-term viability over the next decade hinges on autonomous field operation capabilities under crystallizing EU AI Act liability frameworks. Watch for first-mover certification achievements in unmanned tillage systems as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | ISOBUS-compatible software stacks differentiate German full-line manufacturers from Italian implement specialists. |
| Electrified Powertrain Partnership | Battery supply agreements with Korean cell producers secure Stage V compliance for sub-150 hp utility tractors. |
| Technician Retraining Program | High-voltage maintenance certification at rural French and Polish dealer networks addresses electrification skill gaps. |
| Cooperative Procurement Consortium | Direct manufacturer negotiations in Bavaria and Lombardy disintermediate traditional dealer margins. |
| Autonomous Field Certification | EU AI Act liability framework alignment creates first-mover advantage in Spanish vineyard operations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, agricultural cooperative financial disclosures, and customs trade data for machinery imports. Primary interviews engaged fleet managers at contract farming enterprises, procurement leads at Bavarian and Lombardy cooperatives, precision agriculture integration specialists, and aftermarket service heads at German dealer networks. Bottom-up equipment shipment tallies triangulate against top-down subsidy flow analysis from reformed CAP disbursement records.
Segmentation dimensions modeled span product type, technology tier, end-user archetype, and distribution channel across the projection horizon. CAGRs derive from replacement cycle intensity in Eastern European cereal belts, penetration rates for GPS guidance retrofits, and electrification adoption curves in Mediterranean horticulture. Forecast inputs incorporate Stage V compliance cost pass-through assumptions and cooperative procurement volume commitments.
Material uncertainties — subsidy conditionality revisions, battery cell supply disruptions, and EU AI Act liability framework delays — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
China Agricultural Machinery Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Latin America Agricultural Machinery Market
Agricultural Machinery
Agriculture Tire Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Electric Farm Tractor Market