
 All-Purpose Seasoning Market | 2026-2036
All-Purpose Seasoning Market Size, Share, and Industry Trends Forecast 2026-2036
All-Purpose Seasoning Market Analytics
India is tilting toward expanded seasoning production as domestic spice processing capacity scales to serve export and food service buyers. McCormick leverages its North American distribution infrastructure to sustain shelf-space dominance across conventional and premium lines. Kerry Group anchors European supply through specialized taste-modulation technologies that reduce sodium without flavor loss.
All-purpose seasoning denotes a pre-formulated blend of spices, herbs, salts, and flavor enhancers designed for direct application across multiple protein and vegetable preparations, typically containing between 5 and 15 individual ingredients with standardized granulation for uniform dispersion. The product category serves industrial kitchens, retail consumers, and institutional food operators seeking consistency and labor reduction in flavor delivery. Organic and low-sodium variants are capturing margin pools as health-positioned buyers trade up from conventional blends, while food service applications lead volume throughput due to operational efficiency demands in commercial kitchens. Sachet and bulk packaging formats are splitting growth trajectories, with single-serve sachets accelerating in emerging markets and bulk formats retaining institutional loyalty.
The FDA's Food Safety Modernization Act traceability rules and sodium reduction guidelines are pressuring reformulation cycles and supplier documentation standards across the United States. The European Food Safety Authority's additive evaluations and the EU Green Deal agricultural sourcing requirements are tightening ingredient provenance rules for exporters serving European buyers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven margin erosion and supply disqualification.
Market Dynamics
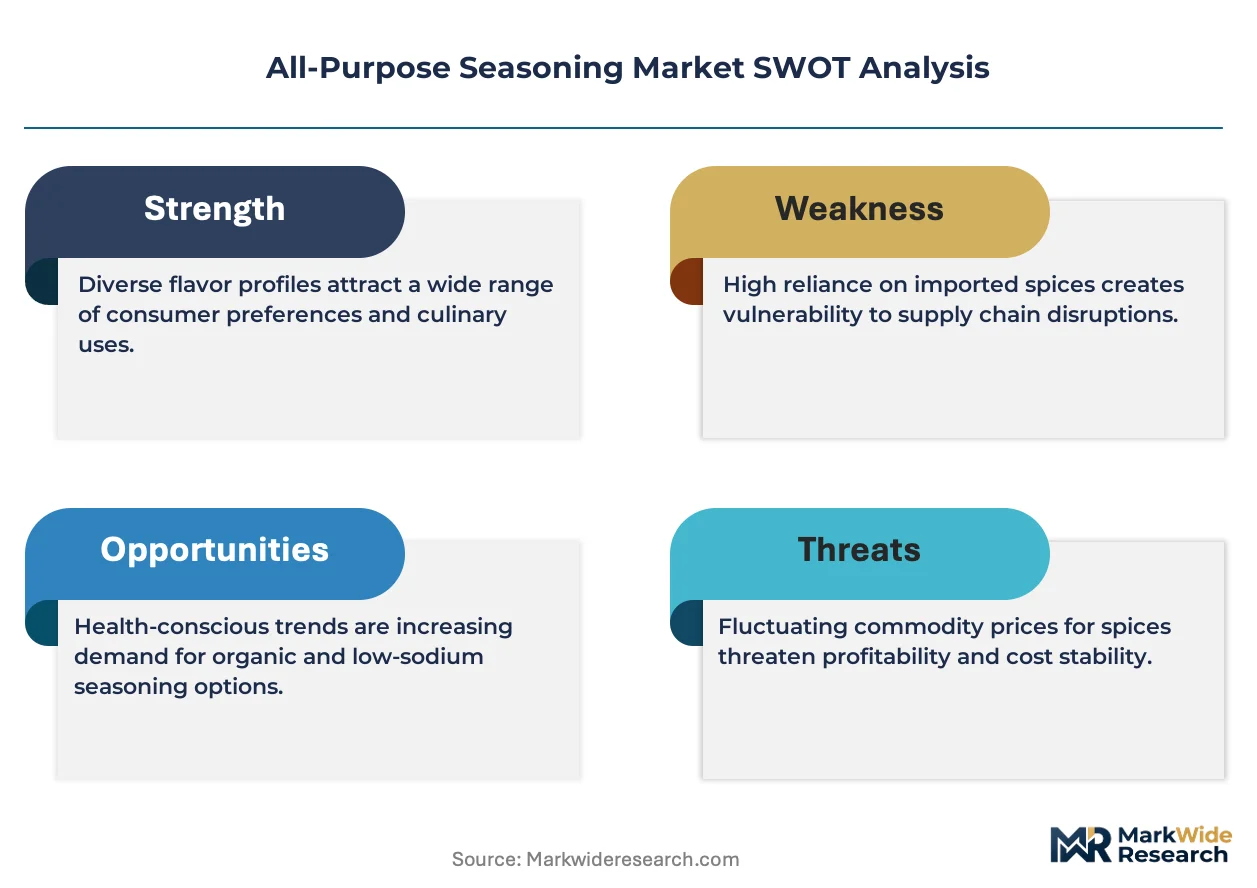
Clean-label procurement mandates from restaurant chains are compressing formulation cycles and forcing suppliers to rebuild documentation systems from farm to finished blend.
Growth Catalysts
- FSMA Traceability Mandates:The FDA's enhanced record-keeping requirements are accelerating supplier consolidation as smaller blenders lack capital for lot-tracking infrastructure.
- Quick-Service Kitchen Automation:Chains deploying robotic cooking lines require pre-standardized granulation that reduces manual measuring and speeds throughput.
- Southeast Asian Export Corridors:Flavor localization investments in Vietnam and Indonesia are opening premium positioning for Western blenders adapting to regional palate profiles.
Market Restraints
- Spice Input Volatility:Black pepper and cumin harvest fluctuations in India and Vietnam create margin compression for blenders locked into annual food service contracts.
- Single-Source Concentration:Over-reliance on Kerala and Gujarat processing clusters exposes supply chains to monsoon disruption and port congestion.
- Sodium Reduction Technical Ceiling:Current potassium chloride substitutes hit bitter taste thresholds at 30% salt replacement, limiting clean-label claims.
Strategic Opportunities
- Mexico Manufacturing Expansion:Proximity to US food service buyers and favorable trade terms under USMCA create cost advantages for bulk production.
- Plant-Based Protein Pairing:Emerging meat-alternative brands require customized umami-forward blends that mask off-notes in pea and soy isolates.
- EU Green Deal Sourcing Incentives:Carbon-certified spice procurement pathways offer tariff advantages and retail shelf access for compliant exporters.
Industry Challenges
- Clean-Label Certification Timelines:Organic and non-GMO verification cycles stretch 14-18 months, delaying product launches and freezing R&D pipelines.
- Legacy ERP Integration:Batch-tracking software from seed to sachet requires retrofitting decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Purpose Seasoning Market |
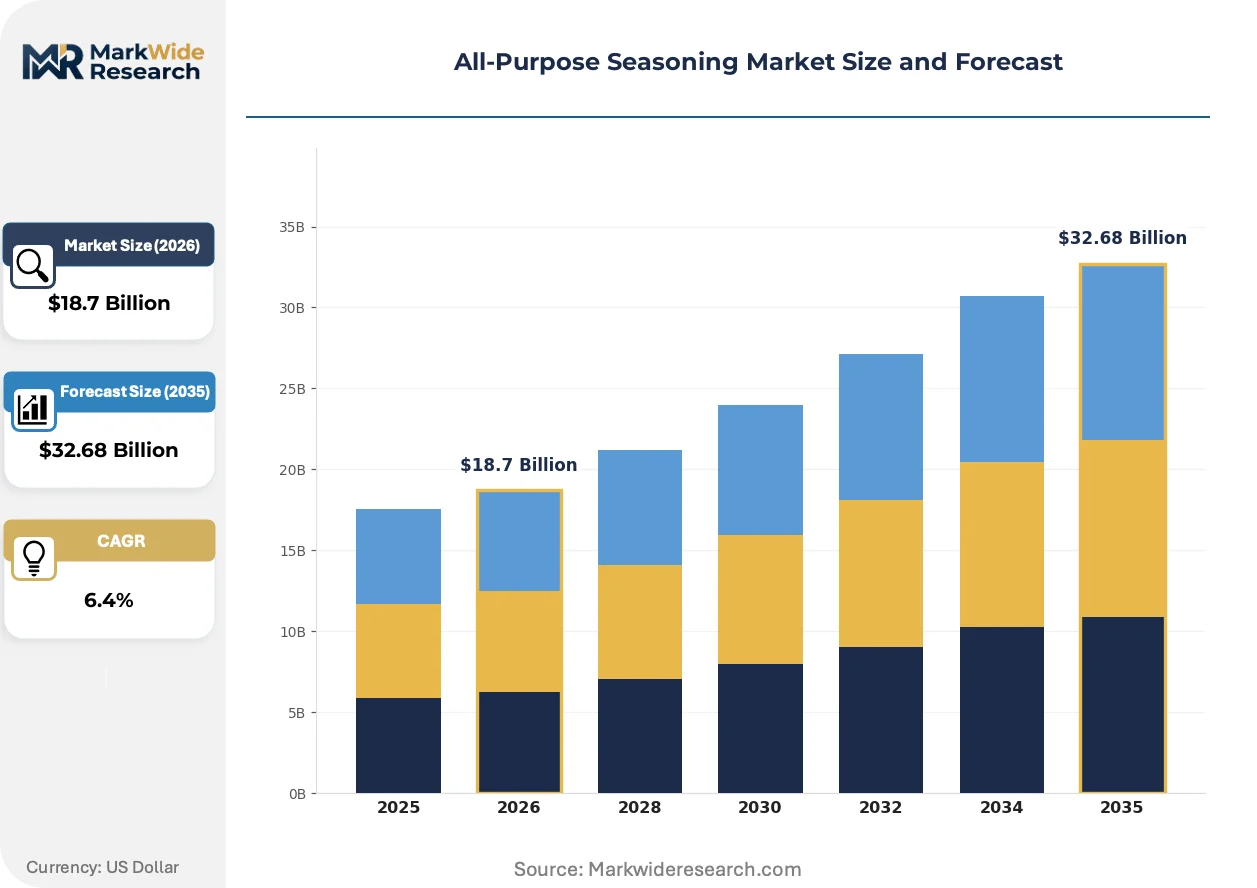
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Low Sodium, Gluten-Free, Conventional Use Case: Retail, Food Service, Home Cooking, Catering Packaging Type: Bottle, Sachet, Bulk, Jar Distribution Channel: Online, Supermarket, Specialty Store, Wholesale |
| Companies Covered | McCormick, Kerry Group, Cargill Incorporated, Ajinomoto, Olam Group, Goya Foods, Frontier Co-op, Sensient Technologies, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Purpose Seasoning Market Evolving Landscape
Reformulation science and digital supply chain tools are redrawing competitive boundaries between commodity blenders and specialized solution providers.
Encapsulated salt technology is collapsing the trade-off between sodium reduction and flavor intensity. Micro-encapsulation of potassium chloride and yeast extracts masks metallic off-notes while maintaining salt crystal dissolution timing. Quick-service chains in the United States are piloting these blends in fried chicken and burger applications where salt perception drives repeat purchase.
EFSA additive re-evaluations are tightening the approved substance list for European-bound seasonings. The 2023-2025 systematic review of flavor enhancers and anti-caking agents is forcing exporters to purge silicon dioxide and certain yeast extract grades from formulations. Blend houses serving EU retail channels are rebuilding master formulas and accelerating natural alternative sourcing from fermentation-derived suppliers.
Direct-procurement platforms are disintermediating traditional spice traders. Large food manufacturers now contract Kerala and Madagascar cooperatives through blockchain-verified marketplaces, slashing intermediary margins and compressing price discovery cycles. This channel shift is most advanced in vanilla and black pepper categories, with paprika and chili powder platforms now emerging.
All-Purpose Seasoning Market Segmentation
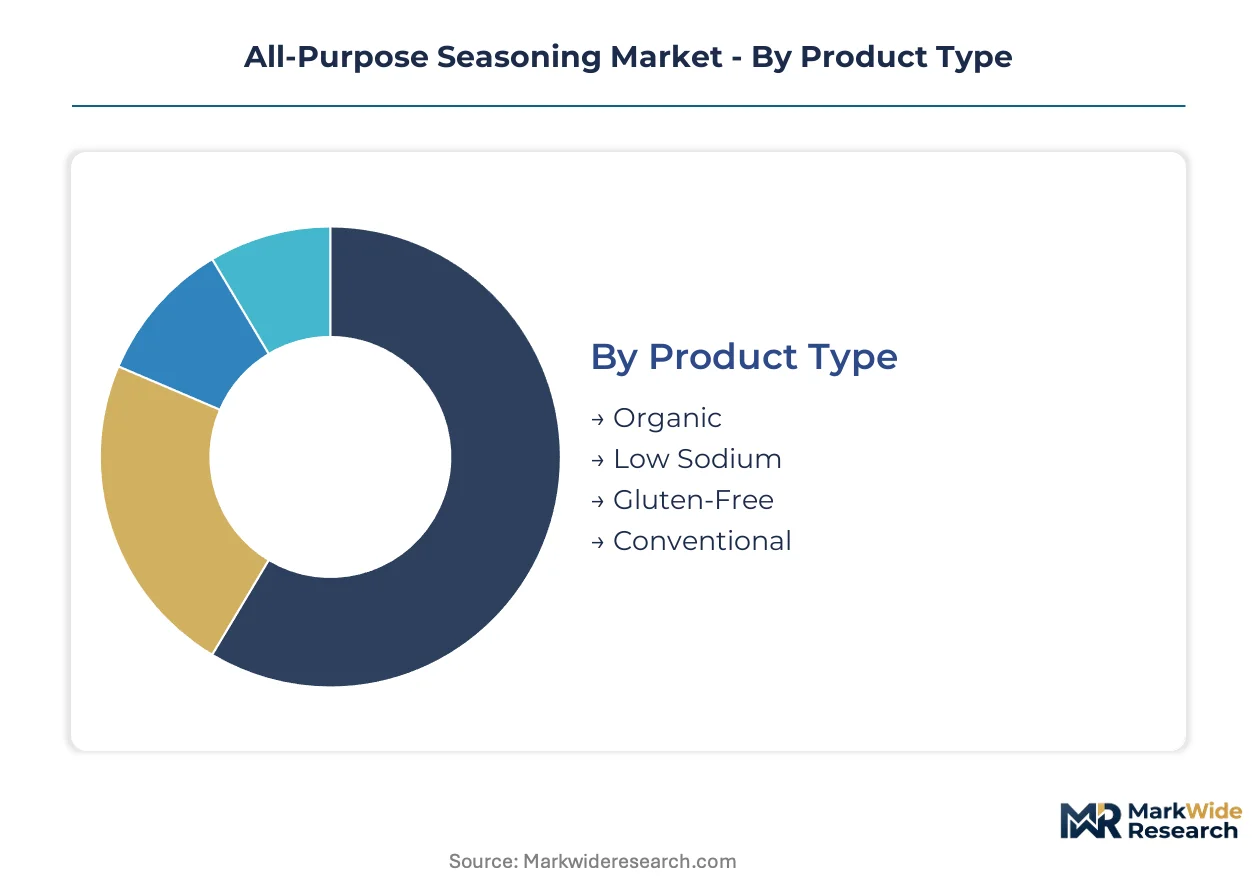
Segmentation in all-purpose seasoning reveals how formulation, packaging, and channel choices map to distinct margin profiles and inventory velocities. Cycle times vary dramatically: food service bulk turns monthly while retail specialty bottles sit for quarters. Understanding these patterns exposes where working capital concentrates and where reformulation investments pay fastest.
Product Type:
Organic and low-sodium variants compress formulation cycles to meet certification windows, while conventional blends turn on commodity spice arbitrage with minimal regulatory friction.
- Organic:Certification through USDA National Organic Program or EU organic regulations requires 14-18 month verification pipelines. Demand clusters in Whole Foods Market and European retail banners where shelf placement premiums offset input costs from certified Kerala and Madagascar cooperatives.
- Low Sodium:Encapsulated potassium chloride and yeast extract technologies mask metallic off-notes at 30% salt replacement thresholds. Quick-service chains in the United States pilot these blends in fried chicken applications where sodium reduction targets from FDA pressure compliance without flavor loss.
- Gluten-Free:Third-party verification prevents cross-contamination in shared milling facilities. Celiac-safe positioning captures specialty retail shelf space in Germany and Australia.
- Conventional:Standard salt-spice-herb matrices dominate institutional procurement through price-competitive annual contracts. Volume throughput sustains processor margins despite input volatility from Indian monsoon patterns.
Conventional blends dominate installed base. Low-sodium formulations are where expansion concentrates.
Use Case:
Volume scale separates food service procurement from retail, while labor reduction drives adoption across commercial kitchens versus home experimentation.
- Food Service:Robotic cooking lines in quick-service chains demand pre-standardized granulation eliminating manual measuring. McDonald's and Chipotle procurement specifications dictate particle size distributions and dissolution timing for automated dispensers.
- Retail:Sachet and bottle formats compete for pantry shelf space with flavor novelty positioning. Mexican and Southeast Asian export corridors show premium localization opportunities for Western blenders adapting to regional palate profiles.
- Home Cooking:Recipe integration through meal kit partnerships drives trial. Blue Apron and HelloFresh specify custom blends reducing consumer preparation steps.
- Catering:Bulk-to-portion flexibility serves event volume volatility. Institutional buyers balance cost control against consistency requirements for multi-location service.
Food service commands volume leadership. Retail specialty positioning shows steepest expansion trajectory.
Packaging Type:
Format selection traces directly to use environment: moisture control for humid climates, portion precision for cost accounting, shelf presence for impulse purchase.
- Sachet:Single-serve portions dominate emerging market penetration where trial pricing and humidity protection matter. Vietnamese and Indonesian distribution favors foil-laminated sachets over bulk alternatives.
- Bulk:Institutional buyers in the United States specify 25-50 pound poly-lined corrugated totes for back-of-house efficiency. Portion control systems integrate directly with inventory management software.
- Bottle:Shaker-top PET and glass containers secure mainstream retail placement. McCormick's North American distribution infrastructure sustains shelf-space dominance through conventional and premium lines.
- Jar:Wide-mouth glass supports spoon-measure cooking behavior in European home kitchens. Premium positioning through tactile weight and reuse potential.
Bulk formats dominate installed base. Sachet packaging is where expansion concentrates.
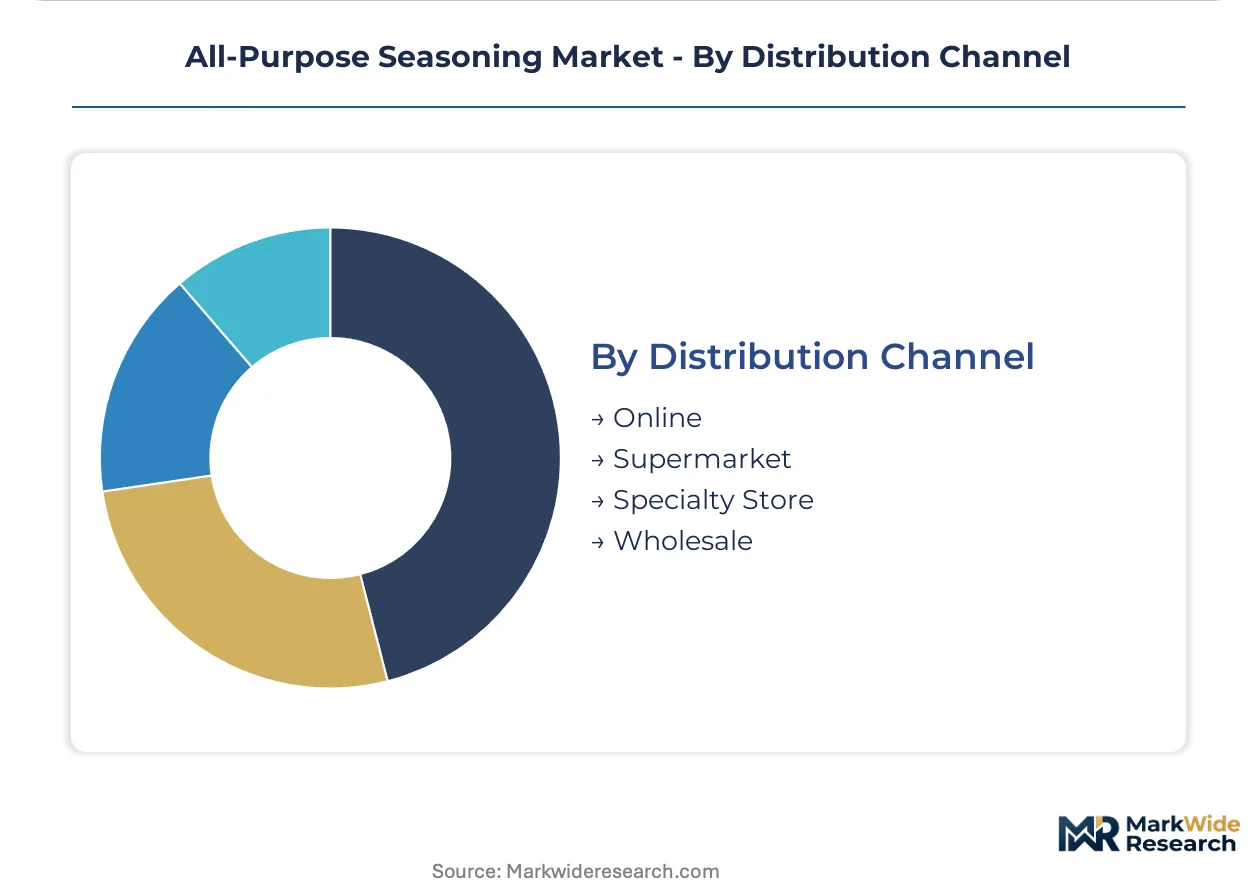
Distribution Channel:
Channel mix determines margin capture: direct platforms disintermediate traders, while specialty retail rewards provenance storytelling with price premiums.
- Supermarket:Slotting fees and planogram compliance dominate mass-market access. Kerry Group anchors European supply through specialized taste-modulation technologies that reduce sodium without flavor loss.
- Online:Direct-to-consumer subscription models capture repeat purchase data. Amazon and specialized spice platforms enable flavor discovery without physical shelf constraints.
- Wholesale:Restaurant depot and cash-and-carry formats serve independent operators with case-quantity flexibility. FSMA traceability mandates pressure documentation standards across distributor networks.
- Specialty Store:Independent retailers reward carbon-certified and fair-trade sourcing with prominent placement. EU Green Deal agricultural requirements tighten ingredient provenance rules for compliant exporters.
Supermarket channels dominate installed base. Online direct platforms are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spice processing clusters in India and Vietnam concentrate upstream supply for blenders serving export markets. FDA traceability mandates and EU Green Deal sourcing requirements are redirecting procurement flows toward compliant origins.
United States
Quick-service chains drive bulk procurement of pre-standardized granulations for automated kitchen lines. FDA sodium reduction targets and FSMA traceability rules pressure reformulation cycles and supplier documentation standards. Chicago and Dallas food service hubs concentrate distribution infrastructure for national restaurant networks.
Germany
Retail demand for organic and carbon-certified blends intensifies under EU Green Deal agricultural requirements. EFSA additive re-evaluations tighten approved substance lists, forcing exporters to purge silicon dioxide from formulations. Hamburg and Rotterdam corridor ports handle spice imports for European processing.
India
Domestic spice processing capacity scales to serve export and food service buyers from Kerala and Gujarat clusters. FSSAI food safety regulations and DGFT export incentives shape compliance frameworks for outbound shipments. Kochi and Unjha processing centers expand clean-label certification pipelines for Western retail channels.
Vietnam
Flavor localization investments target regional palate profiles for Southeast Asian export corridors. Black pepper harvest fluctuations create input volatility for blenders locked into annual contracts. Ho Chi Minh City packaging hubs specialize in foil-laminated sachets for humid climate distribution.
Mexico
Proximity to US food service buyers and favorable USMCA trade terms attract bulk production expansion. Clean-label procurement mandates from restaurant chains compress formulation cycles for cross-border supply. Mexico City and Nuevo León manufacturing zones integrate with Texas distribution networks.
All-Purpose Seasoning Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in granulation and encapsulation technology. The vendor base spans consolidated multinational blenders and fragmented regional processors. Three archetypes dominate: taste-modulation technology licensors, clean-label certification specialists, and commodity-scale spice traders. M&A activity concentrates in traceability software and fermentation-derived flavor alternatives.
Within the multinational platform tier, McCormick and Kerry Group exemplify divergent geographic anchoring strategies. McCormick leverages North American distribution infrastructure for shelf-space dominance across conventional and premium lines. Kerry Group occupies a position in European supply through specialized taste-modulation technologies. Ajinomoto represents the Asian fermentation-derived ingredient archetype, sitting upstream of finished blend formulation.
| Leading Market Players |
|---|
| McCormick |
| Kerry Group |
| Cargill Incorporated |
| Ajinomoto |
| Olam Group |
| Goya Foods |
| Frontier Co-op |
| Sensient Technologies |
| DSM-Firmenich |
| Others |
Value Network & Pricing Analysis
Single-source concentration in Kerala and Gujarat spice processing clusters compresses pricing power for blenders locked into annual food service contracts while simultaneously dictating supply chain redundancy investments. Tariff exposure under evolving trade agreements and monsoon-driven harvest volatility create tiered margin structures that separate multinational platforms from regional processors.
Pricing Analysis
FDA sodium reduction targets and FSMA traceability mandates dictate the pricing tier structure across the all-purpose seasoning market. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified blends with 14-18 month verification pipelines from conventional commodity formulations and private-label economy tiers. Cost compression in the standard tier is intensifying because encapsulated potassium chloride substitutes hit technical ceilings at 30% salt replacement, forcing reformulation investments. Food service buyers exhibit highest price sensitivity due to annual contract lock-ins, while specialty retail channels absorb premium positioning for carbon-certified provenance.
Supply Chain Analysis
Black pepper and cumin feedstock from India and Vietnam, plus paprika from Spain and Peru, anchors upstream sourcing for blenders serving Western markets. Raw material dependencies center on monsoon-sensitive harvest cycles, port congestion at Kochi and Nhava Sheva, and fermentation-derived yeast extract capacity from Ajinomoto's Asian production network. Single-source vulnerability concentrates in Kerala's organic certification pipelines where 14-18 month verification timelines create supply rigidities. Distribution runs through McCormick's North American infrastructure and Kerry Group's European taste-modulation platforms, with emerging direct-procurement blockchain marketplaces disintermediating traditional spice traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label certification pipelines and encapsulated salt technologies are reshaping competitive boundaries, with regulatory compliance timelines becoming the primary capacity constraint for market participants.
For Market Incumbents: Pre-empt supply disruption by securing captive organic processing capacity in Kerala and Gujarat clusters before verification backlogs extend further. Accelerate backward integration into fermentation-derived flavor alternatives to offset EFSA additive restrictions on silicon dioxide and conventional yeast extracts. Defensive patent positioning around micro-encapsulation timing technologies will block emerging entrants from quick-service chain pilot programs. For New Entrants and Emerging Players: Establish a beachhead in plant-based protein pairing formulations where umami-forward blends mask off-notes in pea and soy isolates. Target Mexico manufacturing zones under USMCA terms to serve Texas and California food service hubs with compressed lead times. Direct-procurement platform integration with Madagascar and Kerala cooperatives offers margin capture unavailable to legacy traders. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors taste-modulation technology licensors and traceability software providers over commodity-scale blenders. Acquisition targets should demonstrate FSMA-compliant lot-tracking infrastructure and established relationships with quick-service chain procurement specifications. The signal to watch is accelerated M&A activity in encapsulated salt technology patents and blockchain-verified spice marketplaces.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Pipeline Investment | USDA National Organic Program verification secures Whole Foods Market shelf placement premiums against 14-18 month timelines. |
| Encapsulated Salt Technology Licensing | Micro-encapsulation patents enable 30% sodium reduction in McDonald's and Chipotle fried chicken applications without flavor loss. |
| Mexico Manufacturing Footprint Expansion | USMCA proximity advantages reduce cross-border logistics costs for Texas and California food service distribution networks. |
| Direct-Procurement Platform Integration | Blockchain-verified Kerala cooperative contracts disintermediate traditional spice traders and compress price discovery cycles. |
| Fermentation-Derived Flavor Alternative Sourcing | Ajinomoto's yeast extract technologies replace restricted silicon dioxide additives for EFSA-compliant European retail formulations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA FSMA guidance documents, EFSA additive re-evaluation records, and USDA National Organic Program certification databases. Primary interviews engaged procurement directors at quick-service chains, spice processing plant managers in Kerala and Gujarat, and regulatory affairs leads at multinational blenders. Secondary validation drew from customs trade data on black pepper and cumin imports, SEC 10-K filings of listed seasoning companies, and EU Green Deal agricultural sourcing requirement publications. Bottom-up volume modeling from food service procurement specifications and top-down value estimates from retail scanner data were cross-referenced for triangulation.
Forecast inputs span product type segmentation across organic, low-sodium, gluten-free, and conventional formulations; use case dimensions separating food service, retail, home cooking, and catering channels; and packaging type splits between sachet, bulk, bottle, and jar formats. CAGRs were derived from trend extrapolation of clean-label procurement mandates and sodium reduction compliance timelines, calibrated against historical spice input volatility patterns and trade corridor expansion trajectories.
Sensitivities concentrate around monsoon disruption severity in Indian processing clusters, EFSA additive list revisions, and USMCA tariff renegotiation outcomes. Cross-checking against FAO spice price indices and food service industry procurement survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
White Pepper Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Ginger Salt Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Cajun Seasoning Market
Spices and Seasonings
Mint Oils Market