
 Flour Mixes Market | 2026-2036
Flour Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Flour Mixes Market Foresight
Recipe-as-a-service platforms and subscription-based formulation delivery is decoupling flour mix purchasing from traditional bulk commodity contracts. ADM leverages its vertically integrated grain handling network to sustain supply security for industrial bakeries across North America. Lesaffre anchors European demand through specialized yeast-integrated premix portfolios that reduce client-side blending complexity. PURATOS competes on clean-label innovation, extending its position in enzyme-based dough conditioners that replace chemical additives.
Flour mixes are industrially formulated blends of milled cereals, functional additives, and conditioning agents designed to deliver consistent rheological and nutritional performance in commercial baking and extrusion processes. Standard specifications include protein content between 10-14%, ash levels below 0.55%, and water absorption rates calibrated to 58-62% for bread applications. Wheat flour mix remains the dominant category by volume, though pulse flour mix is gaining fastest as plant-protein formulations displace conventional bases in gluten-free and high-fiber product lines. Snack production applications command premium margins due to specialized particle size requirements and seasoning adhesion properties that standard bakery blends cannot satisfy.
The FDA governs enriched flour standards under 21 CFR 137, while the EU enforces additive limits through EFSA-evaluated regulations, and India's FSSAI mandates fortification protocols for institutional food programs. These frameworks shape formulation choices, with compliance costs pushing smaller regional blenders toward co-manufacturing arrangements with certified facilities. Stakeholders must monitor evolving allergen labeling requirements and emerging carbon-footprint disclosure rules that will soon filter supplier selection criteria across bakery and confectionery channels.
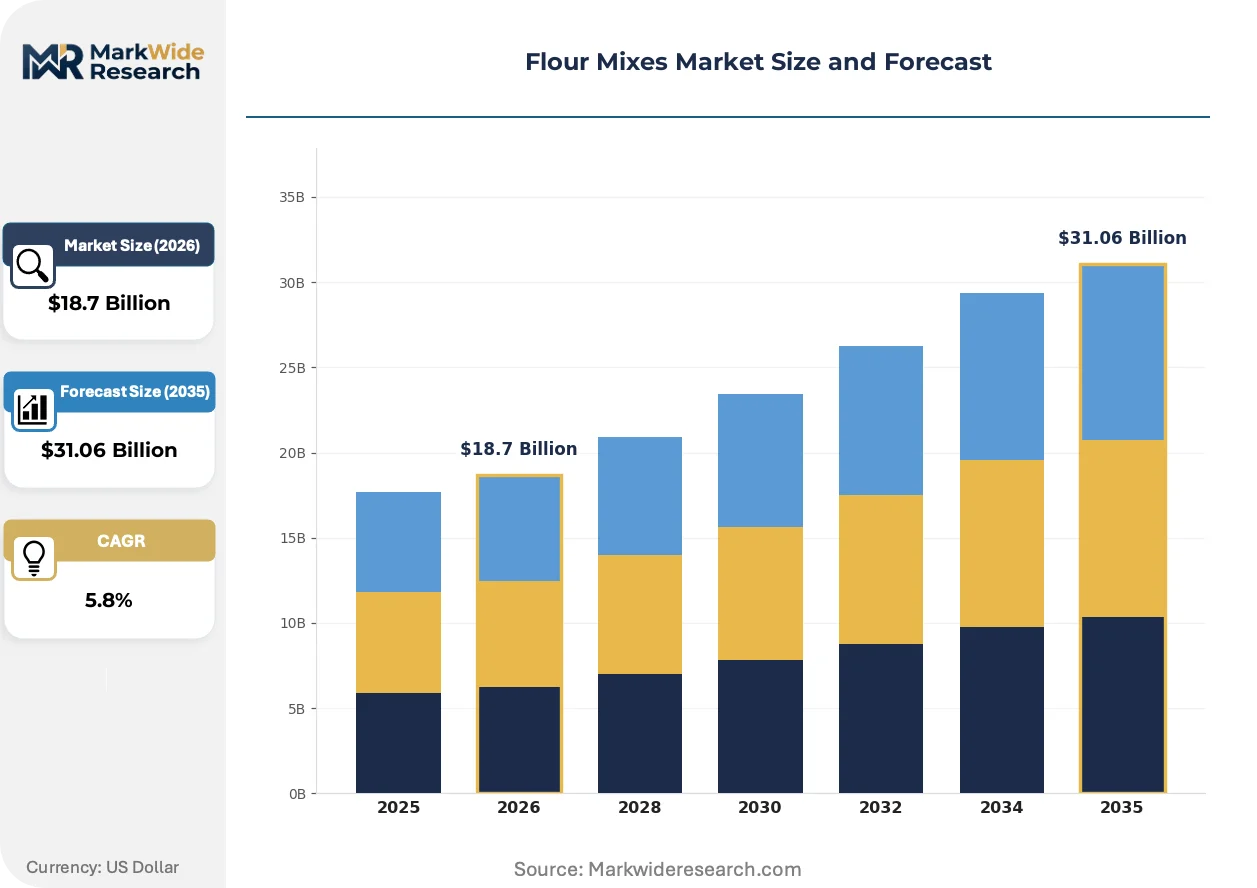
Market Dynamics
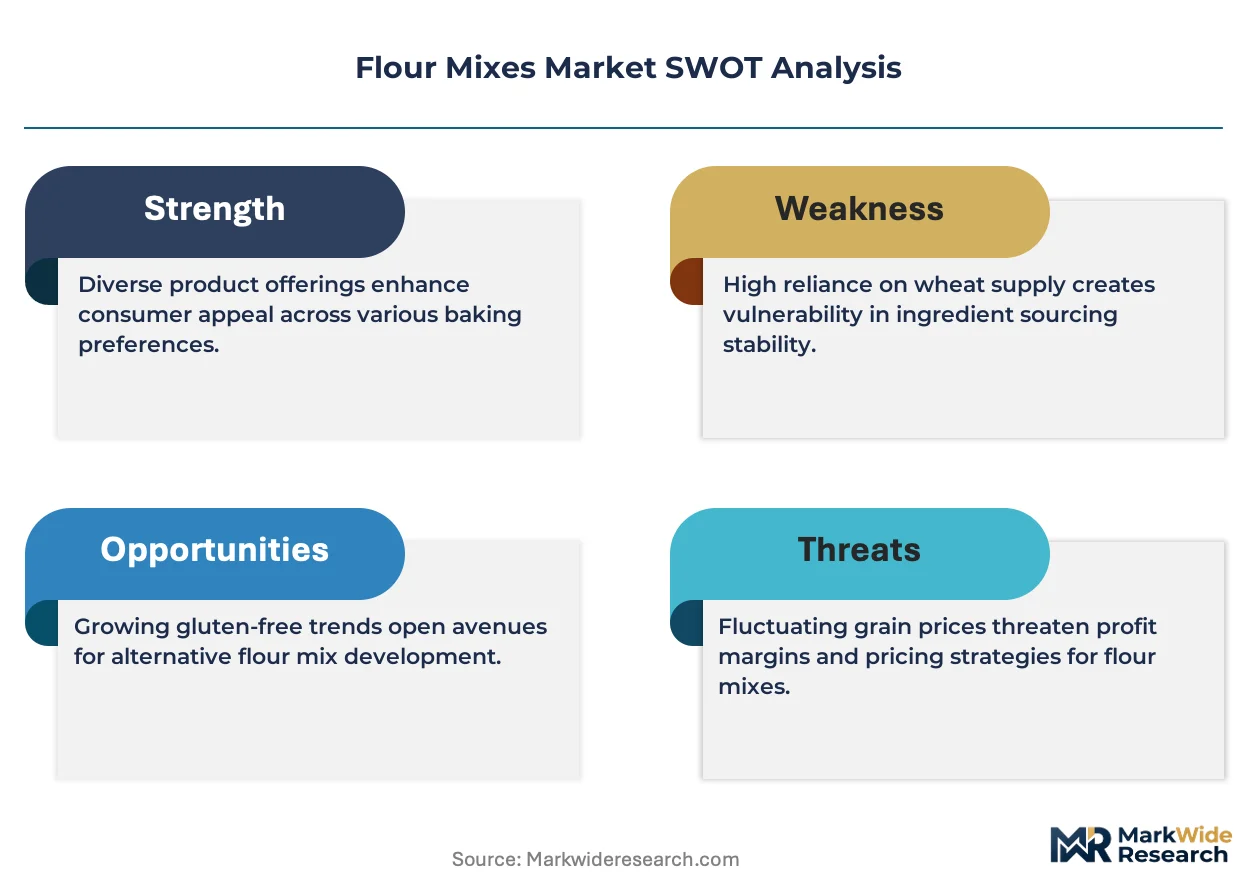
Clean-label mandates from EFSA and FDA are forcing reformulation cycles across industrial bakery supply chains, compressing product development timelines while elevating enzyme-based conditioners over chemical additives in premix specifications.
Growth Catalysts
- India FSSAI Fortification Mandate:Institutional feeding programs now require iron-folic acid enrichment in wheat flour distributed through government channels, expanding addressable volume for certified blenders supplying mid-scale mills.
- Pulse Protein Extraction Advances:Mechanical dehulling and air-classification systems have improved chickpea and lentil flour functionality, enabling gluten-free bakery applications with protein levels matching wheat-based benchmarks.
- Snack Extrusion Complexity:Seasoning adhesion requirements for coated savory products demand specialized particle size distributions that standard bakery mixes cannot achieve, creating premium formulation niches.
Market Restraints
- Wheat Price Volatility:Black Sea supply disruptions and drought cycles in North American growing regions transmit directly into input cost instability for premix manufacturers lacking forward-contract coverage.
- Additive Regulatory Divergence:EFSA's tightening restrictions on emulsifiers and oxidizing agents conflict with FDA 21 CFR 137 permissiveness, forcing dual-SKU strategies that inflate inventory carrying costs.
- Almond Flour Substitution:Keto-formulation brands are displacing conventional wheat mixes in retail channels, though industrial bakeries retain premix dependency for scale consistency.
Strategic Opportunities
- Sub-Saharan Africa Institutional Baking:UN World Food Programme procurement and nascent supermarket chains in Nigeria and Kenya create demand for shelf-stable, vitamin-premixed flours with extended tropical storage stability.
- Enzyme-Clean-Label Convergence:Transglutaminase and lipase systems are replacing DATEM and SSL in dough conditioning, satisfying EFSA additive limits while maintaining industrial process tolerance.
- Direct-to-Bakery Digital Platforms:Recipe-as-a-service models bypass traditional distributor networks, enabling small-batch customization and just-in-time delivery for artisan and regional bakery chains.
Industry Challenges
- Formulation Chemist Scarcity:Industrial baking science programs have contracted across European technical universities, constraining R&D bandwidth for enzyme-integrated premix development.
- Co-Manufacturing Certification Lag:Third-party blending facilities face 18-24 month timelines for FSSC 22000 and organic accreditation, delaying market entry for regional ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flour Mixes Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Flour Mix, Corn Flour Mix, Rice Flour Mix, Multigrain Mix, Pulse Flour Mix Form: Powdered, Granular, Pre-blended, Enriched, Fortified Application: Baking, Confectionery, Snack Production, Pasta Manufacturing, Breakfast Cereals End User: Bakeries, Food Processing Units, Restaurants, Hotels, Catering Services |
| Companies Covered | ADM, Lesaffre, Bakels Group, PURATOS, Associated British Foods plc, Allied Pinnacle Pty. Ltd., Rich Products Corp., Nisshin Seifun Group Inc., Interflour Group Pte Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flour Mixes Market Shifts & Advancements
Enzymatic conditioning systems and digital formulation platforms are converging to displace legacy chemical additive portfolios, while regulatory divergence between major jurisdictions forces adaptive manufacturing architectures.
Enzyme-based dough conditioners are unifying rheological control and clean-label compliance in a single ingredient class. Industrial bakeries in the EU and North America are accelerating adoption as EFSA and FDA scrutiny tightens on azodicarbonamide and potassium bromate. This technology is unifying what were previously separate additive categories—oxidizers, emulsifiers, and reducing agents—into streamlined enzyme portfolios that reduce supplier complexity and inventory SKUs.
EFSA's 2023 re-evaluation of food additive safety profiles has triggered accelerated phase-outs of titanium dioxide and certain phosphate esters in bakery applications. Reformulation costs are concentrating among mid-tier European blenders lacking captive enzyme production capabilities. Snack and cracker segments face the steepest compliance burdens, as these categories historically relied heavily on whiteners and texture modifiers now under regulatory pressure.
Bakery procurement teams are consolidating supplier relationships around full-service premix partners capable of integrated yeast, enzyme, and flour sourcing. Distributor networks that historically stocked commodity flour and separate additive lines are losing share to vertically integrated formulation houses. This consolidation pattern is most pronounced in France and Germany, where industrial bakery chains have centralized purchasing at the holding-company level.
Flour Mixes Market Segmentation
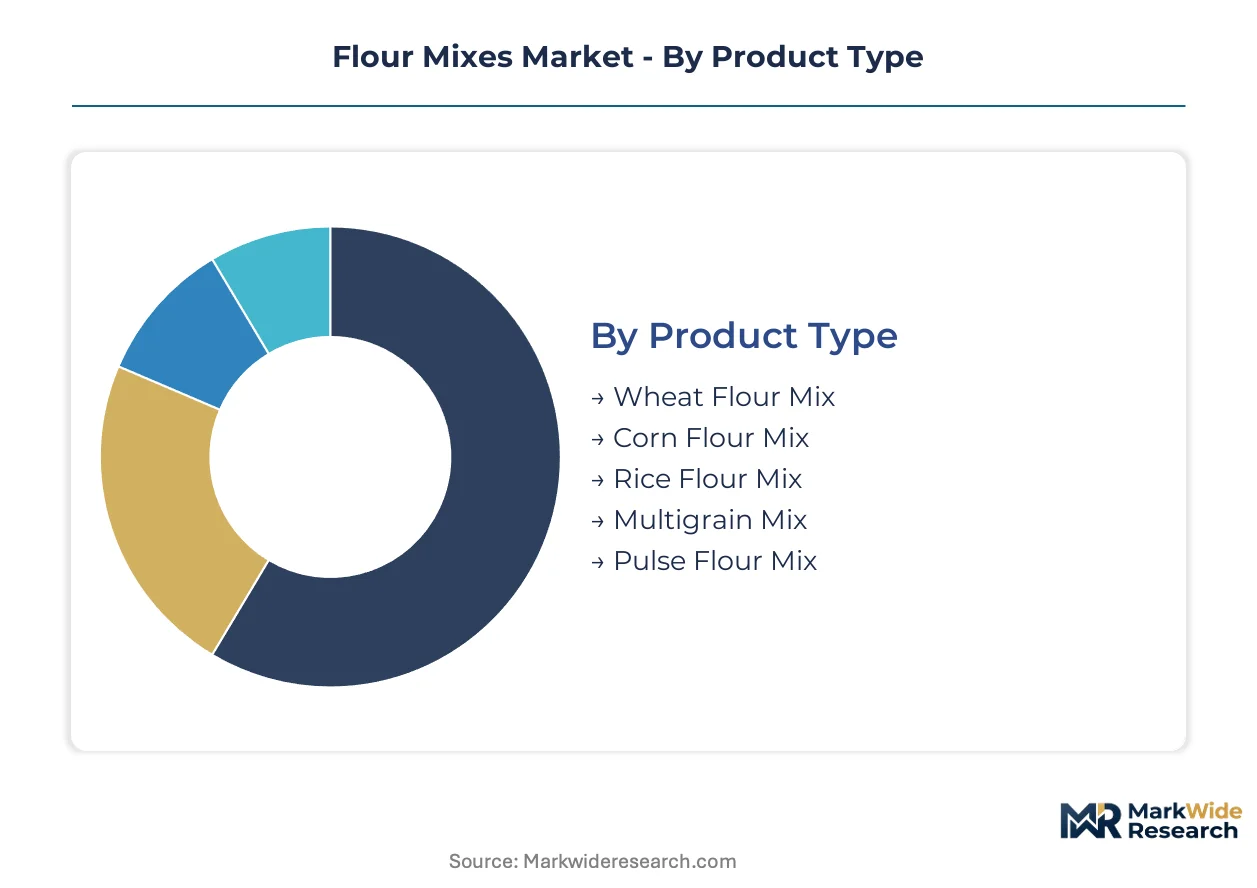
Industrial bakers select flour mixes based on rheological performance requirements and regulatory compliance obligations. Each segment category reflects distinct technical specifications that determine suitability for specific production processes and end-use applications.
Product Type:
Replacement cycles in commercial baking drive shifts toward functional alternatives that reduce dependency on single-commodity inputs.
- Wheat Flour Mix:Standard formulations contain 10-14% protein content with ash levels below 0.55% and water absorption calibrated to 58-62% for bread applications. Industrial bakery chains in India source this category through government procurement channels under FSSAI fortification mandates.
- Pulse Flour Mix:Mechanical dehulling and air-classification systems have improved chickpea and lentil flour functionality to match wheat-based protein benchmarks. Gluten-free product lines in North American and European retail channels are absorbing expanding volumes as clean-label preferences intensify.
- Corn Flour Mix:Masa and extrusion-grade specifications serve tortilla and snack manufacturing with particle size distributions optimized for alkaline cooking processes.
- Rice Flour Mix:Fine-milled and pre-gelatinized variants address Asian noodle production and gluten-free bakery applications with specific amylose content requirements.
- Multigrain Mix:Composite formulations blend wheat, rye, oats, and seeds to achieve fiber claims and visual differentiation in artisan bread segments.
Wheat Flour Mix sits at the top of the volume ranking, with Pulse Flour Mix climbing the fastest.
Form:
Cost tier differentiation separates commodity-grade powders from premium fortified formulations that command manufacturing complexity premiums.
- Powdered:Standard particle size distributions below 150 microns provide uniform hydration in high-speed mixing environments. Bulk procurement by industrial bakeries in Germany and France concentrates demand for this baseline format.
- Fortified:Iron-folic acid and B-vitamin enrichment protocols comply with institutional feeding program requirements in India and Sub-Saharan Africa. UN World Food Programme procurement specifications are accelerating adoption for shelf-stable tropical storage applications.
- Granular:Coarse particle structures improve flow characteristics in pneumatic conveying systems for large-scale milling operations.
- Pre-blended:Complete formulations incorporating conditioners and enzymes reduce client-side blending complexity for mid-scale bakery operations.
- Enriched:FDA 21 CFR 137 compliant formulations meet US enrichment standards for thiamin, riboflavin, niacin, and folic acid restoration.
Powdered form dominates procurement volumes, while Fortified formats are expanding most quickly in institutional channels.
Application:
Application-specific margin structures concentrate R&D investment toward segments with specialized technical barriers.
- Snack Production:Extrusion-grade mixes require precise particle size distributions for seasoning adhesion and expansion control. Coated savory product manufacturers pay formulation premiums that standard bakery blends cannot command.
- Baking:Bread and pastry applications consume the largest absolute volumes through industrial bakery chains and artisan cooperatives. EFSA additive restrictions are forcing enzyme-based conditioner adoption across European production facilities.
- Confectionery:Low-protein cake flour specifications with chlorinated or heat-treated options provide tender crumb structures for high-ratio formulations.
- Pasta Manufacturing:Durum semolina blends and egg pasta mixes require specific gluten strength and color retention properties.
- Breakfast Cereals:Flaking and puffing processes demand precise moisture content and starch damage levels for texture consistency.
Baking commands the largest volume position, with Snack Production generating the steepest expansion trajectory in value terms.
End User:
Customer-type concentration patterns favor direct-supply relationships with large-scale operators over fragmented distributor networks.
- Bakeries:Industrial chains in France and Germany have centralized purchasing at holding-company levels, consolidating supplier relationships around full-service premix partners. Recipe-as-a-service platforms are penetrating artisan and regional bakery segments with just-in-time customization.
- Food Processing Units:Extrusion and ready-meal manufacturers require certified blending facilities with FSSC 22000 accreditation. Co-manufacturing certification timelines of 18-24 months constrain regional supplier entry.
- Restaurants:Casual dining and quick-service chains source pre-portioned mixes for consistency across franchise locations.
- Hotels:In-house bakery operations in hospitality groups demand flexible batch sizes and specialty formulation access.
- Catering Services:Institutional feeding contractors prioritize shelf stability and fortification compliance over premium texture attributes.
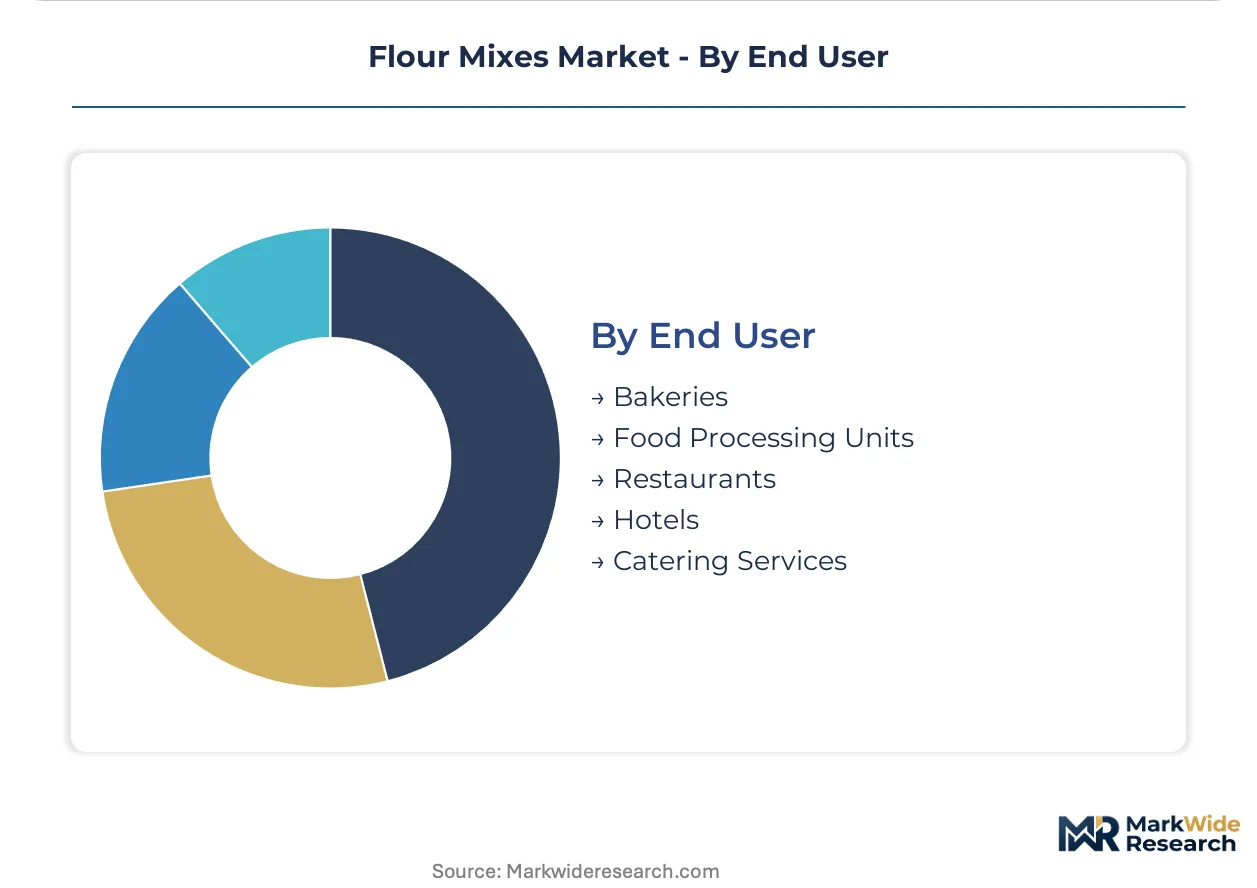
Food Processing Units represent the fastest-growing customer category as extrusion complexity requirements deepen technical supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India institutional procurement volumes now rival German industrial bakery demand, though regulatory frameworks diverge sharply between FSSAI fortification mandates and EFSA clean-label restrictions.
United States
Industrial bakery chains consolidate purchasing around full-service premix partners capable of integrated enzyme and flour sourcing. FDA 21 CFR 137 enrichment standards govern thiamin, riboflavin, niacin, and folic acid restoration protocols. Chicago and Minneapolis-St. Paul milling clusters anchor North American grain processing capacity.
Germany
EFSA additive restrictions accelerate enzyme-based conditioner adoption across European production facilities. Holding-company level purchasing centralization concentrates supplier relationships. Munich and Stuttgart industrial bakery networks drive specialized premix specification demand.
India
FSSAI iron-folic acid fortification mandates expand addressable volume for certified blenders supplying mid-scale mills. Government procurement channels distribute enriched wheat flour through institutional feeding programs. Maharashtra and Gujarat wheat processing clusters scale rapidly to meet bakery chain expansion.
France
Yeast-integrated premix portfolios reduce client-side blending complexity for artisan and industrial bakeries. EFSA 2023 re-evaluation of food additive safety profiles triggers accelerated phase-outs of titanium dioxide. Paris and Lyon bakery cooperatives consolidate formulation sourcing.
Brazil
Snack extrusion complexity requirements deepen technical supplier relationships with certified blending facilities. ANVISA governs food additive limits and fortification protocols for institutional programs. São Paulo state food processing units command premium margins for specialized particle size formulations.
Flour Mixes Market Competitive Landscape
Top-tier vendors anchor full-service premix supply, while regional blenders gravitate toward co-manufacturing arrangements with certified facilities. The structure concentrates around vertically integrated grain handlers, specialized yeast-integrated formulation houses, and clean-label enzyme innovators. Three archetypes dominate: captive supply network operators, integrated fermentation-technology platforms, and enzyme-based conditioning specialists. Competitive moves center on backward integration into grain handling assets and digital platform deployment for direct-to-bakery distribution.
Among North American grain handlers, ADM exemplifies captive supply network architecture. Lesaffre and PURATOS occupy positions within the European fermentation-technology and clean-label enzyme tiers respectively. These three entities represent distinct strategic postures: upstream control over grain logistics, integrated yeast-premix portfolios, and enzyme-based additive replacement systems.
| Leading Market Players |
|---|
| ADM |
| Lesaffre |
| Bakels Group |
| PURATOS |
| Associated British Foods plc |
| Allied Pinnacle Pty. Ltd. |
| Rich Products Corp. |
| Nisshin Seifun Group Inc. |
| Interflour Group Pte Ltd. |
| Others |
Supply & Pricing Matrix
Wheat futures volatility transmits through Black Sea supply corridors into premix manufacturer cost structures, compressing margins for blenders lacking forward-contract coverage while elevating enzyme-integrated formulations to premium pricing tiers. Input cost instability feeds directly into three-tier pricing stratification across commodity-grade powders, fortified institutional blends, and specialized snack-extrusion formulations.
Pricing Analysis
Capacity additions in India are reshaping price floors for fortified wheat flour mixes as domestic processing clusters scale to meet FSSAI institutional procurement volumes. Three-tier pricing structure across premium enzyme-conditioned, standard fortified, and economy commodity blends reflects certification grade and vertical integration depth. Cost compression in mid-tier European blends is intensifying because EFSA additive restrictions force dual-SKU inventory strategies. Artisan bakeries exhibit highest price sensitivity, while snack manufacturers accept formulation premiums for seasoning adhesion performance.
Supply Chain Analysis
Domestic-content mandates in India's institutional feeding programs are reshaping sourcing patterns toward Maharashtra and Gujarat wheat processing clusters. Supply concentration centers on India, Germany, and the United States for specialized premix manufacturing. Raw material dependencies draw from Black Sea wheat corridors, North American enzyme production, and Canadian pulse protein extraction. Single-source vulnerability runs through concentrated enzyme supplier networks for clean-label conditioning systems. Distribution runs through vertically integrated formulation houses consolidating distributor relationships in France and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flour mixes constitute a late-cycle quality story as clean-label enzyme systems displace commodity chemical additives across European and North American industrial bakery procurement. Demand is concentrating toward premium specifications that unify rheological performance with regulatory compliance in single-ingredient-class solutions.
For Market Incumbents: Deploy captive grain handling networks to secure input cost stability against Black Sea supply disruptions. ADM-style upstream control over North American grain logistics anchors supply security for industrial bakery chains. Accelerate FSSC 22000 certification timelines for co-manufacturing partners to compress regional competitor entry windows. Enzyme-integrated portfolio expansion counters margin pressure from EFSA additive phase-outs. For New Entrants and Emerging Players: Capture Sub-Saharan Africa institutional baking demand through UN World Food Programme procurement channels for shelf-stable tropical formulations. Nigeria and Kenya supermarket chain expansion creates addressable white space lacking established premix supplier relationships. Direct-to-bakery digital platforms bypass entrenched distributor networks in artisan and regional bakery segments. Recipe-as-a-service models enable just-in-time customization without bulk inventory commitments. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier European blenders lack captive enzyme production capabilities to absorb EFSA reformulation costs. Acquisition targets cluster around certified blending facilities with FSSC 22000 accreditation and established institutional channel relationships. Long-term viability favors vertically integrated grain handlers with backward integration into enzyme technology platforms. Monitor EFSA additive re-evaluation timelines as inflection indicators for enzyme adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Production | Captive lipase and transglutaminase manufacturing secures margin control under EFSA additive restrictions. |
| Direct-to-Bakery Digital Platform Deployment | Recipe-as-a-service models bypass distributor networks for artisan and regional bakery chain penetration. |
| Sub-Saharan Africa Institutional Channel Entry | UN World Food Programme procurement specifications create shelf-stable formulation demand in Nigeria and Kenya. |
| FSSC 22000 Certification Acceleration | Compressed 12-month accreditation timelines block regional competitor co-manufacturing market entry. |
| Clean-Label Enzyme Portfolio Expansion | Transglutaminase systems replace DATEM and SSL emulsifiers under tightening EFSA safety evaluations. |
Research Methodology
Direct dialogue with industrial bakery procurement directors, premix formulation chemists, grain elevator operations managers, and FSSC 22000 certification auditors grounded qualitative insights across North American, European, and Indian markets. Secondary validation drew from FDA 21 CFR 137 enrichment standards documentation, EFSA food additive safety re-evaluations, FSSAI fortification mandate circulars, and customs trade data for wheat and pulse flour movements. Bottom-up volume triangulation against top-down expenditure flows verified segment-level demand estimates.
Segmentation outputs across product type, application, form, and end-user categories were modeled across the projection horizon. Wheat flour mix, pulse flour mix, and corn flour mix volumes were cross-referenced against industrial bakery chain expansion rates and institutional procurement program specifications. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory compliance cost burdens and enzyme substitution adoption curves. Snack production application premiums and fortified form growth trajectories were calibrated against UN World Food Programme procurement disclosures.
Black Sea supply disruptions, EFSA additive re-evaluation timelines, and FSSAI enforcement variability are the dominant revision risks that could alter volume and value trajectories. Forecasts reflect documented assumptions regarding enzyme cost curves and institutional program scale-up rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Doughnuts Market
Bakery Products
Global Cake Mix Market
Bakery Products
Laminated Dough Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Global Cakes Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Low Calorie Flour Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Bake Stable Pastry Fillings Market