
 Botanical Ingredients Market | 2026-2036
Botanical Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Ingredients Market Intelligence
Certified organic and fair-trade sourcing is redrawing the competitive landscape for botanical ingredient suppliers. Givaudan leverages its extensive R&D capabilities to develop novel active ingredients for the cosmetics sector. Martin Bauer Group specializes in a broad portfolio of herbal and fruit extracts for the food and beverage industry. Synthite Industries Ltd. sustains a strong position through its large-scale production of spice oleoresins.
Botanical ingredients are substances derived from plants, flowers, and roots, processed to concentrate specific phytochemicals like flavonoids or terpenes. These materials serve as active components, flavorants, and fragrances, delivering functional benefits in commercial products. Herbal extracts and essential oils command the highest value within product types due to complex processing requirements. The food & beverage and nutraceuticals applications represent the largest volume segments, while cosmetics demand higher-purity extracts.
Regulatory frameworks from the US FDA and the European Food Safety Authority (EFSA) dictate permissible claims and purity standards for food and nutraceutical applications. In China, the NMPA enforces strict registration for ingredients used in cosmetics, shaping market access. Supplier success depends on navigating this fragmented regulatory environment while ensuring supply chain transparency and substantiating product efficacy claims.
Market Dynamics
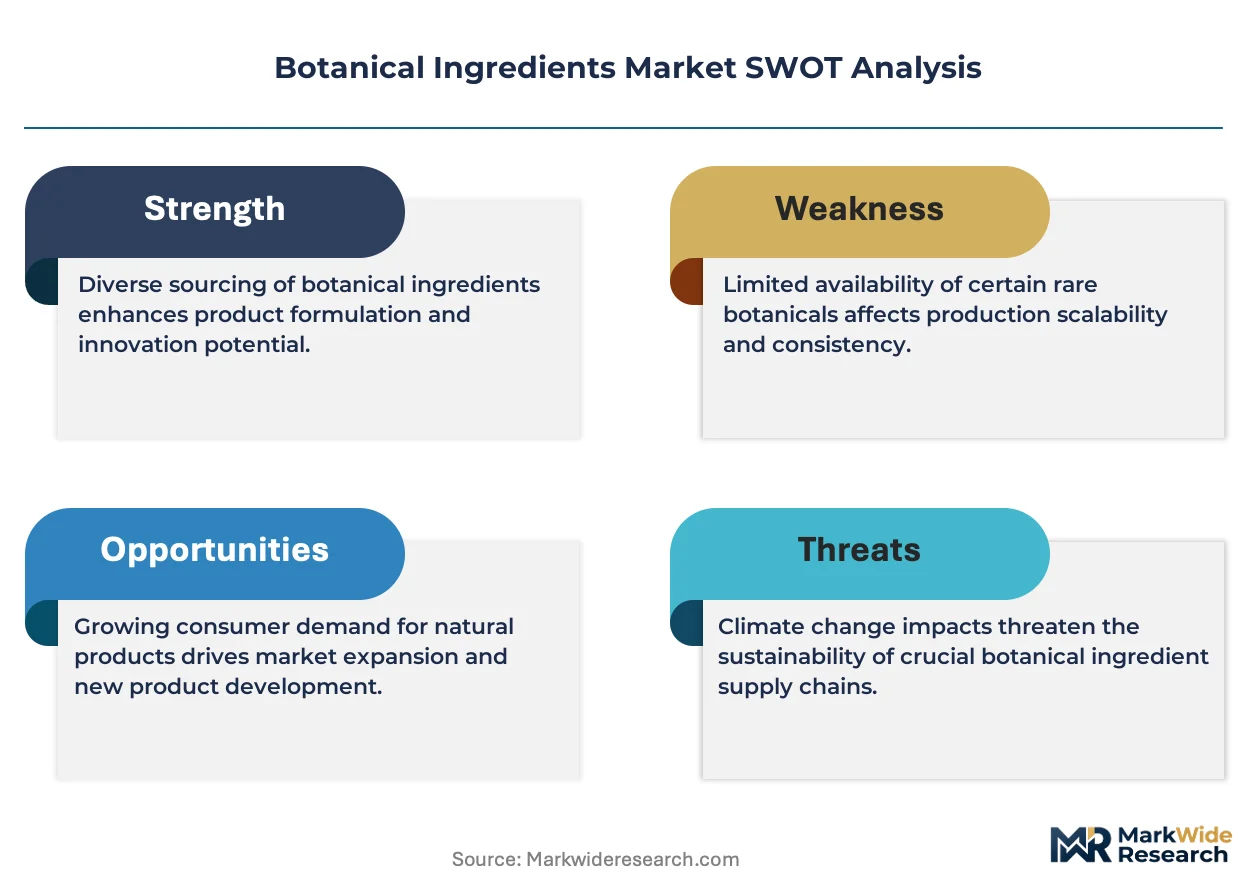
The botanical ingredients market is defined by the central tension between demand for scientifically validated, sustainably sourced materials and the need for cost-effective, scalable production. This dynamic forces suppliers to balance investments in R&D and traceability against price pressures from commoditized segments.
Growth Catalysts
- Nutraceutical Demand:Consumer interest in functional foods and dietary supplements for preventative health is a primary expansion force, particularly for ingredients with substantiated wellness benefits like adaptogens and antioxidants.
- EU Green Deal:This European policy framework is compelling suppliers to adopt more sustainable sourcing and transparent supply chain practices, creating a premium for certified organic and fair-trade ingredients.
- Traditional Medicine Modernization:Demand in China and other parts of Asia is concentrating for standardized botanical extracts used in evidence-based Traditional Chinese Medicine (TCM) formulations, blending ancient remedies with modern quality control.
Market Restraints
- Fragmented Regulations:Navigating disparate regulatory frameworks from bodies like the US FDA, European EFSA, and China's NMPA creates significant compliance costs and market access delays for suppliers.
- Supply Chain Volatility:Dependence on agricultural inputs makes the supply chain vulnerable to climate change, crop failures, and geopolitical instability in key growing regions, leading to price and availability fluctuations.
- Processing Complexity:The high capital and operational costs associated with advanced extraction and purification technologies required for high-value extracts limit their use to premium applications and larger suppliers.
Strategic Opportunities
- Plant-Based Foods:The expansion of the plant-based meat and dairy alternative sector presents an opportunity for botanical extracts to serve as natural flavorants, colorants, and preservatives, improving product appeal.
- Biotechnological Production:Utilizing plant cell culture and precision fermentation offers a path to produce rare or difficult-to-cultivate phytochemicals with high consistency, purity, and a lower environmental footprint.
- Biodiversity Exploration:Untapped ecosystems, particularly in Latin America and Africa, represent a vast genetic library for discovering novel botanical compounds with potential applications in cosmetics, pharmaceuticals, and food.
Industry Challenges
- Claim Substantiation:Suppliers face the significant operational challenge of funding and conducting the clinical studies required to substantiate health and efficacy claims to the satisfaction of regulators like EFSA.
- Standardization of Actives:Achieving consistent phytochemical profiles batch-to-batch is a persistent difficulty due to natural variations in plant material, complicating quality control for finished product manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Ingredients Market |
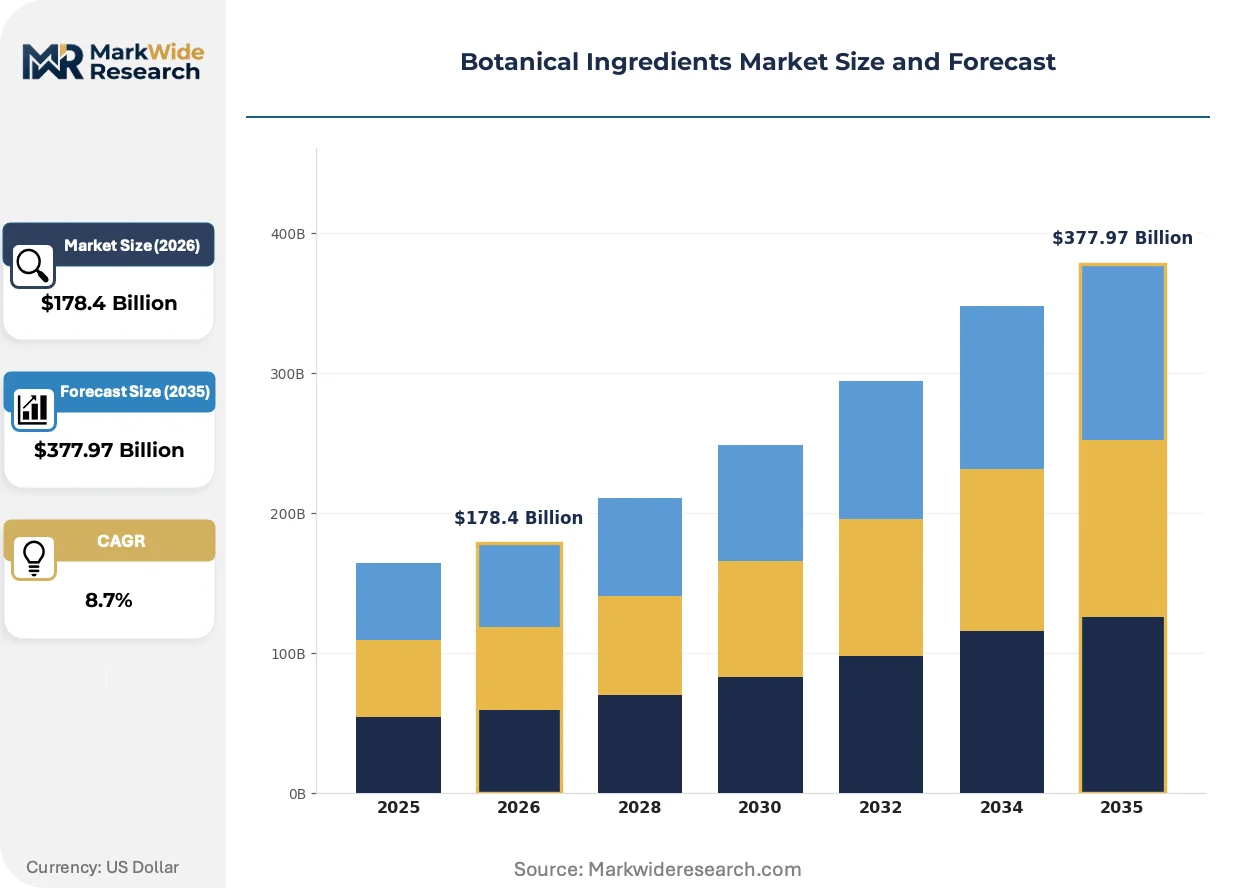
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $377.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Dried Herbs, Floral Waters Application: Cosmetics, Pharmaceuticals, Food & Beverage, Nutraceuticals Source: Plants, Flowers, Leaves, Roots Form: Liquid, Powder, Paste, Granule |
| Companies Covered | Synthite Industries Ltd., Martin Bauer Group, Givaudan, Symrise, Nexira, Koninklijke DSM N.V, Flavex Naturextrakte GmbH, Bio-Botanica, Sensient Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Ingredients Market Strategic Shifts & Innovations
Technological advancements in extraction and analytical chemistry are enabling a fundamental shift in the market. Botanical ingredients are evolving from bulk commodities into high-performance, standardized components, supported by scientific validation of their functional benefits in specific applications.
Advanced extraction techniques like supercritical CO2 and microwave-assisted extraction allow for the precise isolation of target phytochemicals without harsh solvents. The nutraceutical and dermo-cosmetic industries are rapidly adopting these methods to develop high-potency active ingredients. This technology is supplanting traditional solvent-based processes, enabling the development of cleaner, more effective, and scientifically-backed products.
Regulatory frameworks are increasingly focused on supply chain accountability. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates extensive disclosure on environmental and social governance, directly impacting how botanical ingredients are sourced. This affects all suppliers targeting the European market, forcing investment in robust traceability and verification systems to prove compliance with sustainability claims for food and cosmetic ingredients.
A notable behavioral shift is the elevation of supply chain transparency to a primary purchasing criterion for brand owners. This preference disrupts traditional commodity procurement, favoring suppliers who can provide verifiable data on provenance, ethical labor, and environmental impact through digital platforms. This trend is most pronounced within the organic food and "clean beauty" segments, especially in North America and Europe.
Botanical Ingredients Market Segmentation
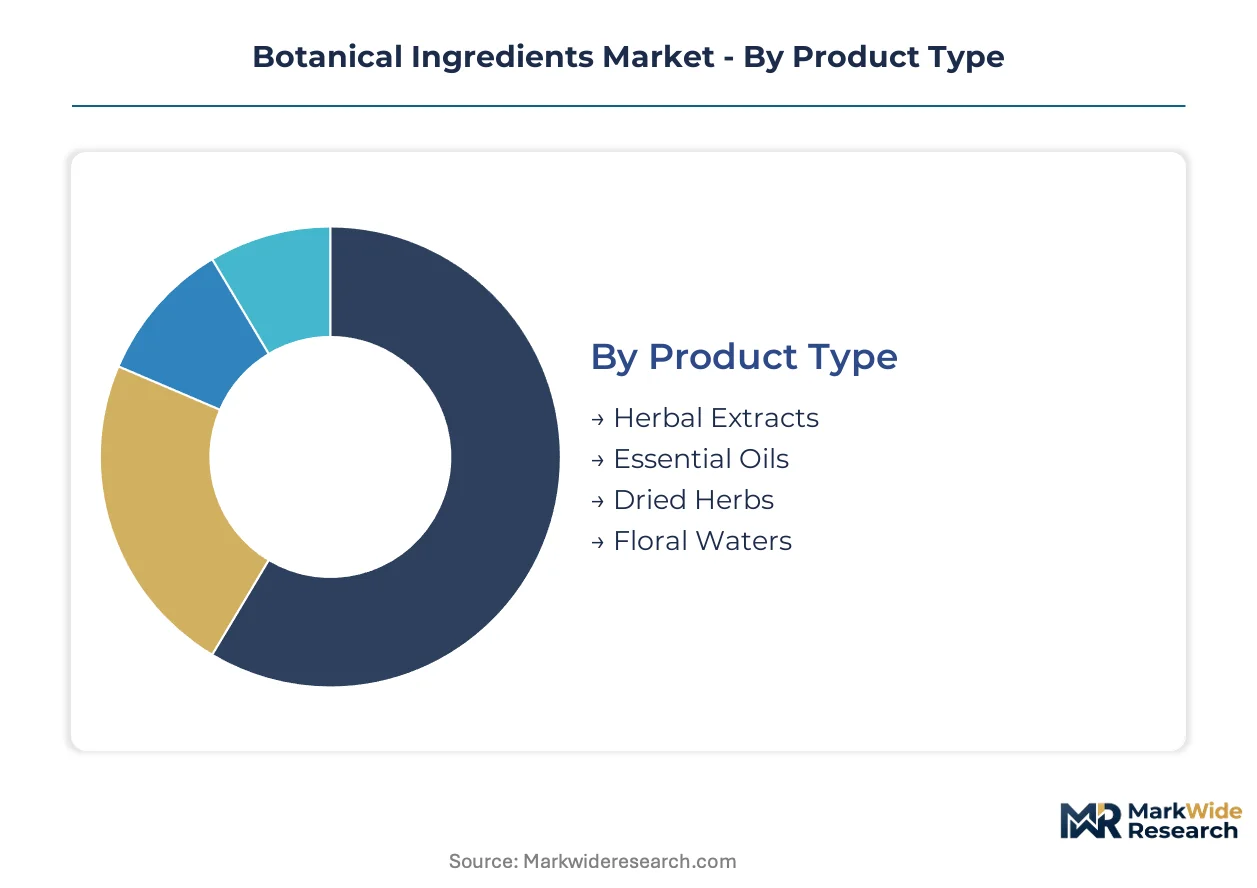
Understanding the distinct segments within the botanical ingredients market is critical for suppliers to tailor product offerings and navigate diverse regulatory landscapes. Segmentation reveals where value concentrates, influencing investment in extraction technologies and sustainable sourcing initiatives. This categorization helps identify niche opportunities and broad volume plays across the industry.
Product Type:
The geographic spread of botanical ingredients varies significantly by product type, with some segments dominating international trade while others serve more localized markets.
- Herbal Extracts:These are concentrated forms of active phytochemicals derived from plants, often standardized to specific compounds. Demand from the nutraceuticals sector for functional foods and dietary supplements drives significant global trade.
- Essential Oils:Volatile aromatic compounds extracted from plants, flowers, and fruits, highly valued for their fragrance and therapeutic properties. The cosmetics and aromatherapy industries represent key end-use markets, particularly in Europe and North America.
- Dried Herbs:Whole or cut plant materials, minimally processed and used in traditional medicine formulations, teas, and culinary applications. This segment often involves more localized supply chains, especially for regional traditional practices.
- Floral Waters:Hydrosols produced as by-products of essential oil distillation, containing water-soluble plant compounds. Skincare and personal care products utilize floral waters for their gentle properties.
Herbal Extracts commands the established base. The steepest expansion runs through Essential Oils.
Application:
The volume requirements for botanical ingredients differ substantially across application segments, with some demanding large-scale production and others prioritizing high purity and specific functionalities.
- Food & Beverage:Botanical ingredients serve as natural flavorants, colorants, and preservatives in a vast array of products. The plant-based foods sector and functional beverages contribute significantly to volume demand.
- Nutraceuticals:This application utilizes botanical compounds for their health-promoting properties in dietary supplements and functional foods. Consumer interest in preventative health, particularly adaptogens and antioxidants, drives this segment.
- Cosmetics:High-purity botanical extracts are incorporated into skincare, haircare, and personal care formulations. The "clean beauty" trend in North America and Europe emphasizes natural and traceable ingredients.
- Pharmaceuticals:Standardized botanical extracts and isolated compounds are used in drug development and traditional medicine formulations. Stringent regulatory approval processes govern this highly specialized segment.
The Food & Beverage sector drives broad consumer engagement. Nutraceuticals demonstrate the most dynamic growth.
Source:
The complexity and environmental impact of sourcing botanical ingredients vary considerably depending on the plant part utilized, influencing cultivation practices and supply chain stability.
- Roots:These plant parts often store concentrated secondary metabolites and are harvested for adaptogens and traditional medicine ingredients. Sourcing roots can involve more labor-intensive cultivation and harvesting processes.
- Flowers:Prized for their fragrant compounds and aesthetic appeal, flowers are critical for essential oils and floral waters. Seasonal availability and delicate handling characterize their supply chain.
- Leaves:Widely used for extracts, teas, and herbal remedies, leaves are a common and often renewable source of botanical ingredients. This segment offers relatively high-volume sourcing opportunities.
- Plants:This category encompasses whole plants or aerial parts, utilized when a broader spectrum of compounds or bulk material is required. Cultivation and harvesting can be mechanized for large-scale production.
Leaves and whole Plants offer high-volume supply. Roots and Flowers often require specialized cultivation or harvesting.
Form:
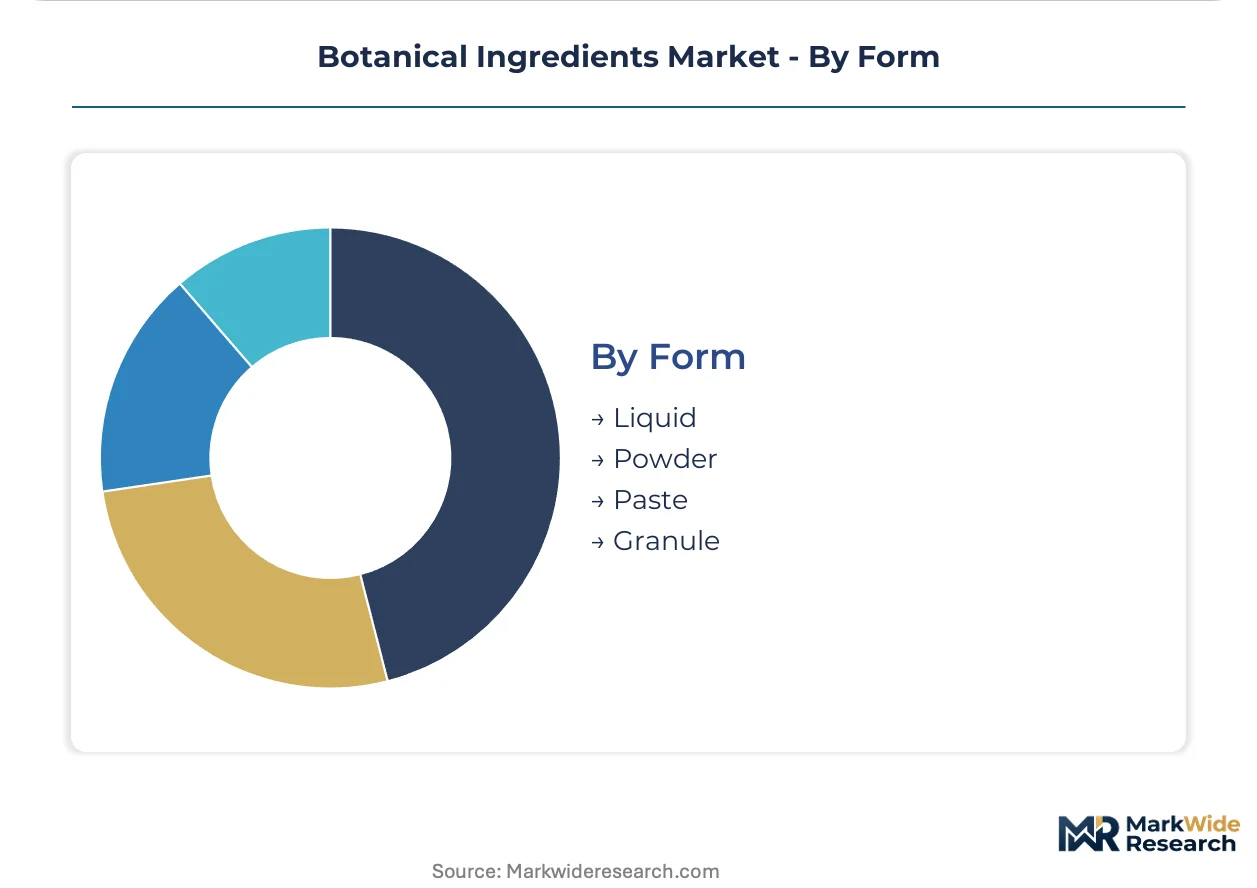
Customer preference and ease of incorporation into final products dictate the prevalent forms of botanical ingredients, ranging from highly concentrated liquids to stable powders.
- Liquid:These forms include tinctures, essential oils, and aqueous extracts, offering ease of blending and immediate bioavailability in many applications. Liquid forms are common in beverages and cosmetic formulations.
- Powder:Dried and milled botanical extracts provide stability, extended shelf life, and ease of handling for manufacturers. Dietary supplements and dry food mixes frequently utilize powdered ingredients.
- Paste:Concentrated semi-solid forms of botanical ingredients, often used in specific food applications or as bases for cosmetic products. Pastes offer a balance between liquid and solid properties.
- Granule:Agglomerated powders that provide improved flowability, reduced dust, and consistent dosage for manufacturing processes. Granules are beneficial in tablet and capsule formulations.
Powdered forms provide broad utility for manufacturers. Liquid formats facilitate direct incorporation into many end products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botanical ingredients trade exhibits a complex export-import balance across key global markets. Europe and North America drive demand for high-value extracts, while Asia, particularly China and India, serve as major sourcing hubs and consumption centers for traditional formulations. Latin America contributes significantly to raw material supply for various industries.
China
Demand for standardized botanical extracts in Traditional Chinese Medicine (TCM) drives significant market activity. The NMPA enforces strict registration for cosmetic ingredients, influencing market access for suppliers. Production clusters in provinces like Sichuan and Yunnan focus on cultivating and processing diverse medicinal plants for domestic and international markets.
Germany
European Green Deal policies compel suppliers to adopt sustainable sourcing and transparent supply chain practices. EFSA regulations dictate permissible claims and purity standards for food and nutraceutical applications. Industrial centers in Bavaria and North Rhine-Westphalia specialize in advanced extraction technologies for high-purity ingredients.
United States
Consumer interest in functional foods and dietary supplements for preventative health boosts demand for adaptogens and antioxidants. The US FDA regulates dietary supplements and food additives, requiring substantiation of efficacy claims. California and the Pacific Northwest host numerous nutraceutical and "clean beauty" manufacturers.
India
Traditional medicine systems like Ayurveda create consistent demand for a wide array of herbal ingredients. The FSSAI regulates food safety and standards for botanical products, ensuring quality control. States like Kerala and Karnataka are key regions for cultivating and processing Ayurvedic herbs and spices.
Brazil
The country's vast biodiversity offers significant potential for discovering novel botanical compounds. ANVISA regulations govern the approval and commercialization of botanical-derived products in food and cosmetics. The Amazon region is a critical sourcing area for unique plant species used in various industries.
Botanical Ingredients Market Key Industry Players
Concentration sits with specialized ingredient manufacturers offering high-purity extracts. The market structure exhibits a tiered landscape, ranging from large-scale commodity producers to niche suppliers of advanced phytochemicals. Strategic archetypes include R&D-intensive innovators, broad-portfolio extract specialists, and volume-focused oleoresin producers. Companies prioritize portfolio diversification and strategic partnerships to navigate evolving consumer preferences and regulatory demands.
Specialists in high-value botanical compounds include Givaudan, known for its extensive R&D capabilities in novel active ingredients. Martin Bauer Group exemplifies suppliers with broad portfolios of herbal and fruit extracts for diverse industrial applications. Synthite Industries Ltd. anchors the segment focused on large-scale production, particularly for spice oleoresins, demonstrating efficiency in high-volume segments.
| Leading Market Players |
|---|
| Synthite Industries Ltd. |
| Martin Bauer Group |
| Givaudan |
| Symrise |
| Nexira |
| Koninklijke DSM N.V |
| Flavex Naturextrakte GmbH |
| Bio-Botanica |
| Sensient Technologies |
| Others |
Cost & Logistics Intelligence
Biotechnological production replacing traditional agricultural sourcing simultaneously reshapes supply geography and pricing economics in the botanical ingredients market. This shift influences where key active compounds are produced and how their value is captured across the supply chain.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for botanical ingredients. Price differentiation stems from certification levels, such as organic and fair-trade, and the purity standards achieved through advanced extraction. Pricing softness reflects oversupply in commoditized botanical segments due to increased cultivation. The Food & Beverage sector demonstrates high price sensitivity, while Nutraceuticals and Cosmetics prioritize high-purity extracts over cost.
Supply Chain Analysis
Climate change leading to crop failures underwrites significant volatility in botanical ingredient supply chains. Geographic supply concentrates in China for Traditional Chinese Medicine ingredients, India for Ayurvedic herbs, and Brazil for novel Amazonian compounds. The market relies on specific plant species and specialized extraction solvents as key raw material dependencies. Single-source vulnerability for rare botanicals presents a structural risk. Multi-tier distribution through specialized ingredient distributors serves manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase, driven by sustained consumer health consciousness and demand for natural product formulations.
For Market Incumbents: Fortify global sourcing networks by securing long-term contracts with diverse agricultural partners. Invest in biotechnological production capabilities for high-value compounds to mitigate supply chain volatility. This counters the threat of climate-induced crop failures and strengthens control over critical raw materials. Prioritize R&D in novel active ingredients with scientifically substantiated efficacy claims to maintain premium positioning.
For New Entrants and Emerging Players: Certification fast-tracking for organic and fair-trade ingredients offers a strong entry point into premium segments. Target the "clean beauty" segment in North America, which values transparency and natural formulations. Develop niche adaptogen formulations or plant-based food additives addressing specific consumer wellness trends. Utilize digital platforms to provide verifiable data on provenance and sustainability, fostering direct-to-manufacturer relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward R&D-intensive specialists in advanced extraction technologies or biotechnological production. These firms offer proprietary processes for consistent, high-purity botanical compounds. The market exhibits long-term viability, supported by enduring consumer preferences for natural health products over the next decade. Watch for regulatory harmonization of botanical claims across major markets as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Precision Fermentation | This enables consistent, high-purity phytochemical production with reduced environmental impact. |
| Expand Certified Sourcing Programs | This meets increasing brand owner demand for traceable and ethically produced ingredients. |
| Develop Novel Active Ingredients | This unlocks new applications and commands premium pricing in cosmetics and nutraceuticals. |
| Implement Blockchain Traceability | This enhances supply chain transparency, satisfying regulatory and consumer demands for provenance. |
| Form Strategic Partnerships with Growers | This secures long-term raw material supply and promotes sustainable cultivation practices. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase of this study. Interviews included nutraceutical formulators, cosmetics R&D directors, food scientists, and botanical extract producers. These insights were combined with extensive secondary validation from sources like EFSA scientific opinions, NMPA registration databases, customs trade data, and academic journals. This approach enabled robust bottom-up and top-down triangulation.
The forecasting boundary spans a multi-year analysis window, employing a granular segmentation framework. Market sizing and projections consider product type, application, source, form, and regional consumption patterns. Compound annual growth rates were derived from historical trends, market drivers, and expert consensus. Key forecast inputs included consumer health spending and regulatory approval rates for novel botanical ingredients.
Decision-makers should treat outputs as directional under base assumptions of stable geopolitical climates and consistent regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions, but unforeseen climate events or rapid shifts in consumer preferences present specific risk factors. Practitioners should keep alternative scenarios live as named conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Non-GMO Soya Market
Ingredients
Self-Rising Flour Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Wheat Germ Oil Market
Ingredients
Bovine Gelatin Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Europe Amino Acid Market
Ingredients
Rice Bran Oil Market
Ingredients
Zero-Calorie Oil Market
Ingredients
Global Pulse Flours Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Insect-Based Ingredients Market