
 MCT Oil Market | 2026-2036
MCT Oil Market Size, Share, and Industry Trends Forecast 2026-2036
MCT Oil Market Outlook
Southeast Asian palm kernel and coconut oil refining capacity is hardening as the dominant feedstock foundation for MCT production. IOI Oleo GmbH leverages its integrated oleochemical complex in Malaysia to sustain cost-advantaged C8-C10 fractionation. BASF SE anchors European pharmaceutical-grade supply through its Ludwigshafen lipid technology platform. Croda International Plc differentiates via high-purity esterification capabilities serving cosmetic and nutraceutical formulators.
Medium-chain triglyceride oil consists of fatty acids with 6-12 carbon atoms, typically derived from fractional distillation of coconut or palm kernel oil to concentrate caprylic acid (C8) and capric acid (C10) fractions; these shorter chains undergo rapid hepatic oxidation, delivering ketone bodies for immediate cellular energy metabolism. Liquid MCTs dominate volume throughput due to established beverage and oil-based supplement formulations, while powdered MCTs represent the fastest-expanding format as spray-dried encapsulation improves shelf stability and enables dry-mix protein applications. The dietary supplements application commands premium pricing relative to food and beverage incorporation, where commoditization pressures intensify.
FDA dietary supplement cGMP enforcement and EFSA novel food authorization pathways shape product standardization and cross-border commercialization timelines for MCT oil suppliers. REACH compliance in Europe and FSMA traceability mandates in the United States further elevate documentation and purity testing burdens across the value chain. Stakeholders must monitor evolving ketogenic health claim substantiation requirements and bioavailability study demands to defend positioning in clinical and performance nutrition segments.
Market Dynamics
Fractionation capacity concentration in Southeast Asian oleochemical complexes is compressing feedstock arbitrage windows and forcing Western formulators into long-term offtake commitments to secure C8-C10 supply.
Growth Catalysts
- Ketogenic diet adherence:Sports nutrition brands in the United States now standardize MCT oil in pre-workout and recovery formulations, creating sustained pull through functional beverage channels.
- FDA cGMP tightening:Enhanced dietary supplement labeling requirements are filtering out substandard suppliers and consolidating shelf space for verified brands.
- Spray-dried encapsulation:Powdered MCT formats are penetrating dry-mix protein applications previously inaccessible to liquid oils, unlocking new formulation flexibility for sports nutrition manufacturers.
Market Restraints
- Palm kernel oil price volatility:Feedstock costs fluctuate with Malaysian and Indonesian plantation yields and biodiesel policy shifts, compressing margin predictability for fractionators.
- REACH documentation burdens:European chemical registration requirements impose substantial purity testing and traceability costs that disproportionately burden smaller importers.
- Long-chain triglyceride substitution:Conventional vegetable oils retain cost advantages in mass-market food applications where ketogenic positioning carries limited premium capture.
Strategic Opportunities
- Clinical nutrition penetration:Medical food applications for epilepsy and metabolic disorder management remain underdeveloped relative to sports nutrition saturation in North America.
- FSMA traceability alignment:Suppliers investing early in lot-level documentation systems can capture preferential positioning with US-based contract manufacturers facing FDA enforcement escalation.
- Cosmetic-grade esterification:High-purity MCT derivatives for skincare formulations command pricing multiples over nutritional grades, attracting oleochemical investment toward personal care capabilities.
Industry Challenges
- Ketogenic health claim substantiation:EFSA novel food authorization pathways demand bioavailability studies that extend commercialization timelines and require specialized clinical research partnerships.
- Cross-border certification complexity:Divergent purity standards between FDA dietary supplement rules and EFSA novel food frameworks force dual-track compliance investments for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MCT Oil Market |
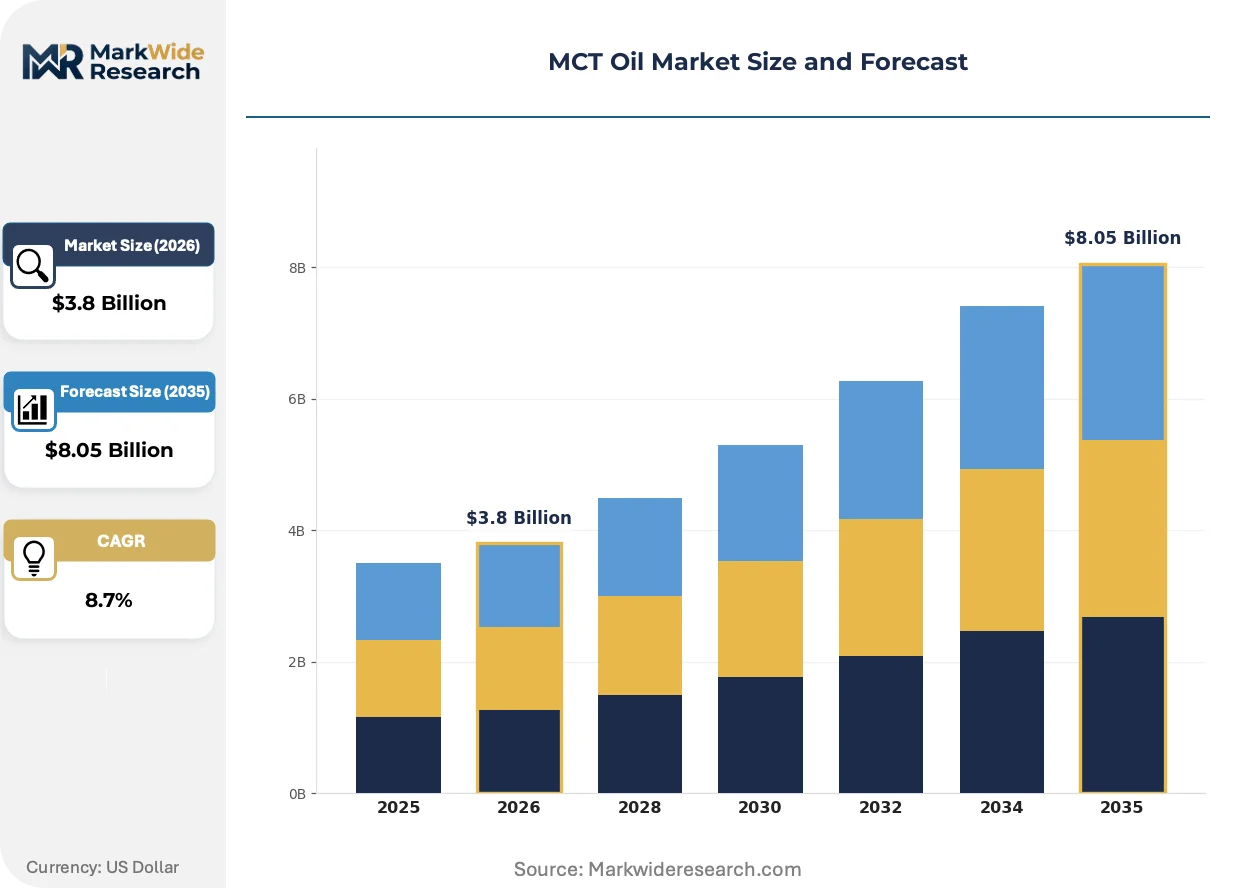
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid MCTs, Powdered MCTs, Organic MCTs, Synthetic MCTs Application: Food & Beverage, Dietary Supplements, Personal Care, Pharmaceuticals Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Specialty Retailers End User: Fitness Enthusiasts, Athletes, Health-Conscious Consumers, Medical Patients |
| Companies Covered | KLK Emmerich GmbH, BASF SE, IOI Oleo GmbH, Barlean's, Croda International Plc, Wilmar International Ltd, The Nisshin OilliO Group, ConnOils LLC, Musim Mas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MCT Oil Market Strategic Shifts
Formulation science and regulatory verification protocols are converging to reshape how MCT oil moves from commodity feedstock to differentiated ingredient positioning across nutrition and personal care verticals.
Microencapsulation technology is expanding into beverage and confectionery applications previously incompatible with oil-based ingredients. Sports nutrition brands now specify powder MCTs for ready-to-mix protein skus, while functional beverage developers leverage nanoemulsion systems for transparent, shelf-stable incorporation. This format diversification is compressing the historical liquid-dominant supply structure and rewarding suppliers with dual-format production capabilities.
EFSA novel food authorization pathways are tightening substantiation requirements for metabolic health claims across European markets. The regulation now demands clinical bioavailability data for new MCT entrants, extending approval timelines and elevating capital requirements for market access. European pharmaceutical-grade suppliers with existing study portfolios are capturing preferential positioning against commodity importers lacking documentation depth.
Direct-to-consumer subscription models are displacing traditional supplement retail distribution in United States ketogenic nutrition segments. Brands now bypass brick-and-mortar shelf competition through personalized dosing protocols and recurring delivery structures. This channel shift concentrates buyer data with vertically integrated formulators and compresses wholesale margin pools for pure-play ingredient suppliers.
MCT Oil Market Segmentation
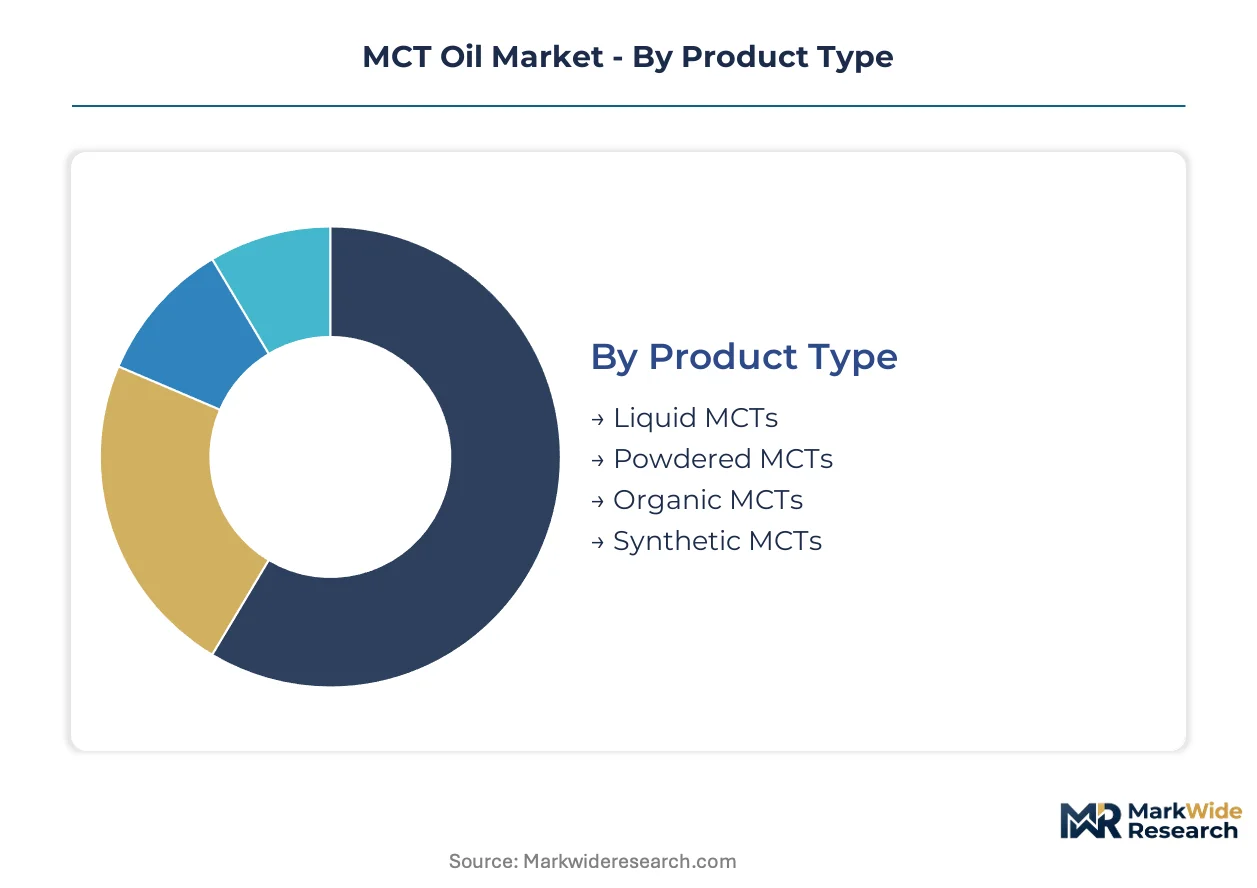
MCT oil segmentation reveals divergent margin structures across formulation formats and end-use verticals. Suppliers configure production assets differently for commodity food-grade throughput versus pharmaceutical-grade purity requirements. Channel selection and user targeting determine whether brands capture premium pricing or compete on volume scale.
Product Type:
Integration depth varies sharply: liquid formats dominate standalone consumption, while powders embed into multi-ingredient systems.
- Liquid MCTs:Caprylic (C8) and capric (C10) acid concentrates in oil form enable rapid hepatic oxidation for immediate ketone generation. United States functional beverage manufacturers specify liquid MCTs for ready-to-drink ketogenic coffee and pre-workout shots, though oxidation sensitivity limits shelf stability.
- Powdered MCTs:Spray-dried encapsulation on maltodextrin or gum arabic carriers transforms oil into free-flowing powders compatible with dry-blend protein systems. Sports nutrition brands in North American direct-to-consumer channels specify powdered formats for subscription-based meal replacements, unlocking formulation flexibility previously inaccessible to oil-based inputs.
- Organic MCTs:Certified organic fractionation from coconut oil rather than palm kernel commands 15-30% price premiums in European natural products retail.
- Synthetic MCTs:Laboratory-synthesized triglycerides from glycerol and purified fatty acids serve pharmaceutical applications requiring batch-to-batch consistency unavailable from natural sources.
Liquid MCTs lead volumes today; powdered MCTs are gaining share fastest.
Application:
Cost tier stratification separates premium-priced clinical positioning from commodity food incorporation.
- Dietary Supplements:Capsule and softgel formulations targeting ketogenic dieters and biohackers sustain the highest per-kilogram pricing in the value chain. FDA cGMP verification requirements filter out substandard suppliers, consolidating shelf space for documentation-heavy brands in United States specialty retail.
- Food & Beverage:Mass-market ketogenic positioning in coffee creamers, salad dressings, and energy bars faces intense commoditization pressure from long-chain triglyceride alternatives. Malaysian and Indonesian fractionators compete primarily on C8-C10 concentration specifications and bulk pricing.
- Personal Care:Cosmetic-grade esterified MCTs serve as fragrance carriers and emollients in premium skincare, with Croda International and BASF SE capturing value through high-purity lipid technology platforms.
- Pharmaceuticals:Medical food applications for epilepsy management and metabolic disorder support remain underdeveloped relative to sports nutrition saturation, offering expansion vectors for suppliers with clinical bioavailability data.
Dietary supplements command premium pricing; pharmaceuticals present the steepest expansion trajectory for credentialed entrants.
Distribution Channel:
Customer type concentration shifts channel economics toward recurring revenue models versus transactional retail.
- Online Stores:Direct-to-consumer subscription platforms displace traditional supplement retail in United States ketogenic segments, concentrating buyer data with vertically integrated formulators.
- Supermarkets:Mass-market food and beverage incorporation depends on brokered relationships with CPG conglomerates, compressing margins for pure-play ingredient suppliers.
- Health Food Stores:Independent natural products retailers in California and Colorado emphasize organic certification and transparent sourcing narratives.
- Specialty Retailers:GNC, Vitamin Shoppe, and Equinox-tier fitness clubs curate premium MCT assortments with third-party testing verification.
Online stores are expanding most quickly; supermarkets anchor volume throughput.
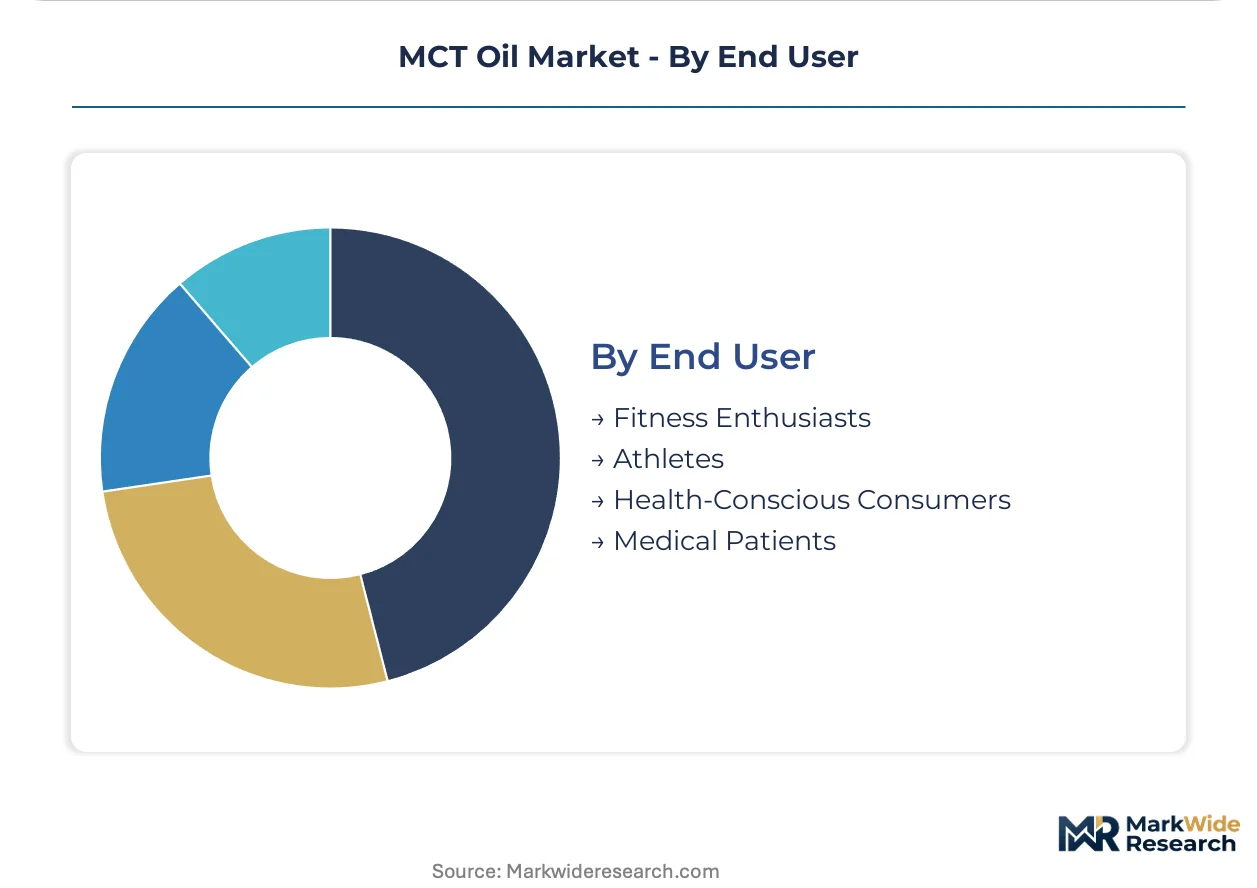
End User:
Maturity gradients separate established fitness segments from emerging clinical populations.
- Fitness Enthusiasts:Recreational ketogenic dieters and gym-goers drive baseline demand through protein powder and pre-workout supplementation, with price sensitivity higher than elite athlete cohorts.
- Athletes:Endurance and strength competitors specify pharmaceutical-grade MCTs for rapid energy substrate conversion during competition windows, tolerating premium pricing for lot-level purity documentation.
- Health-Conscious Consumers:Wellness-oriented purchasers without specific athletic goals respond to cognitive performance and metabolic health positioning in functional foods.
- Medical Patients:Epilepsy, Alzheimer's, and metabolic disorder patients under clinical supervision represent the smallest but highest-loyty user base, with prescription and medical food channels requiring regulatory navigation.
Fitness enthusiasts dominate current volumes; medical patients offer the deepest margin pool for compliant suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian fractionators command feedstock proximity advantages that German pharmaceutical-grade suppliers cannot replicate without long-term offtake commitments. United States functional beverage brands absorb premium C8-C10 concentrates despite logistics costs. This geographic tension shapes competitive positioning across three continents.
United States
Ketogenic diet adherence and sports nutrition innovation drive concentrated demand in California and Colorado functional beverage clusters. FDA cGMP enforcement and FSMA traceability mandates filter substandard imports, consolidating shelf space for documentation-heavy suppliers. Direct-to-consumer subscription platforms in Austin and Los Angeles now displace traditional supplement retail, concentrating buyer data with vertically integrated formulators.
Malaysia
Integrated oleochemical complexes in Klang Valley and Johor anchor global C8-C10 fractionation capacity through palm kernel oil refining. Biodiesel policy shifts and plantation yield fluctuations compress margin predictability for exporters serving Western markets. IOI Oleo GmbH leverages captive Malaysian feedstock access to sustain cost-advantaged supply positions against European competitors.
Germany
REACH documentation burdens and EFSA novel food authorization pathways elevate purity testing costs for MCT importers serving cosmetic and pharmaceutical formulators. BASF SE anchors European pharmaceutical-grade supply through its Ludwigshafen lipid technology platform. The country's central chemical regulator enforces batch-to-batch consistency standards that commodity fractionators struggle to satisfy.
China
Sports nutrition manufacturing clusters in Guangdong and Zhejiang provinces integrate MCT powders into ready-to-mix protein systems for domestic fitness markets. The national market regulator enforces evolving food safety standards for imported lipid ingredients. Wilmar International Ltd maintains processing presence in coastal manufacturing zones to serve both export and domestic functional food channels.
Japan
Cosmetic-grade esterification demand from Tokyo-Osaka skincare formulators sustains premium pricing for high-purity MCT derivatives. The Nisshin OilliO Group leverages domestic lipid technology capabilities to serve fragrance carrier and emollient applications. METI industrial standards for cosmetic raw materials impose documentation requirements that favor established suppliers with existing study portfolios.
MCT Oil Market Competitive Environment
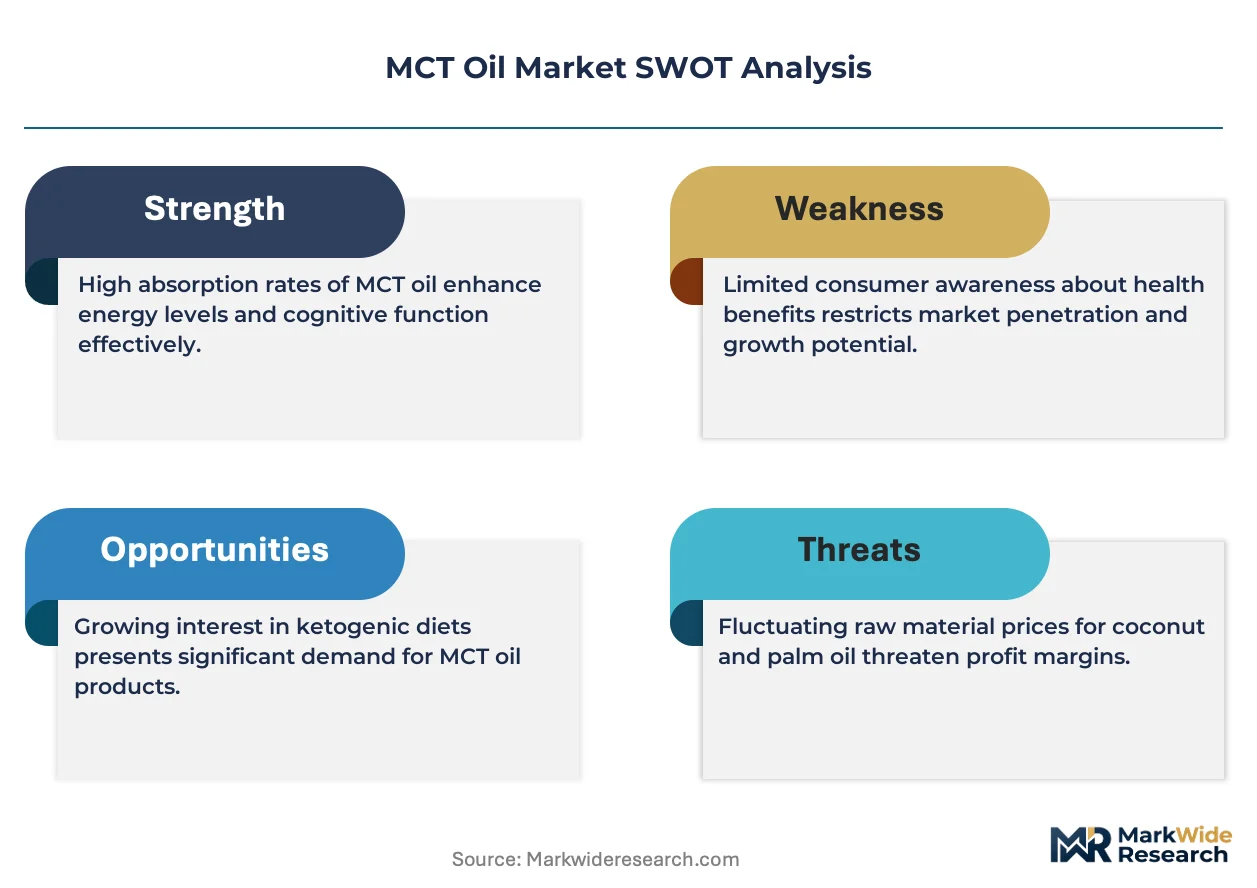
Southeast Asian producers anchor the feedstock-integrated tier; European specialists hold the pharmaceutical-grade premium position. The vendor base stratifies across three functional layers: fractionators with captive plantation access, formulators with spray-dried encapsulation capabilities, and brands with direct-to-consumer channel control. Strategic moves concentrate on long-term offtake contracting and dual-format production investments.
Within the integrated oleochemical tier, IOI Oleo GmbH and Wilmar International Ltd exemplify feedstock-proximate positioning through Malaysian processing assets. BASF SE occupies the European pharmaceutical-grade vector, leveraging Ludwigshafen-based lipid technology platforms to serve cosmetic and medical food formulators with documentation depth. Croda International Plc represents the high-purity esterification specialist archetype, differentiating through capabilities that command pricing multiples in personal care applications.
| Leading Market Players |
|---|
| KLK Emmerich GmbH |
| BASF SE |
| IOI Oleo GmbH |
| Barlean's |
| Croda International Plc |
| Wilmar International Ltd |
| The Nisshin OilliO Group |
| ConnOils LLC |
| Musim Mas |
| Others |
Value Chain & Pricing Dynamics
Malaysian palm kernel oil futures and Indonesian coconut oil benchmarks cascade through C8-C10 fractionation economics into three distinct pricing tiers. Feedstock volatility at plantation origin compresses margin buffers for Western formulators locked into long-term pharmaceutical-grade offtake contracts.
Pricing Analysis
Direct-to-consumer subscription discounts bypass traditional distributor markups and retailer slotting allowances that burden brick-and-mortar channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and cosmetic-grade specifications reflects purity documentation depth and lot-level traceability investments. Pricing pressure stems from Southeast Asian fractionators competing on C8-C10 concentration specifications for commodity food applications. Fitness enthusiasts through mass-market protein powder brands exhibit highest price sensitivity; epilepsy and metabolic disorder patient populations through medical food channels tolerate substantial premiums for batch-to-batch consistency.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale sports nutrition demand while specialty distributors serve cosmetic formulators requiring smaller lot flexibility. Malaysian, Indonesian, and German production assets anchor global C8-C10 supply through palm kernel fractionation and pharmaceutical-grade esterification capabilities. Raw material flows draw from Southeast Asian plantation complexes, Ludwigshafen lipid technology platforms, and Guangdong processing zones. Single-source vulnerability concentrates in Malaysian oleochemical corridors exposed to biodiesel policy arbitrage and El Niño yield impacts. Distribution runs through vertically integrated brand houses controlling direct-to-consumer subscription data and long-term offtake agreements with fractionators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as ketogenic diet adherence shifts demand toward FDA cGMP-verified suppliers with documentation depth. Premium specifications now filter shelf space consolidation in United States sports nutrition channels.
For Market Incumbents: Anticipate spray-dried encapsulation capability shortages and EFSA novel food authorization backlogs that reward existing study portfolios. Defensive consolidation around dual-format production assets in Malaysia and captive plantation access insulates against commodity fractionator price wars. Certification investments in FSMA traceability systems capture preferential positioning with contract manufacturers facing FDA enforcement escalation. For New Entrants and Emerging Players: Capture clinical nutrition white space in epilepsy management and metabolic disorder medical food applications where sports nutrition saturation has not penetrated. European pharmaceutical-grade supply gaps present the most penetrable entry vector against entrenched oleochemical incumbents. Go-to-market leverage rests on partnerships with academic medical centers generating bioavailability data for EFSA novel food pathways. For Investors and Strategic Acquirers: Consolidation pressure builds where spray-dried encapsulation capabilities and direct-to-consumer channel data concentrate in vertically integrated formulators. Long-term viability over the coming decade favors suppliers with dual-format production assets and existing clinical study portfolios over pure-play commodity fractionators. Signal to monitor: FDA cGMP enforcement actions dislodging substandard imports and accelerating shelf space consolidation toward documentation-heavy brands.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Format Production Investment | Spray-dried encapsulation capabilities unlock dry-mix protein applications previously inaccessible to liquid oil suppliers. |
| FSMA Traceability Alignment | Lot-level documentation systems capture preferential positioning with US contract manufacturers facing FDA enforcement escalation. |
| Clinical Bioavailability Partnerships | Academic medical center collaborations generate EFSA novel food authorization data for metabolic health claim substantiation. |
| Direct-to-Consumer Channel Control | Subscription platforms concentrate buyer data and displace wholesale margin pools for pure-play ingredient suppliers. |
| Cosmetic-Grade Esterification Expansion | High-purity MCT derivatives for skincare formulations command pricing multiples over nutritional grades. |
Study Parameters
Direct dialogue with fractionation plant managers, sports nutrition brand formulators, FDA regulatory consultants, and cosmetic R&D directors grounded qualitative assessment in operational reality. Primary interview insights combined with secondary validation from FDA cGMP enforcement records, EFSA novel food authorization databases, Malaysian Palm Oil Board production statistics, and SEC filings from listed oleochemical companies. Bottom-up volume builds across product type, application, and distribution channel segments triangulated against top-down macroeconomic indicators.
Bottom-up modeling of liquid, powdered, organic, and synthetic MCT formats across dietary supplement, food and beverage, personal care, and pharmaceutical applications anchored volume projections. Analytical frameworks incorporated ketogenic diet adherence rates, sports nutrition channel growth, and clinical nutrition penetration curves across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion patterns. Forecast inputs included Malaysian palm kernel oil price volatility indices and EFSA authorization timeline distributions.
Feedstock price shocks, regulatory authorization delays, and ketogenic diet trend deceleration are the dominant revision risks for forecast accuracy. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hexane-Free Protein Market
Ingredients
GCC Egg Powder Market
Ingredients
Carob Protein Market
Ingredients
Kilned Malt Market
Ingredients
United States Soy Protein Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Cold Pressed Oil Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Rose Hips Extract Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
Bean Ingredients Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Arachidonic Acid Market
Ingredients
Smoked Yeast Market