
 Africa Soy Protein Ingredients Market | 2026-2036
Africa Soy Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Soy Protein Ingredients Market Outlook
South Africa's food fortification regulations is broadening compliance costs for imported protein ingredients. ADM leverages its crushing and refining infrastructure to supply food-grade isolates across Southern Africa. Cargill Incorporated sustains ocean freight and port handling networks that reduce landed costs for West African buyers. Crown Protein Soya anchors local crushing operations in Zimbabwe and Zambia, competing on proximity to regional feed millers.
Africa soy protein ingredients comprise defatted and processed soybean fractions containing protein concentrations from fifty to ninety percent, manufactured through aqueous extraction, acid precipitation, or extrusion texturization for human food and animal feed applications. Soy isolate commands premium positioning in dairy alternatives and sports nutrition formulations where protein purity determines functional performance. Textured soy protein extends fastest in meat alternatives as Nigerian and Kenyan food processors reformulate traditional products. Soy flour occupies mature volume positions in bakery applications across North African markets where cost thresholds dominate procurement decisions.
South Africa's Department of Health enforces mandatory fortification standards that shape isolate specifications for infant nutrition and school feeding programs. Nigeria's National Agency for Food and Drug Administration and Control regulates protein content claims on alternative dairy labels, influencing concentrate grading requirements. Ethiopia's Ministry of Agriculture sets feed ingredient quality benchmarks that channel soy protein into poultry and aquaculture rations. Stakeholders must monitor how divergent national standards fragment product certification requirements across African trade corridors.
Market Dynamics
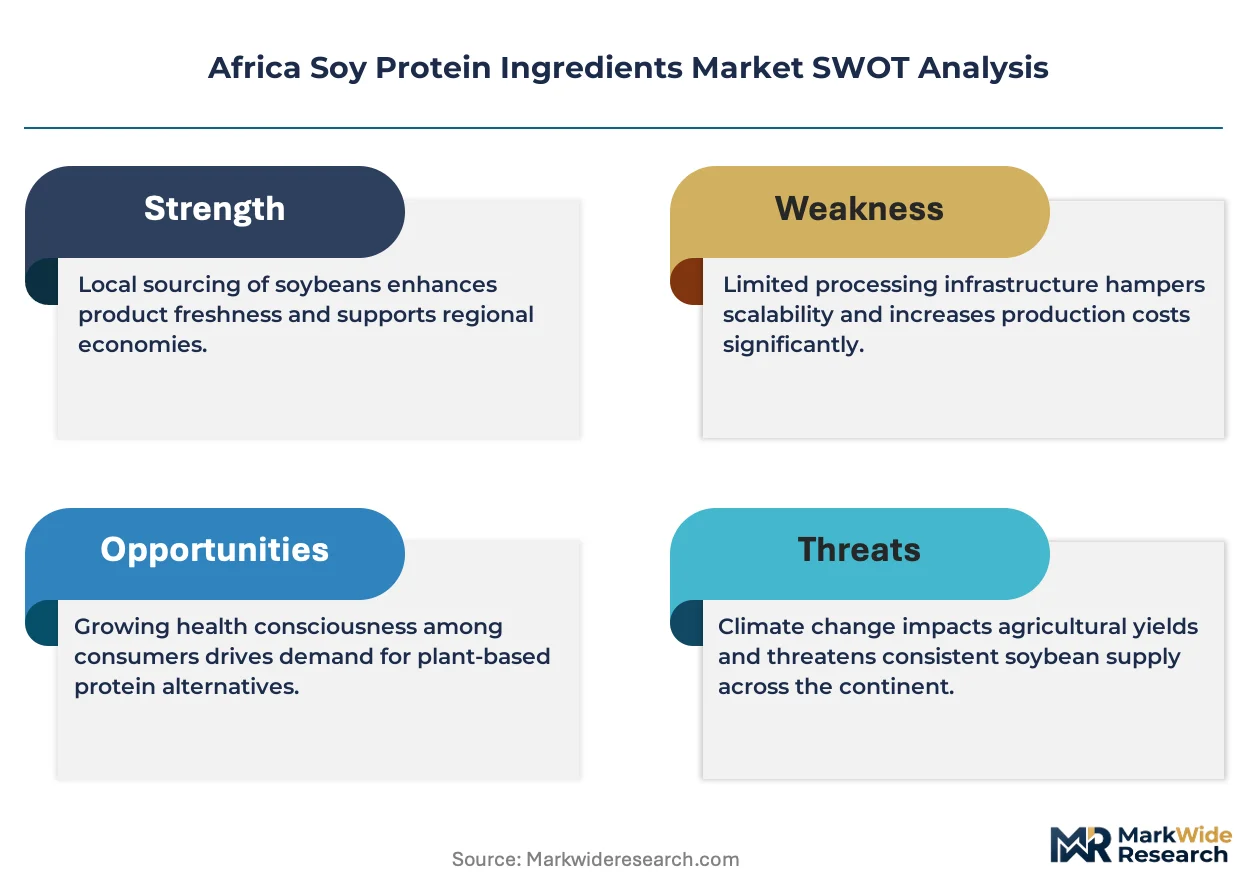
Food-grade protein fortification mandates across African school feeding and maternal nutrition programs are concentrating procurement specifications toward isolate-grade purity thresholds, compressing the addressable supply base for lower-concentration alternatives.
Growth Catalysts
- Ethiopia's livestock feed modernization:Federal agricultural extension programs are channeling soy protein concentrate into commercial poultry and aquaculture rations, displacing fishmeal in Addis Ababa's integrated operations.
- South Africa's fortification standards:Mandatory micronutrient regulations for maize and wheat flour are pulling soy isolates into government tender specifications for infant formula and school nutrition.
- Enzymatic hydrolysis adoption:Nigerian dairy-alternative processors are deploying improved protein extraction to achieve neutral flavor profiles in fermented beverages.
Market Restraints
- Imported input cost volatility:Crushing margins compress when global soybean futures spike, exposing East African toll processors to working capital strain.
- Technical limitation in flavor masking:Beany off-notes in lower-grade concentrates restrict application expansion in premium beverage formulations.
- Substitution threat from pea protein:European suppliers are positioning yellow pea isolates as allergen-free alternatives in South African sports nutrition channels.
Strategic Opportunities
- Kenya's underpenetrated meat alternatives:Nairobi's foodservice distributors lack textured protein supply partnerships for plant-based burger reformulation.
- Regulatory tailwind from Nigeria's NAFDAC:New protein content claim guidelines for dairy-alternative labels are creating compliance-driven demand for certified concentrate grades.
- Direct-to-manufacturer channel innovation:Regional crushing cooperatives in Zambia are bypassing traditional commodity traders to supply feed millers on contract.
Industry Challenges
- Food safety certification timelines:HACCP and FSSC 22000 accreditation for isolate production requires 18-24 month validation cycles that delay market entry.
- Integration complexity with legacy milling infrastructure:North African bakery operations running dated extrusion equipment face protein incorporation uniformity issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Soy Protein Ingredients Market |
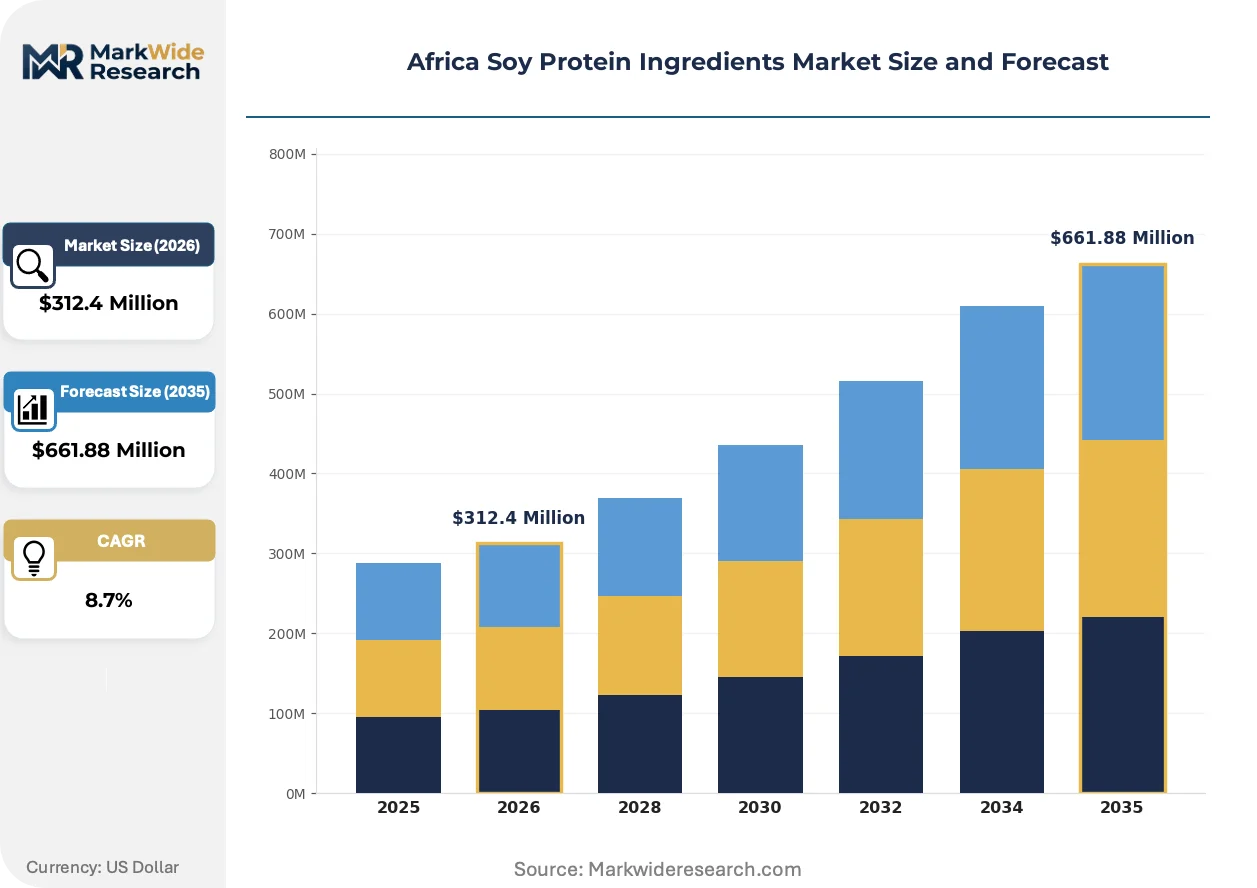
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Isolate, Soy Concentrate, Textured Soy Protein, Soy Flour Application: Beverages, Dairy Alternatives, Meat Alternatives, Bakery Products End User: Food Industry, Animal Feed, Nutraceuticals, Dietary Supplements Distribution Channel: Direct Sales, Online Retail, Hypermarkets, Specialty Stores |
| Companies Covered | ADM (Archer Daniels Midland Company), Cargill Incorporated, Wilmar International Ltd, DuPont, Kerry Group, BRF Global, Fuji Oil Holdings, CHS Inc., Crown Protein Soya, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Soy Protein Ingredients Market Strategic Shifts
Extrusion and enzymatic processing advances are reconfiguring the functional property range of African-manufactured soy ingredients, enabling displacement of imported isolates in mid-tier applications previously dependent on ocean freight supply.
Extrusion texturization technology is integrating high-moisture processing capabilities into West African crushing facilities. Nigerian meat-alternative manufacturers are adopting these systems to produce fibrous structures mimicking poultry muscle. The technology is integrating domestic supply chains into burger and sausage applications that previously required European isolate imports.
South Africa's Department of Health is tightening interpretive guidance on protein quality metrics for school feeding tenders. Industrial bidders must now demonstrate PDCAAS scores above defined thresholds to qualify for national supply contracts. Isolate suppliers with in-house analytical capabilities are capturing tender allocations previously split across concentrate grades.
Procurement patterns among East African feed compounders are compressing supplier qualification cycles from annual to quarterly reviews. Kenyan poultry integrators are unbundling volume commitments across multiple crushing sources to mitigate single-origin risk. This behavior is most visible in the Rift Valley, where feed millers maintain parallel contracts with Zambian and local toll processors.
Africa Soy Protein Ingredients Market Segmentation
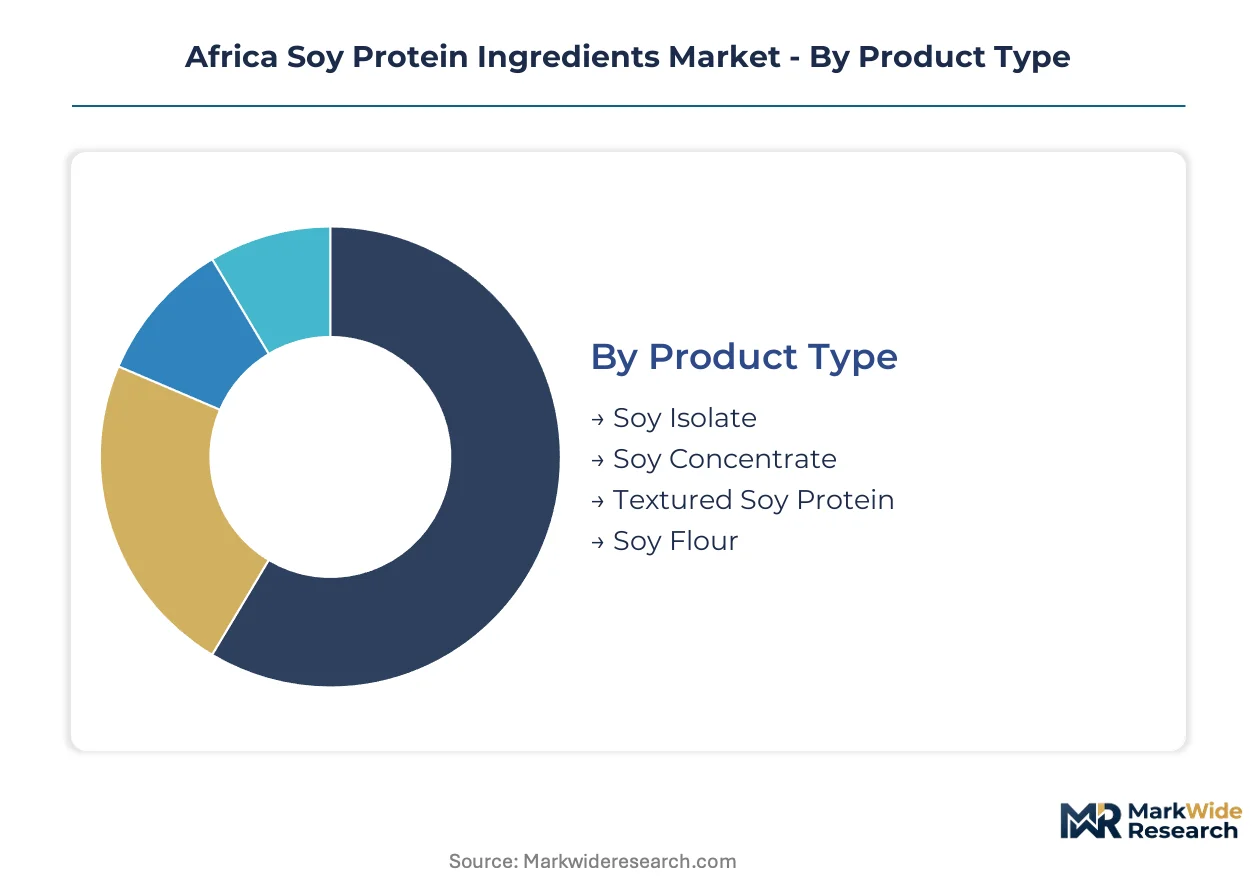
Segmentation in the Africa soy protein ingredients market reveals how protein concentration tiers, application requirements, and end-user specifications create distinct procurement corridors. Manufacturers must align product grades with regulatory thresholds and processing capabilities across human food and animal nutrition channels.
Product Type:
Customization intensity spans from commodity-grade flour to precision-engineered isolates, with protein purity thresholds determining end-use eligibility and pricing power.
- Soy Isolate:Refined to 90% protein content through aqueous extraction and acid precipitation. South Africa's Department of Health mandates isolate-grade purity for infant formula tenders, concentrating procurement among accredited suppliers with in-house analytical capabilities.
- Soy Concentrate:Defatted flakes processed to 65-70% protein retain functional carbohydrates for texturization. Nigerian dairy-alternative processors deploy enzymatic hydrolysis on concentrate bases to achieve neutral flavor profiles in fermented beverages.
- Textured Soy Protein:Extruded concentrates or isolates restructured into fibrous or chunk forms. East African meat-alternative startups source these for plant-based burger reformulation.
- Soy Flour:Ground whole or defatted beans at 50% protein, occupying mature volume positions in North African bakery applications where cost thresholds dominate procurement decisions.
Most installed capacity flows through Soy Flour. Expansion is steepest in Textured Soy Protein.
Application:
Application segmentation tracks how protein functionality requirements split between hydration-critical beverages and structure-dependent meat systems.
- Beverages:Protein fortification in ready-to-drink formats demands dispersibility and suspension stability. Kenyan processors source low-viscosity concentrates for maize-based complementary foods.
- Dairy Alternatives:Fermented and UHT plant milks require emulsion stability and clean flavor. Nigeria's NAFDAC protein content claim guidelines are reshaping concentrate grading specifications for labeled alternatives.
- Meat Alternatives:Textured proteins provide chew structure and water-binding in restructured products. Nigerian manufacturers adopt high-moisture extrusion to displace European isolate imports.
- Bakery Products:Soy flour extends shelf life and improves crumb structure in commercial bread. Egyptian industrial bakeries integrate defatted flour at 3-5% inclusion rates for cost optimization.
Volume concentrates in Bakery Products. Value expansion is climbing fastest in Dairy Alternatives.
End User:
End-user segmentation distinguishes between compliance-heavy human nutrition and specification-driven animal feed procurement.
- Food Industry:Processed food manufacturers drive bulk concentrate demand for reformulation. South African school feeding tenders now require PDCAAS documentation, filtering supplier pools.
- Animal Feed:Poultry and aquaculture compounders source dehulled soybean meal as primary protein. Ethiopia's livestock feed modernization programs channel soy protein into commercial rations, displacing fishmeal in Addis Ababa operations.
- Nutraceuticals:Isolates with documented isoflavone profiles target functional food positioning. Limited local extraction capacity constrains supply.
- Dietary Supplements:Sports nutrition brands in South Africa specify allergen-free isolate grades. European pea protein suppliers are gaining shelf space as alternatives.
Procurement scale favors Food Industry. Regulatory tailwinds are strongest in Animal Feed.
Distribution Channel:
Channel segmentation reflects the tension between bulk contract efficiency and fragmented retail access for specialty grades.
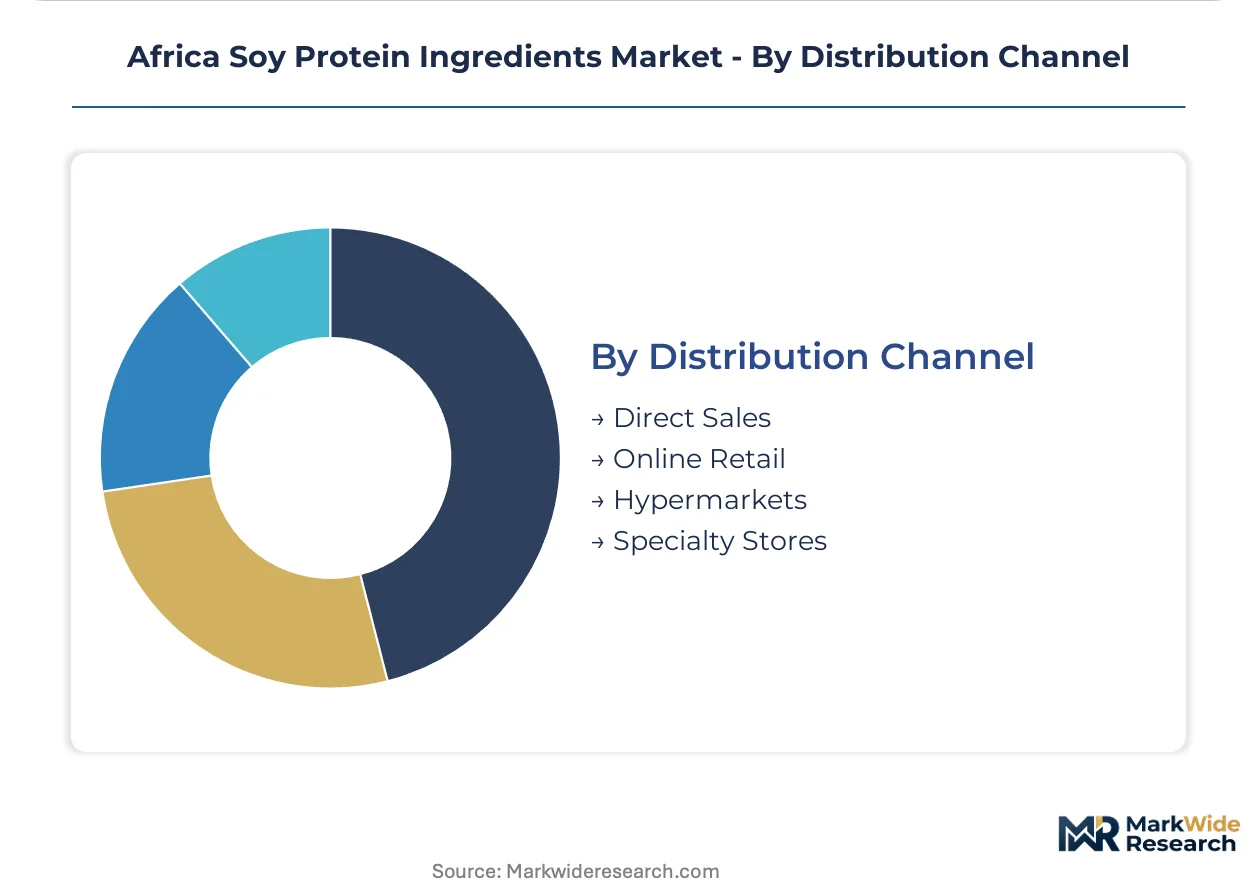
- Direct Sales:Crushing cooperatives in Zambia bypass commodity traders to supply feed millers on contract. Volume commitments compress supplier qualification cycles to quarterly reviews.
- Online Retail:E-commerce platforms aggregate specialty isolate sales for small-scale food manufacturers. Logistics costs limit penetration outside South African urban corridors.
- Hypermarkets:Mass retail stocks consumer-facing soy flour and textured protein for home cooking. North African chains dominate regional sourcing.
- Specialty Stores:Health food retailers stock premium isolate and organic-certified concentrates. Nairobi's distributors lack textured protein partnerships for foodservice expansion.
Transaction volume runs through Direct Sales. Channel innovation is advancing most quickly in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized protein chemists and food formulation technologists cluster in South Africa's Gauteng province and Nigeria's Lagos industrial corridor, anchoring the continent's technical capacity for isolate refinement and dairy-alternative processing.
South Africa
School feeding procurement and infant formula manufacturing concentrate demand for high-purity isolates. The Department of Health enforces PDCAAS documentation thresholds that filter supplier pools for national tenders. Durban's port infrastructure and Gauteng's crushing facilities form the continent's most integrated soy protein supply chain.
Nigeria
Dairy-alternative beverage startups and traditional tofu processors drive concentrate consumption in Lagos and Kano. NAFDAC protein content claim guidelines reshape labeling requirements for plant-based milk products. High-moisture extrusion adoption in Ogun State industrial zones displaces European isolate imports for meat-alternative applications.
Ethiopia
Commercial poultry integrators and aquaculture operations in Addis Ababa source soy protein concentrate for feed rations. Federal agricultural extension programs channel ingredients into modernized livestock operations displacing fishmeal. The Rift Valley feed milling corridor maintains parallel supply contracts with Zambian and domestic toll processors.
Kenya
Foodservice distributors and bakery manufacturers in Nairobi generate unmet demand for textured protein in plant-based burger reformulation. Poultry feed compounders in the Rift Valley compress supplier qualification cycles to quarterly reviews. Local crushing cooperatives bypass commodity traders to supply feed millers on direct contract.
Egypt
Industrial bakeries in Cairo and Alexandria integrate defatted soy flour at 3-5% inclusion rates for cost optimization in commercial bread production. The country's wheat import dependency creates procurement urgency for domestic protein fortification alternatives. Alexandria's port handling infrastructure supports North African distribution of lower-grade concentrates.
Africa Soy Protein Ingredients Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement corridors. Crushing margin volatility and certification timelines fragment the addressable supplier base. Three archetypes dominate: multinational agribusinesses with ocean freight networks, regional cooperatives with proximity to feed millers, and toll processors serving government nutrition tenders. Competitive intensity centers on backward integration into seed crushing and strategic partnerships with food manufacturers.
Among multinational agribusinesses, ADM and Cargill Incorporated occupy positions anchored by crushing infrastructure and port logistics capabilities. Crown Protein Soya exemplifies the regional cooperative archetype with proximity-based supply relationships. These three entities represent distinct competitive vectors: global scale, freight optimization, and local mill integration.
| Leading Market Players |
|---|
| ADM (Archer Daniels Midland Company) |
| Cargill Incorporated |
| Wilmar International Ltd |
| DuPont |
| Kerry Group |
| BRF Global |
| Fuji Oil Holdings |
| CHS Inc. |
| Crown Protein Soya |
| Others |
Value Chain & Pricing Dynamics
Protein chemists and food formulation technologists concentrated in South Africa's Gauteng province and Nigeria's Lagos corridor create labor-cost differentials that widen pricing-tier spreads between premium isolate grades and commodity flour alternatives.
Pricing Analysis
The bundled service split separates toll-processing contracts with full analytical certification from unbundled commodity flour transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein purity grade and PDCAAS documentation depth. Pricing pressure stems from crushing margin compression when global soybean futures spike, forcing East African toll processors toward shorter contract cycles. Feed millers in the Rift Valley exhibit highest price sensitivity, while infant formula manufacturers in South Africa prioritize certification grade over unit cost.
Supply Chain Analysis
Reverse-logistics flows for reconditioned crushing equipment and refurbished extrusion systems extend asset life cycles across second-tier processors in Zambia and Zimbabwe. Supply concentrates in South Africa, Nigeria, and Ethiopia, with raw material dependencies on imported soybean futures, ocean freight capacity, and port handling infrastructure. Single-source vulnerability runs through Durban's port infrastructure for Southern African isolate distribution. Distribution runs through direct contract relationships between crushing cooperatives and feed millers, bypassing traditional commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa soy protein ingredients market represents a late-cycle quality story as procurement specifications tighten toward isolate-grade purity thresholds for school feeding and infant nutrition tenders.
For Market Incumbents: Deepen backward integration into seed crushing infrastructure across Gauteng and Lagos industrial corridors to defend against margin compression from global soybean futures volatility. Prioritize HACCP and FSSC 22000 certification investments to capture tender allocations previously split across concentrate grades. Lock in multi-year supply contracts with Rift Valley poultry integrators before quarterly qualification cycles accelerate further. For New Entrants and Emerging Players: The price-point gap between premium isolate and economy flour tiers creates entry space for mid-grade concentrate positioning in Kenyan meat-alternative applications. Target Nairobi foodservice distributors lacking textured protein supply partnerships for plant-based burger reformulation. Pursue direct-to-manufacturer channel innovation bypassing commodity traders, mirroring Zambian cooperative models. For Investors and Strategic Acquirers: Multinational agribusinesses with ocean freight networks are the most active acquirers in this space, seeking regional cooperative assets for proximity-based feed miller relationships. Long-term viability hinges on backward integration into crushing infrastructure and analytical certification capabilities. Monitor NAFDAC protein content claim guideline enforcement as the inflection signal for concentrate-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Infrastructure | Captures margin compression relief and secures isolate-grade supply for South African infant formula tenders. |
| HACCP and FSSC 22000 Certification Investment | Qualifies suppliers for Department of Health school feeding procurement with PDCAAS documentation requirements. |
| High-Moisture Extrusion Technology Adoption | Enables Nigerian meat-alternative manufacturers to displace European isolate imports with domestic fibrous structures. |
| Direct-to-Manufacturer Channel Development | Bypasses commodity traders to compress supplier qualification cycles and lock in Rift Valley feed miller volumes. |
| Enzymatic Hydrolysis Capability Expansion | Supports Nigerian dairy-alternative processors achieving neutral flavor profiles for fermented beverage compliance. |
Study Parameters
Bottom-up feed miller and food manufacturer modeling reconciled against top-down crushing capacity and port throughput tracking forms the analytical core of this study. Primary interviews with protein procurement managers at poultry integrators, dairy-alternative processing executives, regulatory affairs specialists at national food agencies, and crushing cooperative operations directors combined with secondary validation from customs trade records, national fortification standard filings, and agricultural extension program disclosures. Triangulation across these sources isolates volume and value estimates from import parity pricing and domestic production capacity.
Input-output matrices map protein concentration tiers against application requirements and end-user procurement specifications across the projection horizon. Segmentation dimensions include product type, application channel, end-user category, and distribution structure, with regional regulatory clusters modeled separately. CAGRs derive from trend extrapolation of crushing capacity additions, tender award patterns, and feed ration reformulation rates. Soybean futures volatility and ocean freight rate movements feed into pricing scenario modeling.
Caveats apply where NAFDAC enforcement intensity, Ethiopian agricultural extension budget allocations, or South African school feeding tender specifications could materially shift the outlook. Practitioners should monitor global soybean futures movements, port congestion at Durban and Lagos, and protein content claim litigation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Interesterified Fats Market
Ingredients
Insect-Based Ingredients Market
Ingredients
South America Vegetable Oil Market
Ingredients
Cooking Oils and Fats Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Agarwood Oil Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
US Choline Bitartrate Market
Ingredients
Konjac Root Fiber Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Beverage Ingredients Market
Ingredients
Mirepoix Market
Ingredients
Soybean Oil Market