
 North America Frozen Pizza Market | 2026-2036
North America Frozen Pizza Market Size, Share, and Industry Trends Forecast 2026-2036
North America Frozen Pizza Market Insights
Flash-freezing technology is narrowing the quality gap between frozen and freshly prepared pizza, compelling manufacturers to recalibrate production lines around cryogenic tunnel systems and modified-atmosphere packaging. Nestlé SA leverages its global R&D network to sustain premium positioning across thin-crust and gluten-free portfolios. General Mills Inc. anchors its North American presence through extensive supermarket distribution and frozen-dough expertise. Schwan's Company dominates foodservice channels with customized supply contracts for institutional buyers.
North America frozen pizza comprises par-baked or fully baked dough bases topped with sauces, cheeses, and proteins, then blast-frozen at temperatures below minus forty degrees Fahrenheit to arrest microbial activity and preserve texture; the primary commercial purpose is to deliver restaurant-quality meals through retail and foodservice channels with extended shelf stability. Thin-crust varieties lead household penetration due to shorter bake times and perceived health alignment, while gluten-free formulations represent the fastest-expanding product type as celiac awareness and wheat-avoidance diets proliferate. The foodservice segment commands disproportionate margin pools through volume contracts with chain restaurants and institutional cafeterias.
The FDA governs ingredient disclosures and allergen declarations, while the USDA oversees meat and poultry toppings through its FSIS arm; both agencies push reformulation toward reduced sodium and transparent labeling that elevates compliance costs for smaller packagers. Health Canada enforces bilingual labeling and compositional standards that create cross-border friction for unified North American product lines. Stakeholders must monitor evolving clean-label enforcement and regional sourcing mandates that threaten to fragment supply chain coordination across the United States and Canada.
Market Dynamics
Flash-freezing infrastructure is redrawing competitive boundaries across frozen pizza manufacturing, as cryogenic tunnel adoption separates capital-rich processors from legacy blast-chamber operators unable to fund equipment turnover.
Growth Catalysts
- Clean-label mandates:FDA updated Nutrition Facts requirements pressure reformulation toward shorter ingredient decks, creating first-mover advantage for processors with R&D scale.
- Foodservice contract consolidation:Institutional buyers in the United States and Canada are aggregating procurement through multi-year supply agreements that favor high-volume frozen dough suppliers.
- Cryogenic freezing diffusion:Tunnel systems operating below minus forty degrees Fahrenheit now preserve cellular structure in vegetable toppings previously limited to fresh distribution.
Market Restraints
- Dairy input volatility:Mozzarella and specialty cheese costs fluctuate with global milk powder markets, compressing margin predictability for mid-tier processors.
- Cross-border labeling friction:Health Canada's bilingual packaging requirements create SKU duplication costs that deter unified North American product strategies.
- Fresh pizza substitution:Quick-service chains with in-house dough production capture convenience-seeking households through delivery apps, eroding frozen retail occasions.
Strategic Opportunities
- Celiac disease protocols:Gluten-free certification programs in the United States attract wheat-avoidance consumers willing to pay premium shelf prices.
- Modified-atmosphere packaging convergence:Oxygen-scavenging films combined with nitrogen flush systems extend refrigerated distribution windows for premium thin-crust lines.
- Direct-to-foodservice channels:Bypassing distributor markups through captive delivery fleets captures margin pools in Canadian institutional cafeteria networks.
Industry Challenges
- FSIS compliance timelines:USDA meat and poultry topping inspections create batch-release delays that conflict with just-in-time retail replenishment cycles.
- Legacy equipment integration:Retrofitting existing blast-freeze lines with cryogenic injectors demands extended downtime that seasonal demand peaks cannot accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Frozen Pizza Market |
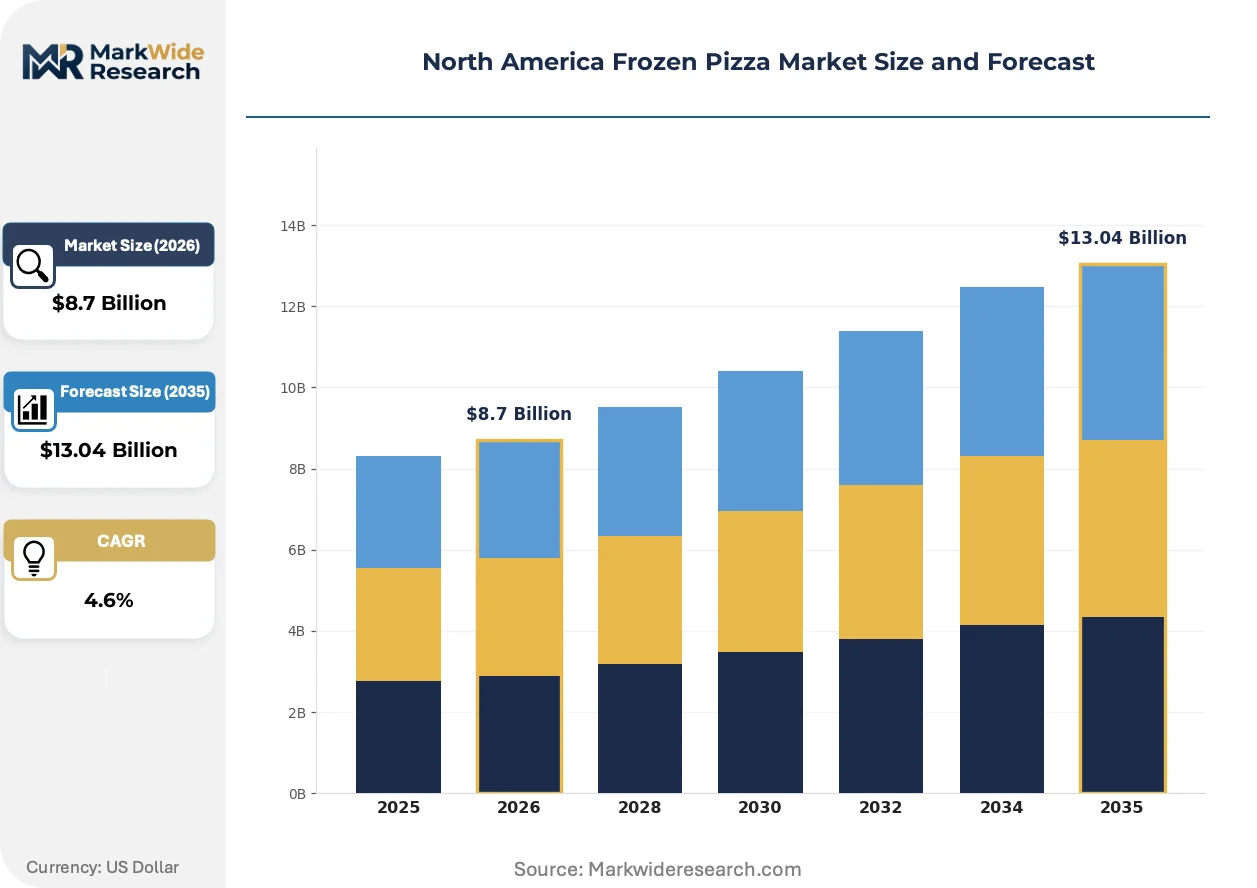
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Crust, Deep Dish, Stuffed Crust, Gluten-Free Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Foodservice Customer Type: Households, Restaurants, Cafes, Institutions Packaging Type: Box, Bag, Tray, Plastic Wrap |
| Companies Covered | Nestlé SA, General Mills Inc., Schwan's Company, Conagra Brands Inc., Dr. August Oetker KG, Amy's Kitchen Inc., Bellisio Foods Inc., McCain Foods Ltd., Palermo Villa Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Frozen Pizza Market Trends and Innovations
Processing technology and regulatory disclosure requirements are compressing product development cycles while reshaping how manufacturers segment their portfolios across price tiers.
Cryogenic tunnel freezing is hybridizing conventional blast-chamber workflows with liquid nitrogen injection stages that arrest ice crystal formation in vegetable toppings. Mid-scale processors in the United States are retrofitting existing lines at measured pace due to capital constraints. The technology is hybridizing quality expectations across retail and foodservice channels, collapsing the sensory gap between frozen and fresh-prepared pizza.
FDA sodium reduction targets are forcing reformulation of cheese blends and cured meat toppings across standard-tier product lines. Processors must resubmit nutrition panels and adjust manufacturing specifications to maintain shelf placement in major retail banners. Thin-crust varieties with reduced sodium claims are capturing disproportionate space in urban grocery corridors as retailers respond to federal pressure.
Households are consolidating weekly meal planning around frozen protein-and-carbohydrate platforms that reduce preparation labor. Subscription-based replenishment through mass-market e-commerce channels is displacing impulse freezer-aisle purchases in suburban United States markets. Quick-service delivery fatigue is rotating demand back toward retail frozen pizza in Canadian metropolitan areas where delivery fees have climbed.
North America Frozen Pizza Market Segmentation
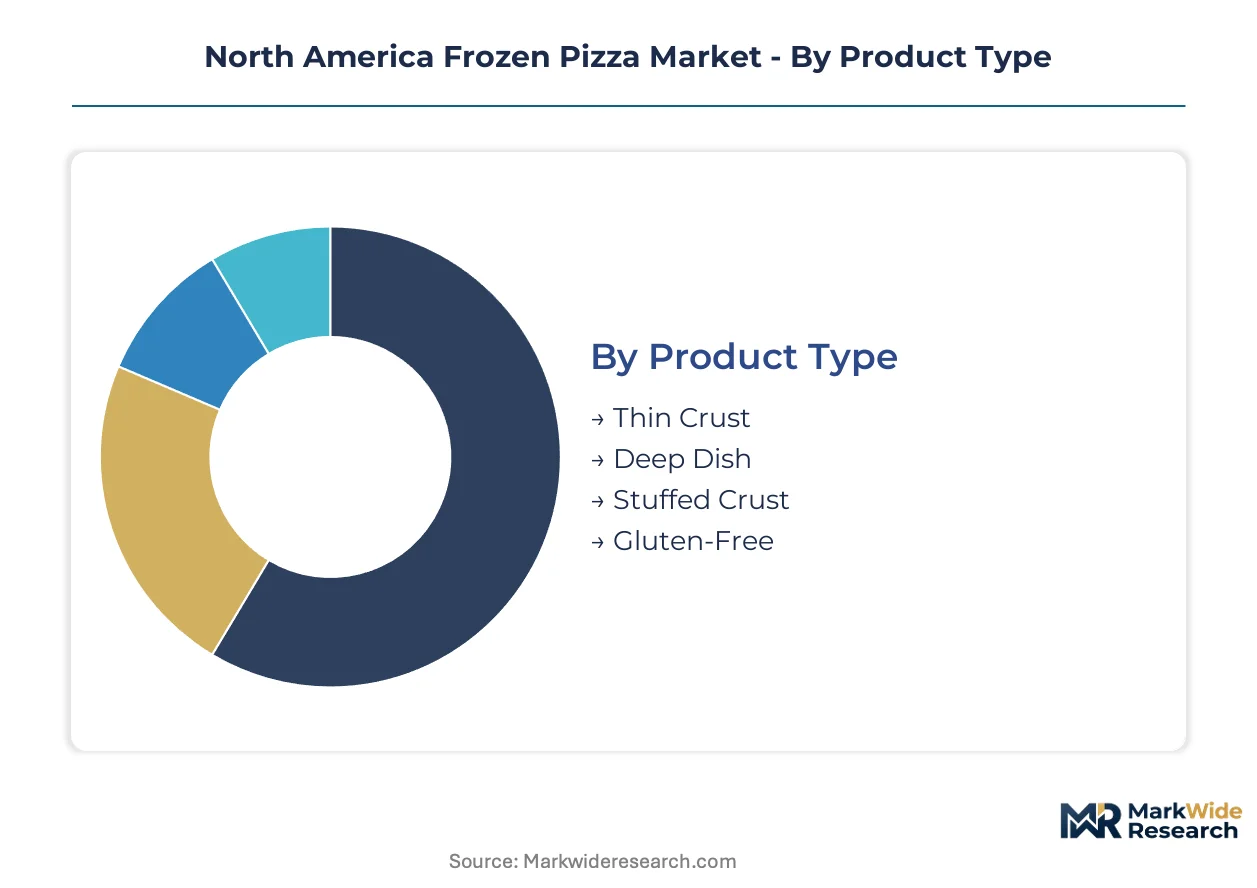
Segmentation in frozen pizza manufacturing determines equipment configuration, cold-chain logistics, and regulatory compliance pathways. Product thickness and topping density dictate freezing tunnel specifications. Distribution channel selection shapes packaging format, shelf-life engineering, and margin structure across the United States and Canada.
Product Type:
Cost tier differentiation separates premium positioning from value-engineered lines through dough complexity and topping density specifications.
- Thin Crust:Par-baked bases with minimal dough mass enable rapid cryogenic freezing and reduced energy consumption per unit. Urban households in the United States favor shorter bake times and perceived caloric moderation. This format dominates retail freezer space allocation in Canadian metropolitan grocery corridors.
- Gluten-Free:Alternative flour blends—rice, tapioca, and almond-based matrices—demand modified freezing curves to prevent starch retrogradation. Celiac disease protocols and wheat-avoidance diets concentrate demand among health-conscious households willing to absorb shelf-price premiums.
- Deep Dish:High-moisture dough and dense cheese layering require extended freeze-cycle duration.
- Stuffed Crust:Cheese-injection manufacturing lines add capital intensity and allergen segregation requirements.
Thin crust commands the established base. The steepest expansion runs through gluten-free certification programs.
Distribution Channel:
Application context—retail self-service versus prepared-food delivery—determines packaging durability, case configuration, and replenishment cadence.
- Supermarkets:Multi-SKU freezer-door placement demands vertical packaging with high-visibility graphics and structural integrity for stacking. United States mass-market banners drive volume through promotional pricing cycles and private-label substitution.
- Foodservice:Institutional contracts for chain restaurants and cafeteria networks require bulk case formats and customized topping specifications. Canadian quick-service chains source frozen dough through multi-year supply agreements with volume-tier pricing.
- Convenience Stores:Single-serve impulse formats with abbreviated shelf space.
- Online Retail:Direct-to-home delivery necessitates insulated packaging and dry-ice compatibility.
Supermarkets anchor volume throughput. Foodservice channels capture margin expansion through contract consolidation.
Customer Type:
Volume scale and purchase frequency stratify procurement behavior from weekly household replenishment to institutional batch ordering.
- Households:Weekly meal-planning consolidation around frozen protein-carbohydrate platforms reduces preparation labor. Subscription-based e-commerce replenishment is displacing impulse freezer-aisle purchases in suburban United States markets.
- Restaurants:Quick-service chains with limited kitchen footprints rely on par-baked crusts and pre-portioned toppings to standardize output. Delivery-app fatigue in Canadian metropolitan areas is rotating demand back toward frozen retail alternatives.
- Cafes:Limited-service formats with constrained oven capacity.
- Institutions:School and hospital cafeteria networks aggregate procurement through centralized purchasing cooperatives.
Households represent the volume foundation. Restaurant channel volatility creates the widest demand swings.
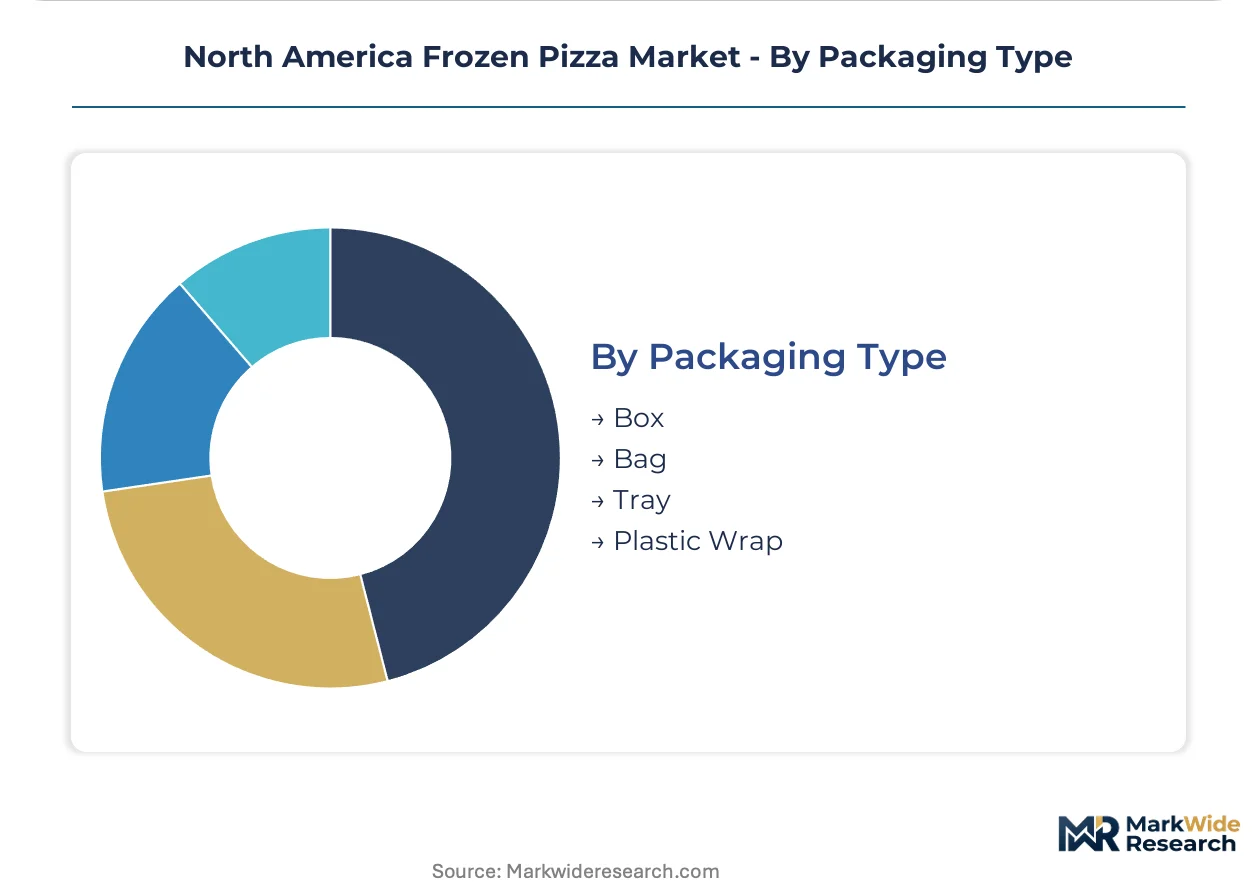
Packaging Type:
Supply concentration in paperboard and flexible film manufacturing shapes format availability and sustainability compliance costs.
- Box:Corrugated paperboard with moisture-resistant coatings dominates premium-tier presentation and stacking logistics. United States retailers mandate recyclable content thresholds that elevate material specifications.
- Bag:Flexible film structures with oxygen-scavenging layers enable modified-atmosphere preservation for thin-crust lines. Canadian bilingual labeling requirements complicate unified North American SKU strategies.
- Tray:Rigid plastic or pressed-pulp formats for stuffed-crust and deep-dish structural support.
- Plastic Wrap:Minimal overwrap for foodservice bulk cases with secondary containment.
Box formats retain retail dominance. Bag structures are gaining share fastest through e-commerce shipment optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports frozen pizza formulations and dough bases into United States retail and foodservice channels, while Mexico supplies corn-based specialty crusts and vegetable toppings to North American processors seeking clean-label ingredient diversification.
United States
Urban grocery corridors in Chicago and New York Metro drive thin-crust and gluten-free penetration among convenience-seeking households. The FDA enforces updated Nutrition Facts labeling requirements that pressure reformulation toward reduced sodium and shorter ingredient decks. California's Central Valley hosts vegetable topping processing clusters where cryogenic tunnel adoption preserves cellular structure in previously fresh-limited produce.
Canada
Metropolitan Toronto and Vancouver anchor household demand for premium thin-crust lines with bilingual packaging compliance. Health Canada mandates French-English labeling standards that create SKU duplication costs deterring unified North American product strategies. Quebec's dairy processing belt supplies specialty cheese blends to frozen pizza manufacturers navigating cross-border formulation adjustments.
Mexico
Quick-service chain expansion in Mexico City and Monterrey generates demand for par-baked crusts and pre-portioned topping systems. The country's federal consumer protection agency enforces nutritional disclosure standards aligned with North American trade integration. Baja California's produce corridor supplies flash-frozen vegetable toppings through maquiladora processing facilities serving United States distribution networks.
Northeast Corridor
Boston-to-Washington urban density concentrates foodservice contract procurement for institutional cafeteria networks and chain restaurant supply. State-level sodium reduction mandates in New York and Massachusetts exceed federal baselines, forcing regional formulation variants. Philadelphia's frozen dough manufacturing cluster specializes in customized supply agreements for mid-Atlantic quick-service operators.
Pacific Northwest
Seattle and Portland households exhibit elevated willingness-to-pay for certified gluten-free and organic-positioned frozen pizza lines. Washington State enforces stricter clean-label enforcement than federal minimums, elevating compliance costs for imported formulations. The region's cold-chain logistics hub in Tacoma distributes modified-atmosphere packaged products to Alaska and Hawaii markets.
North America Frozen Pizza Market Competitive Landscape
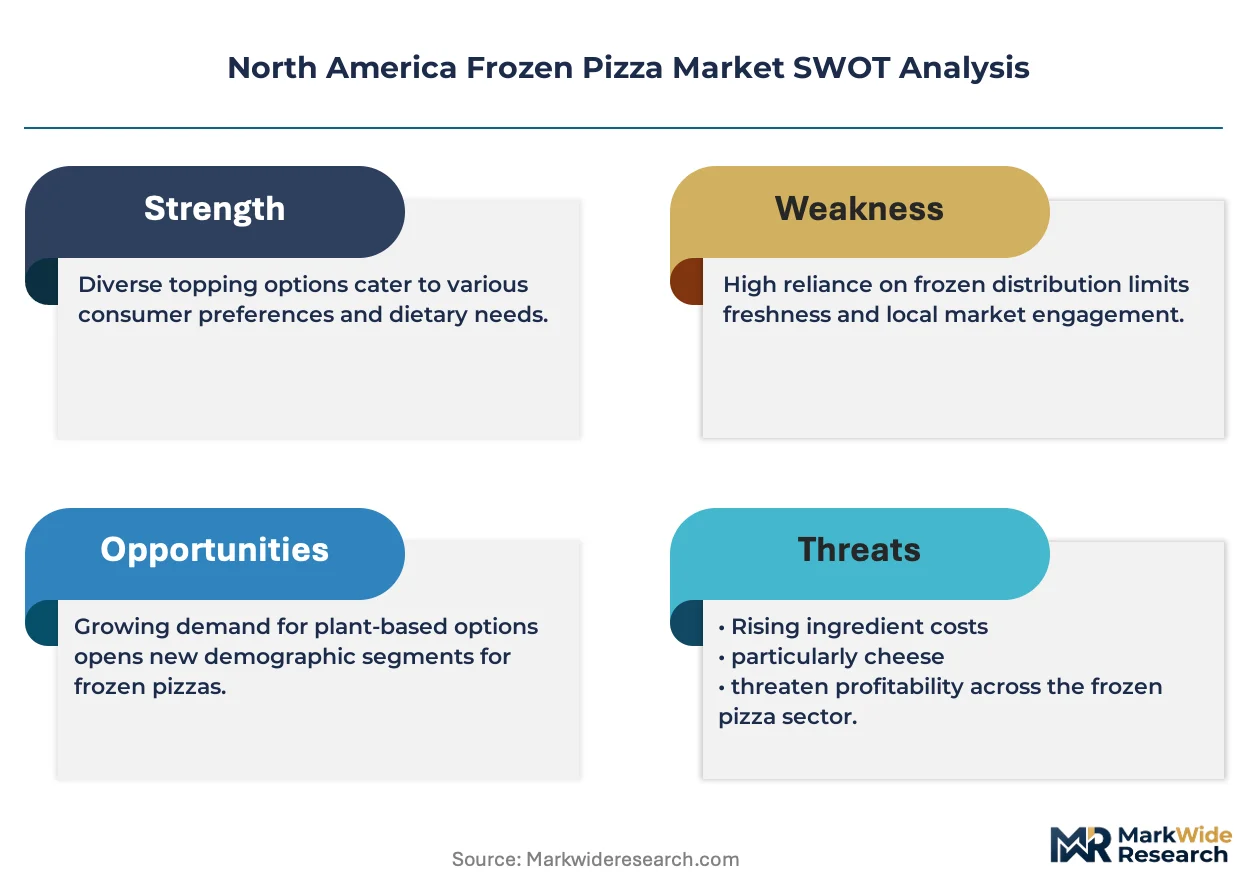
On the supply side, the industry is consolidating around capital-intensive cryogenic freezing infrastructure that separates high-volume processors from legacy operators. Three strategic archetypes dominate: diversified consumer goods conglomerates with global R&D networks, frozen-food specialists with captive distribution fleets, and mid-scale regional processors focused on clean-label certification. Competitive moves concentrate on multi-year foodservice contract consolidation and retrofitting production lines with liquid nitrogen tunnel systems.
Within the diversified conglomerate tier, Nestlé SA and General Mills Inc. exemplify scale-driven positioning across thin-crust and gluten-free portfolios. Schwan's Company anchors the frozen-food specialist archetype through customized supply relationships with institutional buyers. These three entities represent distinct capital-deployment strategies: global R&D leverage, extensive supermarket distribution depth, and foodservice channel captivity respectively.
| Leading Market Players |
|---|
| Nestlé SA |
| General Mills Inc. |
| Schwan's Company |
| Conagra Brands Inc. |
| Dr. August Oetker KG |
| Amy's Kitchen Inc. |
| Bellisio Foods Inc. |
| McCain Foods Ltd. |
| Palermo Villa Inc. |
| Others |
Pricing and Supply Chain Analysis
Cryogenic tunnel overcapacity in the Midwestern United States is pressuring equipment utilization rates below optimal thresholds, compelling processors to absorb fixed costs through aggressive contract pricing while dairy input volatility compresses margin buffers across all tiers.
Pricing Analysis
Blast-chamber legacy systems versus cryogenic tunnel next-generation infrastructure creates a technology-generation pricing gap that stratifies the competitive landscape. Three-tier pricing structure across premium, standard, and economy levels dominates, with price differentiation driven by certification grade (gluten-free protocols) and volume scale (foodservice contract tiers). Pricing pressure stems from mozzarella cost compression in the standard tier as global milk powder markets fluctuate. Household subscribers through e-commerce channels exhibit lowest price sensitivity, while convenience store impulse buyers face highest elasticity.
Supply Chain Analysis
Extended payment terms from sixty to ninety days now characterize supplier-processor relationships in the frozen dough segment, reflecting working capital strain throughout the value chain. Raw material concentration centers on Canadian wheat belts, California vegetable processing clusters, and Wisconsin dairy networks. Mozzarella blocks, tomato paste, and alternative flour blends constitute critical input dependencies. Single-source vulnerability in cryogenic equipment manufacturing creates procurement risk. Distribution runs through captive foodservice fleets and third-party cold-chain logistics with temperature-validated handoffs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as celiac disease protocols and clean-label mandates splinter demand into certifiable micro-segments that reward specialized positioning over conglomerate scale.
For Market Incumbents: Pre-empt emerging regional processors by securing exclusive multi-year foodservice contracts with institutional cafeteria networks before contract consolidation windows close. Accelerate retrofitting of legacy blast-freeze lines with liquid nitrogen injectors in Midwestern production facilities to defend margin position against quality-gap erosion from fresh-pizza delivery substitution.
For New Entrants and Emerging Players: Canadian metropolitan corridors outside Toronto and Vancouver represent the most penetrable geography for premium gluten-free positioning with bilingual packaging compliance as a barrier to incumbent replication. Target direct-to-foodservice channels in Quebec's institutional network through modified-atmosphere packaging specialization. Pursue celiac certification as the primary go-to-market credential.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale processors with captive cryogenic infrastructure and established clean-label certification rather than diversified conglomerates facing reformulation cost inflation. Long-term viability hinges on foodservice contract duration and R&D scale for alternative protein toppings. Monitor FDA sodium reduction timeline acceleration as the critical inflection signal for portfolio repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Tunnel Retrofit | Liquid nitrogen infrastructure preserves vegetable cellular structure previously limited to fresh distribution. |
| Gluten-Free Certification Investment | Celiac disease protocols attract premium shelf-price absorption from wheat-avoidance households. |
| Direct-to-Foodservice Fleet Buildout | Bypassing distributor markups captures margin pools in Canadian institutional cafeteria networks. |
| Modified-Atmosphere Packaging Convergence | Oxygen-scavenging films extend refrigerated distribution windows for premium thin-crust lines. |
| Sodium Reduction Reformulation | FDA targets force cheese blend and cured meat adjustments to maintain retail banner placement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling filings, USDA FSIS inspection records, Nielsen retail audit data, and cold-chain logistics trade publications. Interviews with frozen pizza plant managers, supermarket category buyers, foodservice procurement directors, and cryogenic equipment engineers informed demand-side and supply-side validation. Bottom-up volume triangulation from SKU-level retail velocity data combines with top-down value estimates from processor revenue disclosures across the analysis window.
Forecast inputs span product type segmentation (thin crust, gluten-free, deep dish, stuffed crust), distribution channel dynamics (supermarket, foodservice, convenience store, online retail), and customer archetype behavior (household subscription patterns, restaurant contract cycles, institutional procurement aggregation). CAGRs derive from regression against historical frozen food category performance and projected cryogenic adoption curves. Dairy input cost indices and clean-label regulatory enforcement timelines constitute industry-specific forecast inputs.
Practitioners should monitor FDA sodium reduction mandate acceleration, cryogenic equipment lead time extension, and cross-border Health Canada labeling harmonization efforts for early signals of forecast revision triggers. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Desserts Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Frozen Ready Meals Market
Processed and Frozen Foods
Frozen Shrimp Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Europe Frozen Desserts Market