
 Indonesia Frozen Food Market | 2026-2036
Indonesia Frozen Food Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Frozen Food Market Outlook
BPOM Regulation No. 31 of 2018 on processed food registration is hardening documentation requirements for imported frozen products, extending compliance timelines and raising capital barriers for new entrants. PT Charoen Pokphand Indonesia Tbk leverages its integrated poultry operations to dominate domestic frozen meat supply. McCain Foods Ltd anchors the premium frozen potato segment through controlled distribution partnerships with Indonesian hypermarket chains. JAPFA Ltd (PT So Good Food) competes across processed chicken categories with vertically coordinated feed-to-retail operations.
Indonesia frozen food encompasses thermally stabilized products preserved at minus eighteen degrees Celsius or below, encompassing raw proteins, blanched vegetables, and fully prepared meals manufactured through blast freezing or individual quick freezing to arrest microbial activity and maintain organoleptic integrity. The category serves retail households seeking meal convenience and foodservice operators requiring consistent portion control. Ready-to-eat meals capture expanding margin pools as urban dual-income households trade cooking time for frozen prepared solutions. Seafood maintains structural importance due to Indonesia's archipelagic catch capacity, though cold-chain gaps constrain inland penetration. Supermarkets and online retailers are diverging in assortment strategy, with brick-and-format operators emphasizing bulk frozen proteins while e-commerce platforms prioritize single-serve and premium ethnic meal kits.
BIS-equivalent national standardization through the National Standardization Agency (BSN) governs frozen product labeling and temperature integrity, while halal certification administered by the Halal Product Assurance Organizing Agency (BPJPH) shapes import eligibility and domestic product positioning. Municipal health departments in Surabaya and Medan enforce additional cold-storage inspection protocols that fragment compliance costs across distribution nodes. Stakeholders must monitor BPJPH's accelerating mandate timeline for mandatory halal labeling, which will force portfolio restructuring decisions before enforcement fully crystallizes.
Market Dynamics
BPOM's halal certification mandate is compressing product development cycles as importers reformulate recipes and relabel packaging to maintain market access across Java's urban corridor.
Growth Catalysts
- Cold-chain infrastructure:Refrigerated warehousing and last-mile delivery networks are penetrating Surabaya and Bandung, unlocking frozen protein distribution beyond Jakarta's established logistics basin.
- Dual-income household formation:Urban professionals in Greater Jakarta are trading cooking time for ready-to-eat frozen meals, expanding the addressable market for prepared solutions.
- BPJPH mandate acceleration:The Halal Product Assurance Organizing Agency's enforcement timeline is pulling forward domestic production investments to capture certification-compliant shelf space.
Market Restraints
- Import documentation burden:BPOM Regulation No. 31 of 2018 extends compliance timelines for frozen seafood and meat arrivals, raising working capital requirements for distributors.
- Cold-storage fragmentation:Municipal health departments in Medan enforce inspection protocols divergent from Surabaya standards, multiplying compliance nodes across the archipelago.
- Feed input volatility:Poultry processors face margin pressure from corn and soybean meal price swings that transmit directly into frozen chicken pricing power.
Strategic Opportunities
- Eastern Indonesia penetration:Sulawesi and Papua present underdeveloped frozen food markets where cold-chain gaps currently limit competitive entry.
- Ethnic meal kit formats:E-commerce platforms are prioritizing single-serve rendang and soto ayam kits that command premium positioning over bulk protein blocks.
- BSN standardization alignment:The National Standardization Agency's labeling harmonization creates first-mover advantage for domestic producers mastering temperature-integrity documentation.
Industry Challenges
- Halal certification backlog:BPJPH processing delays are stretching product launch timelines, forcing inventory pre-positioning ahead of approval confirmation.
- Cold-chain technician scarcity:Refrigeration maintenance and blast-freezing operation skills concentrate in Java, constraining facility expansion to secondary islands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Frozen Food Market |
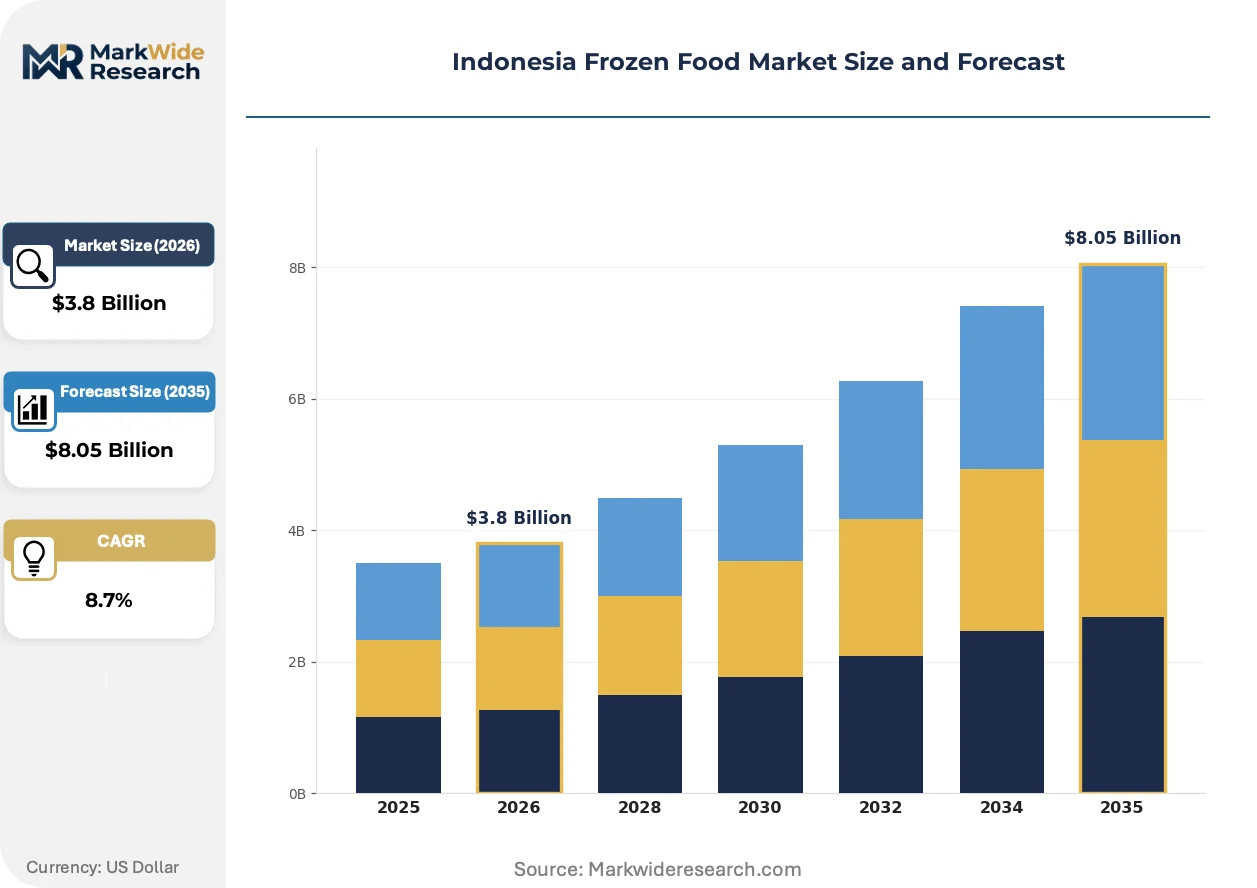
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Seafood, Vegetables, Ready-to-Eat Meals Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale End User: Households, Restaurants, Catering Services, Food Processors Packaging Type: Bags, Boxes, Trays, Vacuum Sealed |
| Companies Covered | Gunung Sewu Group (Belfoods Indonesia), General Mills Inc., PT Charoen Pokphand Indonesia Tbk, Pronas Indonesia, Ezaki Glico Co. Ltd, JAPFA Ltd (PT So Good Food), PT Sekar Bumi Tbk, McCain Foods Ltd, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Frozen Food Market Strategic Shifts
Blast freezing and individual quick freezing technologies are reshaping product quality benchmarks as urban consumers reject ice-crystal degradation in home-prepared meals.
Individual quick freezing is overtaking traditional blast freezing in premium vegetable and seafood processing. Quick-service restaurants in Surabaya are adopting IQF shrimp and cut vegetables to reduce prep labor. This technology is overtaking commodity freezing methods by preserving cellular structure and extending thawed shelf appeal.
BPJPH's accelerating mandatory halal labeling timeline is forcing portfolio restructuring decisions across imported and domestic product lines. Processors must segregate production lines and audit supply chains to maintain certification integrity. Frozen prepared meals and processed chicken categories face the steepest compliance investment requirements as enforcement crystallizes.
Urban households are consolidating frozen food purchases into weekly e-commerce orders with precise delivery-window requirements. Hypermarket operators are responding with dark-store fulfillment models that bypass in-store frozen aisle browsing. This pattern is most pronounced in Jakarta's satellite cities where traffic congestion and working-hour compression limit traditional retail trips.
Indonesia Frozen Food Market Segmentation
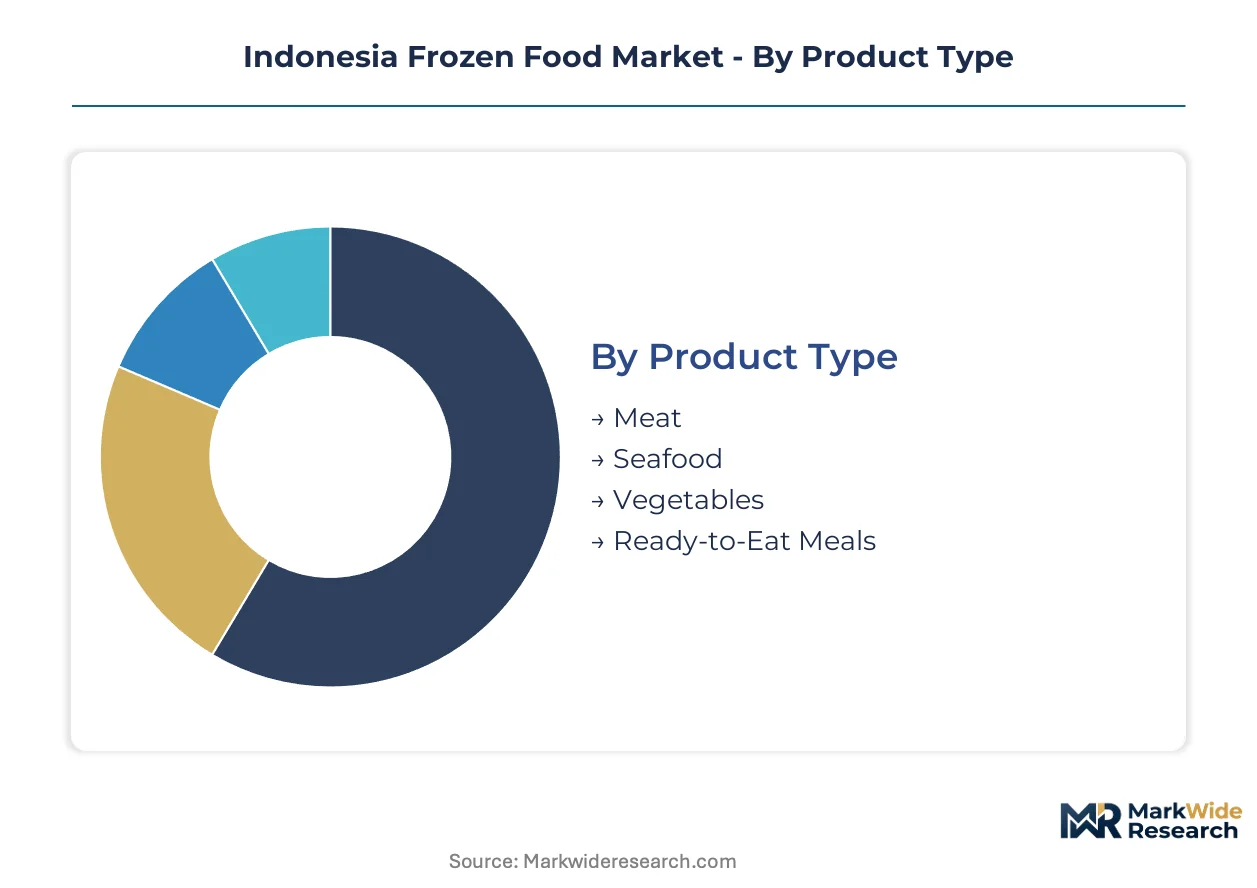
Indonesia's frozen food segmentation reveals distinct operational requirements across product categories, with cold-chain maturity and halal compliance creating divergent competitive barriers. Understanding these segment boundaries clarifies where capital deployment yields protected returns versus commoditized positioning.
Product Type:
Standalone frozen categories operate through dedicated supply chains, while embedded frozen ingredients integrate into broader food manufacturing workflows.
- Meat:Frozen poultry and beef cuts preserved at minus eighteen degrees Celsius serve quick-service restaurants requiring portion consistency. Procurement concentrates in Jakarta and Surabaya as cold-storage facilities cluster around urban processing centers.
- Seafood:IQF shrimp and fish fillets maintain cellular integrity through rapid freezing protocols. Demand anchors in coastal catch zones with BPOM import documentation extending compliance timelines for foreign-sourced products.
- Vegetables:Blanched frozen produce supplies industrial food processors and retail private labels.
- Ready-to-Eat Meals:Fully prepared frozen dishes target dual-income households trading cooking time for convenience solutions.
Volume placements concentrate in meat; the faster expansion belongs to ready-to-eat meals.
Distribution Channel:
Channel selection determines temperature-integrity investment levels and last-mile cost structures across Indonesia's fragmented logistics landscape.
- Supermarkets:Brick-and-mortar frozen aisles emphasize bulk protein blocks and family-size packaging formats. Modern retail chains in Java's urban corridor deploy dark-store fulfillment to defend against e-commerce encroachment.
- Online Retailers:E-commerce platforms prioritize single-serve ethnic meal kits and premium seafood with precise delivery-window guarantees. Jakarta's satellite cities drive adoption as traffic congestion limits traditional retail trips.
- Convenience Stores:Limited frozen SKUs target impulse purchases and immediate consumption occasions.
- Wholesale:Bulk frozen protein distribution serves foodservice operators and institutional buyers.
Supermarkets retain the largest volume footprint; online retailers are climbing the fastest.
End User:
User segments separate between consumption at point-of-purchase versus transformation through further processing or foodservice preparation.
- Households:Urban families in Greater Jakarta consolidate weekly frozen purchases through e-commerce platforms with scheduled delivery slots. Meal kit formats command premium positioning over commodity protein blocks.
- Restaurants:Quick-service chains in Surabaya and Bandung expand IQF vegetable and seafood procurement to reduce kitchen labor and standardize portion costs.
- Catering Services:Institutional meal providers source bulk frozen proteins for event and contract feeding operations.
- Food Processors:Manufacturers integrate frozen ingredients into further-processed consumer goods and industrial food formulations.
Restaurants generate the steepest volume concentration; households show the steepest expansion trajectory.
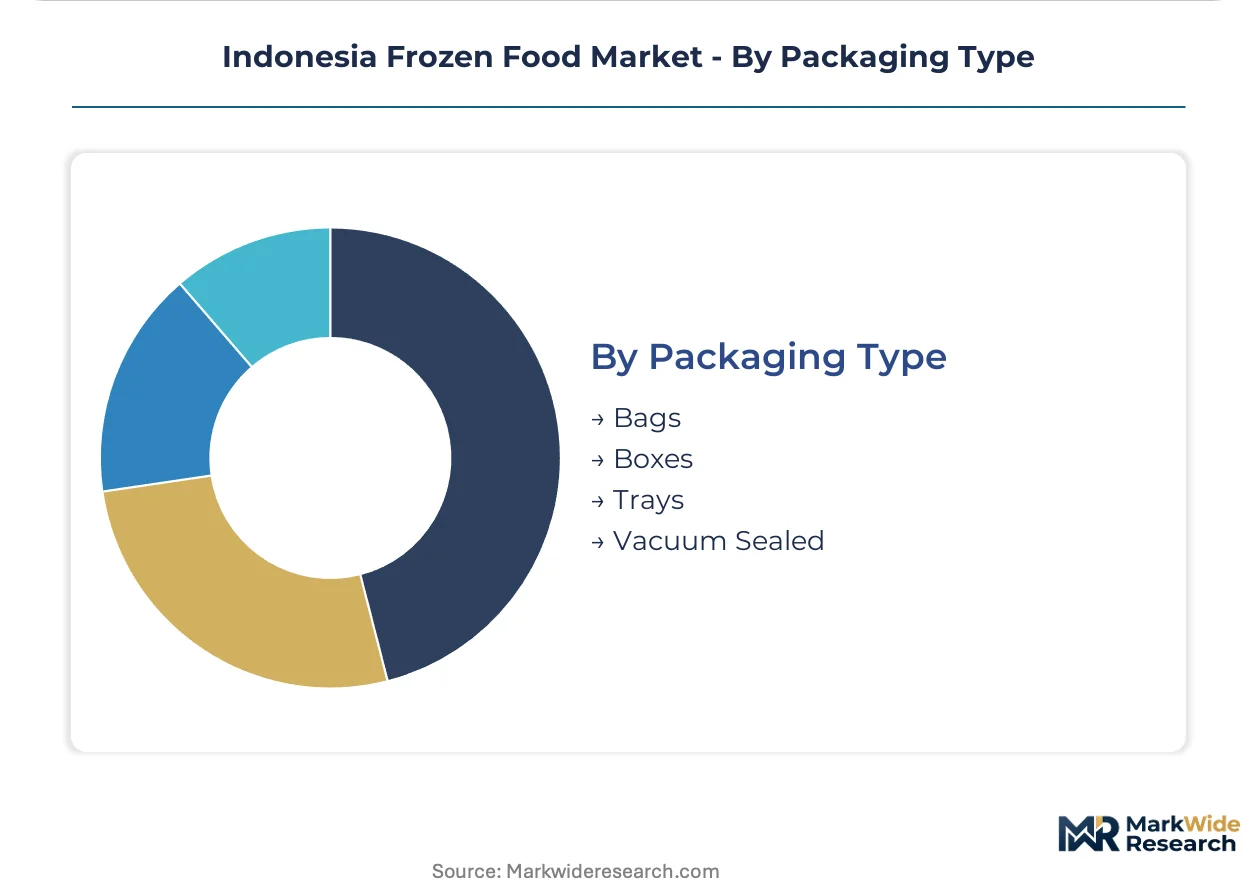
Packaging Type:
Packaging selection reflects shelf-life requirements, handling durability, and retail format constraints across distribution environments.
- Bags:Flexible polyethylene packaging dominates frozen vegetable and portioned meat categories. Cost efficiency and storage density favor bag formats for wholesale and supermarket bulk sales.
- Boxes:Rigid paperboard containers protect ready-to-eat meals and premium seafood through distribution handling. Shelf presence and stacking stability support hypermarket placement.
- Trays:Thermoformed plastic containers serve marinated meats and prepared meal components.
- Vacuum Sealed:Barrier film packaging extends shelf life for high-value seafood and specialty meat cuts.
Bags capture the dominant volume share; vacuum sealed formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
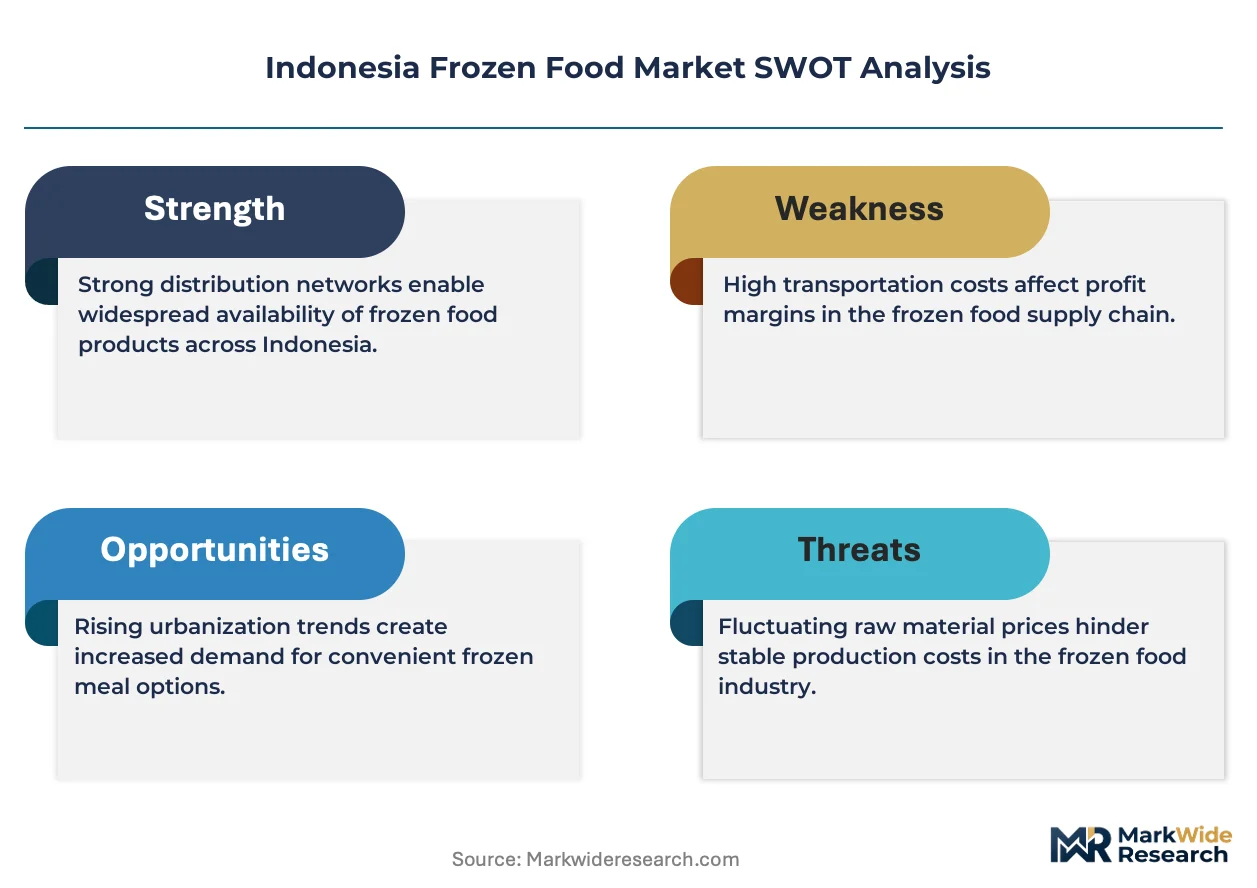
The Kendal Industrial Park in Central Java anchors frozen food manufacturing concentration through tax holidays and import duty exemptions that draw cold-chain infrastructure investment away from Jakarta's saturated logistics basin.
Java
Greater Jakarta and Surabaya generate the steepest frozen protein demand as quick-service restaurant chains expand procurement. BPJPH halal certification mandates compress product development cycles for processors seeking shelf space in modern retail. Bandung's emerging cold-storage clusters unlock distribution reach into West Java's secondary urban corridors.
Sumatra
Medan's municipal health departments enforce cold-storage inspection protocols divergent from Java standards, fragmenting compliance costs. Feed input volatility around corn and soybean meal squeezes poultry processor margins across North Sumatra's integrated operations. Palembang's growing retail footprint attracts frozen vegetable distributors seeking alternatives to Jakarta congestion.
Sulawesi
Underdeveloped cold-chain gaps currently limit competitive entry into Makassar and Manado markets. BPOM import documentation burdens extend timelines for frozen seafood arrivals at Bitung's port facilities. Local catch capacity supports structural seafood demand, though inland penetration awaits refrigerated warehousing expansion.
Kalimantan
Balikpapan and Samarinda present nascent demand for frozen prepared meals among oil and gas sector dual-income households. BSN national standardization alignment creates documentation advantages for domestic producers mastering temperature-integrity protocols. Cold-chain technician scarcity constrains facility expansion beyond coastal logistics nodes.
Papua
Jayapura's isolated geography preserves premium pricing for air-frozen protein imports serving mining camp foodservice operations. Halal certification backlogs stretch product launch timelines, forcing inventory pre-positioning ahead of BPJPH approval confirmation. Limited retail infrastructure channels demand through wholesale procurement by institutional catering providers.
Indonesia Frozen Food Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Indonesia's frozen food terrain. The vendor base fragments between integrated poultry operators controlling upstream feed supply and import-dependent distributors navigating BPOM documentation burdens. Three archetypes dominate: vertically coordinated agribusinesses, multinational frozen potato and meal kit specialists, and domestic processors leveraging halal certification speed-to-market. Capacity expansion and portfolio diversification constitute the dominant competitive moves as players reposition ahead of mandatory halal labeling enforcement.
Among domestic integrated operators, PT Charoen Pokphand Indonesia Tbk and JAPFA Ltd (PT So Good Food) exemplify the feed-to-retail coordination archetype that dominates frozen poultry supply. McCain Foods Ltd anchors the premium frozen potato segment through controlled distribution partnerships with Indonesian hypermarket chains. These three occupy positions that illustrate how backward integration into captive feed supply and certification-compliant production lines separate protected returns from commoditized import-distributor positioning.
| Leading Market Players |
|---|
| Gunung Sewu Group (Belfoods Indonesia) |
| General Mills Inc. |
| PT Charoen Pokphand Indonesia Tbk |
| Pronas Indonesia |
| Ezaki Glico Co. Ltd |
| JAPFA Ltd (PT So Good Food) |
| PT Sekar Bumi Tbk |
| McCain Foods Ltd |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
BPJPH's mandatory halal labeling timeline gates qualified supply access and premium-tier pricing power, forcing processors to segregate production lines and audit supply chains before certification deadlines crystallize. Importers lacking compliant documentation face extended clearance timelines at Indonesian ports, compressing margins and diverting volume toward domestic producers with in-house certification capabilities.
Pricing Analysis
Short lead-time premiums attach to IQF seafood and certified halal poultry arriving through Jakarta's expedited cold-chain corridors, while spot inventory discounts clear excess frozen vegetable stocks ahead of temperature-integrity degradation. Three-tier pricing structure across premium, standard, and economy levels separates BPJPH-certified meal kits from commodity protein blocks and bulk wholesale lots. Pricing pressure stems from feed input volatility transmitting through integrated poultry operations. Quick-service restaurants show least price sensitivity; institutional catering buyers exhibit highest elasticity.
Supply Chain Analysis
Inter-island freight costs multiply landed expenses for frozen proteins moving beyond Java's refrigerated warehousing clusters, with last-mile cold-chain gaps in Sulawesi and Papua preserving premium pricing for air-freighted imports. Supply concentrates in Indonesia's domestic poultry operations, Australian beef exporters, and Thai seafood processors. Raw material dependencies center on corn and soybean meal for feed, blast-freezing equipment for processing, and halal-certified packaging films. Single-source vulnerability runs through BPJPH certification bottlenecks. Distribution runs through hypermarket dark-store fulfillment and e-commerce scheduled delivery slots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive feed supply and certification-compliant production lines separate protected returns from commoditized import-distributor positioning. Players are pursuing upstream control over poultry breeding and feed milling to defend margin structures.
For Market Incumbents: Anticipate BPJPH processing delays by pre-positioning inventory ahead of approval confirmation and accelerating captive halal certification capacity. Defend shelf space through dark-store fulfillment partnerships with Jakarta hypermarket chains. Threat: E-commerce platforms capturing dual-income household volume through ethnic meal kit subscriptions.
For New Entrants and Emerging Players: Launch via e-commerce scheduled delivery slots targeting Jakarta satellite cities where traffic congestion limits traditional retail trips. White-space targets: Sulawesi's underdeveloped cold-chain corridors and Papua's mining camp foodservice procurement. Go-to-market angle: Premium IQF seafood with temperature-integrity documentation exceeding BSN standards.
For Investors and Strategic Acquirers: BPJPH certification backlogs stretching product launch timelines is the leading indicator that domestic halal-compliant production assets command scarcity premiums. Long-term viability favors integrated feed-to-retail operators with captive cold-storage networks. Acquisition target archetype: Mid-cap processors with certified production lines and established hypermarket relationships. Signal to watch: Municipal health department protocol harmonization reducing compliance fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | BPJPH-compliant production lines capture shelf space ahead of mandatory labeling enforcement. |
| Cold-Chain Infrastructure Expansion | Refrigerated warehousing in Surabaya and Bandung unlocks distribution beyond Jakarta's logistics basin. |
| Backward Integration into Feed Supply | Captive corn and soybean meal sourcing insulates poultry processors from input price volatility. |
| E-Commerce Platform Partnership | Dark-store fulfillment models defend hypermarket volume against online ethnic meal kit encroachment. |
| IQF Technology Upgrade | Individual quick freezing preserves cellular integrity for premium positioning in quick-service restaurant procurement. |
Study Parameters
Document review covered BPOM regulatory filings, BSN standardization protocols, and BPJPH certification timelines, complemented by interviews with cold-chain logistics operators, hypermarket category buyers, poultry processing plant managers, and quick-service restaurant procurement heads. Secondary sources included customs import records, municipal health department inspection protocols, and integrated agribusiness financial disclosures. Bottom-up demand modeling from household consumption patterns and foodservice procurement volumes was cross-referenced against top-down market sizing from production capacity assessments.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end-user category, and packaging format. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated cold-chain infrastructure buildout timelines and BPJPH enforcement acceleration scenarios.
Feed price volatility, BPJPH processing delays, and municipal protocol fragmentation are the dominant revision risks that could compress or extend projected growth trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Frozen Tart Shells Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market