
 Frozen Ready Meals Market | 2026-2036
Frozen Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Ready Meals Market Intelligence
Food technologist shortages across developed markets is redrawing production capacity and innovation pipelines. Nestle leverages its European R&D network to sustain clean-label development, while Conagra Brands, Inc. anchors North American manufacturing scale through multi-plant distribution. Ajinomoto Co. Inc. differentiates via umami-based flavor systems that reduce sodium without reformulation trade-offs.
Frozen ready meals are pre-cooked, blast-chilled food products stored at minus 18 degrees Celsius, typically incorporating proteins, starches, and sauces in single-serve formats designed for microwave or oven regeneration within minutes. Microwaveable meals dominate volume due to workplace and dormitory consumption patterns, while gluten-free options capture expanding margin pools from allergen-sensitive buyers. Vegetarian options are outpacing cooked frozen meat in growth velocity across online grocery platforms where specialty diet filtering drives discovery.
The US FDA enforces nutrition fact panel modernization and sodium reduction targets that reshape formulation priorities, while EU EFSA additive approvals and the EU Green Deal packaging directives constrain material choices and shelf-life engineering. Japan's Ministry of Health, Labour and Welfare maintains strict microbiological standards for retort-compatible frozen imports. Stakeholders must monitor regulatory divergence between preservative tolerance thresholds and circular packaging mandates to align R&D spending with compliance boundaries.
Market Dynamics
Reformulation pressure from sodium disclosure mandates is compressing R&D timelines and forcing trade-offs between clean-label positioning and shelf-life stability across frozen ready meal portfolios.
Growth Catalysts
- Single-person household expansion:Germany, the United Kingdom, and Japan are seeing accelerated adoption of microwaveable and tray-pack formats as demographic shifts favor convenience-oriented portion sizes.
- EU Green Deal packaging directives:Circular material mandates are driving investment in recyclable tray substrates and biodegradable films that align with retailer sustainability scorecards.
- Cold-chain infrastructure maturation:Premium frozen seafood and vegetarian ranges now reach urban distribution nodes in Japan and Western Europe with minimal temperature excursion risk.
Market Restraints
- Input cost volatility:Wheat protein and specialty vegetable oil prices fluctuate with climate-driven harvest variability, squeezing margin on mid-tier vegetarian formulations.
- Regulatory friction:Divergent sodium tolerance thresholds between US FDA reduction targets and EU EFSA disclosure rules complicate pan-regional product line architecture.
- Substitution threat:Fresh meal-kit delivery services with shorter ingredient lists capture health-conscious buyers willing to trade convenience for perceived freshness.
Strategic Opportunities
- Underpenetrated geography:Poland and Romania present white space for premium frozen ready meals as modern retail formats expand beyond capital cities.
- Technology convergence:High-pressure processing combined with modified atmosphere packaging extends clean-label shelf life without traditional preservatives.
- Regulatory tailwind:Japan's Ministry of Health, Labour and Welfare microbiological standards for retort-compatible frozen imports create a certification moat for compliant exporters.
Industry Challenges
- Food technologist scarcity:Developed markets face acute shortages of formulation specialists capable of balancing sodium reduction with umami delivery and freeze-thaw stability.
- Capex intensity:Blast-freezing equipment upgrades and automated tray-sealing lines demand capital deployment that mid-tier producers struggle to fund.
- Certification timeline compression:Dual compliance with EU EFSA additive approvals and US FDA nutrition panel modernization extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Ready Meals Market |
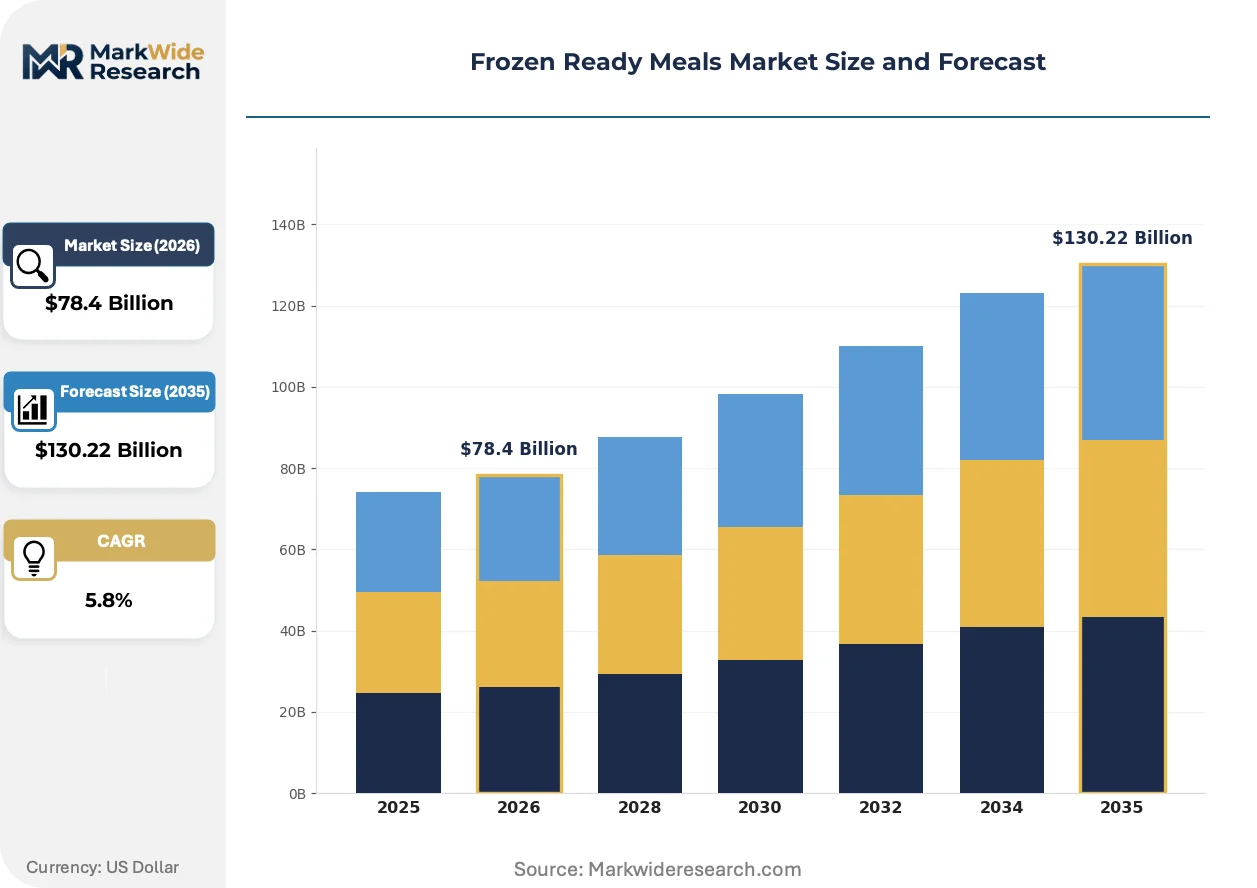
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microwaveable Meals, Cooked Frozen Meat, Vegetarian Options, Seafood Frozen Meals, Gluten-Free Options Packaging Type: Tray Packs, Vacuum Packs, Boxed Meals, Pouch Packs, Clamshell Containers Sales Channel: Supermarkets, Convenience Stores, Online Grocery Platforms, Wholesale Distributors, Specialty Food Stores Customer Type: Working Professionals, Students, Elderly Consumers, Fitness Enthusiasts, Single-Person Households |
| Companies Covered | The Kraft Heinz Company, Unilever, Conagra Brands, Inc., Nomad Foods Ltd., Kellogg Co., General Mills Inc., McCain Foods Limited, Ajinomoto Co. Inc., Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Ready Meals Market Strategic Shifts & Innovations
Clean-label preservation and rapid regeneration technologies are converging to redefine acceptable trade-offs between convenience and ingredient transparency in frozen meal portfolios.
High-pressure processing is supplanting traditional thermal sterilization in premium frozen ready meal manufacturing. Retailers in Germany and the United Kingdom are prioritizing HPP-treated lines for their private-label portfolios. This shift is compressing the acceptable ingredient list while extending refrigerated shelf life claims.
EU EFSA additive approval tightening is reshaping emulsifier and stabilizer selection across European formulation labs. Manufacturers are retreating from long-standing hydrocolloid systems toward label-friendly alternatives like citrus fiber and potato starch derivatives. Vegetarian and vegan frozen ranges face the steepest reformulation burden as texture replication without synthetic additives becomes mandatory.
Direct-to-freezer subscription models are fragmenting traditional grocery channel dominance in urban Japan and the United Kingdom. Young professional households are bypassing supermarket frozen aisles for curated monthly boxes with dietary preference filtering. This behavioral pivot is forcing legacy brands to rebuild digital fulfillment capabilities and micro-segment their SKU architectures.
Frozen Ready Meals Market Segmentation
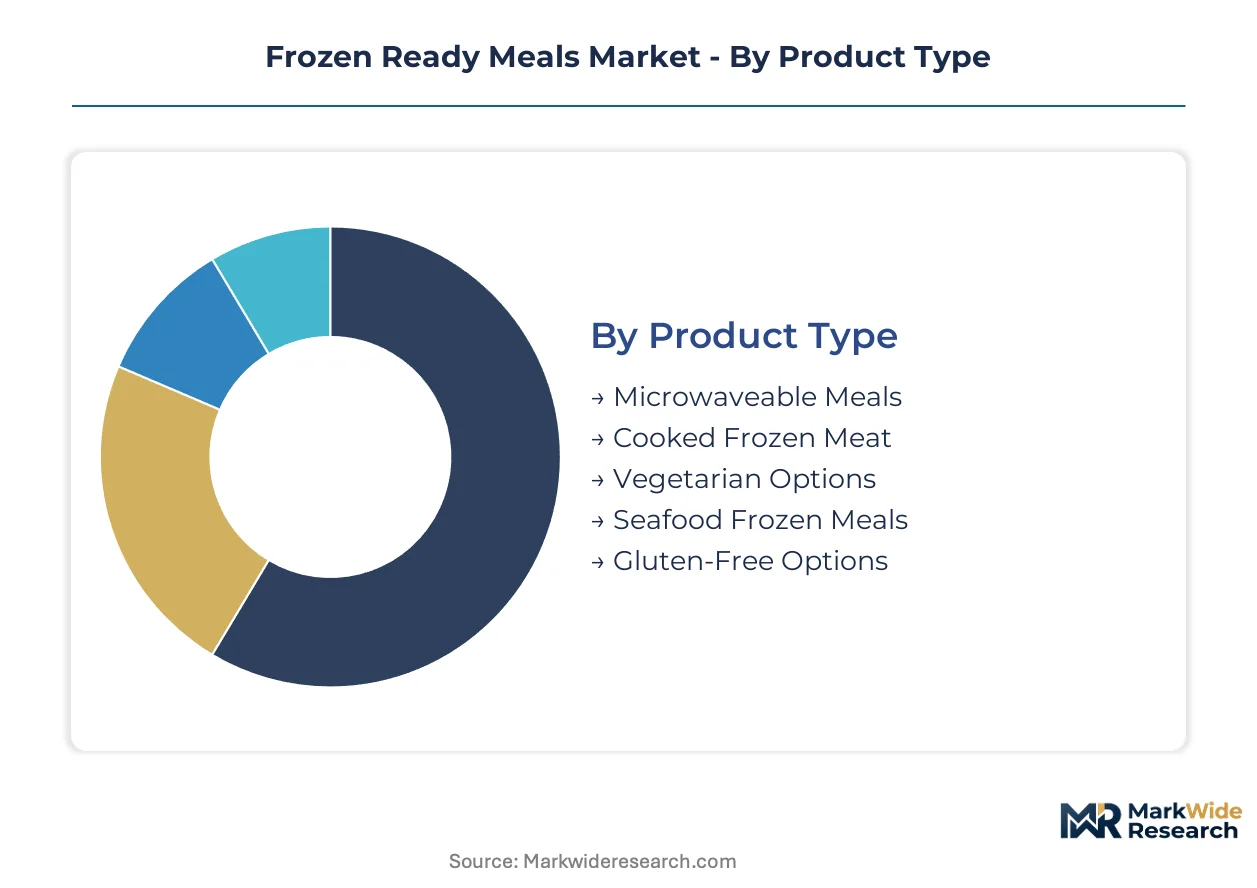
Frozen ready meals segment along four axes that reshape competitive priorities. Product and packaging choices determine cold-chain requirements and shelf-life engineering, while channel and customer splits dictate pricing architecture and portion strategy.
Product Type:
Microwaveable meals dominate domestic consumption across Germany and Japan, where single-person households prioritize speed over preparation ritual. Export-led segments concentrate in premium seafood and vegetarian ranges bound for cold-chain mature markets.
- Microwaveable Meals:Pre-cooked protein-starch-sauce combinations in single-serve formats engineered for sub-five-minute regeneration. Demand clusters in Japanese urban corridors and UK workplace canteens where time compression overrides price sensitivity.
- Vegetarian Options:Plant-protein centric formulations using textured vegetable proteins and legume bases with reduced sodium profiles. Germany's clean-label retail environment accelerates SKU proliferation beyond capital cities into secondary urban nodes.
- Cooked Frozen Meat:Traditional protein-centric meals with gravy or sauce matrices.
- Seafood Frozen Meals:Premium fish and shellfish combinations requiring strict temperature maintenance.
- Gluten-Free Options:Rice, quinoa, or specialty grain bases targeting allergen-sensitive buyers.
Microwaveable meals hold the largest share; momentum sits with vegetarian options.
Packaging Type:
Cost tier stratification runs through material selection, with substrate engineering determining retail price positioning and sustainability credentialing.
- Tray Packs:Rigid polymer or fiber-based containers with heat-stable films enabling direct oven or microwave regeneration. UK and German retailers mandate recyclable tray substrates under EU Green Deal packaging directives, forcing substrate migration from multi-layer plastics to mono-material or fiber alternatives.
- Vacuum Packs:Barrier film systems removing headspace oxygen to extend frozen shelf life without preservative loading. Japanese import channels favor vacuum configurations for seafood ranges where oxidation control determines quality perception at premium price points.
- Boxed Meals:Carton-sleeved formats with internal tray or pouch containment.
- Pouch Packs:Flexible standing or flat pouches reducing shipping cube and freezer footprint.
- Clamshell Containers:Hinged-lid formats for multi-component meal separation.
Tray packs command the volume base; vacuum packs are climbing the fastest on export premiumization.
Sales Channel:
Channel concentration patterns reveal geographic maturity gradients, with modern retail penetration dictating format availability.
- Supermarkets:Full-range frozen aisles with category management driving planogram placement fees. Poland and Romania expand modern retail floor space beyond Warsaw and Bucharest, creating white space for premium range entry.
- Online Grocery Platforms:Digital fulfillment with dietary preference filtering and subscription bundling. UK and Japanese young professional households bypass physical aisles for curated monthly boxes, fragmenting traditional grocery dominance.
- Convenience Stores:Grab-and-go formats targeting immediate consumption occasions.
- Wholesale Distributors:Foodservice and institutional volume channels.
- Specialty Food Stores:Curated premium and allergen-specific ranges.
Supermarkets retain the dominant share; online grocery platforms show the steepest expansion trajectory.
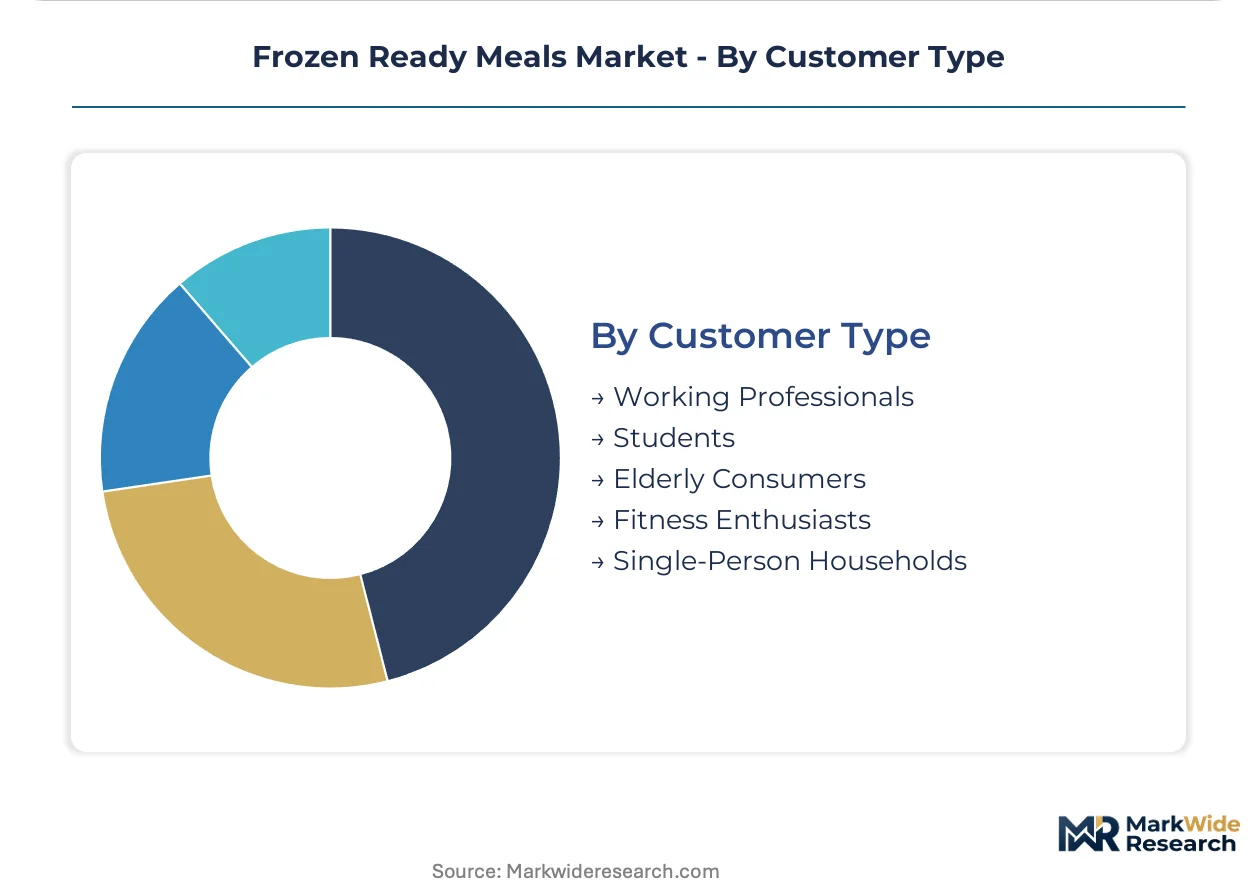
Customer Type:
Demographic targeting aligns portion engineering with life-stage consumption patterns and health positioning.
- Single-Person Households:Single-serve portions optimized for no-waste consumption with protein targets calibrated to individual daily intake. Germany, the United Kingdom, and Japan show accelerated adoption as household size compression favors convenience-oriented formats.
- Working Professionals:Time-pressed buyers prioritizing speed and nutritional density over price minimization. Lunch occasion targeting drives microwaveable format preference in urban employment clusters.
- Students:Price-sensitive volume buyers accepting ingredient transparency trade-offs.
- Elderly Consumers:Soft-texture and sodium-controlled formulations.
- Fitness Enthusiasts:Macro-balanced high-protein ranges with clean-label positioning.
Single-person households represent the largest addressable base; fitness enthusiasts are gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition fact panel modernization and sodium reduction targets anchor the United States as the regulatory benchmark shaping formulation priorities across developed markets. Cold-chain infrastructure maturation and single-person household expansion drive divergent growth velocities across national markets.
United States
Working professionals and single-person households in urban corridors accelerate microwaveable meal adoption. FDA sodium disclosure mandates compress R&D timelines for reformulation cycles. Chicago and Dallas-Fort Worth industrial clusters host automated tray-sealing lines serving national distribution networks.
Germany
Clean-label retail environments and EU Green Deal packaging directives accelerate substrate migration toward recyclable tray formats. EFSA additive approval tightening reshapes emulsifier selection in European formulation labs. Berlin and Munich distribution nodes support premium vegetarian range penetration into secondary urban markets.
United Kingdom
Online grocery platforms with dietary preference filtering fragment traditional supermarket channel dominance among young professional households. EU EFSA disclosure rules overlap with domestic sodium reduction campaigns. London and Manchester cold-chain infrastructure supports direct-to-freezer subscription model expansion.
Japan
Ministry of Health, Labour and Welfare microbiological standards for retort-compatible frozen imports create certification moats for compliant exporters. Single-person households in Tokyo and Osaka corridors favor microwaveable formats for workplace consumption. Nagoya industrial zones concentrate blast-freezing capacity for seafood meal export.
Poland
Modern retail floor space expansion beyond Warsaw creates white space for premium range entry. EU packaging directives apply as member state obligations. Krakow and Wrocław distribution nodes extend cold-chain reach into secondary cities previously served by ambient alternatives.
Frozen Ready Meals Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in multi-plant distribution networks and continental R&D footprints. Mid-tier producers face capital constraints on blast-freezing equipment upgrades and automated sealing line deployment. Two strategic archetypes dominate: diversified food conglomerates leveraging cross-category formulation expertise, and frozen specialists optimizing cold-chain logistics density. Competitive moves center on portfolio diversification into vegetarian and clean-label ranges, and geographic expansion through modern retail penetration in underdeveloped secondary cities.
Within the diversified conglomerate tier, Nestle and Conagra Brands, Inc. exemplify scale-driven positions anchored in continental manufacturing footprints and multi-channel distribution architectures. Ajinomoto Co. Inc. occupies a distinct specialization vector focused on umami-based flavor systems that address sodium reduction without reformulation trade-offs. These three entities collectively represent the strategic spectrum spanning R&D-intensive clean-label development, North American manufacturing scale, and Asia-Pacific flavor technology integration.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Unilever |
| Conagra Brands, Inc. |
| Nomad Foods Ltd. |
| Kellogg Co. |
| General Mills Inc. |
| McCain Foods Limited |
| Ajinomoto Co. Inc. |
| Nestle |
| Others |
Cost & Logistics Intelligence
Ninety-day frozen inventory cycles in blast-chilled distribution networks concentrate pricing power with cold-chain operators while squeezing mid-tier producers unable to fund automated tray-sealing upgrades. This lead-time band tightens margins on vegetarian formulations where wheat protein and specialty vegetable oil inputs fluctuate with climate-driven harvest variability.
Pricing Analysis
German and Japanese retail price spreads for premium frozen seafood meals diverge from economy microwaveable tiers by certification grade and packaging substrate compliance with EU Green Deal directives. Three-tier pricing structure across premium, standard, and economy levels stratifies by clean-label positioning and sodium disclosure tier, with fitness enthusiasts showing least price sensitivity and students most. Pricing pressure stems from input cost volatility in mid-tier vegetarian ranges, compressing margins for producers lacking multi-plant distribution scale.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Japanese seafood meal exporters sourcing retort-compatible packaging films. Supply concentrates in Germany, the United Kingdom, and Japan for blast-freezing capacity, with raw material dependencies on Norwegian frozen fish, Ukrainian wheat protein, and Malaysian palm oil derivatives. Single-source vulnerability in specialized emulsifier supply chains feeds from EFSA additive approval tightening. Distribution runs through supermarket frozen aisles and direct-to-freezer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as fresh meal-kit delivery services with shorter ingredient lists capture health-conscious buyers willing to trade convenience for perceived freshness.
For Market Incumbents: Compound clean-label R&D investments with high-pressure processing adoption to extend shelf life without preservative loading, defending against meal-kit freshness claims. Deepen backward integration into recyclable tray substrate manufacturing to secure EU Green Deal compliance margins. Prioritize certification moats under Japan's Ministry of Health, Labour and Welfare microbiological standards for retort-compatible frozen imports.
For New Entrants and Emerging Players: Anchor in Poland and Romania's secondary urban markets where modern retail floor space expansion creates white space for premium range entry. Target single-person households in Krakow and Wrocław with microwaveable vegetarian formats priced below German import tiers. Deploy direct-to-freezer subscription bundling with dietary preference filtering to bypass incumbent supermarket planogram fees.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates spinning non-core frozen assets amid portfolio rationalization pressures. Mid-tier producers with blast-freezing equipment gaps but established retail relationships present consolidation value over a five-to-ten year cold-chain infrastructure buildout horizon. Monitor EU EFSA sodium disclosure rule harmonization progress as inflection indicator for pan-regional product line viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | Reduces sodium profiles using Ajinomoto-style umami systems without texture trade-offs. |
| Recyclable Tray Substrate Migration | Aligns packaging engineering with EU Green Deal circular material mandates. |
| High-Pressure Processing Deployment | Extends refrigerated shelf life claims for private-label retail portfolios in Germany. |
| Direct-to-Freezer Subscription Launch | Bypasses supermarket channel dominance among UK and Japanese young professionals. |
| Secondary City Distribution Expansion | Captures white space in Poland and Romania beyond Warsaw and Bucharest nodes. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA nutrition panel filings, EU EFSA additive approval registers, and cold-chain logistics databases. Food technologists, category buyers at German and UK retailers, blast-freezing equipment operators, and regulatory affairs specialists at frozen meal manufacturers provided operational validation. Customs trade data, Nielsen retail audit figures, and Ministry of Health, Labour and Welfare import certification records anchored secondary triangulation. Bottom-up SKU-level volume builds and top-down category expenditure estimates were cross-checked for convergence.
Segmentation dimensions modeled include product type, packaging substrate, sales channel architecture, and customer demographic across the analysis window. CAGRs derived from trend extrapolation of single-person household formation rates, cold-chain infrastructure investment flows, and sodium disclosure regulatory adoption curves. Forecast inputs incorporated vegetarian SKU proliferation velocity and high-pressure processing equipment installation pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable Asia-Europe shipping lane capacity; material deviation would warrant model refresh. Forecasts reflect baseline scenarios of regulatory harmonization progress and cold-chain maturation in target geographies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
South America Frozen Food Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Europe Frozen Finger Chips Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Spiral Freezer Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market