
 South America Frozen Desserts Market | 2026-2036
South America Frozen Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
South America Frozen Desserts Market Analytics
ANVISA's revised food additive and labeling standards is rebalancing the cost-of-entry calculus for both domestic producers and importers entering Brazil. Nestlé S.A. leverages its multi-brand portfolio and cold-chain infrastructure to sustain shelf presence across supermarket and convenience channels. Grupo Nutresa anchors its position through deep distribution in Colombia and Andean markets, while Arcor competes aggressively on price in Argentina's inflation-pressured retail environment.
Frozen desserts comprise dairy-based and water-based formulations preserved below freezing temperatures, typically incorporating milk fat, sweeteners, stabilizers, and flavoring agents to achieve specific overrun and texture parameters; their primary commercial purpose is to deliver portion-controlled, ready-to-consume indulgence through retail and food-service channels. Ice cream occupies the dominant margin pool given its higher per-unit value and established consumer habituation, while frozen yogurt captures faster velocity in health-positioned urban demographics. Gelato remains a niche premium tier concentrated in upscale food-service accounts and specialty retail.
ANVISA in Brazil, INVIMA in Colombia, and Senasa in Argentina enforce divergent additive approvals and nutritional labeling mandates that fragment product standardization across borders. These regulatory discontinuities force manufacturers to maintain country-specific SKUs, elevating compliance costs and constraining scale economies for regional rollouts. Stakeholders must monitor pending Mercosur harmonization talks and pre-position flexible formulation platforms that can adapt to whichever regulatory convergence path materializes.
Market Dynamics
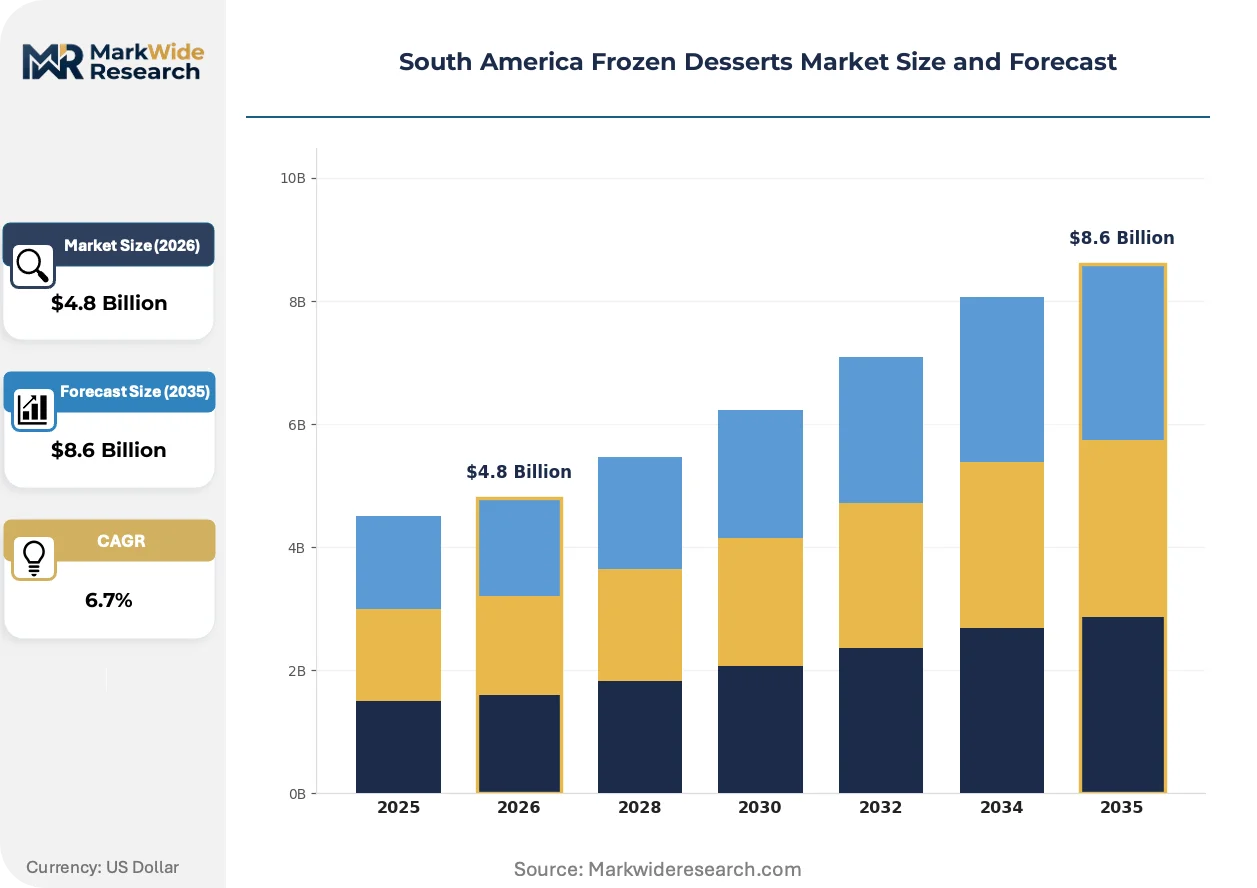
ANVISA's additive reformulation mandates are forcing simultaneous SKU proliferation and cold-chain recalibration across Brazil's frozen dessert supply base, compressing margin structures while elevating compliance barriers for cross-border trade.
Growth Catalysts
- Supermarket Channel Expansion:Brazilian retail chains are dedicating expanded freezer bay space to frozen yogurt and gelato formats, widening urban access beyond traditional ice cream parlors.
- ANVISA Harmonization Trajectory:Pending Mercosur regulatory convergence talks are creating anticipatory investment windows for manufacturers pre-positioning flexible formulation platforms.
- Urban Health Positioning:Frozen yogurt velocity is accelerating in São Paulo and Rio de Janeiro metropolitan corridors as portion-controlled indulgence aligns with wellness-oriented consumption.
Market Restraints
- Dairy Input Volatility:Milk fat and milk solids price swings in Argentina's inflation-pressured economy destabilize cost forecasting for dairy-based formulations.
- Cold-Chain Infrastructure Gaps:Last-mile refrigeration deficiencies in Colombia's secondary cities constrain gelato distribution beyond Bogotá and Medellín.
- Regulatory Fragmentation:Divergent additive approvals between ANVISA, INVIMA, and Senasa force country-specific SKU maintenance, eroding scale economies.
Strategic Opportunities
- Andean Premium Tier Development:Colombia's secondary urban centers present underexploited terrain for artisan gelato positioning above standard ice cream price bands.
- Plant-Based Formulation Convergence:Coconut cream and oat milk technologies are opening clean-label pathways for lactose-intolerant demographics across Brazil.
- Convenience Channel Penetration:Petrol station freezer networks in Argentina's Route 2 corridor offer impulse-purchase access beyond traditional grocery.
Industry Challenges
- Refrigeration Technician Scarcity:Qualified service personnel for industrial blast freezing equipment are concentrated in São Paulo, leaving regional production facilities exposed to downtime risk.
- Reformulation Timeline Compression:ANVISA's accelerated compliance deadlines for stabilizer substitutions are forcing simultaneous R&D and manufacturing line revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Frozen Desserts Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream, Sorbet, Frozen Yogurt, Gelato Flavor Profile: Chocolate, Vanilla, Strawberry, Mango Packaging Type: Cups, Tubs, Bars, Pints Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service |
| Companies Covered | Nestlé S.A., Unilever, Grupo Nutresa, Arcor, Creme Mel Sorvetes, Dunkin' Brands Group, Inc., General Mills Inc., Chiquinho Ice Cream, Colombina S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Frozen Desserts Market Evolving Landscape
Clean-label stabilizer systems and precision fermentation-derived dairy proteins are restructuring formulation pipelines, while digital cold-chain monitoring is compressing spoilage rates and enabling premium positioning.
Precision fermentation for whey protein and milk fat replication is electrifying R&D roadmaps at Brazilian and Argentine manufacturers. Mid-tier brands in São Paulo's metropolitan zone are piloting these ingredients to reduce dairy commodity exposure. The technology is electrifying competitive positioning by collapsing the cost gap between conventional and alternative protein formulations.
ANVISA's updated food additive positive list is mandating reformulation across imported and domestic frozen dessert portfolios. Manufacturers must substitute legacy stabilizers with approved alternatives or face import suspension. Brazilian supermarket private-label suppliers are responding fastest, leveraging local regulatory intelligence to accelerate compliance timelines.
Urban Brazilian consumers are consolidating frozen dessert purchases into weekly supermarket trips rather than daily convenience store visits. This channel rotation is compressing impulse-purchase velocity while rewarding larger-format, multi-serve packaging. São Paulo's southeastern corridor exhibits the most pronounced shift, with hypermarket freezer sections capturing gelato occasions previously served by street vendors.
South America Frozen Desserts Market Segmentation
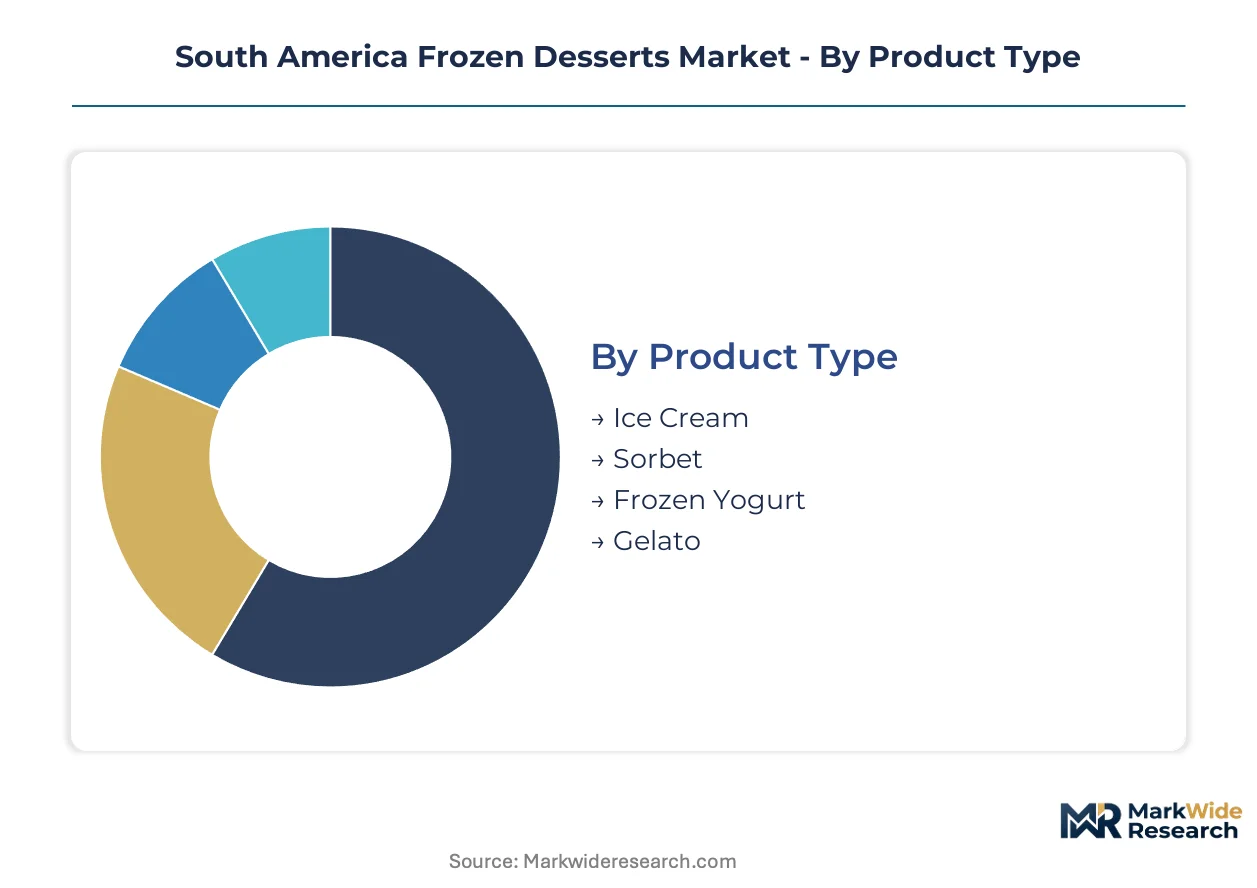
Frozen dessert segmentation across South America reflects divergent formulation technologies, consumption occasions, and cold-chain capabilities. Manufacturers must align product architecture with ANVISA compliance requirements while capturing distinct urban consumption patterns in São Paulo, Rio de Janeiro, and Bogotá.
Product Type:
Formulation technology determines overrun targets, fat content specifications, and stabilizer requirements across the category.
- Ice Cream:Dairy-based formulations with 10-16% milk fat content and 80-100% overrun deliver the creamiest mouthfeel. São Paulo's supermarket chains dedicate premium freezer bay space to multi-serve tubs, though ANVISA's revised additive standards are forcing stabilizer reformulation across domestic and imported portfolios.
- Frozen Yogurt:Cultured dairy bases with live probiotic claims and 4-6% milk fat target health-positioned urban demographics. Rio de Janeiro's metropolitan corridor shows the strongest velocity for portion-controlled cups as wellness-oriented consumption displaces traditional ice cream occasions.
- Sorbet:Water-based formulations with fruit puree concentrations above 25% and zero dairy fat serve lactose-intolerant and vegan-positioned demand.
- Gelato:Italian-style dense formulations with 4-8% milk fat and 20-35% overrun concentrate in Bogotá and Medellín specialty retail accounts.
Ice cream leads on scale; frozen yogurt leads on momentum.
Flavor Profile:
Raw material sourcing geography and local agricultural output shape flavor availability and cost structures across the continent.
- Chocolate:Cocoa butter and cocoa powder formulations depend on West African and Ecuadorian supply chains. Brazilian manufacturers face input cost pressure from currency volatility, though São Paulo's industrial chocolate processors maintain regional formulation leadership.
- Vanilla:Bourbon and Tahitian extract varieties command premium positioning in Colombian urban centers. Bogotá's specialty gelato shops favor Madagascar-sourced beans for clean-label positioning above synthetic vanillin alternatives.
- Strawberry:Seasonal Argentine and Chilean fruit puree supplies concentrate production in the Southern Cone months.
- Mango:Tropical fruit formulations leverage Brazilian Northeast harvests and Peruvian export volumes for sorbet and gelato applications.
Chocolate dominates volume throughput; mango claims the steepest expansion trajectory.
Packaging Type:
Cold-chain integrity requirements and consumption occasion fragmentation drive format diversification.
- Tubs:Multi-serve polyethylene containers from 500ml to 2L maximize household pantry stocking efficiency. Brazilian hypermarkets are expanding private-label tub offerings as weekly shopping trips displace daily convenience purchases.
- Cups:Single-serve polystyrene and paperboard formats with domed lids target impulse and food-service channels. Argentina's petrol station freezer networks favor 100-150ml cups for Route 2 corridor travelers.
- Bars:Stick-mounted formats with chocolate coating or fruit shell exteriors require specialized enrobing equipment.
- Pints:473ml glass and plastic containers occupy premium positioning in Colombian specialty retail.
Tubs anchor mass-market penetration; cups drive channel expansion.
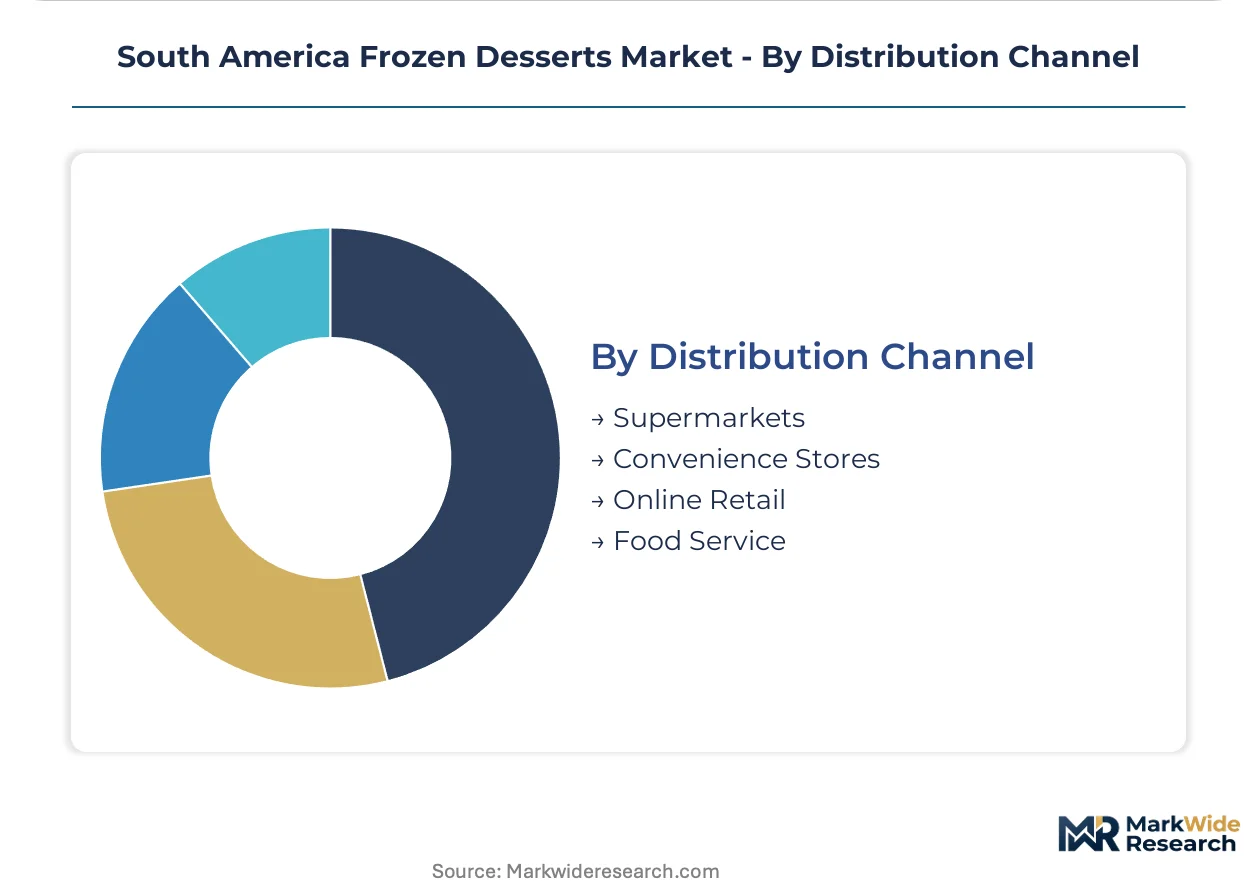
Distribution Channel:
Refrigeration infrastructure maturity and consumer trip consolidation patterns determine channel economics.
- Supermarkets:Expanded freezer sections in São Paulo's southeastern corridor now capture gelato occasions previously served by street vendors. Carrefour and GPA chains are dedicating 15-20% more linear footage to frozen yogurt and premium ice cream formats.
- Convenience Stores:Limited freezer capacity and higher per-unit operating costs concentrate on high-velocity impulse bars and cups. Rio de Janeiro's urban density supports 24-hour convenience penetration, though velocity is compressing as weekly supermarket trips rise.
- Online Retail:Insulated packaging and same-day cold-chain delivery pilot programs target affluent São Paulo households.
- Food Service:Upscale restaurant and hotel accounts in Bogotá and Medellín drive artisan gelato portioning.
Supermarkets command volume concentration; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled refrigeration technicians and food formulation chemists concentrate in São Paulo's industrial corridor, anchoring production capacity for the broader continent. This talent distribution shapes where cold-chain infrastructure scales fastest and where regulatory compliance expertise clusters.
Brazil
Supermarket freezer expansion in São Paulo and Rio de Janeiro drives gelato and frozen yogurt velocity among urban wellness demographics. ANVISA's additive reformulation mandates force simultaneous SKU proliferation and manufacturing line revalidation across domestic and imported portfolios. The southeastern corridor from São Paulo to Rio anchors national consumption, with hypermarket chains capturing occasions previously served by street vendors.
Argentina
Milk fat price volatility in Buenos Aires and Córdoba provinces destabilizes cost forecasting for dairy-based formulations amid persistent inflation. Senasa enforces additive approval standards that diverge from Mercosur neighbors, forcing country-specific SKU maintenance. Route 2 corridor petrol stations present underexploited impulse-purchase terrain for single-serve cups targeting domestic travelers.
Colombia
Bogotá and Medellín specialty retail accounts drive artisan gelato demand above standard ice cream price bands. INVIMA's nutritional labeling mandates fragment product standardization with Brazilian and Argentine regulatory regimes. Cold-chain gaps in secondary cities beyond the capital constrain distribution reach for premium frozen formats requiring strict temperature maintenance.
Chile
Santiago's metropolitan concentration supports sophisticated supermarket freezer infrastructure for imported premium ice cream portfolios. The country's national food safety regulator maintains additive standards aligned more closely with European benchmarks than Mercosur neighbors. Southern fruit puree supplies from the O'Higgins and Maule regions anchor seasonal strawberry and berry formulation inputs.
South America Frozen Desserts Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-positioning bands. The market structure concentrates around multinational packaged food groups with existing cold-chain infrastructure and regional dairy processing networks. Three archetypes dominate: diversified nutrition conglomerates with multi-brand portfolios, Andean-focused distribution specialists, and Argentine price-competitive manufacturers. Capacity expansion and formulation platform flexibility represent the dominant competitive moves as regulatory compliance timelines compress.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever exemplify scale-driven players leveraging multi-brand portfolios and captive cold-chain infrastructure. Grupo Nutresa occupies a position as the Andean distribution anchor, while Arcor represents Argentine manufacturing competitiveness. These three names illustrate how geographic coverage and regulatory adaptation capabilities separate market participants.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Unilever |
| Grupo Nutresa |
| Arcor |
| Creme Mel Sorvetes |
| Dunkin' Brands Group, Inc. |
| General Mills Inc. |
| Chiquinho Ice Cream |
| Colombina S.A. |
| Others |
Value Network & Pricing Analysis
Milk fat futures volatility in Argentina's inflation-pressured economy cascades through formulation cost structures, compressing margins for dairy-based frozen desserts while amplifying price stratification between premium gelato tiers and economy ice cream lines across Brazilian and Colombian retail channels.
Pricing Analysis
The bundled service split separates base product pricing from cold-chain logistics fees, with manufacturers absorbing transport costs for supermarket direct delivery while charging premium markups for food-service accounts requiring specialized blast freezing. Price differentiation hinges on ANVISA compliance certification tiers and volume scale commitments, with private-label suppliers commanding flexibility that branded portfolios cannot match. Pricing pressure stems from stabilizer reformulation mandates elevating input costs. Economy-tier supermarket SKUs exhibit highest price sensitivity; artisan gelato in Bogotá specialty accounts shows lowest elasticity.
Supply Chain Analysis
Qualified refrigeration technicians and food formulation chemists concentrate in São Paulo's industrial corridor, leaving regional production facilities in Argentina's Córdoba province and Colombia's secondary cities exposed to equipment downtime risks. Raw material sourcing draws from Brazilian Northeast mango harvests, Argentine Southern Cone dairy cooperatives, and Ecuadorian cocoa butter processors. Supply chain risk centers on single-source vulnerability for precision fermentation-derived dairy proteins piloted by mid-tier São Paulo manufacturers. Distribution runs through supermarket chains with captive cold-chain infrastructure, supplemented by petrol station freezer networks along Argentina's Route 2 corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America frozen desserts market compounds steadily as urban health positioning in São Paulo and Rio de Janeiro metropolitan corridors sustains frozen yogurt velocity and premium gelato trial.
For Market Incumbents: Lock in formulation platform flexibility by pre-positioning clean-label stabilizer systems capable of rapid ANVISA compliance adaptation. Secure backward integration into captive dairy processing in Minas Gerais to buffer Argentina's milk fat price volatility. Channel control through expanded supermarket freezer bay commitments protects against convenience store velocity compression. For New Entrants and Emerging Players: ANVISA's pending Mercosur harmonization talks in Brazil open a window for plant-based formulation specialists to capture lactose-intolerant demand before incumbent R&D cycles complete. Target Colombia's secondary urban centers beyond Bogotá for artisan gelato white-space penetration. Route-to-market through petrol station freezer networks in Argentina's Route 2 corridor enables impulse-purchase trial with minimal capital deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Brazilian manufacturers piloting precision fermentation technologies that collapse alternative protein cost gaps. Five-to-ten-year viability favors acquisition targets with flexible formulation platforms and established ANVISA regulatory intelligence rather than pure distribution assets. Monitor Mercosur harmonization implementation timelines as inflection signal for regional SKU consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Stabilizer Reformulation | ANVISA compliance mandates force rapid R&D pivot across imported and domestic portfolios. |
| Precision Fermentation Scale-Up | Whey protein replication technology collapses cost gap for alternative dairy formulations in São Paulo. |
| Supermarket Freezer Bay Expansion | Carrefour and GPA chains capture gelato occasions previously served by street vendors. |
| Plant-Based Product Line Extension | Coconut cream and oat milk pathways unlock lactose-intolerant segments across Brazilian urban demographics. |
| Petrol Station Channel Penetration | Route 2 corridor freezer networks enable impulse access beyond traditional grocery in Argentina. |
Research Methodology
Bottom-up supermarket and food-service channel modeling reconciled against top-down cold-chain infrastructure tracking forms the analytical core of this study. Primary interviews with category buyers at Brazilian retail chains, formulation chemists at Argentine dairy processors, ANVISA regulatory consultants, and logistics directors at regional cold-storage operators combined with secondary validation. Trade data from Brazilian customs records, INVIMA additive approval filings, Nielsen retail audit data for frozen dessert velocity, and SEC filings from multinational packaged food groups enabled triangulation.
Historical trendline analysis across milk fat price indices, supermarket freezer space allocation patterns, and urban consumption occasion shifts informed projection parameters. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel complexity alongside regional regulatory cluster alignment. CAGRs derived from regression analysis against demographic urbanization rates and disposable income elasticity for indulgence categories. Forecast inputs incorporated ANVISA compliance timeline scenarios and precision fermentation cost curve assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Mercosur regulatory divergence or sustained Argentine inflationary pressure. Forecasts reflect documented assumptions about cold-chain infrastructure buildout rates and stabilizer substitution technology maturation. Material deviation in ANVISA implementation timelines or dairy commodity volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Ice Structuring Protein Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Middle East and Africa Ice Cream Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Europe Ice Cream Market