
 Frozen Cheese Market | 2026-2036
Frozen Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Cheese Market Foresight
A shortage of cold-chain logistics specialists is unwinding throughput capacity at major dairy distribution hubs. Leprino Foods Company leverages its captive milk supply network to secure raw material continuity. Fonterra Co-operative Group Limited anchors its competitive position through integrated processing from farm to frozen block. Saputo Inc. specializes in shredded mozzarella formats for North American pizza chains.
Frozen cheese denotes cheese products blast-frozen at temperatures below minus eighteen degrees Celsius to arrest microbial activity and preserve functional melt characteristics for industrial food preparation. The category serves primarily as a standardized ingredient input where portion control, shelf stability, and consistent performance under thermal processing outweigh fresh-product premiums. Mozzarella occupies the dominant volume position due to pizza-sector pull, while shredded form commands the widest foodservice penetration because of labor-cost savings in commercial kitchens. Quick service restaurants represent the fastest-expanding application channel as chains centralize procurement through frozen-dedicated distributors.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that govern pathogen controls across frozen cheese production, while USDA grading programs certify compositional benchmarks that determine eligibility for institutional contracts. State-level dairy plant licensing in Wisconsin and California adds further compliance layers that shape regional manufacturing siting decisions. Stakeholders must monitor evolving clean-label demands against the technical necessity of cryoprotectant additives and modified-atmosphere packaging systems.
Market Dynamics
Quick service restaurant chains are consolidating procurement through frozen-dedicated distributors, concentrating volume purchasing power and compressing supplier margins across the frozen cheese supply base.
Growth Catalysts
- FDA Pasteurization Mandates:The FDA's updated Grade A Pasteurized Milk Ordinance standards are accelerating facility upgrades that favor large-scale frozen cheese processors with capital reserves for compliance infrastructure.
- Pizza-Sector Standardization:National pizza chains are mandating frozen shredded mozzarella to eliminate kitchen labor variability and ensure consistent melt performance across franchise locations.
- Blast-Freezing Technology:Advanced cryogenic tunnel systems are extending shelf stability beyond twenty-four months, opening institutional contract opportunities previously reserved for canned or dried alternatives.
Market Restraints
- Milk Supply Concentration:Captive dairy farm networks in Wisconsin and California limit independent processor access to Grade A raw milk during seasonal shortfalls.
- Cryoprotectant Additive Costs:Phosphate-based moisture retention compounds face price volatility tied to phosphate rock mining output and export restrictions.
- Fresh Cheese Substitution:Artisan pizzerias in metropolitan markets are rejecting frozen formats despite higher per-unit costs, fragmenting the addressable foodservice base.
Strategic Opportunities
- Plant-Based Cheese Convergence:Hybrid frozen products combining dairy and fermented protein isolates are capturing flexitarian consumers in California and New York foodservice trials.
- School Nutrition Programs:USDA National School Lunch Program commodity cheese specifications favor frozen block formats with extended holding capacity for district-level distribution.
- Direct-to-Operator E-Commerce:Specialized frozen cheese distributors are launching digital procurement platforms that bypass traditional broadline foodservice intermediaries.
Industry Challenges
- Cold-Chain Technician Scarcity:Refrigeration mechanics certified for ultra-low temperature blast freezer maintenance command wage premiums that inflate distribution hub operating costs.
- Multi-Jurisdictional Licensing:Dairy plant operators must maintain parallel state licenses in Wisconsin, California, and New York, each with distinct inspection cadences and documentation requirements.
- Modified-Atmosphere Packaging Validation:Nitrogen flush systems require extended shelf-life testing protocols that delay new product introductions by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Cheese Market |
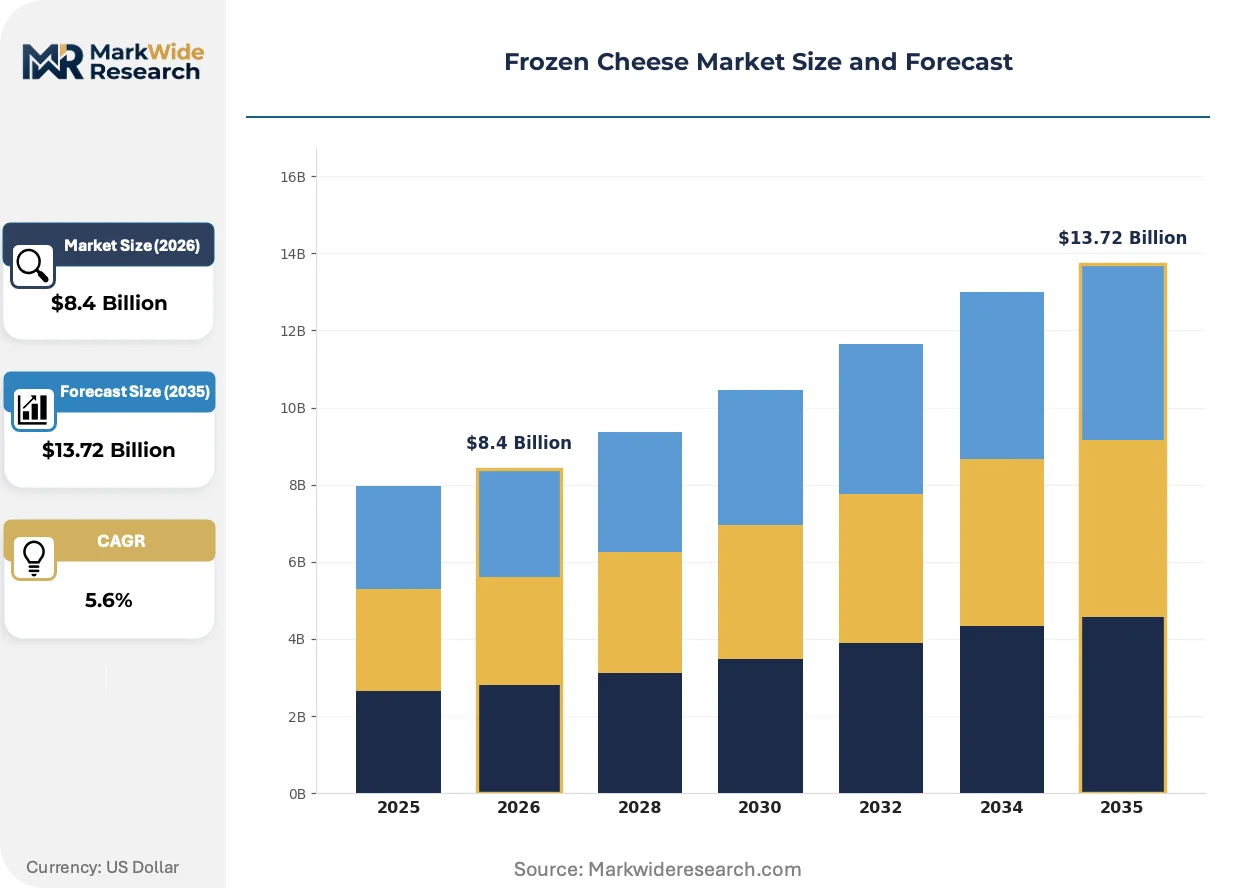
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mozzarella, Cheddar, Parmesan, Swiss, Provolone Form: Shredded, Sliced, Block, Cubed, Crumbled Application: Pizzerias, Food Processing, Quick Service Restaurants, Catering Services, Frozen Food Manufacturers End User: Foodservice Operators, Dairy Product Manufacturers, Gourmet Retailers, Institutional Buyers |
| Companies Covered | Granarolo S.p.A., Leprino Foods Company, Fonterra Co-operative Group Limited, Saputo Inc., Arla Foods, Lactalis Ingredients, Dairy Farmers of America, Schreiber Foods, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Cheese Market Shifts & Advancements
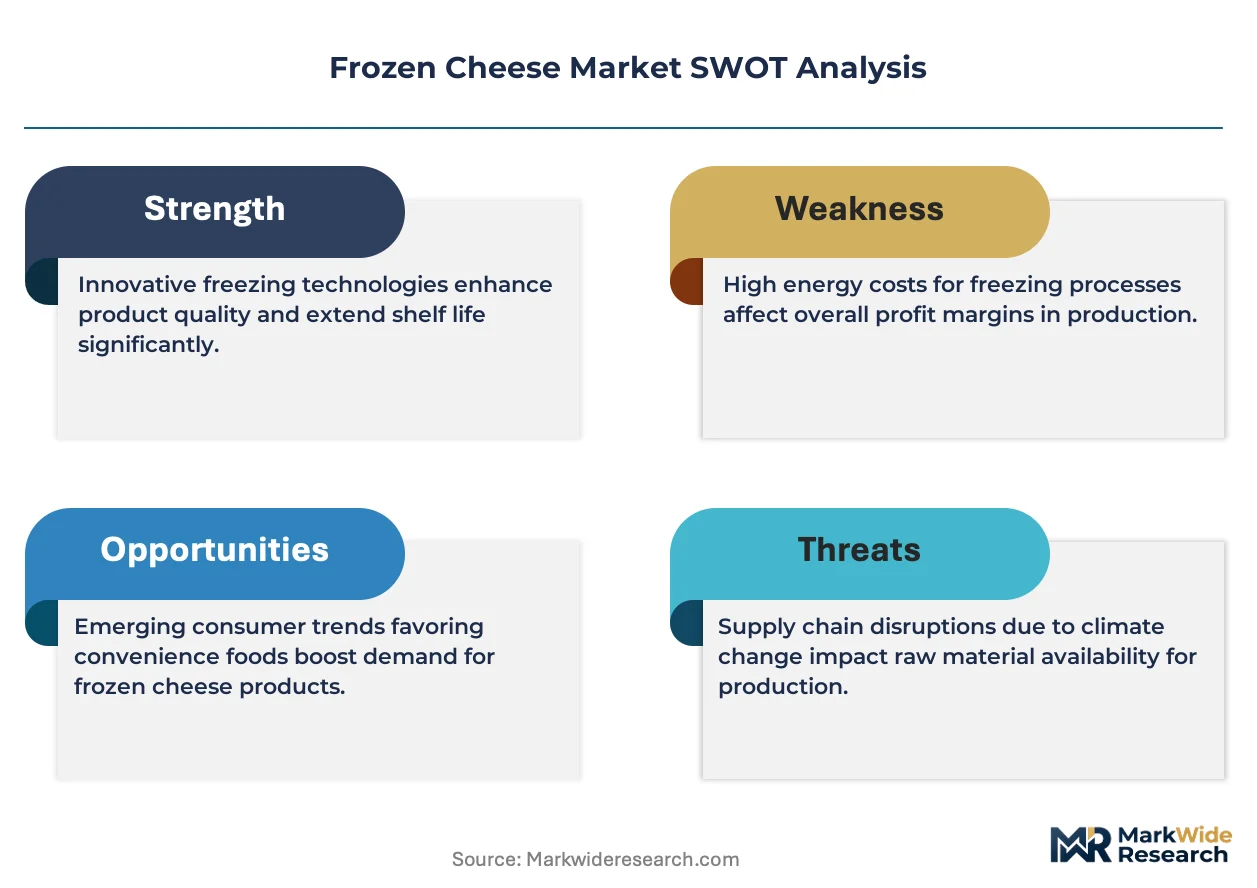
Functional ingredient engineering and regulatory compliance automation are redefining competitive advantage in frozen cheese manufacturing, separating capital-intensive operators from commodity processors.
High-pressure processing technology is displacing traditional thermal pasteurization in premium frozen cheese lines. Artisan pizza chains in the Northeast are adopting HPP-treated mozzarella for extended refrigerated holding prior to freezing, preserving native protein structures that conventional heat treatment degrades. This shift is compressing the technical gap between frozen and fresh cheese performance metrics.
EU F-Gas Regulation phase-down schedules are forcing refrigeration system retrofits across European frozen cheese storage facilities. Industrial cold stores in Italy and Germany are replacing hydrofluorocarbon-based cooling with ammonia-CO2 cascade systems, adding capital recovery timelines to operating cost models. Frozen cheese exporters serving EU institutional buyers must document facility compliance to maintain contract eligibility.
Centralized procurement desks at multi-unit restaurant operators are consolidating supplier relationships into single-source frozen cheese agreements. Broadline distributors are losing share to specialized dairy logistics providers with dedicated frozen infrastructure. This concentration is most visible in the US Southeast, where regional pizza chains are bypassing legacy foodservice intermediaries entirely.
Frozen Cheese Market Segmentation
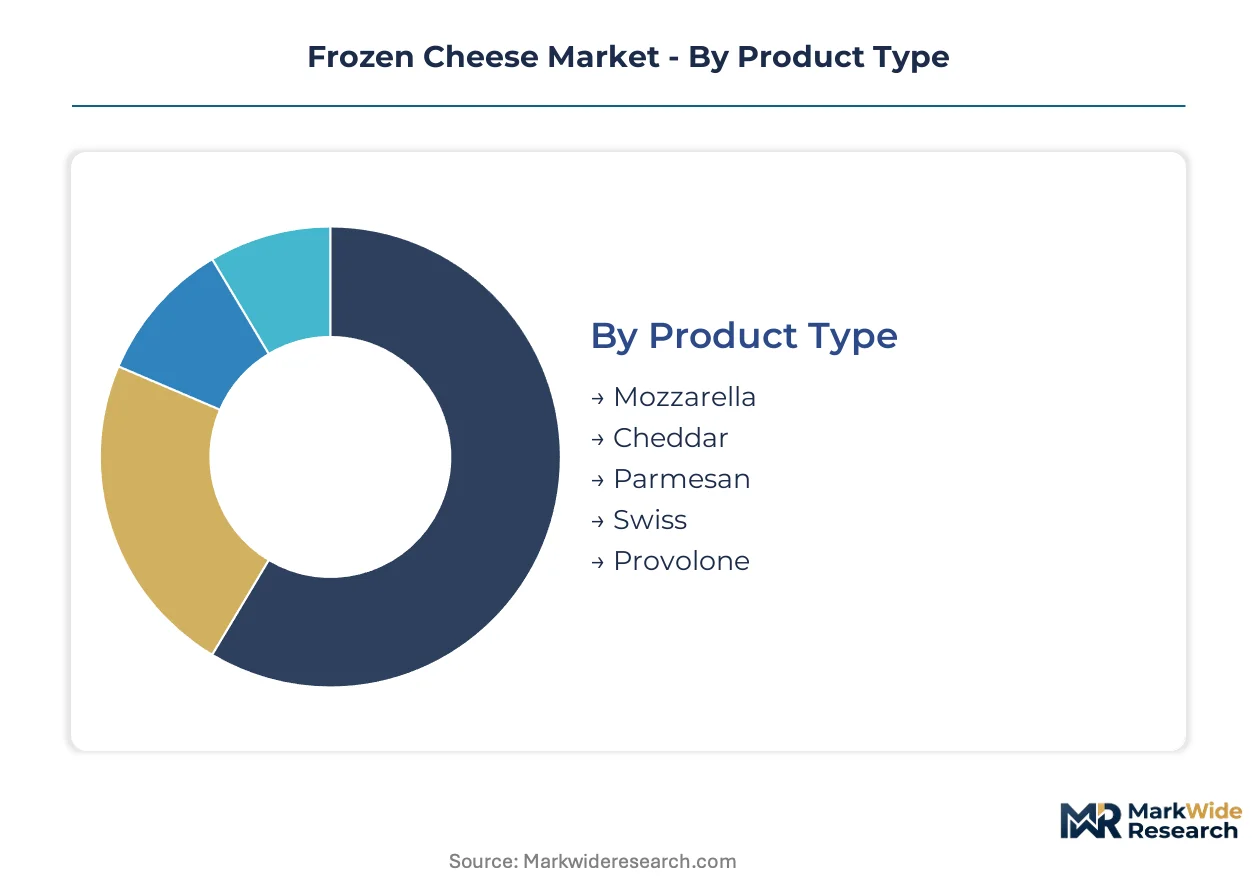
Frozen cheese segmentation determines procurement routing and margin capture across the supply chain. Channel configuration varies sharply by product format and end-user scale, with institutional buyers and quick service restaurants driving divergent packaging and logistics requirements.
Product Type:
Mozzarella and cheddar move through frozen-dedicated distributors into high-volume foodservice, while specialty varieties channel through gourmet retail and regional Italian food processors.
- Mozzarella:Low-moisture part-skim formulations dominate pizza-sector procurement. Quick service restaurants in the United States specify frozen shredded mozzarella for operational consistency across franchise networks.
- Cheddar:Aged and medium profiles serve processed food manufacturers and institutional buyers. Wisconsin and California production clusters supply Grade A blocks to frozen food processors requiring standardized melt behavior.
- Parmesan:Grana-style hard cheeses freeze with minimal texture degradation. Italian exporters and domestic Wisconsin processors supply foodservice distributors serving white-tablecloth pizzerias.
- Swiss:Eye-formation stability under blast-freezing remains technically challenging. Limited processors maintain commercial-scale output for sandwich manufacturing and airline catering contracts.
- Provolone:Smoked and unsmoked variants serve Philadelphia-style sandwich chains and Midwest pizza operators. Regional dairy cooperatives control captive supply of this lower-volume specialty.
Mozzarella dominates installed base. Cheddar is where expansion concentrates.
Form:
Labor-cost differentials between commercial kitchens and industrial processors determine format preference, with shredded commanding foodservice premiums and block formats serving manufacturing economies.
- Shredded:Pre-portioned bags eliminate kitchen labor and reduce waste variability. National pizza chains mandate this format for franchise standardization, with nitrogen-flush packaging extending shelf stability.
- Block:Twenty-pound frozen blocks serve industrial reprocessors and school nutrition programs. USDA commodity specifications favor this format for district-level distribution and extended holding capacity.
- Sliced:Deli-thin and sandwich-weight profiles target quick service burger chains and airline catering. Modified-atmosphere packaging requirements delay new product introductions.
- Cubed:Salad bar and buffet applications drive modest volume. Foodservice distributors stock this format for institutional accounts and hospitality sector contracts.
- Crumbled:Blue cheese and feta derivatives serve salad kit manufacturers and gourmet retail. Higher per-unit pricing reflects processing complexity and niche demand concentration.
Block formats anchor manufacturing procurement. Shredded is gaining share fastest in commercial foodservice.
Application:
Scale requirements and technical specifications fragment the addressable market, with pizzerias demanding melt-performance consistency and food processors prioritizing ingredient handling efficiency.
- Quick Service Restaurants:Centralized procurement desks consolidate frozen cheese purchasing into single-source agreements. Chains bypass broadline distributors for specialized dairy logistics providers with dedicated frozen infrastructure.
- Pizzerias:Independent operators and regional chains specify frozen mozzarella for cost predictability. Artisan pizzerias in metropolitan markets reject frozen formats despite higher per-unit costs.
- Food Processing:Frozen cheese inputs serve frozen entree manufacturers and prepared meal producers. Compositional specifications govern eligibility for institutional contracts.
- Frozen Food Manufacturers:Pizza roll, pocket sandwich, and macaroni-and-cheese producers require precise shred dimensions and moisture retention. Phosphate-based cryoprotectant additives face price volatility.
- Catering Services:Event and airline catering demand portion-controlled formats with extended thaw stability. Cold-chain technician scarcity inflates distribution hub operating costs.
Quick service restaurants drive volume concentration. Frozen food manufacturers represent the steepest expansion trajectory.
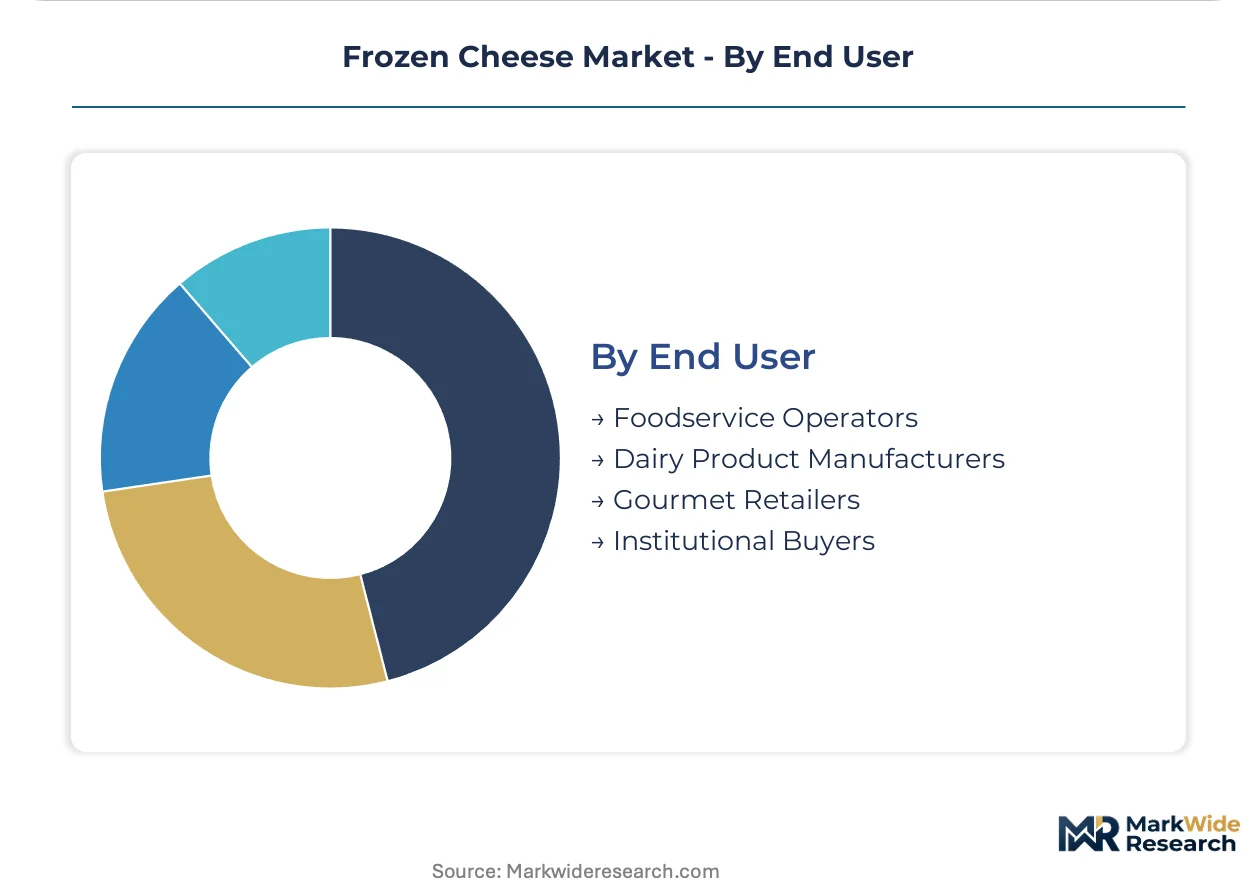
End User:
Procurement authority and technical sophistication vary across buyer types, with institutional buyers leveraging specification power and gourmet retailers commanding premium positioning.
- Foodservice Operators:Multi-unit restaurant groups consolidate volume purchasing power. Specialized frozen cheese distributors are launching digital procurement platforms that bypass traditional broadline intermediaries.
- Institutional Buyers:School districts and healthcare systems specify USDA-graded frozen block formats. Extended holding capacity requirements favor blast-frozen products with twenty-four-month shelf stability.
- Dairy Product Manufacturers:Reprocessors blend frozen cheese inputs into formulated products. Wisconsin and California plant licensing requirements shape regional manufacturing siting decisions.
- Gourmet Retailers:Specialty food stores and high-end grocers stock premium frozen mozzarella for home pizza preparation. High-pressure processing technology is displacing traditional thermal pasteurization in this channel.
Foodservice operators concentrate procurement volume. Gourmet retailers are expanding most quickly as home meal preparation trends shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pasteurization mandates anchor the United States as the dominant geography, with Wisconsin and California dairy clusters driving frozen cheese production capacity. Quick service restaurant procurement consolidation concentrates volume purchasing power in this market. European and Asia-Pacific markets follow distinct regulatory and demand trajectories.
United States
Quick service restaurant chains and national pizza operators drive frozen mozzarella procurement at scale. The FDA enforces Grade A Pasteurized Milk Ordinance standards that govern pathogen controls across production facilities. Wisconsin dairy plants and California Central Valley processors supply Grade A blocks to frozen food manufacturers requiring standardized melt behavior.
Italy
Grana-style hard cheese exports and artisan pizza chain demand sustain frozen parmesan volumes. EU F-Gas Regulation phase-down schedules force refrigeration system retrofits across cold storage facilities in Lombardy and Emilia-Romagna. Italian exporters serving EU institutional buyers must document ammonia-CO2 cascade system compliance to maintain contract eligibility.
Germany
Industrial cold stores and prepared meal manufacturers anchor frozen cheese distribution throughput. ECHA chemical safety protocols and EU packaging waste directives shape modified-atmosphere packaging validation requirements. Bavaria and North Rhine-Westphalia dairy logistics hubs face technician scarcity for ultra-low temperature blast freezer maintenance.
China
Western-style pizza chain expansion and frozen food manufacturing growth accelerate mozzarella import demand. SAMR dairy import licensing and GB food safety standards govern cold-chain compliance for foreign suppliers. Yangtze River Delta cold storage clusters in Shanghai and Jiangsu province handle bulk frozen cheese re-exports to Southeast Asian markets.
Australia
Foodservice distributor consolidation and institutional catering contracts sustain frozen block format demand. FSANZ dairy processing standards and state-level dairy plant licensing add compliance layers that shape manufacturing siting. Victoria and New South Wales dairy cooperatives supply frozen cheddar to Southeast Asian export markets.
Frozen Cheese Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the frozen cheese supply base. Large-scale dairy cooperatives with captive milk supply networks dominate volume production, while specialized mozzarella processors command foodservice premiums through format innovation. Strategic archetypes include vertically integrated dairy cooperatives, frozen-dedicated ingredient specialists, and broadline dairy processors diversifying into blast-frozen formats. Competitive moves center on cold-chain infrastructure expansion and direct-to-operator digital procurement platform launches.
Among North American dairy processors, Leprino Foods Company, Saputo Inc., and Dairy Farmers of America exemplify distinct strategic positions. Leprino Foods occupies a position anchored by captive milk supply network control. Saputo Inc. represents the frozen-dedicated ingredient specialist archetype with shredded format concentration. Dairy Farmers of America exemplifies cooperative-scale procurement consolidation. Fonterra Co-operative Group Limited and Arla Foods anchor the cooperative exporter segment serving institutional buyers across multiple geographies.
| Leading Market Players |
|---|
| Granarolo S.p.A. |
| Leprino Foods Company |
| Fonterra Co-operative Group Limited |
| Saputo Inc. |
| Arla Foods |
| Lactalis Ingredients |
| Dairy Farmers of America |
| Schreiber Foods |
| Kraft Heinz Company |
| Others |
Supply & Pricing Matrix
Phosphate-based cryoprotectant substitution for traditional moisture retention compounds is redrawing ingredient sourcing maps toward North African phosphate rock deposits while simultaneously compressing margin structures for frozen cheese processors facing export restriction volatility.
Pricing Analysis
Price spreads between Wisconsin-origin frozen mozzarella blocks and California Central Valley equivalents widen during seasonal milk supply contractions, reflecting captive dairy network premiums. Pricing stratifies across premium HPP-treated, standard blast-frozen, and economy-grade thermal-pasteurized tiers. Cost compression in the economy tier is intensifying because quick service restaurant procurement desks are consolidating volume into single-source agreements. Independent pizzerias exhibit highest price sensitivity, while national pizza chains prioritize melt-performance consistency over per-unit cost.
Supply Chain Analysis
Frozen cheese inventory cycles stretch to twenty-four months for nitrogen-flush shredded formats, compressing working capital turns for distributors. Supply concentrates in the United States, Italy, and New Zealand, with Wisconsin and California dairy clusters anchoring North American capacity. Raw milk, phosphate additives, and modified-atmosphere packaging films constitute critical input dependencies. Single-source vulnerability runs through the Yangtze River Delta cold storage cluster handling Southeast Asian re-exports. Distribution runs through frozen-dedicated dairy logistics providers bypassing legacy broadline intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen cheese operates as a regulatory-moat market where FDA Grade A Pasteurized Milk Ordinance compliance entrenchment creates switching costs that lock institutional buyers into validated supplier relationships.
For Market Incumbents: Secure captive milk supply continuity through backward integration into Wisconsin and California dairy farm networks before seasonal shortfalls intensify. Expand blast-freezer capacity at existing licensed facilities rather than navigating multi-jurisdictional state licensing for greenfield sites. Cold-chain technician scarcity threatens distribution hub throughput. For New Entrants and Emerging Players: Anchor in plant-based hybrid frozen cheese trials targeting California and New York flexitarian foodservice operators where conventional dairy processors lack formulation expertise. Direct-to-operator e-commerce platforms represent the most penetrable channel, bypassing entrenched broadline distributor relationships. Lead with USDA National School Lunch Program commodity certification to unlock institutional volume. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed frozen-dedicated ingredient specialists holding shredded format concentration but lacking captive milk supply. Five-to-ten year viability hinges on regulatory compliance automation capex deployment rather than commodity scale. Watch for FDA pasteurization mandate acceleration as inflection signal favoring capital-reserve holders.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Dedicated blast-freezer capacity at dairy hubs locks in quick service restaurant single-source contracts. |
| Backward Integration into Milk Supply | Wisconsin and California captive dairy networks insulate processors from Grade A raw milk seasonal volatility. |
| Regulatory Compliance Automation | FDA Pasteurized Milk Ordinance upgrade investments separate capital-intensive operators from commodity processors. |
| Direct-to-Operator E-Commerce Launch | Digital procurement platforms bypass legacy broadline intermediaries serving multi-unit restaurant groups. |
| Hybrid Plant-Based Product Development | Fermented protein isolate formulations capture flexitarian demand in California and New York foodservice trials. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the frozen cheese value chain, including quick service restaurant procurement directors, dairy plant operations managers, cold-chain logistics coordinators, and institutional foodservice buyers. Secondary validation drew from FDA Grade A Pasteurized Milk Ordinance filings, USDA commodity cheese specification databases, state-level dairy plant licensing records, and customs trade data for frozen dairy exports. Bottom-up volume modeling triangulated against top-down expenditure analysis across foodservice and institutional end-use segments.
Across the analysis window, projections integrated product type segmentation by mozzarella, cheddar, and specialty varieties; form factor differentiation between shredded, block, and sliced formats; and application channel splits across quick service restaurants, pizzerias, and frozen food manufacturers. CAGRs were derived from historical trajectory analysis adjusted for regulatory catalyst timing and procurement consolidation patterns. Milk supply concentration indices and cryoprotectant additive cost volatility served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA pasteurization enforcement and quick service restaurant procurement centralization; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Frozen Chicken Market