
 Europe Lobster Market | 2026-2036
Europe Lobster Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lobster Market Intelligence
MSC Chain of Custody certification is bifurcating the Europe lobster supply base into credentialed and non-credentialed tiers. Royal Greenland leverages its Arctic vertical integration to sustain year-round live shipments into Continental Europe. Clearwater Europe Ltd. competes through controlled-atmosphere logistics that extend shelf life across its distribution network.
Europe lobster comprises decapod crustaceans of the family Nephropidae, distinguished by a rigid exoskeleton, five pairs of walking legs with enlarged chelae, and a muscular abdomen valued for its dense protein content exceeding eighteen percent by weight; the species serves premium food service and retail channels requiring live, fresh, or frozen preservation states. Homarus gammarus dominates landed volume in European waters, though spiny lobster imports from warmer fisheries anchor margin pools in Mediterranean markets. Frozen packaging controls working-capital efficiency for wholesalers, while live handling commands price premiums in restaurant-directed channels.
EU Common Fisheries Policy quotas and EFSA food safety standards govern harvest volumes and cold-chain hygiene protocols, with national regulators in Norway and Iceland layering additional catch documentation requirements. Ecolabelling under the Marine Stewardship Council shapes procurement eligibility for major retail banners across Germany and the United Kingdom. Stakeholders must monitor quota negotiations and certification renewal cycles to secure supply continuity.
Market Dynamics
MSC Chain of Custody certification is splitting European lobster procurement into parallel supply tiers, with credentialed Arctic and North Atlantic sources commanding preferential access to German and UK retail banners while uncertified Mediterranean landings face channel exclusion.
Growth Catalysts
- Premium restaurant expansion:French and Spanish hospitality groups are enlarging live lobster tank installations across coastal dining corridors from Barcelona to Marseille.
- EFSA cold-chain protocols:Harmonized hygiene standards across EU member states are reducing cross-border friction for fresh and frozen consignments.
- Controlled-atmosphere logistics:Modified packaging systems are extending shelf life for live shipments reaching inland distribution nodes.
Market Restraints
- Quota compression:EU Common Fisheries Policy harvest limits constrain Homarus gammarus landings in traditional North Atlantic fishing zones.
- Input cost volatility:Diesel and ice expenses for vessel operations fluctuate with North Sea energy pricing.
- Spiny lobster substitution:Warm-water Palinuridae imports from Atlantic African fisheries erode margin pools in Mediterranean wholesale channels.
Strategic Opportunities
- Norwegian regulatory layering:Oslo's catch documentation requirements create premium positioning for documented-origin product in Continental Europe.
- Direct-to-chef platforms:Digital procurement interfaces are bypassing traditional wholesale auctions for restaurant-directed live supply.
- CE marking convergence:Processing equipment harmonization under EU machinery directives reduces capital barriers for value-added product lines.
Industry Challenges
- Live-handling expertise scarcity:Qualified tank management personnel for long-haul transport remain concentrated in Brittany and Galicia.
- MSC audit timeline compression:Certification renewal cycles demand continuous chain-of-custody documentation across multi-handler logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lobster Market |
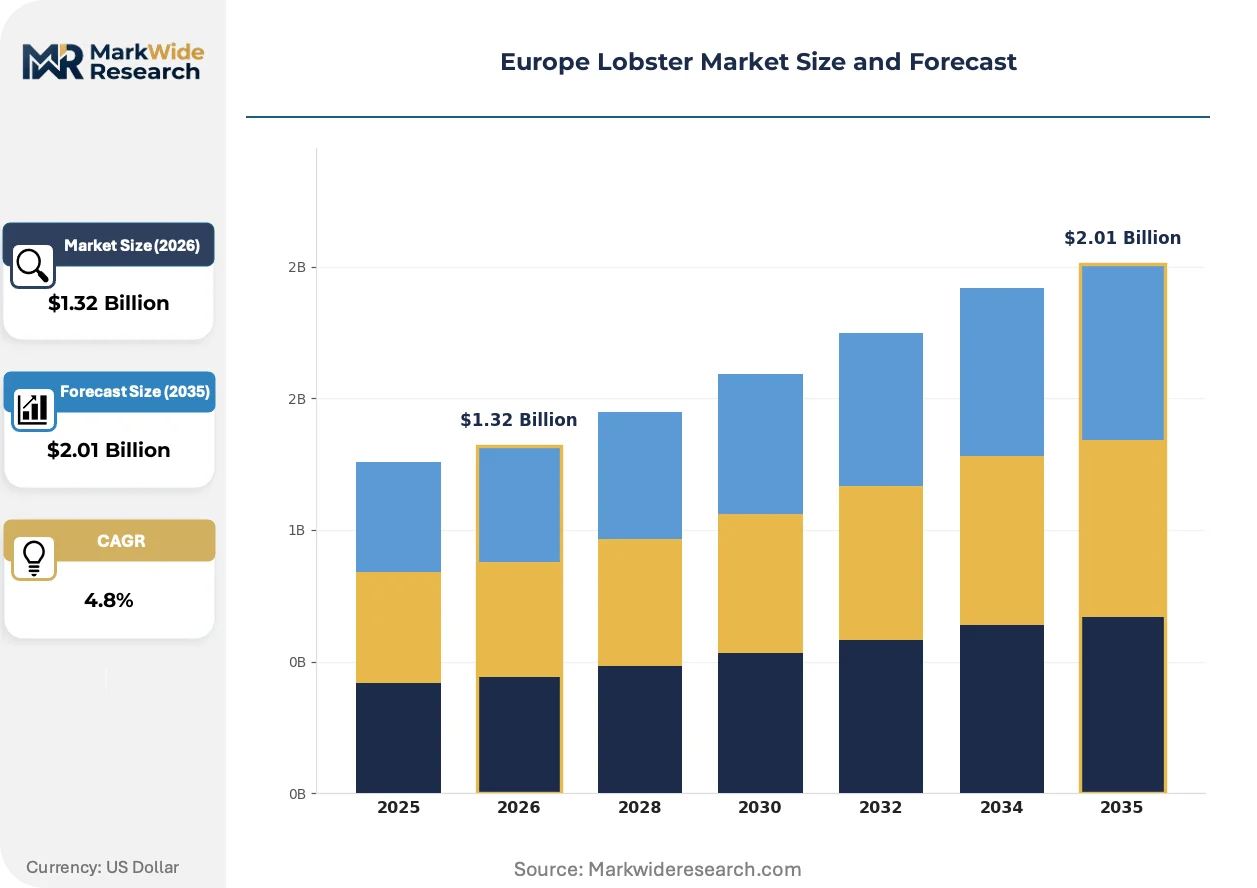
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.01 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homarus gammarus, Homarus americanus, Spiny Lobster, Rock Lobster Distribution Channel: Retail, Wholesale, E-commerce, Food Service Packaging Type: Live, Frozen, Canned, Processed End User: Restaurants, Households, Retailers, Seafood Markets |
| Companies Covered | Fylkir Seafood, Austevoll Seafood ASA, Blue Lobster Company, Grieg Seafood ASA, Mowi ASA, Royal Greenland, Northbay Seafood, Iceland Seafood International, Clearwater Europe Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lobster Market Strategic Shifts & Innovations
Live-lobster supply chains are adopting sensor-enabled traceability systems that track temperature and mortality risk across multimodal journeys from trap to tank.
Recirculating aquaculture systems for temporary holding are displacing flow-through seawater tanks in major European distribution hubs. Wholesale operators in Rotterdam and Hamburg are retrofitting facilities with biofiltration and oxygen injection. This technology is displacing conventional open-system architecture that required continuous seawater exchange and limited inland positioning.
EU Green Deal sustainability reporting under CSRD is mandating carbon footprint disclosure for seafood procurement. Large retail banners in Germany and the United Kingdom must now document fuel and refrigeration emissions across their lobster supply chains. Nordic processors are responding with vessel electrification pilots and shore-power cold storage.
Chef-direct procurement is consolidating purchase authority away from traditional wholesale auctions. High-end restaurants in Paris and Madrid now contract directly with Icelandic and Norwegian fishing cooperatives for scheduled live deliveries. This pattern concentrates volume with vertically integrated Arctic suppliers while Mediterranean auction houses face volume attrition.
Europe Lobster Market Segmentation
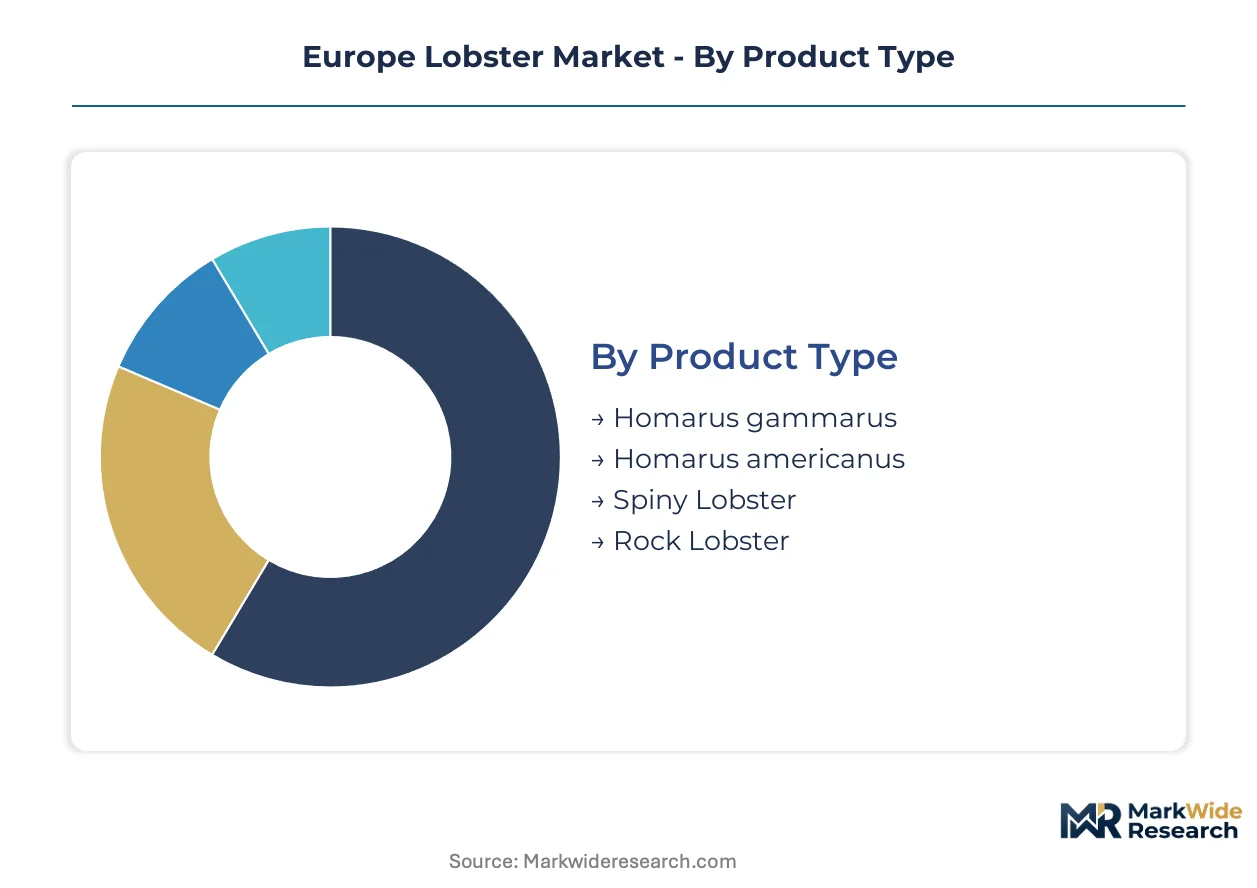
European lobster procurement splits along regulatory compliance lines, with EFSA cold-chain protocols and MSC certification eligibility determining channel access across member states. Segmentation reveals how premium live product commands distinct logistics infrastructure compared to frozen commodity flows.
Product Type:
EFSA traceability requirements and CITES appendices create divergent compliance burdens across species categories, shaping which products reach German retail banners versus Mediterranean wholesale channels.
- Homarus gammarus:The native European species carries stringent EU Common Fisheries Policy quota documentation and EFSA hygiene marking. French and Spanish premium restaurant chains along the Barcelona-Marseille corridor concentrate procurement of live-caught specimens with verified Brittany or Galicia landing documentation.
- Homarus americanus:North American imports compete through year-round availability and larger average carapace sizes. Norwegian catch documentation requirements create premium positioning for documented-origin transatlantic shipments entering Continental Europe through Rotterdam and Hamburg distribution nodes.
- Spiny Lobster:Warm-water Palinuridae from Atlantic African fisheries anchor margin pools in Mediterranean wholesale markets.
- Rock Lobster:Southern hemisphere imports supply frozen commodity demand in UK and German retail segments.
Homarus gammarus handles the majority of throughput; Homarus americanus is the fastest mover on share.
Distribution Channel:
Cost tier differentiation separates capital-intensive live-handling infrastructure from working-capital-efficient frozen distribution networks.
- Food Service:Direct-to-chef platforms bypass traditional wholesale auctions for scheduled live deliveries from Icelandic and Norwegian cooperatives. Paris and Madrid high-end restaurants contract vertically with Arctic suppliers, concentrating volume away from Mediterranean auction houses.
- Wholesale:Rotterdam and Hamburg operators retrofit facilities with recirculating aquaculture systems and biofiltration for temporary live holding. Modified atmosphere logistics extend shelf life for inland distribution nodes across Germany and Benelux.
- Retail:German and UK banners require MSC Chain of Custody certification for procurement eligibility under Ecolabelling standards.
- E-commerce:Digital interfaces emerge for chef-direct procurement and premium home delivery segments.
Wholesale channels carry the volume base; Food Service is expanding most quickly as procurement authority consolidates with restaurant groups.
Packaging Type:
Application requirements dictate preservation state, with live handling commanding tank infrastructure and frozen product optimizing inventory turnover.
- Live:Sensor-enabled traceability systems track temperature and mortality risk across multimodal journeys from trap to tank. Controlled-atmosphere packaging and oxygen injection systems enable long-haul transport to inland European markets.
- Frozen:Blast-freezing at sea and shore-power cold storage reduce carbon footprint disclosure burdens under EU Green Deal CSRD reporting for Nordic processors. Working-capital efficiency favors wholesale inventory management.
- Processed:Value-added product lines benefit from CE marking convergence under EU machinery directives.
- Canned:Shelf-stable formats serve retail mass-market segments with lower per-unit margins.
Frozen packaging dominates working-capital efficiency; Live handling captures the steepest expansion trajectory in premium channel penetration.
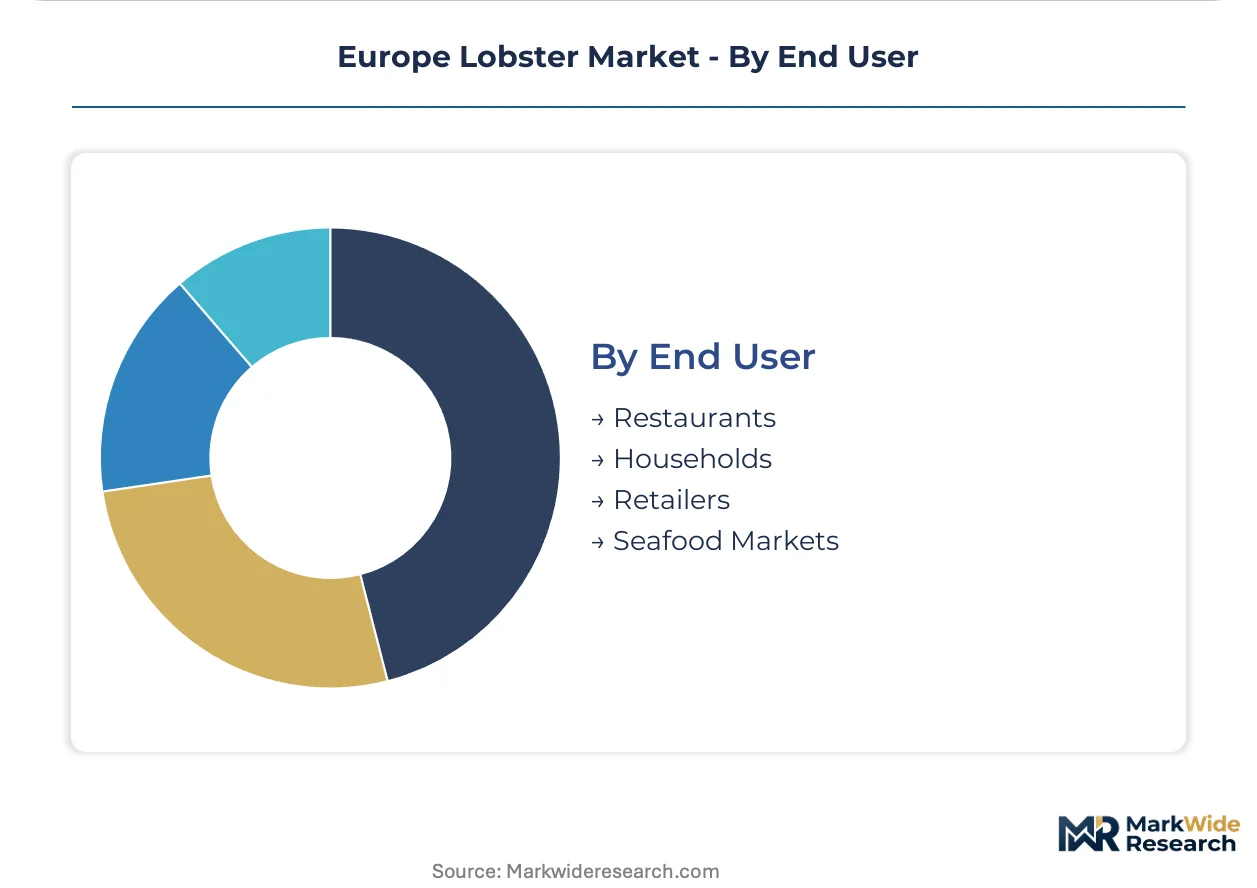
End User:
Customer type determines specification stringency, from tank-installation restaurants to price-sensitive household segments.
- Restaurants:Premium hospitality groups enlarge live lobster tank installations across coastal dining corridors. MSC certification and documented-origin product satisfy Ecolabelling requirements for menu transparency.
- Retailers:Large banners in Germany and the United Kingdom mandate carbon footprint disclosure across supply chains under CSRD sustainability reporting.
- Seafood Markets:Traditional auction houses in Mediterranean ports face volume attrition as procurement shifts to direct contracts.
- Households:E-commerce and retail frozen segments serve occasional consumption with lower handling complexity.
Restaurants absorb the premium live volume; Retailers are gaining share fastest through certification-driven procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Continental Europe's role as the primary entry node for Arctic and North Atlantic live lobster shipments.
France
Premium restaurant chains along the Barcelona-Marseille corridor drive live Homarus gammarus procurement with verified Brittany landing documentation. EFSA hygiene marking requirements govern cross-border fresh consignments entering from Spanish Galicia. The Brittany fishing cooperative cluster near Saint-Malo concentrates tank-management expertise for long-haul live transport.
Spain
Galician landing ports supply domestic hospitality groups expanding tank installations across coastal dining corridors. The country's national fisheries regulator enforces catch documentation requirements that parallel Norwegian standards for premium positioning. Barcelona's wholesale auction houses face volume attrition as Madrid restaurants contract directly with Icelandic suppliers.
Germany
Large retail banners mandate MSC Chain of Custody certification for procurement eligibility under Ecolabelling standards. EU Green Deal CSRD sustainability reporting requires carbon footprint disclosure across seafood supply chains. Hamburg distribution operators retrofit facilities with recirculating aquaculture systems for temporary live holding.
United Kingdom
Scottish landing documentation creates premium positioning for documented-origin product in London food service channels. EFSA cold-chain protocols reduce cross-border friction for fresh consignments entering from EU member states. The Billingsgate Market cluster in London concentrates wholesale handling expertise for restaurant-directed supply.
Norway
Oslo's catch documentation requirements layer additional compliance burdens that create premium positioning for Arctic-origin product in Continental Europe. The country's national fisheries directorate enforces vessel electrification pilots responding to EU Green Deal emissions disclosure mandates. Tromsø-based fishing cooperatives anchor direct-to-chef platform contracts with Paris and Madrid restaurants.
Europe Lobster Market Key Industry Players
Listed leaders compete with private specialists across certification tiers and cold-chain capabilities. The vendor base fragments across Arctic vertical integrators, Mediterranean auction intermediaries, and logistics-focused distributors. Three archetypes dominate: MSC-credentialed Arctic suppliers, controlled-atmosphere logistics specialists, and direct-to-chef platform operators. Capacity expansion in live-handling infrastructure and strategic partnerships with hospitality groups represent the dominant competitive moves.
Among Nordic-based suppliers, Royal Greenland and Iceland Seafood International exemplify the MSC-credentialed Arctic archetype through their vertical integration into North Atlantic fisheries. Clearwater Europe Ltd. occupies a position within the controlled-atmosphere logistics tier, extending shelf life across Continental distribution networks.
| Leading Market Players |
|---|
| Fylkir Seafood |
| Austevoll Seafood ASA |
| Blue Lobster Company |
| Grieg Seafood ASA |
| Mowi ASA |
| Royal Greenland |
| Northbay Seafood |
| Iceland Seafood International |
| Clearwater Europe Ltd. |
| Others |
Cost & Logistics Intelligence
Spiny lobster substitution from Atlantic African fisheries is compressing margin pools in Mediterranean wholesale channels while simultaneously shifting procurement gravity toward Arctic and North Atlantic sources that command documented-origin premiums in Continental Europe.
Pricing Analysis
Volume-discount tiering structures separate MSC-credentialed Arctic shipments from uncertified Mediterranean landings, with German and UK retail banners paying documented-origin premiums for verified Brittany and Galicia landing documentation. Price differentiation rests on certification grade and live-handling infrastructure investment, with tank-equipped hospitality groups absorbing the highest per-unit costs. Pricing pressure stems from diesel and ice expense volatility tied to North Sea energy pricing, compressing vessel operator margins. Frozen wholesale channels exhibit the greatest price sensitivity, while premium restaurant-directed live supply maintains inelastic demand.
Supply Chain Analysis
Inventory lead times for live shipments extend across multimodal journeys from Icelandic and Norwegian fishing cooperatives to Paris and Madrid restaurants, with sensor-enabled traceability systems monitoring temperature and mortality risk throughout. Supply concentrates in Norway, Iceland, and Greenland for Arctic-origin product, while Brittany and Galicia anchor European landings. The chain draws from diesel fuel, ice production, and oxygen injection systems as critical inputs. Single-source vulnerability runs through Rotterdam and Hamburg distribution nodes that handle Continental Europe's cold-chain throughput. Distribution runs through vertically integrated Arctic suppliers, controlled-atmosphere logistics specialists, and direct-to-chef platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSRD carbon footprint disclosure mandates are disrupting procurement patterns across German and UK retail banners, creating competitive separation between electrified Nordic processors and conventional Mediterranean operators.
For Market Incumbents: Secure MSC Chain of Custody recertification ahead of renewal cycles to maintain preferential access to Ecolabelling-driven retail procurement. Invest in recirculating aquaculture systems at Rotterdam and Hamburg distribution hubs to defend live-handling capacity against emerging logistics specialists. Arctic vertical integrators face margin pressure from chef-direct platforms consolidating purchase authority away from traditional wholesale auctions.
For New Entrants and Emerging Players: Lead with direct-to-chef digital procurement interfaces targeting Madrid and Paris restaurant groups seeking scheduled live deliveries from documented-origin suppliers. Mediterranean wholesale channels offer the most penetrable white-space as auction houses face volume attrition. Position against controlled-atmosphere logistics gaps in inland German and Benelux markets where live-handling infrastructure remains underdeveloped.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed controlled-atmosphere logistics specialists holding distribution contracts with major retail banners. Five-to-ten year viability hinges on EU Green Deal compliance infrastructure and CSRD reporting capabilities. Monitor vessel electrification pilot progress among Nordic processors as an inflection indicator for carbon-adjusted procurement preferences.
| Strategic Initiative | Industry Significance |
|---|---|
| MSC Chain of Custody Recertification | Secures procurement eligibility for German and UK retail banners under Ecolabelling standards. |
| Recirculating Aquaculture System Deployment | Enables inland live-handling capacity at Rotterdam and Hamburg distribution nodes. |
| Chef-Direct Platform Development | Bypasses Mediterranean auction houses to capture Paris and Madrid restaurant procurement. |
| Vessel Electrification Investment | Reduces CSRD carbon footprint disclosure burdens for Nordic processors supplying retail banners. |
| Sensor-Enabled Traceability Integration | Tracks temperature and mortality risk across multimodal live shipments from trap to tank. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fishing cooperative managers, cold-chain logistics operators, hospitality procurement directors, and retail banner sustainability officers; and secondary validation against EU Common Fisheries Policy quota documentation, EFSA hygiene marking records, MSC certification databases, and customs trade flows for North Atlantic and Mediterranean landings. Bottom-up volume triangulation from landing documentation and top-down value estimation from wholesale auction and direct-contract pricing were cross-referenced.
Across the analysis window, the forecast framework modeled product type segmentation by species and preservation state, distribution channel differentiation between live-handling and frozen networks, and end-user concentration across restaurant, retail, and seafood market channels. CAGRs were derived from quota-constrained supply growth assumptions and demand elasticity estimates for premium live product versus frozen commodity alternatives. EFSA cold-chain protocol harmonization and CSRD reporting adoption curves served as regulatory input variables.
The analysis sits within stated boundaries; outcomes outside continued EU Common Fisheries Policy quota stability and MSC certification retention rates would require recalibration. Forecasts reflect assumptions regarding diesel price trajectories and chef-direct platform penetration rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Meal Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Octopus Market
Seafood
Milkfish Market
Seafood
Salmon Market
Seafood
Global White Shrimp Market
Seafood
Trout Market
Seafood
Mackerel Market
Seafood
North America Salmon Market
Seafood
Canned Salmon Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Canned Anchovy Market
Seafood
United Arab Emirates Seafood Market
Seafood
North America Seafood Market
Seafood
Herring Market
Seafood
Edible Seaweed Market