
 European Frozen Seafood Market | 2026-2036
European Frozen Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
European Frozen Seafood Market Intelligence
Plant-based coating materials are displacing conventional breadcrumb batters in value-added frozen fish products, which is recalibrating input cost structures across processing lines. Royal Greenland A/S leverages its integrated Arctic fishing and processing footprint to sustain margin control from catch to retail shelf. Nomad Foods Limited dominates the European branded frozen seafood aisle through category-leading positions in breaded fish and fish fingers.
European frozen seafood encompasses finfish, shellfish, and cephalopods preserved at temperatures below minus 18 degrees Celsius to halt microbial activity and extend shelf life, with blast freezing and individual quick freezing representing the dominant industrial techniques for texture retention. The product serves retail consumers seeking convenient protein sources and food service operators requiring consistent portion-controlled inventory. Fish commands the largest volume share within product type segments, while shrimp captures disproportionate value growth in retail and food service channels. Online distribution is expanding fastest among channels, though wholesale remains the margin anchor for bulk transactions to institutional buyers.
EMA food-contact material rules, EFSA safety thresholds for contaminants in seafood, and EU Green Deal decarbonization mandates collectively shape processing standards, labeling requirements, and cold-chain infrastructure investments across member states. REACH compliance for packaging chemicals further constrains material choices for vacuum-sealed and retail pack formats. Stakeholders must weigh carbon-border adjustment exposure against the cost of retrofitting freezing equipment to meet tightening F-Gas phase-down schedules.
Market Dynamics
The EU Green Deal's F-Gas phase-down is forcing cold-chain operators across Spain, Germany, and France to retrofit freezing equipment, redistributing capital from expansion to compliance and compressing margins for mid-scale processors dependent on legacy hydrofluorocarbon systems.
Growth Catalysts
- Ready-meal manufacturer procurement:Food manufacturers in Germany and the UK are expanding frozen seafood volumes for premium retail lines, pulling demand for individually quick-frozen fillets and value-added portions.
- Blast freezing technology diffusion:Lower-capital blast freezing units are penetrating mid-tier Spanish and Italian processors, enabling texture-competitive product without IQF infrastructure investment.
- EU Green Deal cold-chain subsidies:Member-state decarbonization grants for refrigeration retrofit are unlocking equipment upgrade cycles among Dutch and Danish distributors.
Market Restraints
- Wild catch supply volatility:North Atlantic cod and haddock quotas set by regional fisheries management organizations constrain raw material predictability for breaded fish processors.
- F-Gas equipment lock-in:Existing hydrofluorocarbon freezing systems in older French and Belgian plants face stranded asset risk under tightening phase-down schedules.
- Energy cost spikes:Cold-chain electricity intensity exposes Polish and Baltic-state operators to margin erosion from grid price volatility.
Strategic Opportunities
- Portuguese market underpenetration:Frozen seafood distribution networks remain less developed than in Spain, creating first-mover space for direct-to-retail logistics investment.
- Plant-based coating convergence:Algae-protein and legume-based batter technologies are opening clean-label positioning for value-added products targeting Nordic health-conscious segments.
- Online channel expansion:E-commerce fulfillment infrastructure for temperature-controlled home delivery is scaling fastest in UK and German urban corridors.
Industry Challenges
- Refrigeration technician scarcity:Specialized ammonia and CO2 system maintenance skills are concentrated among aging workforces in Denmark and Norway, constraining retrofit timelines.
- EMA packaging material compliance:REACH-constrained vacuum-seal film approvals are extending new product launch cycles by 8-14 months for reformulated retail packs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | European Frozen Seafood Market |
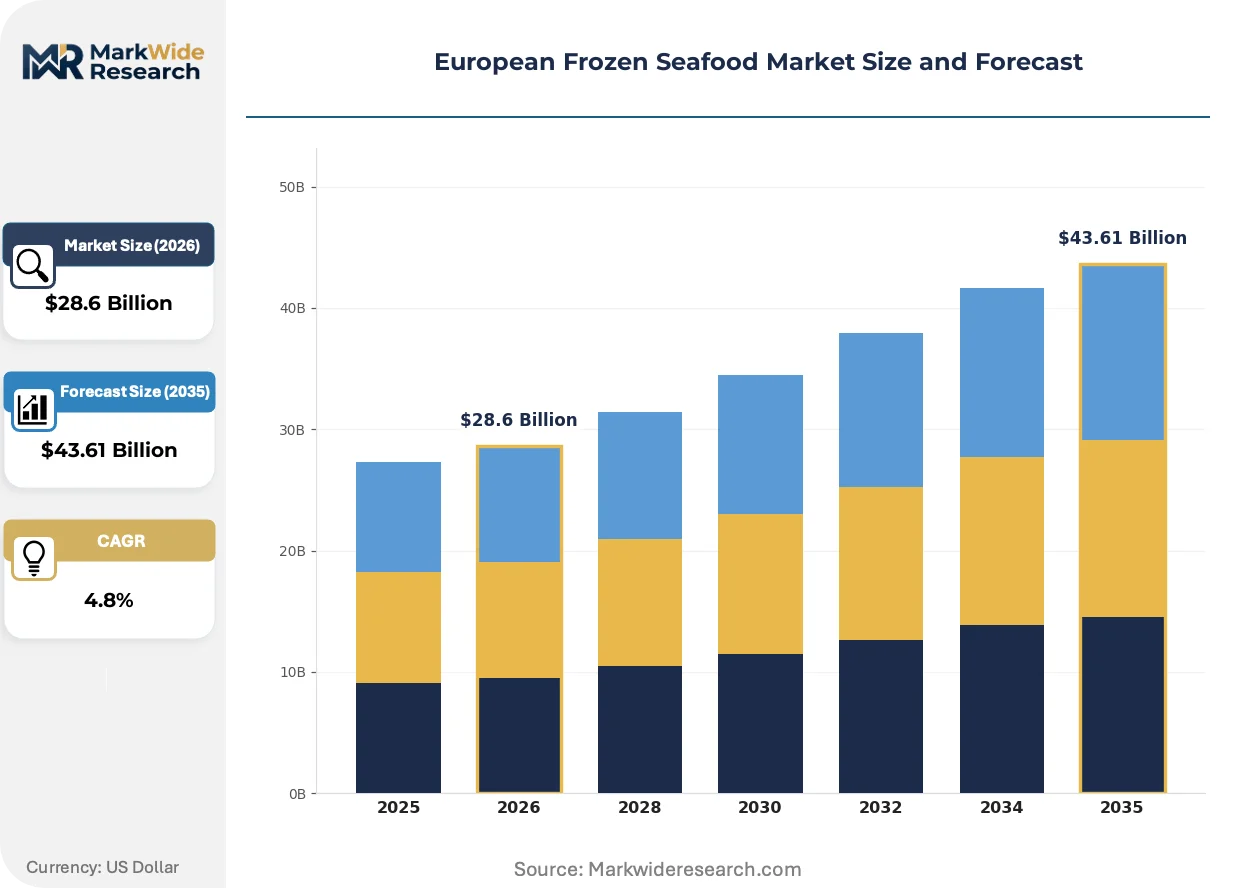
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shrimp, Crab, Squid Distribution Channel: Retail, Food Service, Online, Wholesale Packaging Type: Vacuum Sealed, Bulk, Retail Packs, Canned End User: Restaurants, Supermarkets, Households, Food Manufacturers |
| Companies Covered | Findus Group Limited, Royal Greenland A/S, Mowi ASA, Grieg Seafood ASA, Clearwater Seafoods Incorporated, Thai Union Group Public Company Limited, Lerøy Seafood Group ASA, Austevoll Seafood ASA, Nomad Foods Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
European Frozen Seafood Market Strategic Shifts & Innovations
Automation and regulatory stringency are converging to reshape European frozen seafood processing, with environmental compliance and labor scarcity jointly driving capital deployment toward sensor-integrated production lines and alternative refrigeration chemistries.
Hyperspectral sorting systems paired with robotic portioning arms are automating defect detection and weight-standardization tasks previously handled by manual grading stations. Spanish and Norwegian processors are deploying these integrated lines at greenfield sites to offset wage pressure and reduce giveaway from inconsistent portion weights. The technology is automating quality-control staffing models and compressing the payback period for capital-intensive plant upgrades.
The F-Gas Regulation's stepped refrigerant phase-down is mandating CO2 transcritical and ammonia secondary systems across EU member states, with EFSA-aligned cold-chain documentation requirements adding traceability layers. German and Dutch cold-storage operators are absorbing 15-25% equipment premiums for compliant systems versus hydrofluorocarbon equivalents. Smaller French and Italian processors are responding through cooperative procurement consortia to achieve vendor scale discounts.
Food service operators are consolidating frozen seafood purchasing through centralized procurement platforms, displacing traditional wholesale broker relationships. Large UK and German contract catering groups are negotiating direct annual contracts with Icelandic and Faroese primary processors, bypassing layered distribution. This concentration is most visible in institutional channels serving healthcare and education sectors, where volume predictability outweighs spot-market flexibility.
European Frozen Seafood Market Segmentation
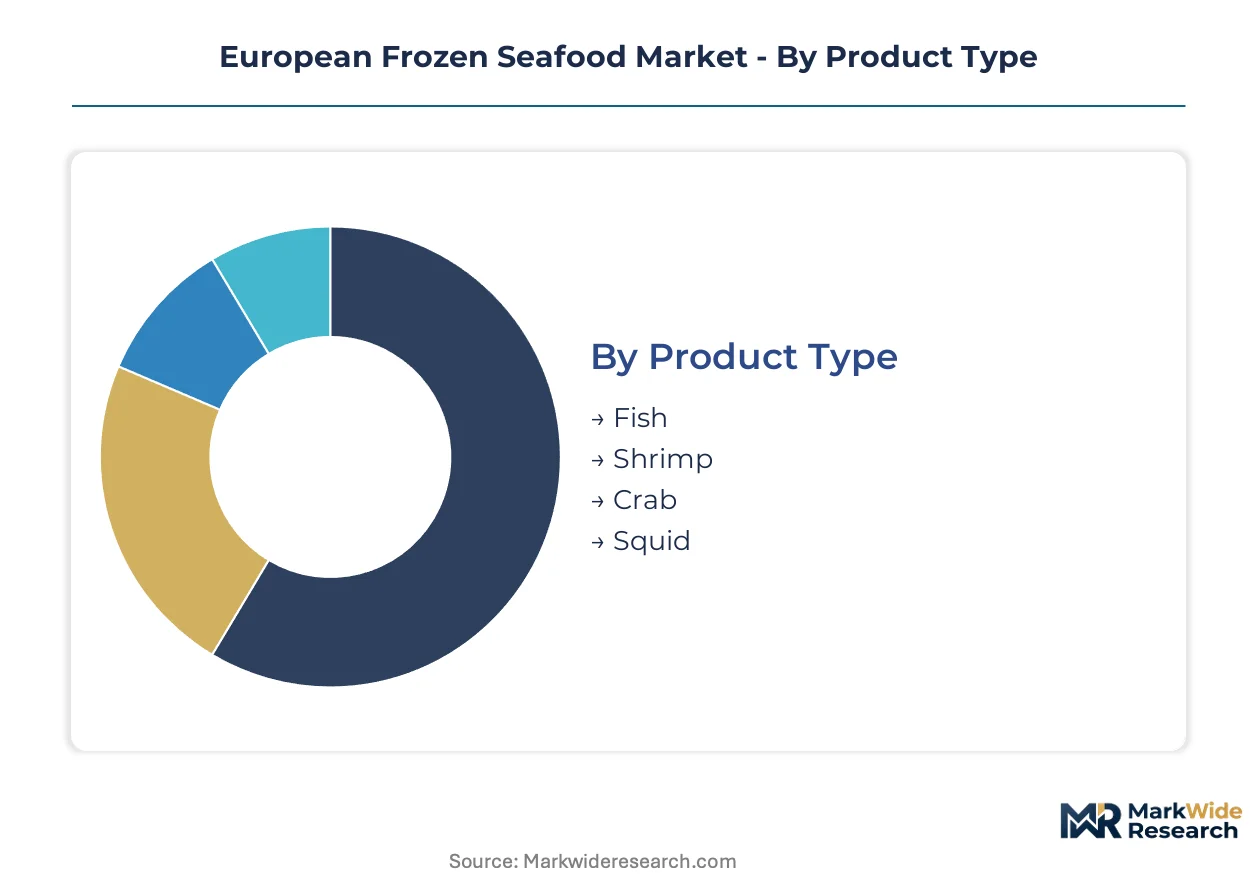
Segmentation in European frozen seafood reveals divergent margin structures and regulatory exposure across processing tiers. Product type and channel selection determine capital intensity, while packaging and end-user targeting shape compliance burdens and price realization.
Product Type:
Standardized bulk formats dominate volume, while differentiated species command premium positioning through origin certification and portion control.
- Fish:Finfish species including cod, haddock, and pollock constitute the foundational volume base, with individually quick-frozen fillets anchoring food manufacturer procurement in Germany and the UK. North Atlantic quota constraints under regional fisheries management organizations create supply volatility for breaded fish processors dependent on predictable raw material flows.
- Shrimp:Crustacean products capture disproportionate value growth through retail and food service channels, with warm-water varieties from South Asian aquaculture and cold-water Nordic catches serving distinct price tiers. EFSA contaminant thresholds for heavy metals and antibiotics impose batch-testing costs that favor larger importers with in-house laboratory capacity.
- Crab:Snow crab and brown crab segments serve premium food service accounts in France and Belgium, with cooked-frozen clusters requiring specialized blast freezing to preserve texture.
- Squid:Cephalopod products concentrate in Mediterranean markets, with Spanish and Italian processors dominating cleaned-tube and tentacle portioning for food service distribution.
Leading the category by volume: Fish. Expanding most quickly: Shrimp.
Distribution Channel:
Channel selection determines cold-chain infrastructure requirements and margin capture, with direct-to-retail formats demanding stricter temperature documentation than wholesale bulk.
- Retail:Branded frozen seafood through supermarket chains requires EFSA-aligned labeling and REACH-compliant retail packaging, with Nomad Foods and Royal Greenland dominating shelf space in UK and Nordic markets. Private-label expansion among German discounters is compressing branded price premiums while expanding volume throughput.
- Food Service:Institutional buyers including contract caterers and restaurant groups negotiate direct annual contracts with Icelandic and Faroese primary processors, bypassing traditional wholesale layers. Portion consistency and predictable supply schedules outweigh spot-market price flexibility in procurement decisions.
- Online:Temperature-controlled home delivery infrastructure is scaling fastest in UK and German urban corridors, with last-mile cold-chain reliability remaining the primary constraint on geographic expansion.
- Wholesale:Bulk transactions to distributors and brokers remain the margin anchor for volume processors, with Rotterdam and Hamburg serving as primary consolidation hubs for intra-European redistribution.
Capturing the largest revenue share: Retail. Climbing the fastest: Online.
Packaging Type:
Packaging format selection reflects the trade-off between shelf-life extension, regulatory compliance cost, and retail presentation requirements.
- Vacuum Sealed:Oxygen-exclusion films extend shelf life for high-value species, with REACH-constrained material approvals extending new product launch cycles by 8-14 months for reformulated retail packs.
- Bulk:Food service and manufacturer channels favor unbranded frozen blocks and IQF cartons, minimizing per-unit packaging cost while requiring downstream portioning investment.
- Retail Packs:Consumer-facing cartons and bags must satisfy EMA food-contact material rules and national labeling requirements, with sustainability-driven film thickness reductions creating mechanical handling challenges.
- Canned:Thermally processed seafood in metal containers occupies a distinct preservation category, with longer ambient shelf life but different consumer perception versus frozen positioning.
Dominating food service procurement: Bulk. Gaining share fastest in retail: Vacuum Sealed.
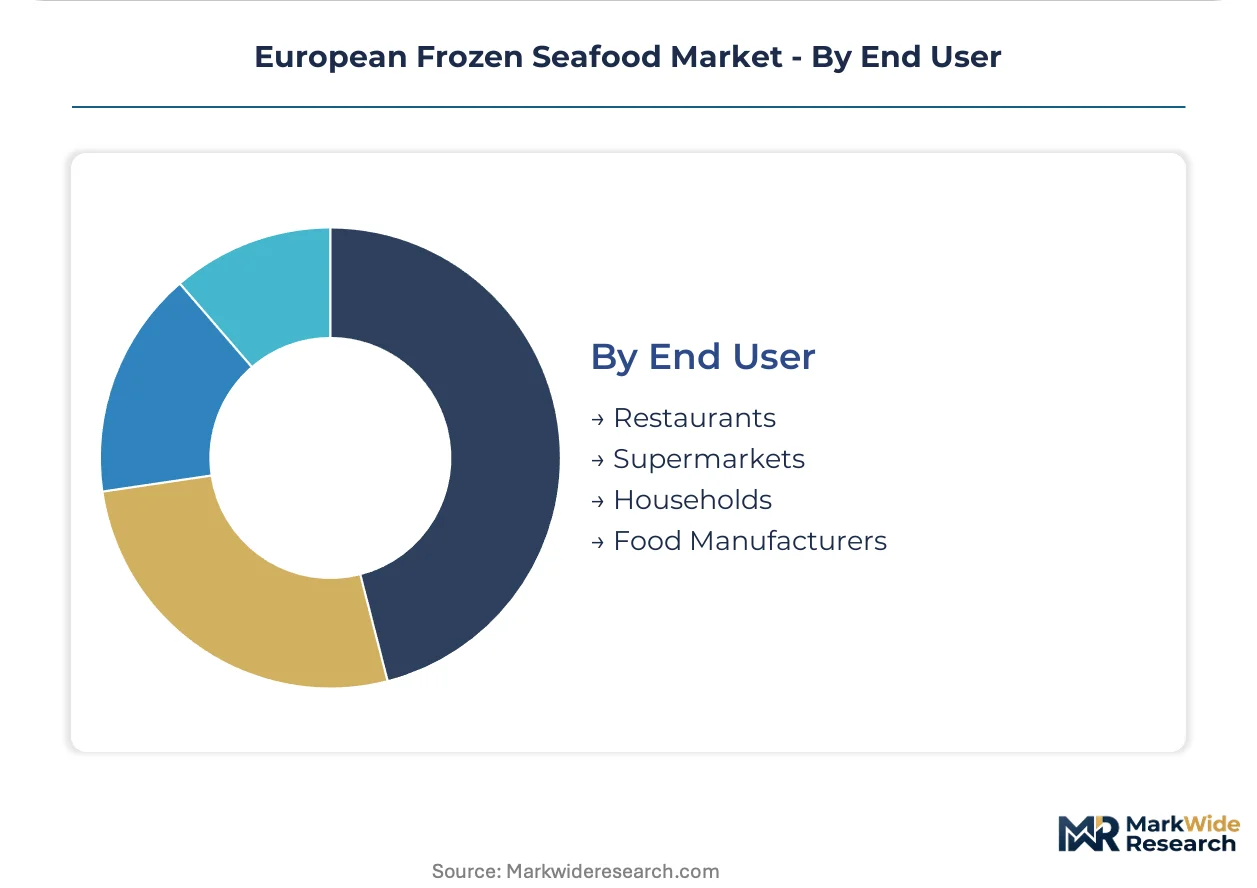
End User:
End-user targeting determines product specification, certification burden, and relationship structure across the value chain.
- Restaurants:Independent and chain food service operators require consistent portion weights and predictable supply schedules, with automated sorting systems reducing giveaway from manual grading variation.
- Supermarkets:Retail chains impose supplier qualification programs covering EFSA safety documentation, carbon footprint disclosure, and packaging recyclability compliance.
- Households:Direct consumer purchases through retail and online channels drive demand for convenience formats including pre-portioned fillets and value-added breaded products.
- Food Manufacturers:Ready-meal producers in Germany and the UK are expanding frozen seafood procurement for premium retail lines, pulling demand for specification-controlled raw material with defined moisture and protein content.
Generating highest volume throughput: Food Manufacturers. Steepest expansion trajectory: Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Basque Country hosts the densest concentration of frozen seafood processing infrastructure in Europe, with Bilbao and Vigo serving as Atlantic catch consolidation hubs where EU Green Deal cold-chain subsidies are accelerating ammonia refrigeration retrofits.
Spain
Spanish households consume more frozen seafood per capita than any other European nation, with Galicia and Andalusia hosting the continent's most developed blast-freezing networks. EFSA contaminant thresholds for heavy metals impose batch-testing costs that favor larger importers with in-house laboratory capacity. Vigo anchors the national industry, where cooperatives process North Atlantic cod and haddock for redistribution across Iberian retail chains.
Germany
German ready-meal manufacturers are expanding frozen seafood procurement for premium retail lines, pulling demand for individually quick-frozen fillets with defined moisture specifications. The F-Gas Regulation's stepped refrigerant phase-down is forcing cold-chain operators in Hamburg and Bremerhaven to retrofit freezing equipment. Berlin-based distributors are absorbing equipment premiums for CO2 transcritical systems to maintain compliance with tightening environmental standards.
United Kingdom
UK food service operators are consolidating frozen seafood purchasing through centralized procurement platforms, displacing traditional wholesale broker relationships. EMA food-contact material rules and REACH compliance for packaging chemicals constrain vacuum-seal film approvals. Grimsby and Hull maintain their positions as primary North Sea catch processing centers, with automated sorting systems reducing giveaway from manual grading variation.
France
French contract caterers and restaurant groups negotiate direct annual contracts with Icelandic and Faroese primary processors, bypassing layered distribution. The EU Green Deal's decarbonization mandates are reshaping cold-chain infrastructure investments across member states. Boulogne-sur-Mer hosts the country's largest seafood auction and freezing complex, where mid-scale processors face stranded asset risk from legacy hydrofluorocarbon systems.
Netherlands
Dutch cold-storage operators are unlocking equipment upgrade cycles through member-state decarbonization grants for refrigeration retrofit. Rotterdam serves as the primary consolidation hub for intra-European redistribution, with blast freezing technology diffusing among mid-tier processors. EFSA-aligned cold-chain documentation requirements are adding traceability layers that favor operators with integrated digital tracking systems.
European Frozen Seafood Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with retail shelf space concentrating around established names while food service channels favor direct processor relationships. The vendor base organizes into three tiers: integrated Arctic fishing operations, European branded portfolio companies, and Asian aquaculture-backed processors. Strategic moves center on backward integration into primary catch and cooperative procurement consortia to achieve vendor scale discounts.
Within the integrated fishing tier, Royal Greenland A/S exemplifies the catch-to-retail model through its Arctic processing footprint. Nomad Foods Limited anchors the branded specialist position across UK and Nordic retail channels. Mowi ASA and Grieg Seafood ASA represent Norwegian salmon farming integration, while Thai Union Group Public Company Limited occupies the Asian aquaculture-backed processor archetype.
| Leading Market Players |
|---|
| Findus Group Limited |
| Royal Greenland A/S |
| Mowi ASA |
| Grieg Seafood ASA |
| Clearwater Seafoods Incorporated |
| Thai Union Group Public Company Limited |
| Lerøy Seafood Group ASA |
| Austevoll Seafood ASA |
| Nomad Foods Limited |
| Others |
Cost & Logistics Intelligence
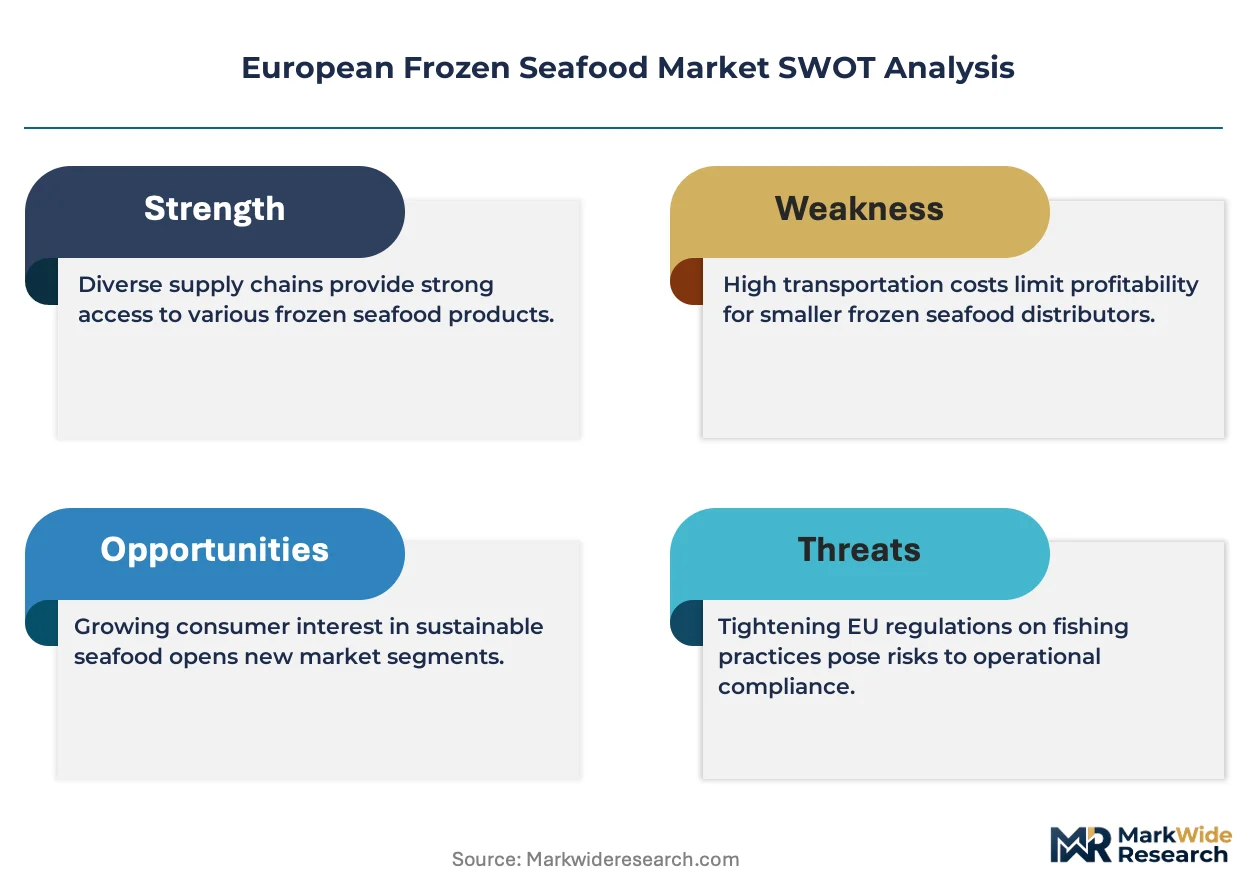
Family-owned Spanish cooperatives and sovereign-backed Norwegian producers anchor supply discipline across the European frozen seafood value chain, translating quota-limited raw material access into pricing power at the processor level while compressing margins for unintegrated distributors dependent on spot-market procurement.
Pricing Analysis
Premium pricing for short lead-time delivery of individually quick-frozen fillets separates contract-caterer procurement from spot-market bulk purchasing, with three-tier pricing structure across premium, standard, and economy levels reflecting origin certification, portion precision, and cold-chain documentation depth. Arctic-caught cod with Marine Stewardship Council accreditation commands substantial brand premiums over unmarked South Asian aquaculture imports. Cost compression in mid-tier breaded fish segments is intensifying because German discounters are expanding private-label penetration. Food manufacturers represent the most price-sensitive buyer segment, while French contract caterers exhibit lowest sensitivity due to menu-price pass-through mechanisms.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Vigo orchestrate hub-and-spoke patterns for intra-European redistribution, with cold-storage capacity expansion lagging demand growth in UK urban corridors. Raw material supply concentrates in Norway, Iceland, and the Faroe Islands for North Atlantic whitefish, while warm-water shrimp feeds from Vietnamese and Ecuadorian aquaculture operations. Single-source vulnerability runs through the Strait of Dover logistics chokepoint for UK-bound reefer traffic. Distribution runs through layered wholesale broker relationships that food service operators are progressively displacing through direct processor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European frozen seafood market is becoming a vertical-integration race, with catch-to-retail control over Arctic quota allocations emerging as the decisive margin-preservation lever against supply volatility.
For Market Incumbents: Acquire in-house laboratory capacity for EFSA contaminant testing to neutralize batch-verification cost disadvantages against larger importers. Secure ammonia refrigeration retrofit capabilities before technician scarcity in Denmark and Norway constrains equipment upgrade timelines. Consolidate Portuguese distribution infrastructure ahead of competitor entry into this underpenetrated corridor. For New Entrants and Emerging Players: Direct-to-retail logistics partnerships offer the most accessible entry vector for bypassing entrenched wholesale layers. Target Portuguese supermarket chains with blast-frozen value-added products, where Spanish distribution networks remain undeveloped relative to Iberian market potential. Lead with algae-protein coating formulations to capture Nordic clean-label positioning ahead of incumbent reformulation cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale French processors with stranded hydrofluorocarbon assets in Boulogne-sur-Mer, where F-Gas compliance costs are forcing divestiture below replacement value. Five-to-ten-year viability hinges on successful refrigeration chemistry transition and direct food service contract penetration. Monitor EU Green Deal subsidy disbursement velocity as the inflection indicator for equipment upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Catch-to-Retail Integration | Arctic quota control insulates Royal Greenland against raw material volatility in cod processing. |
| Ammonia Refrigeration Retrofit | F-Gas phase-down compliance preserves market access for Dutch and Danish cold-storage operators. |
| Plant-Based Coating Development | Algae-protein batter technologies unlock clean-label positioning for Nordic health-conscious retail segments. |
| Direct Food Service Contracting | Bypassing wholesale layers captures margin from UK and German institutional procurement consolidation. |
| Portuguese Distribution Buildout | First-mover logistics investment exploits frozen seafood network gaps relative to Spanish infrastructure density. |
Research Approach
Document review covered EU fisheries management organization quota filings, EFSA contaminant threshold documentation, and member-state cold-chain subsidy disbursement records, complemented by interviews with Spanish cooperative processing managers, German ready-meal procurement directors, Dutch cold-storage operators, and Danish ammonia system technicians. Secondary validation drew from customs trade data, refrigerated transport operator filings, and seafood industry association capacity surveys. Bottom-up volume modeling triangulated against top-down expenditure flow analysis across the analysis window.
Historical catch volume trajectories cross-referenced against panel input from primary processors established baseline supply assumptions. Segmentation modeling addressed product type, distribution channel, packaging format, and end-user archetype dimensions throughout the forecast period. CAGRs were derived from fitted trend extrapolation moderated by regulatory phase-down schedules and equipment replacement cycle timing. Forecast inputs incorporated F-Gas Regulation compliance cost curves and fisheries quota negotiation outcomes.
Caveats apply where North Atlantic stock assessments, energy price volatility, or REACH packaging material approval delays could materially shift the outlook beyond modeled parameters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Organic Salmon Market
Seafood
Fish Protein Concentrate Market
Seafood
Asian Sea Bass Market
Seafood
Dried Scallop Market
Seafood
Sea Bream Market
Seafood
COD Market
Seafood
North America Salmon Market
Seafood
Surimi Market
Seafood
Crayfish Market
Seafood
Smoked Salmon Market
Seafood
United Arab Emirates Seafood Market
Seafood
Surimi by-Product Market
Seafood
Europe Salmon Market
Seafood
Japan Frozen Seafood Market
Seafood
Herring Market
Seafood
Seafood Flavors Market