
 Organic Salmon Market | 2026-2036
Organic Salmon Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Salmon Market Analytics
Asc certification cycles and national organic aquaculture standards are bifurcating the competitive landscape into qualified incumbents and excluded aspirants. Mowi ASA leverages its integrated feed-to-fork operations across Norwegian fjords to sustain volume leadership. Lerøy Seafood Group ASA anchors its position through vertical control of hatchery, grow-out, and processing stages in Arctic waters. The Irish Organic Salmon Company differentiates via island-based farming with shorter logistics loops to British and continental buyers.
Organic salmon denotes Atlantic salmon raised in marine net-pens or land-based recirculating systems without synthetic pesticides, GMO feed, or prophylactic antibiotics, achieving flesh lipid profiles above 10% omega-3 content and meeting ISO 65 organic accreditation. Fresh salmon commands the dominant value share as retail and foodservice buyers prioritize short supply chains and unprocessed fillet formats. Frozen salmon represents the fastest-expanding product type, driven by Asian market development and extended shelf-life requirements in distant wholesale channels. Smoked salmon concentrates margin pools in European specialty stores where artisanal curing commands price premiums over commoditized alternatives.
EU organic aquaculture regulation, USDA National Organic Program standards, and ASC certification protocols collectively determine farm eligibility, feed sourcing rules, and stocking density limits that directly shape production economics. Norway's national organic standard administered by Debio and the UK's Soil Association certification impose additional domestic layers that filter market access for non-compliant imports. Stakeholders must monitor evolving feed ingredient rules, particularly around fishmeal substitution thresholds and non-GMO oilseed verification, as these specifications will determine which farming operations retain organic designation and pricing power.
Market Dynamics
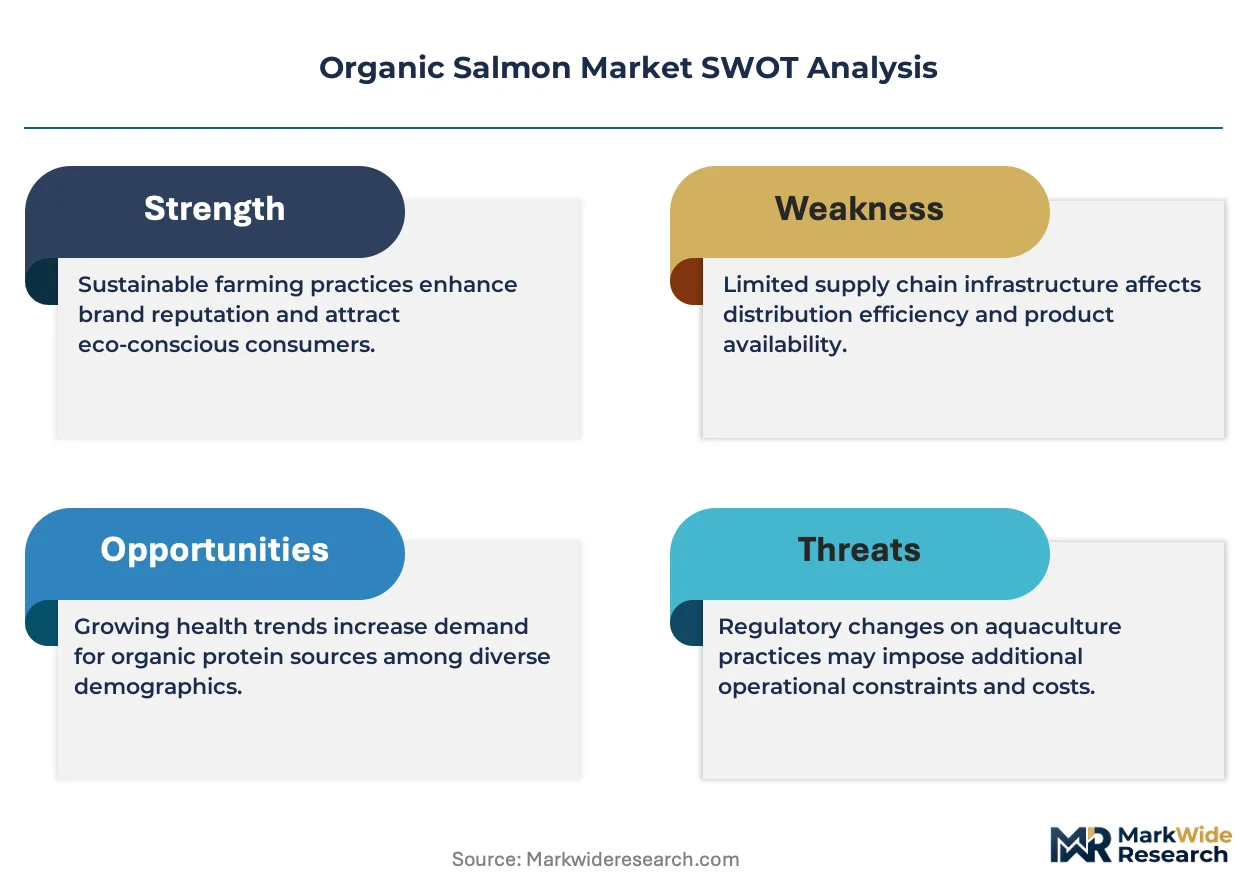
EU organic aquaculture regulation is tightening feed ingredient verification and stocking density limits, forcing Norwegian and Scottish producers to restructure hatchery-to-harvest operations or surrender certification status.
Growth Catalysts
- EU organic aquaculture regulation:Certification mandates from Brussels are filtering non-compliant imports and securing premium price tiers for accredited Norwegian fjord operations.
- Clean-label seafood procurement:Premium restaurant chains in France and Germany are rewriting supplier scorecards to prioritize ASC-certified and Debio-accredited Atlantic salmon.
- Land-based recirculating aquaculture systems:Closed-containment technology is expanding organic production geography beyond traditional cold-water fjord sites into controlled indoor environments.
Market Restraints
- Fishmeal substitution thresholds:Non-GMO oilseed verification costs and limited marine protein supply are compressing feed formulation margins for organic-certified farms.
- Norwegian supply concentration:Cold-water infrastructure lock-in around Lofoten and Shetland basins creates geographic vulnerability to algal bloom and temperature anomalies.
- USDA National Organic Program delays:Pending final aquaculture standards are freezing American producer investment and channeling import demand toward EU-certified supply.
Strategic Opportunities
- Asian wholesale channel development:Frozen organic salmon is penetrating Japanese and South Korean retail through extended shelf-life logistics and ISO 65 recognition.
- Soil Association certification arbitrage:Post-Brexit UK regulatory divergence is creating parallel premium tiers for British buyers seeking domestic accreditation.
- Blockchain-enabled provenance tracking:Distributed ledger verification is converging with existing ASC audit protocols to shorten due diligence cycles for institutional procurement.
Industry Challenges
- Organic aquaculture veterinary expertise:Limited pools of fish health specialists trained in prophylactic-free disease management are constraining farm expansion timelines.
- Multi-certification audit fatigue:Simultaneous ASC, Debio, and Soil Association compliance cycles are extending administrative overhead and diluting operational focus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Salmon Market |
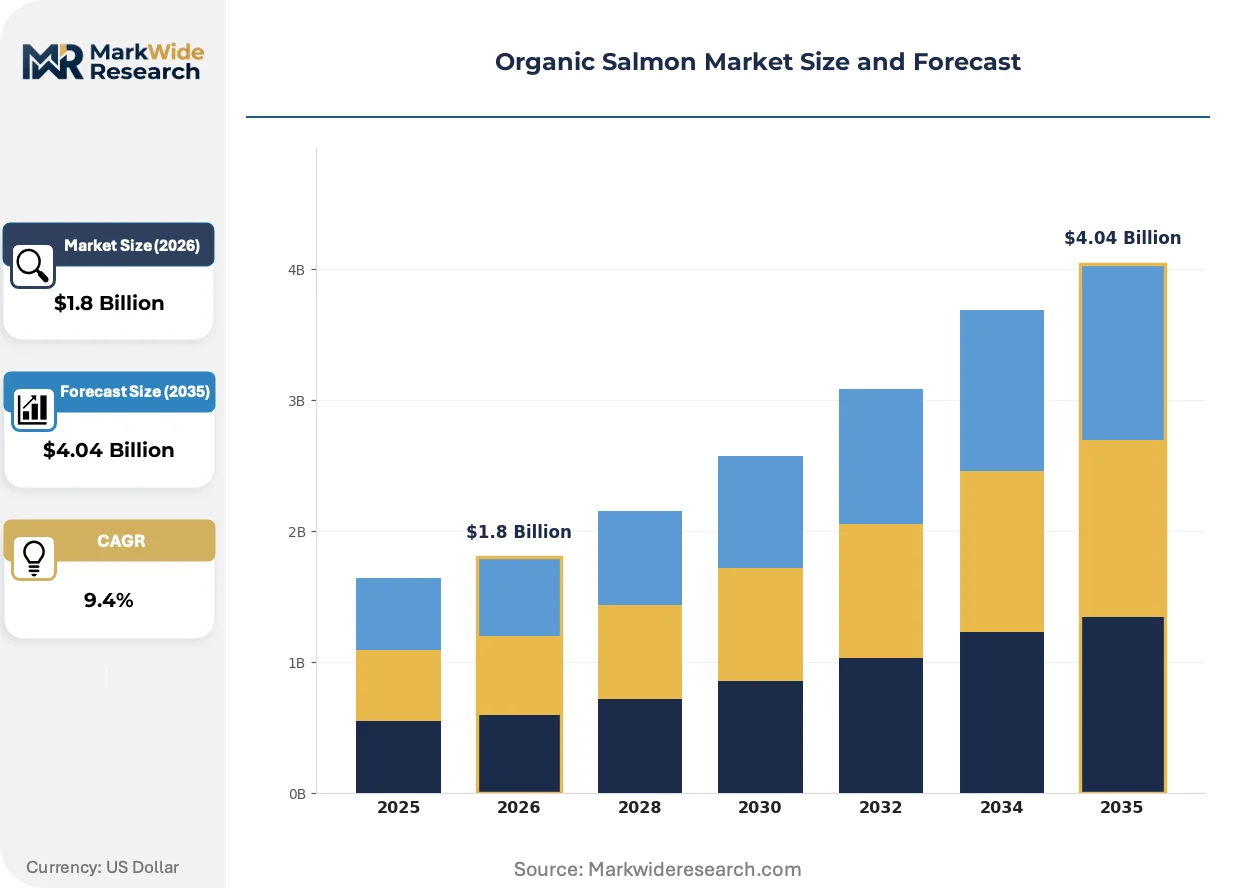
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Salmon, Frozen Salmon, Smoked Salmon, Canned Salmon Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale End User: Restaurants, Retail Consumers, Foodservice, Caterers Package Type: Tray, Bag, Can, Box |
| Companies Covered | Lerøy Seafood Group ASA, The Irish Organic Salmon Company, Mowi ASA, Grieg Seafood ASA, SalMar ASA, Cermaq Group AS, Scottish Sea Farms Ltd., Tassal Group Limited, Cooke Aquaculture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Salmon Market Evolving Landscape
Biological monitoring systems and alternative feed chemistry are reconfiguring production economics, while regulatory divergence between Brussels and Washington is fragmenting certification pathways.
Single-cell protein and insect meal formulations are decomposing traditional fishmeal dependency in organic feed rations. Norwegian integrators are piloting bacterial biomass and black soldier fly larvae at commercial scale. This ingredient transition is decomposing the marine raw material bottleneck that has constrained organic production volume growth.
REACH chemical authorization and EU F-Gas Regulation are tightening equipment standards for land-based recirculating systems. Refrigeration and water treatment machinery face substance restrictions and energy efficiency mandates. Arctic Circle producers are retrofitting facilities to comply, accelerating capital replacement cycles ahead of regulatory deadlines.
Direct contracting between certified farms and specialty retail banners is compressing traditional wholesale intermediary layers. British and German organic supermarket chains are negotiating multi-year volume agreements with named Scottish and Irish suppliers. This channel restructuring is most visible in London and Hamburg metro areas where traceability marketing commands shelf placement premiums.
Organic Salmon Market Segmentation
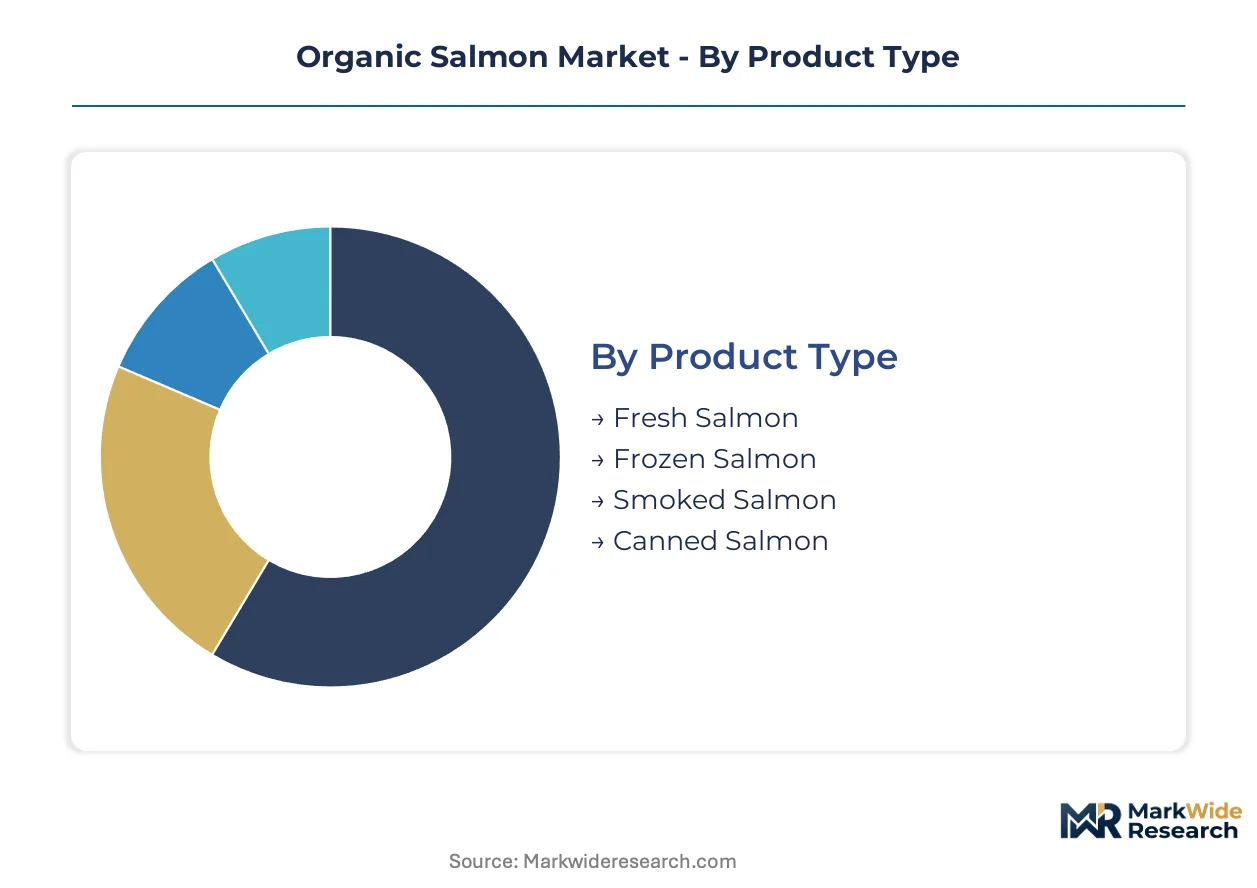
Channel economics in organic salmon hinge on temperature control requirements and certification visibility. Each segment category maps distinct margin pools to specific buyer workflows and logistics investments.
Product Type:
Fresh salmon dominates premium foodservice procurement through short-turn supply chains, while frozen formats unlock distant wholesale channels where shelf-life extension justifies logistics costs.
- Fresh Salmon:Unprocessed fillets and whole fish distributed within 48-72 hour windows to retain omega-3 lipid profiles above certification thresholds. Norwegian fjord operations supply Paris and Hamburg restaurant groups through dedicated cold-chain logistics. EU organic aquaculture regulation mandates traceability documentation that fresh-channel buyers absorb as procurement overhead.
- Frozen Salmon:Blast-frozen at sea or shore facilities to extend distribution reach into Asian retail and institutional catering. Japanese and South Korean buyers prioritize ISO 65 recognition over proximity sourcing. Frozen formats are expanding most quickly as land-based recirculating systems diversify production geography beyond traditional cold-water basins.
- Smoked Salmon:Artisanal curing commands specialty store premiums in London and Berlin organic retail clusters.
- Canned Salmon:Shelf-stable formats serve backup supply roles in remote institutional kitchens with limited cold storage.
By volume, fresh salmon leads. By growth pace, frozen salmon is ahead.
Distribution Channel:
Margin capture varies sharply by channel control—direct farm-retail contracting compresses intermediary layers while wholesale volumes absorb certification audit costs across aggregated supply.
- Specialty Stores:Curated organic banners in British and German metro areas negotiate multi-year volume agreements with named Scottish and Irish suppliers. Soil Association and Debio accreditation determine shelf placement premiums. These channels concentrate the highest per-kilogram margins through traceability marketing.
- Supermarkets:Broad-assortment retail chains in France and Germany are rewriting supplier scorecards to prioritize ASC-certified Atlantic salmon. Clean-label procurement mandates filter non-compliant imports and secure premium price tiers for accredited Norwegian operations.
- Online Retail:Direct-to-consumer platforms aggregate smaller order quantities with premium delivery guarantees.
- Wholesale:Volume aggregation serves foodservice intermediaries with extended payment terms and certification documentation bundles.
Specialty stores command margin leadership. Supermarkets drive volume scale.
End User:
Procurement sophistication splits end users by certification fluency—restaurant groups employ dedicated seafood buyers while retail consumers respond to front-of-package claims.
- Restaurants:Premium chains in North America and Europe are expanding organic salmon procurement as consumer willingness to pay for certified clean-label seafood rises. Menu transparency requirements and supplier scorecard audits dominate sourcing decisions. These buyers absorb the steepest price premiums for named-farm provenance.
- Foodservice:Institutional catering operations in corporate and educational settings balance cost targets with emerging ESG procurement mandates. Volume contracting with frozen suppliers dominates this segment.
- Retail Consumers:Individual purchasers respond to Debio, Soil Association, and ASC labeling in supermarket and specialty store environments.
- Caterers:Event-based foodservice operations source through wholesale channels with flexible volume commitments.
Restaurants anchor premium pricing. Foodservice scales volume throughput.
Package Type:
Packaging economics reflect last-mile temperature control requirements and retail display constraints across channel formats.
- Tray:Modified-atmosphere packaging dominates fresh salmon retail presentation in European supermarkets. Film specifications must comply with REACH chemical authorization and EU F-Gas Regulation for sealing equipment. Tray formats align with grab-and-go consumption patterns in urban metro areas.
- Bag:Vacuum-sealed formats serve frozen salmon distribution with extended shelf-life requirements. Thawing instructions and certification logos compete for limited label surface area.
- Can:Shelf-stable formats for smoked and processed salmon comply with metal packaging substance restrictions under REACH frameworks.
- Box:Bulk insulated containers protect fresh salmon through wholesale and foodservice distribution with gel pack or dry ice supplementation.
Tray formats dominate retail visibility. Bag formats scale frozen logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium restaurant groups in Paris and Hamburg drive continental procurement volumes. Specialty retail banners in London and Berlin absorb the steepest price premiums for named-farm provenance. Cold-water farming infrastructure concentrates in Norwegian fjords and Scottish sea lochs.
Norway
Debio-certified fjord operations supply Parisian restaurant groups through dedicated cold-chain logistics. The country's national organic standard administered by Debio imposes feed sourcing rules and stocking density limits that filter market access. Lofoten basin producers are restructuring hatchery-to-harvest operations to retain certification status amid tightening EU organic aquaculture regulation.
United Kingdom
Soil Association accreditation determines shelf placement premiums in London and Berlin organic retail clusters. Post-Brexit regulatory divergence creates parallel premium tiers for British buyers seeking domestic certification. Scottish Sea Farms and Shetland basin operations anchor supply concentration for British and continental buyers.
Ireland
Island-based farming operations leverage shorter logistics loops to British and continental buyers. The Irish Organic Salmon Company differentiates via geographic isolation that supports clean-label marketing claims. West coast producers negotiate multi-year volume agreements with specialty retail banners in Hamburg and Amsterdam.
Germany
Clean-label procurement mandates from premium restaurant chains filter non-compliant imports and secure premium price tiers. EFSA and EU organic aquaculture regulation shape farm eligibility and feed formulation requirements. Hamburg metro area buyers absorb the steepest certification documentation overhead as traceability marketing commands shelf placement premiums.
France
Menu transparency requirements from Parisian restaurant groups dominate sourcing decisions for ASC-certified Atlantic salmon. EU F-Gas Regulation and REACH chemical authorization tighten equipment standards for processing and distribution infrastructure. Brittany and Normandy logistics hubs channel Norwegian and Scottish supply into continental foodservice networks.
Organic Salmon Market Competitive Landscape
Player mix skews toward integrated Norwegian aquaculture conglomerates with captive feed-to-fork operations. Three strategic archetypes dominate: vertically integrated fjord operators controlling hatchery-to-harvest stages, island-based specialists exploiting geographic isolation for clean-label differentiation, and land-based recirculating system pioneers expanding production geography beyond traditional cold-water basins. Competitive moves concentrate on certification arbitrage across ASC, Debio, and Soil Association protocols, plus direct contracting with specialty retail banners to compress wholesale intermediary layers.
Within the integrated operator tier, Mowi ASA and Lerøy Seafood Group ASA exemplify scale-driven positioning through Norwegian fjord and Arctic water operations. The Irish Organic Salmon Company occupies a specialist position representing island-based farming archetypes with shorter logistics loops to British and continental buyers. Grieg Seafood ASA and SalMar ASA sit within the mid-tier integrated category, while Cermaq Group AS and Scottish Sea Farms Ltd. anchor regional supply concentration in Scottish sea lochs. Tassal Group Limited and Cooke Aquaculture represent geographic diversification beyond North Atlantic basins.
| Leading Market Players |
|---|
| Lerøy Seafood Group ASA |
| The Irish Organic Salmon Company |
| Mowi ASA |
| Grieg Seafood ASA |
| SalMar ASA |
| Cermaq Group AS |
| Scottish Sea Farms Ltd. |
| Tassal Group Limited |
| Cooke Aquaculture |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Debio-certified Norwegian farms and Parisian restaurant groups lock in supply access while anchoring price visibility against spot market volatility. These agreements transfer feed formulation risk to producers while securing volume commitments for buyers navigating EU organic aquaculture regulation compliance.
Pricing Analysis
Cost-plus contracts indexed to non-GMO oilseed and fishmeal spot prices dominate organic salmon procurement. Three-tier pricing structure across Debio-certified premium, ASC-standard, and conventional farmed tiers reflects certification audit overhead and stocking density compliance costs. Pricing pressure stems from fishmeal substitution thresholds compressing feed margins. Foodservice intermediaries exhibit highest price sensitivity; specialty retail banners absorb premiums for named-farm provenance.
Supply Chain Analysis
Norway and Scotland anchor organic salmon production through fjord and sea loch infrastructure. Supply chains draw from marine protein processors, non-GMO oilseed crushers, and veterinary service networks trained in prophylactic-free disease management. Single-source vulnerability concentrates around Lofoten basin temperature anomalies and algal bloom events. Distribution runs through dedicated cold-chain logistics to Hamburg and Paris metro clusters, with frozen formats extending reach through Japanese and South Korean wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic salmon operates as a regulatory entrenchment market where multi-certification compliance creates switching costs that freeze out non-compliant aspirants. Network effects concentrate in established cold-water farming regions where hatchery-to-harvest expertise pools are geographically locked.
For Market Incumbents: Consolidate through backward integration into alternative feed ingredient supply—single-cell protein and insect meal formulations—to decompose marine raw material bottlenecks. Expand land-based recirculating system capacity in controlled indoor environments beyond traditional fjord geography. Channel control through direct contracting with specialty retail banners in London and Hamburg compresses wholesale intermediary layers and defends margin pools against ASC audit fatigue. For New Entrants and Emerging Players: Differentiate on island-based farming archetypes with shorter logistics loops to British and continental buyers, mirroring Irish west coast positioning. Target Japanese and South Korean frozen wholesale channels where ISO 65 recognition unlocks shelf-life-extended distribution without proximity sourcing requirements. Go-to-market through blockchain-enabled provenance tracking converges with existing audit protocols to shorten due diligence cycles for institutional procurement. For Investors and Strategic Acquirers: Land-based recirculating system pioneers with captive feed formulation capabilities represent the priority acquisition archetype. Long-term viability frames around regulatory divergence between Brussels and Washington creating parallel certification tiers with distinct margin pools. Watch for final USDA National Organic Program aquaculture standards as the inflection signal—American producer investment thawing would redirect import demand patterns and reshape Atlantic supply allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Feed Supply | Single-cell protein and insect meal sourcing decomposes marine raw material bottlenecks constraining organic volume growth. |
| Land-Based Recirculating System Expansion | Closed-containment technology diversifies production geography beyond Lofoten and Shetland cold-water basin concentration. |
| Multi-Certification Compliance Investment | Simultaneous ASC, Debio, and Soil Association accreditation filters market access and secures premium price tiers. |
| Direct Farm-Retail Contracting | Named-supplier agreements with British and German organic banners compress wholesale intermediary margin extraction. |
| Blockchain Provenance Implementation | Distributed ledger verification converges with existing audit protocols to shorten institutional procurement due diligence cycles. |
Research Methodology
Cross-validation between primary interviews with aquaculture operations managers, feed formulation specialists, and specialty retail category buyers anchors the qualitative findings. Secondary validation draws from EU organic aquaculture regulation filings, Debio and Soil Association certification registries, customs trade data for Atlantic salmon flows, and EFSA feed ingredient safety assessments. Bottom-up volume modeling triangulates against top-down expenditure analysis across restaurant procurement budgets and retail scanner data.
Sensitivity analysis frames the analytical approach across the projection horizon. Segmentation dimensions include product type (fresh, frozen, smoked), distribution channel (specialty stores, supermarkets, wholesale), and certification tier (Debio, ASC, Soil Association). CAGRs derive from trend extrapolation moderated by feed cost inflation assumptions and regulatory compliance cost trajectories. Industry-specific inputs incorporate fishmeal substitution threshold evolution and land-based recirculating system capacity buildout timelines.
The analysis sits within stated boundaries; outcomes outside EU-US regulatory convergence or sustained marine protein supply disruption would require recalibration. Forecasts reflect assumptions around certification stringency maintenance and cold-chain infrastructure investment continuity. Recalibration cycles align with material shifts in EU organic aquaculture regulation enforcement and USDA National Organic Program final standard promulgation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Tuna Fish Market
Seafood
United States Plant-Based Seafood Market
Seafood
Sea Biscuits Market
Seafood
Mussel Oil Market
Seafood
Halibut Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
Fish Powder Market
Seafood
Europe Lobster Market
Seafood
Herring Market
Seafood
Global Shrimp Market
Seafood
Fin Fish Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Europe Seafood Market
Seafood
Crustacean Market
Seafood
Fish Protein Concentrate Market
Seafood
United Arab Emirates Seafood Market