
 Rainbow Trout Market | 2026-2036
Rainbow Trout Market Size, Share, and Industry Trends Forecast 2026-2036
Rainbow Trout Market Analysis
Foodservice buyer concentration is expanding as multinational restaurant chains and institutional catering networks consolidate procurement volumes across fewer approved suppliers. Cermaq Group AS leverages its integrated hatchery-to-harvest operations across Norwegian fjords to secure long-term supply contracts with European retail banners. Lerøy Seafood Group ASA anchors its competitive position through vertical control over processing and logistics infrastructure in northern Europe. Grieg Seafood ASA competes by specializing in land-based and open-pen systems optimized for different regional water temperature profiles.
Rainbow trout (Oncorhynchus mykiss) is a cold-water salmonid species farmed in freshwater and marine net-pen systems, typically harvested at 1.5 to 4 kilograms for fillet production or whole-sale distribution. The fish contains 18-22% protein by weight and serves as a premium protein source for retail, foodservice, and direct-to-consumer channels across temperate markets. Frozen product categories dominate volume throughput due to extended shelf stability and export logistics flexibility, while smoked segments capture disproportionate margin pools in European specialty retail. Direct sales channels from farm-gate to restaurant groups are growing fastest as traceability verification becomes a procurement prerequisite for certified sustainable seafood programs.
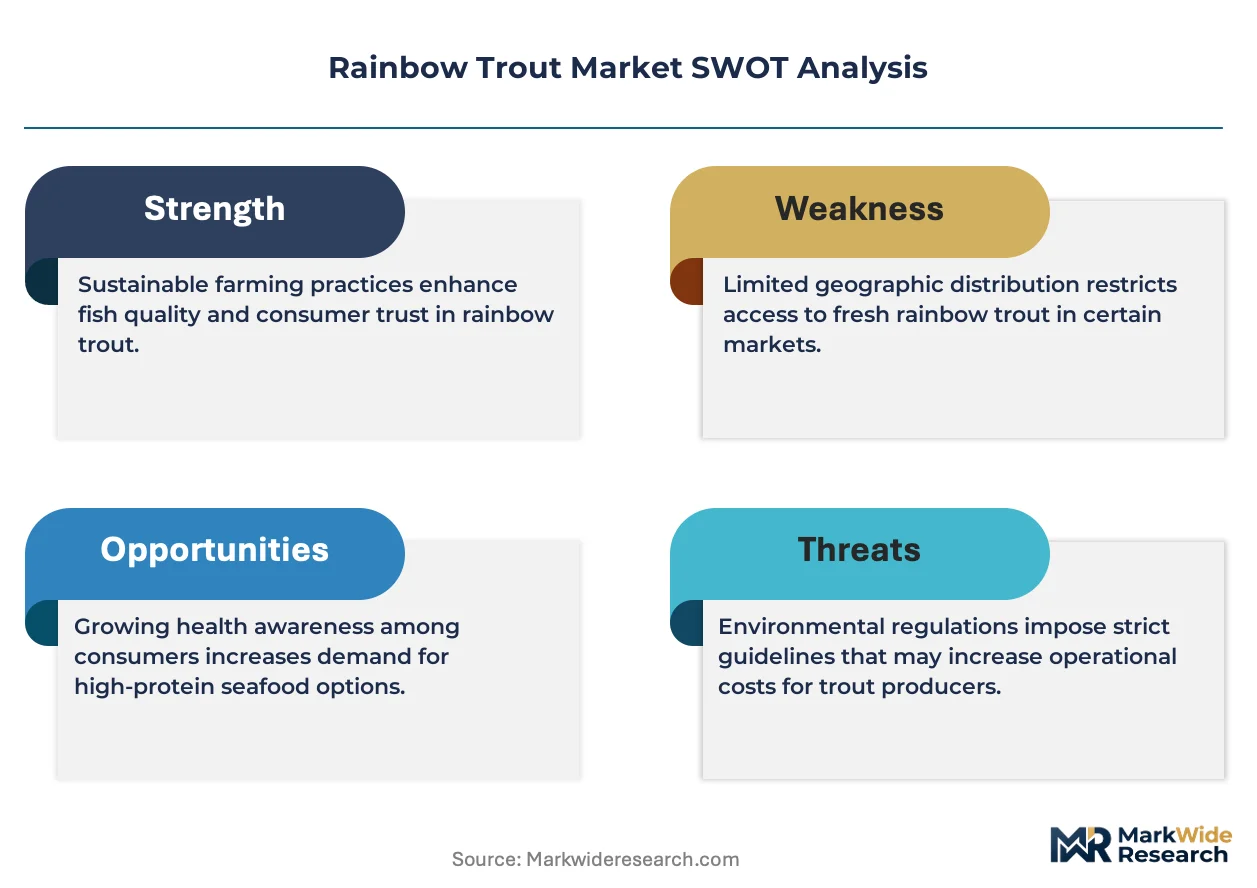
The EU's Common Fisheries Policy and Aquaculture Stewardship Council standards govern stocking densities, feed sourcing, and escape prevention across European production zones, while the FDA and USDA jointly oversee HACCP compliance and labeling requirements for imported and domestic trout in the United States. Norway's national regulations under the Norwegian Food Safety Authority impose stricter sea lice monitoring and antibiotic reporting than baseline EU directives, creating differentiated compliance tiers for exporters. Stakeholders must monitor evolving feed ingredient sustainability criteria, particularly the substitution of marine-derived fishmeal with terrestrial proteins and novel single-cell ingredients, to preserve market access under tightening retailer certification protocols.
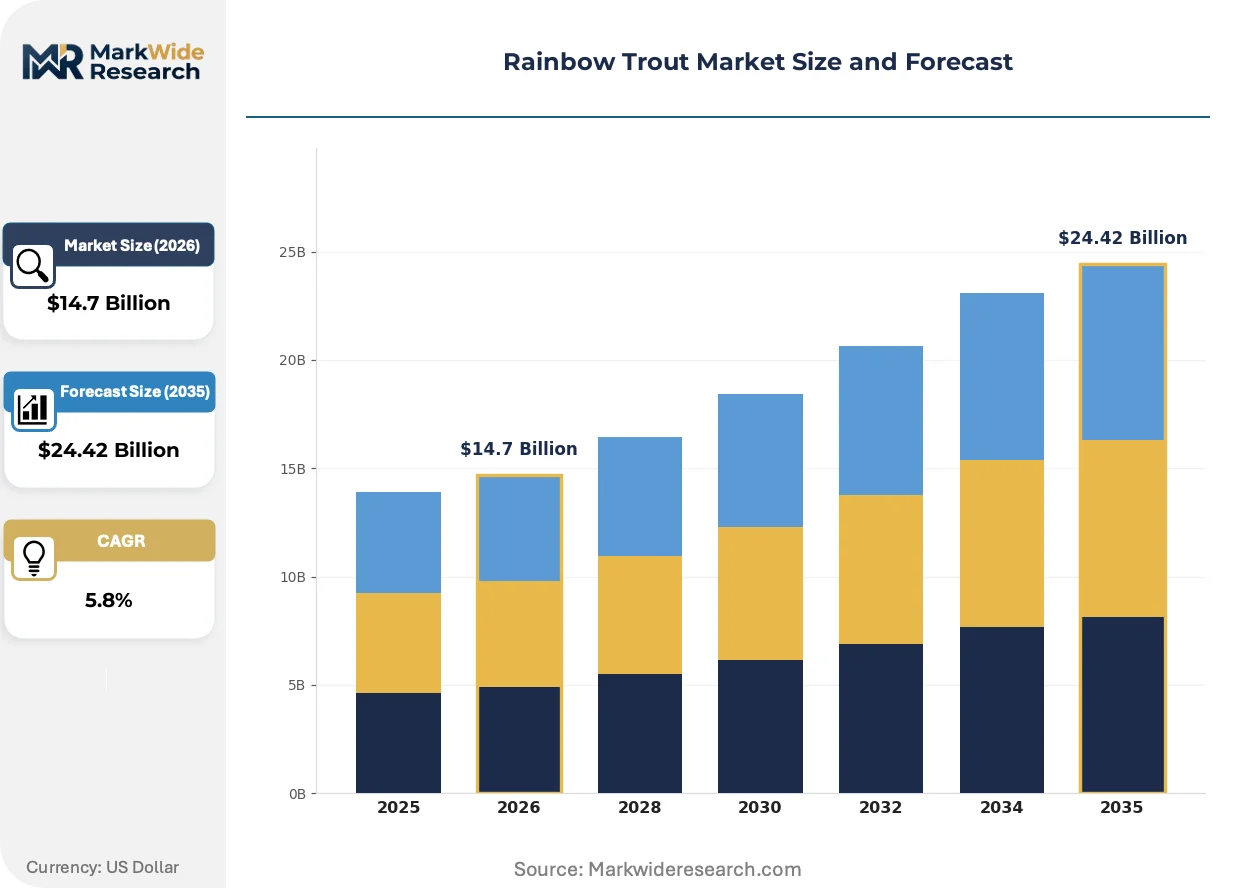
Market Dynamics
Foodservice procurement consolidation is compressing supplier margins while ASC and EU Common Fisheries Policy traceability mandates are absorbing operational overhead across Norwegian, Chilean, and US production clusters.
Growth Catalysts
- EU Common Fisheries Policy traceability mandates:Retail banners in Germany and France now require lot-level documentation, locking in certified suppliers and excluding uncertified competitors from shelf placement.
- Single-cell protein feed innovation:Novel fermentation-derived ingredients are reducing marine fishmeal dependence, satisfying retailer sustainability scorecards without compromising growth rates in land-based systems.
- Direct-to-restaurant channel expansion:Hotel foodservice operations in North America are bypassing distributors for farm-gate contracts, prioritizing origin-verified product with compressed handling stages.
Market Restraints
- Marine ingredient cost volatility:Fishmeal and fish oil prices fluctuate with Peruvian anchovy quota announcements, squeezing feed conversion economics for open-pen operators.
- Norwegian sea lice monitoring burden:The Norwegian Food Safety Authority mandates weekly reporting and treatment thresholds that elevate labor and veterinary costs above EU baseline requirements.
- Atlantic salmon substitution pressure:Farmed salmon achieves comparable fillet yields at lower unit costs in retail, diverting volume-sensitive buyers from rainbow trout.
Strategic Opportunities
- Smoked trout specialty retail in Poland:Traditional smokehouse culture and underdeveloped branded presence create white space for ASC-certified entrants with cold-chain logistics capability.
- Recirculating aquaculture system convergence:Integration of AI-driven water quality monitoring with modular tank designs enables inland production near major US population centers.
- USDA BioPreferred procurement preference:Federal foodservice contracts now award points for domestically farmed, sustainably certified seafood, tilting institutional demand toward verified suppliers.
Industry Challenges
- Recirculating system engineering talent scarcity:Land-based facilities require hydrodynamics and biofiltration specialists that existing aquaculture programs do not produce at scale.
- ASC certification timeline compression:Farm-level audits and supply chain documentation require 12-18 months, delaying market access for new entrants facing retailer deadlines.
- Genetic broodstock IP fragmentation:Proprietary strain licensing across Norwegian, Scottish, and US hatcheries creates royalty stacking and performance variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rainbow Trout Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Smoked, Whole Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Households, Restaurants, Retailers, Aquaculture Packaging Type: Vacuum Sealed, Styrofoam, Plastic Wrap, Carton |
| Companies Covered | Cermaq Group AS, Nordic Trout, Clear Springs Foods, Lerøy Seafood Group ASA, Pacific Seafood Group, Riverence, Grieg Seafood ASA, SmartGreen Aquaculture, Mowi ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rainbow Trout Market Emerging Trajectories
Production technology and procurement verification systems are converging to reshape competitive positioning across temperate-zone farming operations. Three developments merit particular attention.
Recirculating aquaculture systems with closed-loop water treatment are absorbing capital deployment from conventional net-pen expansion. US inland operators near Chicago and Denver are commissioning these facilities to supply restaurant groups with 48-hour freshness guarantees. The technology is absorbing volume growth that would otherwise flow to Chilean and Norwegian imports.
REACH chemical authorization and EFSA feed additive reviews are tightening residue monitoring protocols for European processors. Norwegian exporters must now document absence of ethoxyquin in finished product, adding analytical costs that smaller processors struggle to absorb. Smoked trout specialists in Denmark and Germany are consolidating testing infrastructure to maintain EU market access.
Chain-of-custody verification is replacing origin claims as the primary procurement filter for multinational foodservice buyers. Sodexo and Compass Group contracts now specify blockchain-tracked documentation from egg to fillet, disqualifying suppliers with fragmented handling records. This behavioral shift is most visible in UK and Nordic institutional catering, where public sector tender mandates drive adoption.
Rainbow Trout Market Segmentation
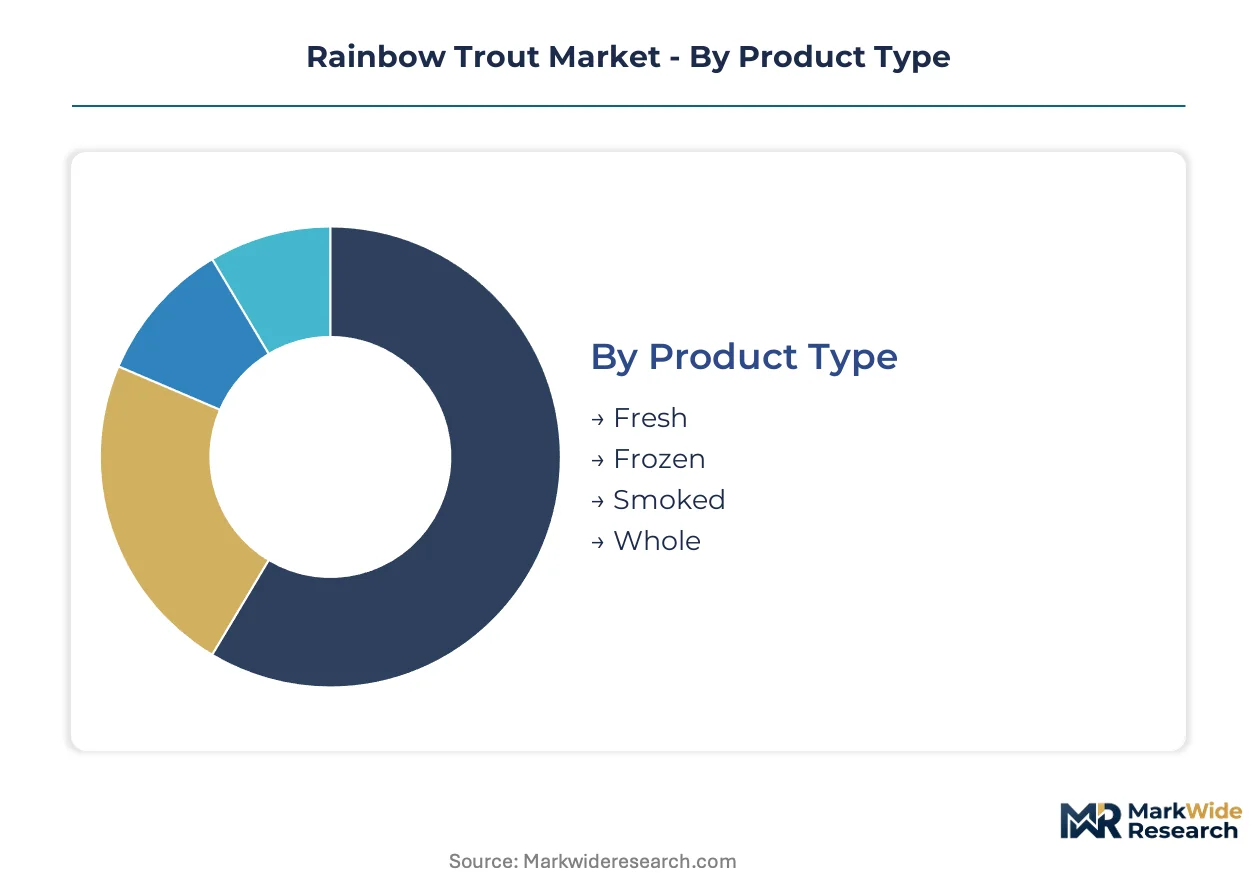
Rainbow trout supply chains fragment across temperature-controlled handling requirements and buyer certification standards. Each segment category carries distinct margin profiles and regulatory exposure that reshape procurement priorities across Norwegian, Chilean, and US production clusters.
Product Type:
Volume throughput concentrates in frozen formats, while premium margin capture depends on freshness preservation and smokehouse processing.
- Fresh:Harvest-to-delivery windows of 48-72 hours limit geographic radius. Norwegian fjord operations supply Paris and Berlin retail banners with ASC-certified fillets meeting EU Common Fisheries Policy traceability mandates.
- Frozen:Blast-frozen at sea or shore plants enables transoceanic logistics. Chilean exporters leverage this format for US Midwest retail penetration where inland cold-chain infrastructure supports distribution economics.
- Smoked:Traditional cold-smoke methods in Denmark and Germany command specialty retail premiums.
- Whole:Live-hauled or gutted-on-ice formats serve ethnic retail and live-market channels in urban centers.
Mature deployment sits with Frozen. Newer deployment is concentrated in Fresh.
Distribution Channel:
Channel selection determines traceability documentation burden and working capital intensity for producers.
- Retail:German and French supermarket banners require blockchain-tracked lot documentation from egg to fillet. ASC certification gates shelf placement, absorbing 12-18 month compliance timelines for new supplier onboarding.
- Wholesale:Consolidators in Rotterdam and Miami aggregate volumes from multiple farms for redistribution. Foodservice buyers leverage this channel for price discovery and supply security across seasonal availability gaps.
- Online:Direct-to-consumer platforms in US coastal metros promise 24-hour freshness guarantees.
- Direct Sales:Farm-gate contracts with hotel foodservice operations in Chicago and Denver bypass distributor margins.
Wholesale channels dominate volume throughput. Direct Sales are climbing the fastest as traceability verification becomes non-negotiable.
End User:
Buyer sophistication varies dramatically across consumption occasions and procurement scale.
- Households:Premium protein substitution drives refrigerated case purchases in US Northeast and Nordic markets. Retail price sensitivity limits volume growth relative to Atlantic salmon alternatives.
- Restaurants:White-tablecloth and fast-casual chains in North America specify origin-verified product with compressed handling stages. USDA BioPreferred procurement preference tilts federal contracts toward domestically farmed, certified supply.
- Retailers:Banner consolidation in Germany and France reduces approved supplier pools.
- Aquaculture:Broodstock and feed trial demand from research facilities and hatchery operations.
Restaurants anchor premium pricing power. Household consumption shows steepest expansion trajectory as retail certification transparency improves.
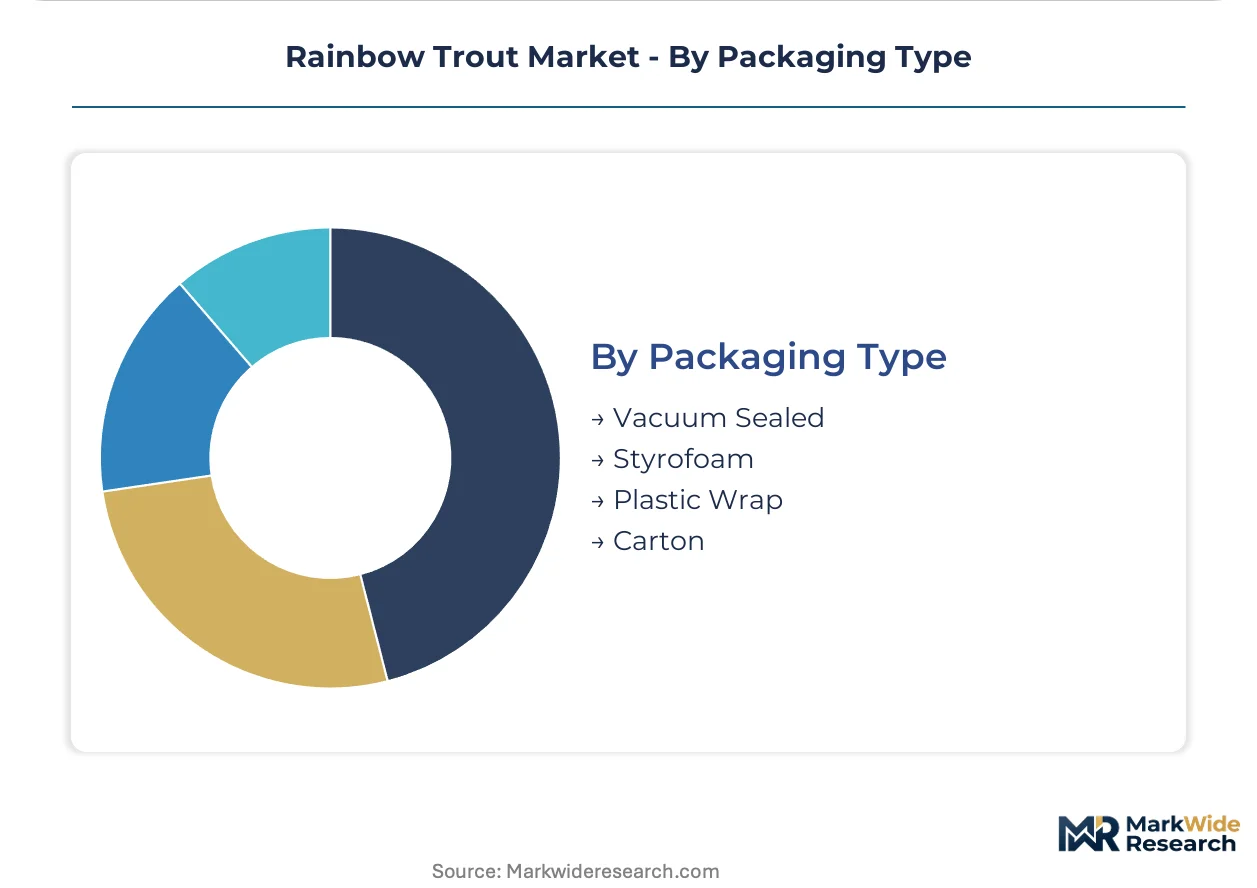
Packaging Type:
Material selection balances shelf-life extension against sustainability scorecard compliance.
- Vacuum Sealed:Modified atmosphere packaging extends refrigerated shelf life to 14-21 days. REACH chemical authorization in Europe mandates residue documentation for packaging adhesives and films.
- Styrofoam:Insulated shippers dominate air freight and long-haul trucking. EFSA reviews of food contact materials are tightening migration testing protocols for expanded polystyrene.
- Plastic Wrap:Overwrap for fresh counter displays faces retailer sustainability targets.
- Carton:Recyclable fiber-based packaging gains share in Nordic retail.
Vacuum Sealed formats command processing infrastructure investment. Carton alternatives are gaining share fastest under retailer plastic reduction commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement consolidation in Germany and France is reshaping supplier access across temperate-zone production basins. Hotel chains and institutional catering networks in North America are compressing approved vendor lists to single-digit counts. Norwegian fjord operations, Chilean lake districts, and US inland aquaculture zones each face distinct certification burdens and cold-chain cost structures.
Norway
Hotel foodservice contracts from Oslo to Bergen demand ASC-certified fillets with blockchain-tracked documentation. The Norwegian Food Safety Authority imposes weekly sea lice monitoring and antibiotic reporting that exceeds EU baseline requirements. Tromsø and Trondheim processing clusters absorb these compliance costs through long-term supply agreements with French retail banners.
United States
Chicago and Denver restaurant groups are sourcing directly from Idaho and Colorado land-based facilities to secure 48-hour freshness guarantees. USDA BioPreferred procurement preference awards federal foodservice contract points to domestically farmed, sustainably certified supply. Pacific Northwest hatchery-to-harvest operations near Seattle are expanding recirculating aquaculture capacity to serve West Coast hotel chains.
Chile
Midwest US retail penetration depends on Chilean blast-frozen fillets distributed through Miami consolidators. The national fisheries regulator under SERNAPESCA enforces HACCP compliance and residue monitoring for export-bound product. Lake District farming zones near Puerto Montt specialize in volume production for transoceanic frozen logistics.
Germany
Supermarket banner consolidation in Berlin and Munich retail corridors reduces approved trout supplier pools to ASC-certified incumbents. REACH chemical authorization mandates residue documentation for packaging adhesives and processing aids. Hamburg and Bremen smokehouse specialists are consolidating testing infrastructure to maintain EU market access under tightening EFSA protocols.
France
Paris retail banners require lot-level traceability documentation from egg to fillet under EU Common Fisheries Policy mandates. ANSM and DGCCRF coordinate feed additive residue surveillance across imported and domestic supply. Brittany and Normandy processing clusters specialize in cold-smoked formats commanding specialty retail premiums in Île-de-France.
Rainbow Trout Market Vendor Landscape
Norwegian producers anchor the premium certified tier; US inland specialists hold the direct-to-restaurant channel. The vendor base splits between vertically integrated fjord operators and modular land-based technologists. Three archetypes dominate: ASC-certified volume suppliers, recirculating system innovators, and smokehouse processing specialists. Competitive moves center on hatchery-to-harvest certification acceleration and AI-driven water quality platform licensing.
Within the integrated Norwegian tier, Cermaq Group AS and Lerøy Seafood Group ASA occupy positions exemplifying fjord-based vertical control. Grieg Seafood ASA represents the dual-system archetype, spanning land-based and open-pen configurations. Among US-based operators, Clear Springs Foods anchors the inland production cluster serving Chicago and Denver foodservice corridors.
| Leading Market Players |
|---|
| Cermaq Group AS |
| Nordic Trout |
| Clear Springs Foods |
| Lerøy Seafood Group ASA |
| Pacific Seafood Group |
| Riverence |
| Grieg Seafood ASA |
| SmartGreen Aquaculture |
| Mowi ASA |
| Others |
Supply Flow & Price Mechanics
ASC certification requirements gate qualified supply and premium-tier pricing access, excluding uncertified Norwegian and Chilean farms from German retail placement while rewarding compliant operators with 15-20% shelf price premiums over standard-tier alternatives.
Pricing Analysis
Volume throughput concentrates in frozen commodity tiers while margin capture concentrates in fresh and smoked specialty segments. Three-tier pricing structure across premium ASC-certified, standard EU-compliant, and economy unverified levels separates buyers by traceability documentation requirements. Pricing pressure stems from Atlantic salmon substitution in retail cases, compressing rainbow trout fillet premiums in volume-sensitive European markets. Quick-service restaurant procurement teams show highest price sensitivity; white-tablecloth hotel foodservice buyers accept 25-30% premiums for origin-verified product with compressed handling stages.
Supply Chain Analysis
Reverse-logistics flows for returned or expired product remain underdeveloped, with most unsold fresh fillets diverted to rendering or pet food channels rather than refurbishment. Supply concentrates in Norway, Chile, and the United States, with Norwegian fjord operations anchoring premium certified volumes and Chilean lake districts feeding frozen export pipelines. Feed formulation draws from marine fishmeal, fish oil, and emerging single-cell protein alternatives, exposing cost structures to Peruvian anchovy quota volatility. Single-source vulnerability sits with concentrated hatchery broodstock licensing across Scottish, Norwegian, and US genetic suppliers. Distribution runs through Rotterdam and Miami consolidators for transoceanic frozen logistics, with direct farm-gate contracts gaining share in North American foodservice corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with hatchery-to-harvest certification acceleration and captive feed milling capacity serving as the decisive upstream levers separating premium-tier pricing access from commodity margin compression.
For Market Incumbents: Hedge against Atlantic salmon substitution pressure by deepening backward integration into proprietary broodstock genetics and single-cell protein feed milling. Secure long-term supply contracts with European retail banners before ASC certification timelines compress further. Accelerate land-based recirculating system deployment near Chicago and Denver population centers to defend direct-to-restaurant channel share against Chilean frozen imports.
For New Entrants and Emerging Players: Capture white space in Poland's smoked trout specialty retail, where traditional smokehouse culture meets underdeveloped branded ASC-certified presence. Target US federal foodservice contracts leveraging USDA BioPreferred procurement preference points for domestically farmed, sustainably certified supply. Lead with blockchain-tracked traceability documentation as the primary go-to-market wedge against incumbent commodity suppliers.
For Investors and Strategic Acquirers: ASC certification audit completion timelines stretching to 18 months is the leading indicator that land-based recirculating system operators with existing certifications command scarcity premia in acquisition markets. Long-term viability favors vertically integrated mid-cap specialists with hatchery-to-harvest control and AI-driven water quality platforms. Monitor weekly Norwegian Food Safety Authority sea lice reporting thresholds as the inflection signal for veterinary cost escalation across open-pen operators.
| Strategic Initiative | Industry Significance |
|---|---|
| ASC Certification Acceleration | Locks shelf placement with German and French retail banners requiring lot-level blockchain documentation. |
| Single-Cell Protein Feed Integration | Reduces marine fishmeal dependence while satisfying retailer sustainability scorecards for premium positioning. |
| Land-Based RAS Capacity Expansion | Enables 48-hour freshness guarantees to Chicago and Denver restaurant groups bypassing distributor margins. |
| Direct Farm-Gate Contracting | Captures foodservice procurement consolidation by compressing handling stages and verifying origin claims. |
| AI-Driven Water Quality Licensing | Creates recurring revenue streams from modular platform deployment across third-party inland operations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hatchery managers, processing plant operators, retail category buyers, foodservice procurement directors, and feed formulation specialists. Norwegian Food Safety Authority weekly reporting databases, EU Common Fisheries Policy traceability registries, SERNAPESCA export certifications, and USDA BioPreferred program disclosures supplied validation benchmarks. Bottom-up farm-level production estimates and top-down trade flow reconstructions were triangulated against import-export statistics.
Granularity-level modeling captured product type splits across fresh, frozen, smoked, and whole formats; distribution channel dynamics spanning retail, wholesale, online, and direct sales; and end-user segmentation across households, restaurants, retailers, and aquaculture operations. CAGRs were derived from production capacity expansion pipelines, regulatory compliance timeline assumptions, and substitution elasticity estimates against Atlantic salmon across the projection horizon. Feed ingredient cost trajectories and certification adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to marine ingredient price volatility, ASC audit timeline compression, and sea lice treatment resistance patterns. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and retailer sustainability scorecard evolution. Practitioners should monitor Peruvian anchovy quota announcements, Norwegian sea lice threshold adjustments, and EU REACH chemical authorization updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Hydrolysate Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Canned Anchovy Market
Seafood
Saudi Arabia Seafood Market
Seafood
Global White Shrimp Market
Seafood
Crustacean Market
Seafood
Europe Salmon Market
Seafood
Canned Tuna Market
Seafood
Crayfish Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
South America Canned Seafood Market
Seafood
United States Seafood Market
Seafood
Sea Bream Market
Seafood
Dried Scallop Market
Seafood
North America Seafood Market
Seafood
Wild Pollock Market