
 Global Frozen and Canned Seafood Market | 2026-2036
Global Frozen and Canned Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Global Frozen and Canned Seafood Market Foresight
Foodservice procurement is consolidating around premium frozen species and value-added canned formats. Thai Union Group PCL leverages its integrated supply chain across tuna and shrimp categories to sustain volume leadership in European retail channels. Maruha Nichiro Corporation anchors its position through deep cold storage networks and Japanese domestic distribution control. Mowi ASA specializes in Atlantic salmon frozen fillets, competing on traceability credentials and aquaculture certification standards.
Frozen and canned seafood comprises finfish, shellfish, and cephalopods preserved through blast freezing at minus 18 degrees Celsius or thermal processing in hermetically sealed containers, with shelf stability ranging from 12 to 36 months depending on method and packaging barrier properties. These products serve commercial food preparation, retail distribution, and direct household consumption where fresh supply remains intermittent or cost-prohibitive. Frozen fish occupies the largest value share across retail and foodservice channels, while canned crustaceans command premium positioning in specialty stores and gift markets. Vacuum packs and modified atmosphere trays are gaining traction in supermarket chilled sections, displacing conventional bulk frozen blocks where convenience and portion control drive purchase decisions.
FDA seafood HACCP regulations, EU REACH compliance for packaging materials, and Japan's Food Sanitation Act collectively govern import access, labeling integrity, and contaminant thresholds across major destination markets. ECHA restrictions on bisphenol-A in can linings are accelerating migration toward polyester and oleoresin coatings, adding reformulation costs for suppliers serving European buyers. Stakeholders must monitor evolving MEE discharge standards in China and emerging ESG disclosure requirements under EU CSRD, as these frameworks will increasingly determine processor eligibility for contract volumes with multinational retailers.
Market Dynamics
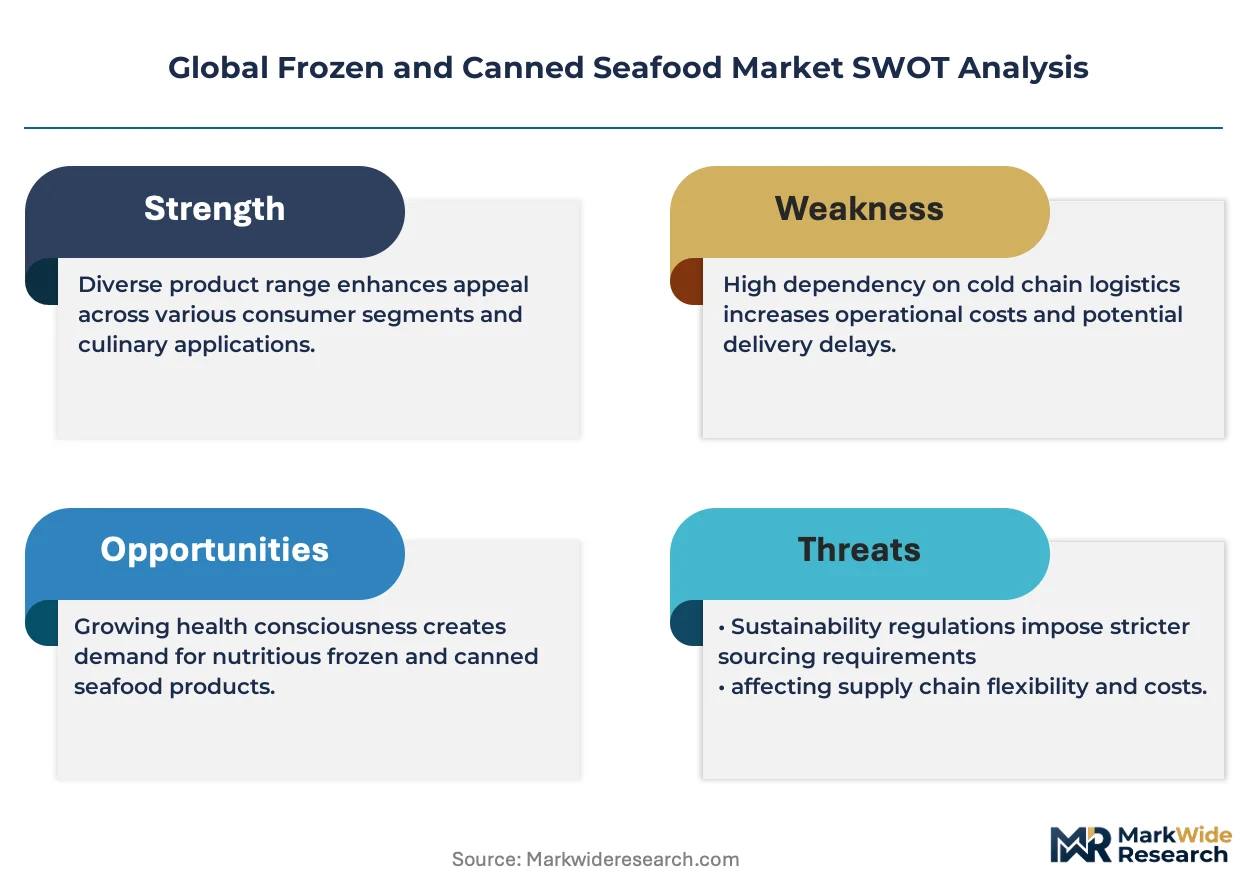
EU hygiene regulations under EC 853/2004 and ECHA restrictions on bisphenol-A are forcing processors to rebuild can-lining formulations and cold chain documentation systems simultaneously. Foodservice procurement consolidation around premium frozen cephalopod and shellfish is compressing supplier margins while demanding traceability upgrades.
Growth Catalysts
- Cold chain infrastructure expansion:Vietnam, Thailand, and Indonesia are deepening export capacity through port refrigeration investments and blast freezing at minus 18 degrees Celsius, enabling longer shelf stability for finfish and cephalopods.
- EC 853/2004 compliance mandates:EU hygiene regulations are standardizing processing documentation across Southeast Asian hubs, qualifying more suppliers for European retail and foodservice contract volumes.
- Vacuum packaging adoption:Modified atmosphere trays are displacing conventional bulk frozen blocks in supermarket chilled sections where convenience and portion control drive purchase decisions.
Market Restraints
- Input cost volatility:Wild catch quotas and aquaculture feed prices create margin pressure for Atlantic salmon and tuna processors dependent on finite marine biomass.
- Supply concentration risk:Processing gravity centers on Vietnam, Thailand, and Indonesia, exposing buyers to port congestion and climate-related disruption in the Mekong Delta and Gulf of Thailand.
- ECHA reformulation costs:Migration from bisphenol-A can linings toward polyester and oleoresin coatings adds capital expenditure for suppliers serving European buyers under REACH compliance.
Strategic Opportunities
- Underpenetrated African retail:Cold chain gaps in Nigeria, Kenya, and South Africa create first-mover potential for frozen fillet distribution through supermarket format expansion.
- EU CSRD disclosure readiness:Early alignment with emerging ESG reporting requirements will determine processor eligibility for multinational retailer contract volumes before 2025 implementation.
- Direct-to-foodservice platforms:Digital procurement channels are compressing distributor layers between Southeast Asian processors and European restaurant chains seeking traceable cephalopod supply.
Industry Challenges
- HACCP certification timelines:FDA seafood HACCP compliance for US market access requires 12-18 month documentation cycles that delay revenue recognition for new processing entrants.
- Cold storage capex intensity:Deep freezing infrastructure and hermetic sealing equipment demand capital deployment that strains mid-scale processors competing with integrated multinationals.
- Legacy system integration:Traceability software for EU REACH and Japan's Food Sanitation Act must interface with existing ERP platforms, creating data architecture friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Frozen and Canned Seafood Market |
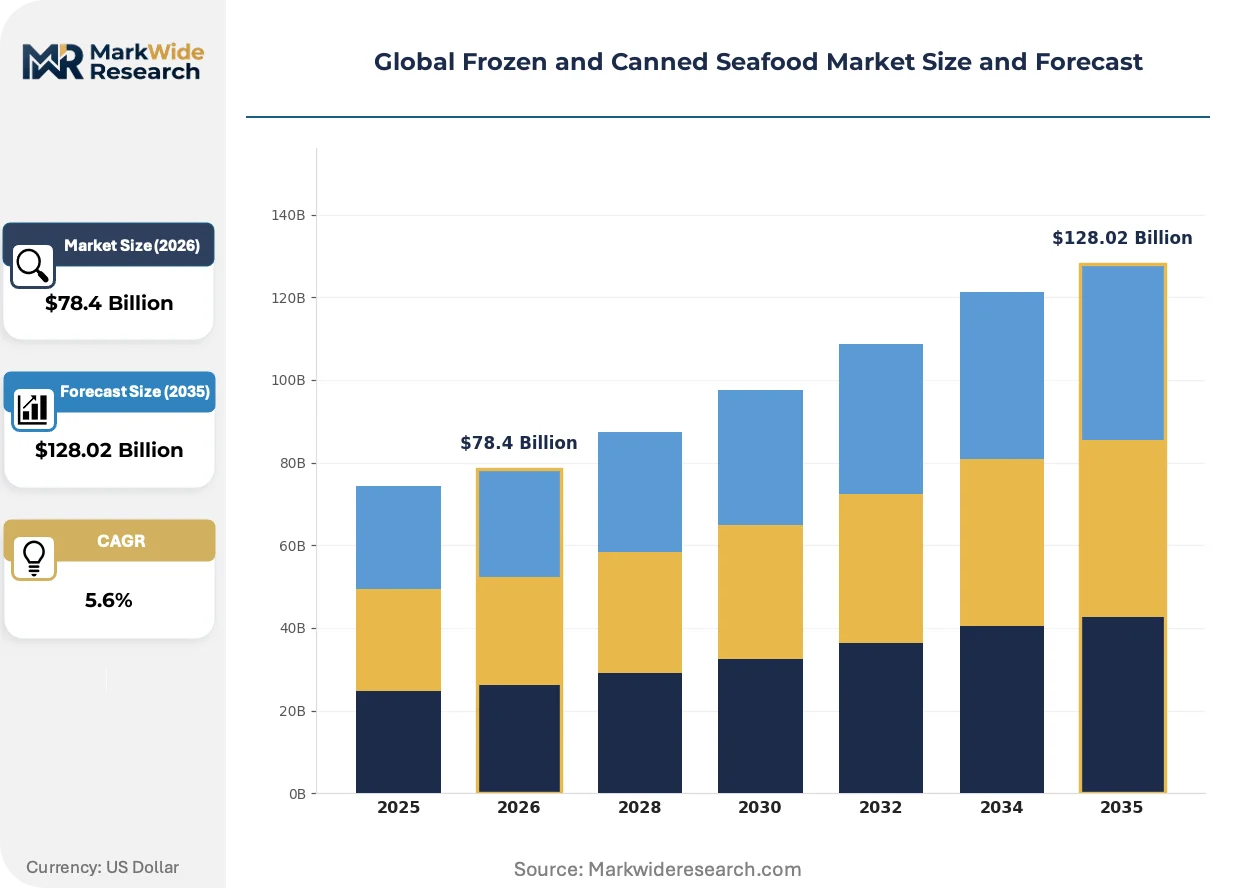
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Frozen Fish, Frozen Shellfish, Canned Fish, Canned Crustaceans, Frozen Cephalopods Packaging Type: Vacuum Packs, Tins, Bottles, Trays, Cartons, Jars Application: Foodservice, Retail, Institutional Catering, Household Consumption, Food Processing End User: Supermarkets, Restaurants, Wholesalers, Food Manufacturers, Specialty Stores |
| Companies Covered | Thai Union Group PCL, Maruha Nichiro Corporation, Mowi ASA, Trident Seafoods Corporation, High Liner Foods Inc., Nippon Suisan Kaisha Ltd, Bolton Group, StarKist Co., Dongwon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Frozen and Canned Seafood Market Shifts & Advancements
Processing technology and regulatory chemistry are converging to redefine preservation economics. Automation of quality verification and can-lining reformulation are compressing cost structures while procurement platforms restructure distribution layers.
Hyperspectral imaging systems are automating real-time detection of parasite loads and freshness markers in tuna and salmon fillets. Large-scale processors in Thailand and Vietnam are deploying these systems to reduce manual inspection labor and accelerate FDA HACCP documentation. This automation is compressing the gap between catch landing and blast freezing certification, tightening cold chain integrity windows.
REACH restrictions on bisphenol-A are mandating polyester and oleoresin coatings in can linings across European import supply chains. Reformulation timelines extend 18-24 months for coating suppliers, delaying processor recertification. Canned crustacean and premium shellfish segments face the steepest cost pass-through as gift-market buyers resist price elasticity.
Foodservice chains are consolidating supplier relationships around integrated processors with captive cold storage and direct logistics control. European restaurant groups are bypassing traditional seafood distributors to contract Thai and Vietnamese processors for frozen cephalopod and value-added shrimp. This channel compression is most visible in Germany and the Netherlands where procurement teams prioritize traceability credentials over distributor relationships.
Global Frozen and Canned Seafood Market Segmentation
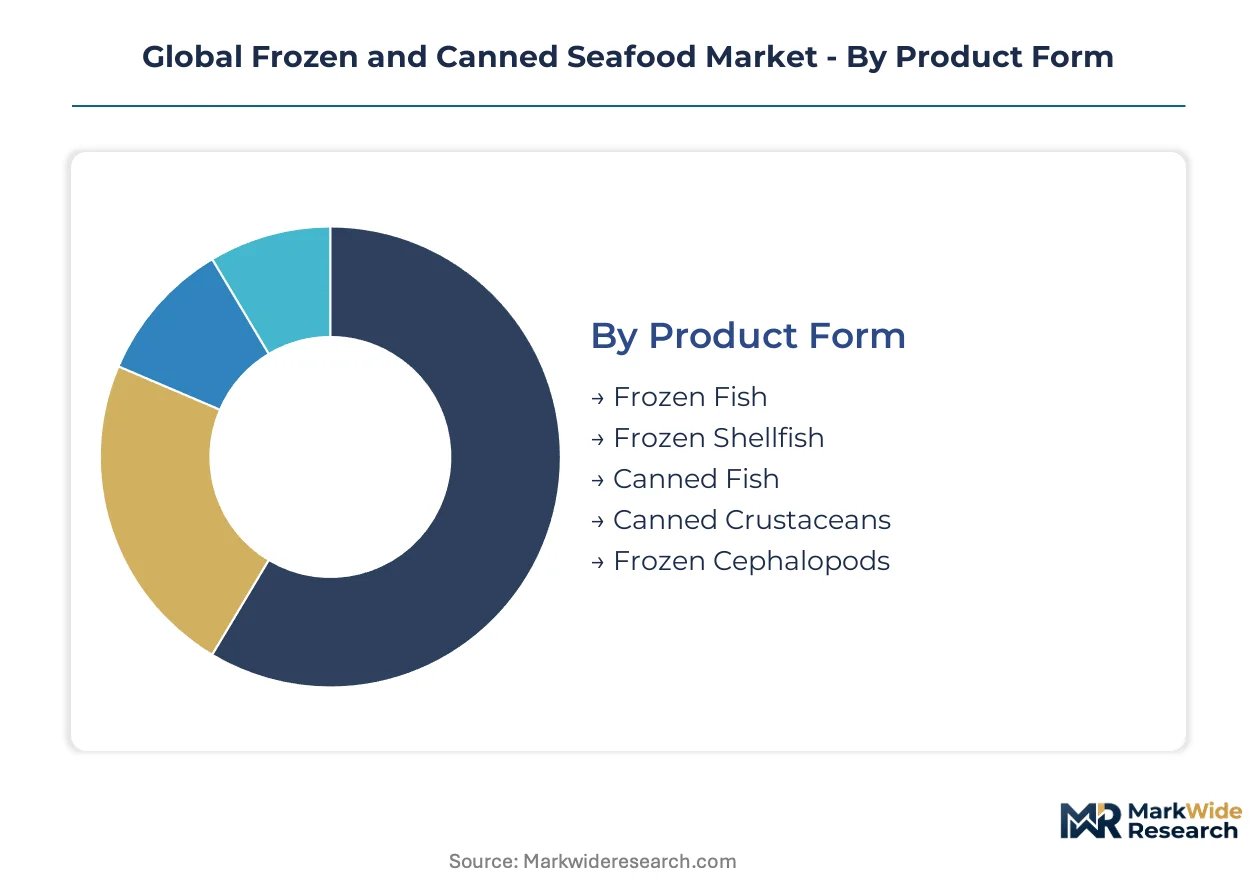
Segmentation in frozen and canned seafood reveals how regulatory burdens, preservation economics, and distribution infrastructure fragment procurement strategies across buyer types. Each dimension carries distinct certification requirements that determine supplier eligibility for contract volumes in major destination markets.
Product Form:
FDA seafood HACCP applies universally across all product forms, while EU EC 853/2004 hygiene documentation demands escalate for frozen cephalopods and canned crustaceans entering European retail channels. Japan's Food Sanitation Act imposes additional parasite testing protocols on frozen finfish destined for sashimi-grade applications.
- Frozen Fish:Blast-frozen finfish at minus 18 degrees Celsius dominates retail and foodservice procurement for Atlantic salmon, tuna, and whitefish species. Demand concentrates in European supermarket chains where traceability credentials and aquaculture certification standards determine shelf placement.
- Frozen Shellfish:Mussels, oysters, and scallops preserved through individual quick freezing retain texture profiles critical for restaurant preparation. Vietnamese and Thai processors are expanding cold storage capacity to capture foodservice contract volumes from German and Dutch restaurant groups.
- Canned Fish:Thermal-processed tuna and mackerel in hermetically sealed containers serve household consumption where fresh supply remains intermittent. ECHA REACH compliance for can linings adds reformulation costs for suppliers serving European buyers.
- Canned Crustaceans:Premium crab and lobster meat in sealed containers commands gift-market positioning in Japan and South Korea. Buyers in these markets resist price elasticity, passing through coating reformulation costs from bisphenol-A migration.
- Frozen Cephalopods:Squid and octopus segments preserved for extended shelf stability supply European restaurant chains seeking menu diversification. Indonesian processors are deepening export capacity through port refrigeration investments.
Leading the category by volume: Frozen Fish. Growing fastest: Frozen Cephalopods.
Packaging Type:
Cost tiers separate commodity bulk formats from premium convenience packaging, with vacuum and modified atmosphere technologies commanding price premiums in retail channels.
- Vacuum Packs:Barrier film systems removing oxygen to extend shelf life are displacing conventional bulk frozen blocks in supermarket chilled sections. European retail buyers prioritize portion control and convenience.
- Tins:Metal containers with hermetic seals remain the standard for thermal-processed fish and crustaceans. ECHA restrictions on bisphenol-A linings are accelerating coating migration toward polyester and oleoresin alternatives.
- Bottles:Glass and polymer containers for marinated and sauced seafood products serve specialty store distribution. Japanese gift markets favor transparent packaging for premium shellfish presentation.
- Trays:Modified atmosphere packaging in rigid plastic formats supports fresh-frozen positioning in retail chilled sections. German supermarket chains are consolidating procurement around tray formats for salmon and whitefish fillets.
- Cartons:Paperboard secondary packaging for retail multipacks and foodservice bulk formats. Sustainability credentials drive adoption in Nordic retail channels.
- Jars:Glass containers for pickled and preserved seafood products targeting household consumption in Mediterranean markets. Italian and Spanish retail buyers maintain strong jar format preferences for anchovy and sardine products.
Standard formats dominate volume: Tins. Premium packaging expanding most quickly: Vacuum Packs.
Application:
Customer type determines traceability depth and documentation intensity, with foodservice and food processing demanding the most rigorous cold chain verification.
- Foodservice:Restaurant and hotel procurement of frozen cephalopod and shellfish requires HACCP documentation and direct processor relationships. European chains are bypassing distributors to contract Southeast Asian suppliers.
- Retail:Supermarket and specialty store distribution of frozen fillets and canned products demands barcode traceability and certification labeling. EU CSRD disclosure requirements will determine processor eligibility for multinational retailer contracts.
- Institutional Catering:Hospital, school, and corporate cafeteria procurement prioritizes cost-controlled bulk formats with extended shelf stability. Tender processes favor suppliers with integrated cold storage networks.
- Household Consumption:Direct consumer purchase of canned and frozen seafood for home preparation concentrates in urban markets with cold chain reliability. Nigerian and Kenyan supermarket expansion creates first-mover potential.
- Food Processing:Ingredient supply to ready-meal and seafood product manufacturers requires consistent specification and volume guarantees. Thai and Vietnamese processors are capturing contract volumes through captive raw material supply.
Retail maintains volume leadership. Foodservice climbs fastest as menu diversification accelerates.
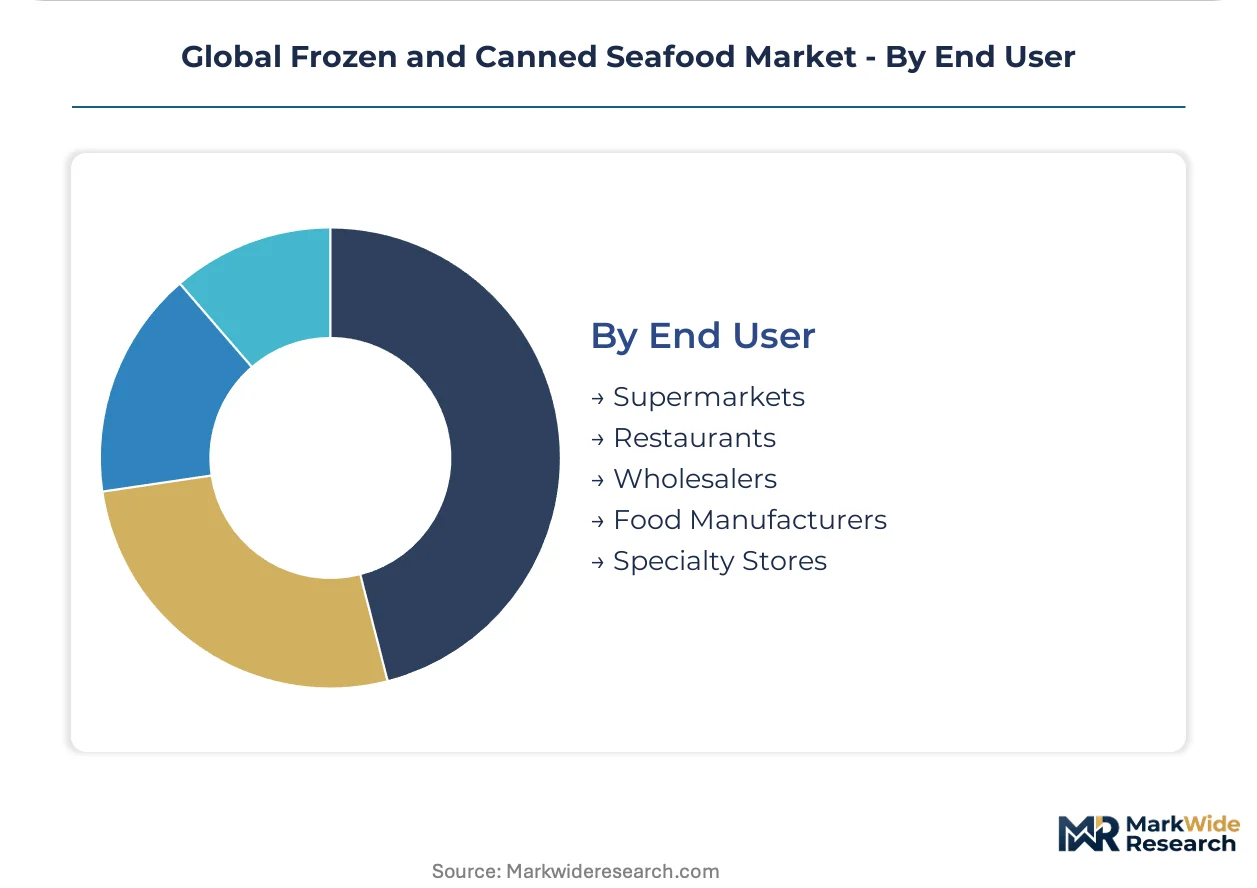
End User:
Supply concentration varies sharply by buyer scale, with multinational supermarkets and integrated restaurant groups consolidating procurement around traceable Southeast Asian processors.
- Supermarkets:Large-format retail chains in Germany, Netherlands, and France are standardizing vacuum pack and modified atmosphere tray formats. Private label programs demand full supply chain visibility.
- Restaurants:European restaurant groups in Germany and Netherlands prioritize direct contracts with Thai and Vietnamese processors for frozen cephalopod. Digital procurement platforms compress distributor layers.
- Wholesalers:Traditional distribution intermediaries face margin compression as foodservice chains consolidate direct supplier relationships. Cold storage asset ownership determines survival.
- Food Manufacturers:Ready-meal and processed seafood producers require consistent raw material specifications and volume guarantees. Integrated processors with captive supply chains capture contract volumes.
- Specialty Stores:Premium canned crustacean and gift-format seafood distribution in Japan and South Korea commands highest price realization. ECHA coating reformulation costs pass through most easily in this channel.
Supermarkets lead by procurement volume. Restaurants gain share fastest through direct sourcing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam, Thailand, and Indonesia concentrate blast-freezing capacity for European and Japanese export markets. Cold chain infrastructure investments in Haiphong, Samut Sakhon, and Surabaya are reshaping processing gravity toward Southeast Asian hubs.
Vietnam
Frozen cephalopod exports to Germany and the Netherlands drive port refrigeration expansion in Haiphong and Ho Chi Minh City. MEE discharge standards govern wastewater treatment investments in Mekong Delta processing zones. Vietnamese processors are capturing direct foodservice contracts from European restaurant chains seeking traceable squid supply.
Thailand
Tuna and shrimp value-added formats dominate retail procurement from British and French supermarket chains. EU EC 853/2004 hygiene documentation mandates are standardizing cold chain verification systems in Samut Sakhon. Thai processors are deploying hyperspectral imaging to accelerate FDA HACCP certification for US market access.
Indonesia
Squid and octopus segments supply Japanese sashimi-grade applications with parasite testing under the Food Sanitation Act. Port refrigeration investments in Surabaya and Makassar are deepening export capacity for frozen cephalopod. Indonesian processors are consolidating around integrated cold storage networks to qualify for multinational retailer contracts.
United States
Alaska pollock and Pacific cod frozen fillets serve domestic retail and foodservice channels with 12-18 month HACCP documentation cycles. FDA seafood HACCP regulations govern import access for Southeast Asian processors. Seattle-based distributors are compressing supply layers through direct procurement platforms with Thai and Vietnamese suppliers.
Japan
Premium canned crustacean gift markets command highest price realization in Tokyo and Osaka retail channels. METI standards and the Food Sanitation Act impose additional testing protocols on frozen finfish. Japanese trading houses are securing captive supply through equity stakes in Indonesian and Thai processing ventures.
Global Frozen and Canned Seafood Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals controlling retail shelf placement and mid-scale processors serving foodservice direct contracts. Market structure tilts toward consolidation in frozen salmon and tuna categories where traceability certifications create entry barriers. Three archetypes dominate: vertically integrated conglomerates with captive cold storage, species-specialist aquaculture operators, and regional processing cooperatives serving export markets. Competitive moves concentrate on M&A for cold chain asset acquisition and strategic partnerships with foodservice procurement platforms.
Among Thailand-based conglomerates, Thai Union Group PCL exemplifies integrated supply chain control across tuna and shrimp categories. Japanese corporate groups represented by Maruha Nichiro Corporation anchor positions through deep cold storage networks and domestic distribution infrastructure. Norwegian aquaculture specialists including Mowi ASA occupy positions built on Atlantic salmon traceability credentials and certification standards. These three archetypes illustrate how geographic origin and corporate structure shape competitive positioning in frozen and canned seafood procurement.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| Maruha Nichiro Corporation |
| Mowi ASA |
| Trident Seafoods Corporation |
| High Liner Foods Inc. |
| Nippon Suisan Kaisha Ltd |
| Bolton Group |
| StarKist Co. |
| Dongwon Industries |
| Others |
Supply & Pricing Matrix
Hyperspectral imaging deployment across Thai and Vietnamese processing lines is compressing quality verification labor costs while simultaneously concentrating procurement power among capital-rich operators capable of absorbing automation capex. This technology transition widens the gap between integrated multinationals and mid-scale processors, reshaping how frozen cephalopod and shellfish contracts are priced across European foodservice channels.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with European restaurant chains paying 15-25% markups for guaranteed two-week delivery windows on frozen squid and octopus versus spot-market inventory clearing at discount. Three-tier pricing structure across premium traceability-certified, standard HACCP-compliant, and economy-grade frozen blocks reflects EU EC 853/2004 documentation intensity. Cost compression in the economy tier is intensifying because Indonesian processors are flooding spot markets with uncontracted volume. Institutional catering buyers exhibit highest price sensitivity, while Japanese gift-market purchasers of canned crustaceans resist elasticity entirely.
Supply Chain Analysis
Workforce availability constraints in Samut Sakhon and Haiphong are forcing processors to automate blast-freezing lines faster than depreciation schedules originally planned. Supply concentrates in Vietnam, Thailand, and Indonesia, with raw material draws from Alaska pollock fisheries, Peruvian anchovy reduction fisheries, and Indian Ocean tuna longline fleets. Single-source vulnerability runs through the Mekong Delta, where MEE discharge enforcement could shutter processing zones without warning. Distribution runs through Rotterdam and Hamburg cold storage hubs before final mile delivery to German and Dutch supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU REACH can-lining reformulation and FDA HACCP certification timelines erect barrier-to-entry moats favoring processors with dedicated regulatory affairs staff and captive laboratory testing capacity.
For Market Incumbents: Lock in direct foodservice contracts with German and Dutch restaurant groups before digital procurement platforms fully disintermediate traditional distributors. Defend margin position by accelerating backward integration into cold storage networks in Haiphong and Surabaya, neutralizing port congestion risk that threatens delivery reliability premiums. Prioritize EU CSRD disclosure readiness to secure multinational retailer shelf placement ahead of 2025 implementation.
For New Entrants and Emerging Players: Hyperspectral imaging as-a-service offerings create technology-first wedge opportunities for mid-scale Vietnamese and Indonesian processors unable to fund capital purchase outright. Target underpenetrated African retail in Nigeria and Kenya where supermarket format expansion outruns local cold chain infrastructure. Deploy direct-to-foodservice digital platforms to bypass wholesaler layers and capture traceability premiums from European restaurant procurement teams.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated Southeast Asian processors with captive cold storage and established EU retail relationships. Long-term viability over the coming decade hinges on regulatory compliance automation rather than raw volume scale. Watch for ECHA coating reformulation completion rates as the inflection signal separating acquisition-ready targets from stranded asset risks.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Storage Network Expansion | Captive freezing capacity in Haiphong and Surabaya secures EU contract eligibility under EC 853/2004. |
| Can-Lining Reformulation Partnership | Polyester and oleoresin coating supplier alliances accelerate REACH compliance for European retail access. |
| Hyperspectral Imaging Deployment | Automated parasite detection compresses FDA HACCP documentation cycles for US market entry. |
| Direct-to-Foodservice Platform Launch | Digital procurement channels displace traditional wholesalers in German and Dutch restaurant supply. |
| Traceability Certification Investment | Aquaculture stewardship and chain-of-custody credentials command shelf placement premiums in Nordic retail. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with seafood processing plant managers, European retail category buyers, foodservice procurement directors, cold storage logistics operators, and regulatory compliance officers. FDA seafood HACCP guidance documents, EU EC 853/2004 implementing measures, ECHA REACH restriction dossiers, and Japan Food Sanitation Act enforcement bulletins provided secondary validation. Bottom-up volume modeling across product forms and packaging types triangulated against top-down trade flow analysis.
Data-stream reconciliation between export statistics from Vietnam Customs, Thai Ministry of Commerce trade registers, and import declarations to EU TRACES database resolved discrepancies across the analysis window. Segmentation dimensions modeled include product form, packaging technology, application channel, and end-user scale, with CAGRs derived from regression against cold chain infrastructure investment flows and regulatory implementation timelines. Wild catch quota announcements and aquaculture feed price indices fed directly into margin compression scenarios for Atlantic salmon and tuna processors.
Several conditions sit outside the modeled scope, including abrupt climate events disrupting Mekong Delta processing zones, geopolitical trade restrictions affecting Southeast Asian export access, and unforeseen ECHA substance restrictions beyond bisphenol-A. Forecasts reflect assumptions of continued EU regulatory enforcement intensity and stable cold chain infrastructure investment rates across Vietnamese, Thai, and Indonesian port zones. Material deviation in wild biomass availability or REACH reformulation cost pass-through elasticity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
GCC Seafood Market
Seafood
Canned Fishery Product Market
Seafood
Canned Mackerel Market
Seafood
Molluscs Market
Seafood
Cod Fish Market
Seafood
Fish Protein Hydrolysate Market
Seafood
Global Seafood Market
Seafood
Milkfish Market
Seafood
Oyster Market
Seafood
Latin America Salmon Market
Seafood
Asia-Pacific Shrimp Market
Seafood
United States Salmon Market
Seafood
Canned Salmon Market
Seafood
Middle East Seafood Market
Seafood
Europe Shrimp Market
Seafood
Europe Lobster Market