
 Tinned Fish Market | 2026-2036
Tinned Fish Market Size, Share, and Industry Trends Forecast 2026-2036
Tinned Fish Market Outlook
Multi-pack bundling and curated variety packs is expanding consumer trial across premium and everyday price points. Thai Union Group PLC leverages its integrated supply chain from catch to can to sustain cost advantages in tuna sourcing. Bolton Group anchors European distribution through established retail partnerships across multiple countries. Wild Planet Foods Inc. differentiates with pole-and-line caught positioning in the North American specialty channel.
Tinned fish comprises seafood preserved through thermal processing in hermetically sealed containers, typically achieving commercial sterility at F0 values exceeding three minutes to ensure shelf stability without refrigeration. The product serves as a protein source for retail households and as an ingredient for food manufacturers requiring consistent supply outside fresh fish seasonality. Tuna dominates volume across most retail markets due to its versatility and established consumer recognition, while salmon commands premium positioning in pouches and glass jars where perceived quality justifies higher price points. The food service channel shows structural momentum as restaurants incorporate tinned fish into menu items beyond traditional appetizer applications.
FDA regulations govern low-acid canned food standards in the United States, requiring strict thermal process documentation and facility registration that shapes manufacturing investment decisions. EU REACH and F-Gas Regulation affect coating materials and refrigeration in processing facilities, while EFSA standards on contaminant limits influence sourcing geography for European market access. Stakeholders must monitor evolving extended producer responsibility frameworks for packaging waste as these rules increasingly determine competitive viability across export markets.
Market Dynamics
EU extended producer responsibility frameworks for packaging waste are forcing processors to redesign can coatings and secondary packaging formats ahead of enforcement deadlines, compressing supplier qualification timelines.
Growth Catalysts
- REACH-compliant coating materials:Manufacturers adopting BPA-NI epoxy alternatives gain automatic shelf access across German and French retail banners. Reformulation investments now qualify for green transition financing under EU Green Deal implementation funds.
- Food service menu integration:Restaurants in Madrid, Lisbon, and Milan are expanding tinned fish beyond appetizer plates into pasta mains and composed salads. This channel absorbs higher-margin glass jar formats that supermarkets move slowly.
- Pole-and-line sourcing concentration:Coastal communities in the Maldives and Indonesia maintain MSC certification density that satisfies EFSA contaminant thresholds. Processors with direct offtake agreements bypass auction volatility.
Market Restraints
- Skipjack tuna price volatility:Bangkok auction prices swing with El Niño cycles, compressing processor margins when long-term retail contracts fix shelf prices. Smaller canneries lack frozen inventory capacity to smooth input costs.
- Single-source glass jar supply:European pharmaceutical-grade glass capacity concentrates in Germany and Italy, creating bottlenecks when artisanal brands scale. Lead times for amber and flint variants now exceed sixteen weeks.
- Substitute protein competition:Plant-based tuna analogs from soy and pea protein isolate gain trial among flexitarian households in urban UK and Netherlands markets. These products bypass thermal processing regulations that constrain conventional tinned fish.
Strategic Opportunities
- Direct-to-restaurant distribution:Bypassing wholesale intermediaries lets specialty canneries capture food service margin pools in Barcelona and Rome. Digital ordering platforms reduce route-to-market establishment costs.
- EU F-Gas Regulation retrofit incentives:Processing facilities replacing refrigeration systems with ammonia or CO2 circuits qualify for national recovery fund grants. Early movers lock in operating cost advantages as hydrofluorocarbon phase-down accelerates.
- Subscription variety boxes:Curated monthly shipments of regional Portuguese and Spanish conservas build recurring revenue and consumer education. This format justifies premium pricing through discovery value rather than commodity comparison.
Industry Challenges
- Retort operator skill scarcity:Thermal process validation requires F0 calculation expertise that vocational programs in Portugal and Spain no longer produce at scale. Canneries compete for aging specialists approaching retirement.
- Legacy ERP integration with traceability platforms:Batch-level digital passport requirements under incoming EU DPP regulation clash with AS/400 systems common in family-owned processors. Middleware development consumes IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinned Fish Market |
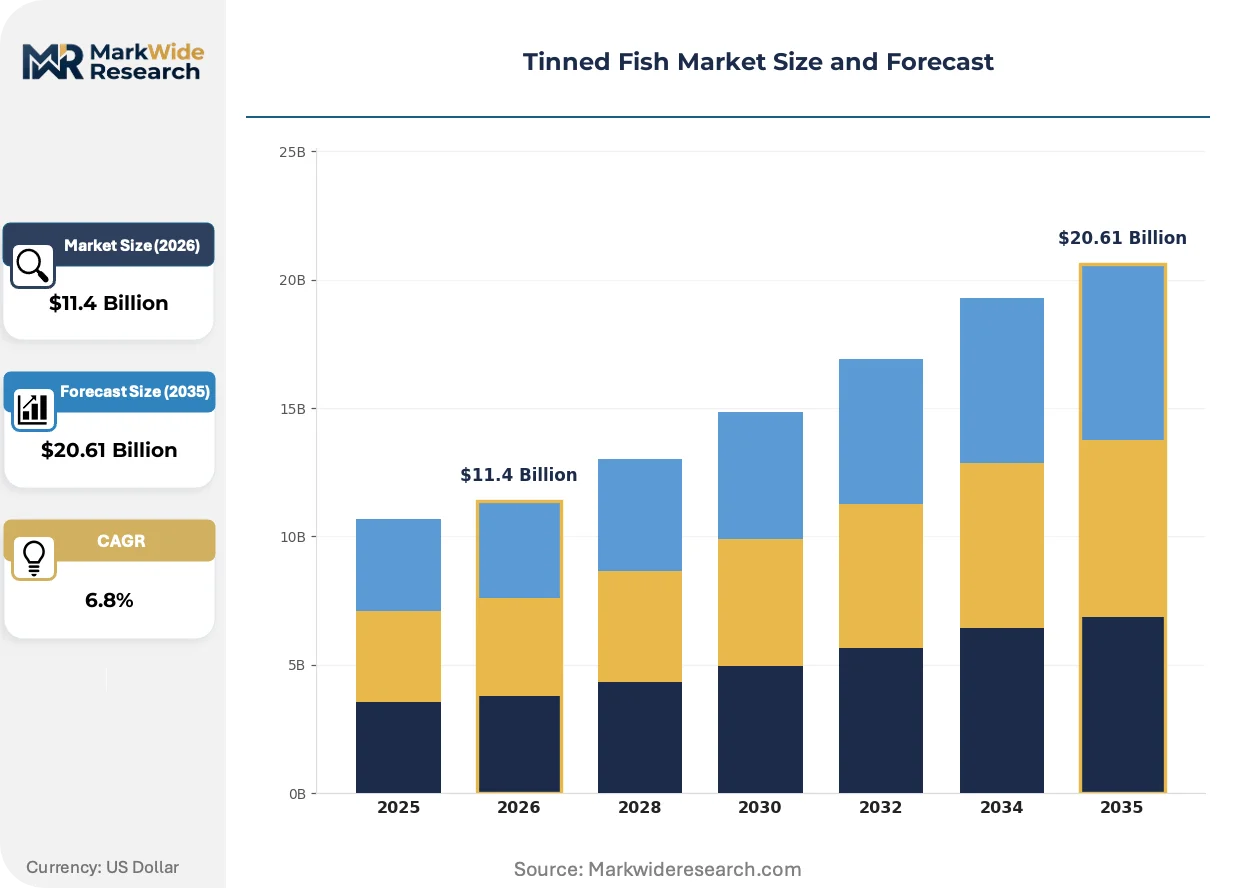
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuna, Salmon, Sardines, Mackerel Packaging Type: Cans, Pouches, Glass Jars, Tetra Pak Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service End User: Households, Restaurants, Caterers, Food Manufacturers |
| Companies Covered | Bolton Group, Wild Planet Foods Inc., Thai Union Group PLC, American Tuna Inc., Bumble Bee Foods LLC, Maruha Nichiro Corporation, Century Pacific Food Inc., Frinsa Group, Dongwon Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinned Fish Market Strategic Shifts
Packaging material substitution and thermal process digitization are compressing traditional competitive moats while opening premium positioning paths for agile processors.
Retort pouch formats with aluminum oxide barrier layers are rewriting shelf-stable seafood economics. UK and Netherlands retail buyers are adopting these SKUs for lunchbox convenience segments. The format enables 40% weight reduction in finished goods logistics, compressing freight cost structures for distant export markets.
EU Deforestation Regulation due diligence requirements are reshaping soybean and palm oil sourcing for canning oils. Processors must document supply chain geolocation data back to farm level by late 2025. Italian and Spanish brands with existing organic certification infrastructure are adapting faster than commodity competitors.
Restaurant procurement departments are consolidating supplier lists around single-source traceability. Group purchasing organizations in France and Belgium now require blockchain-verified catch documentation. This behavior concentrates volume with vertically integrated processors while fragmenting spot-market dependent competitors.
Tinned Fish Market Segmentation
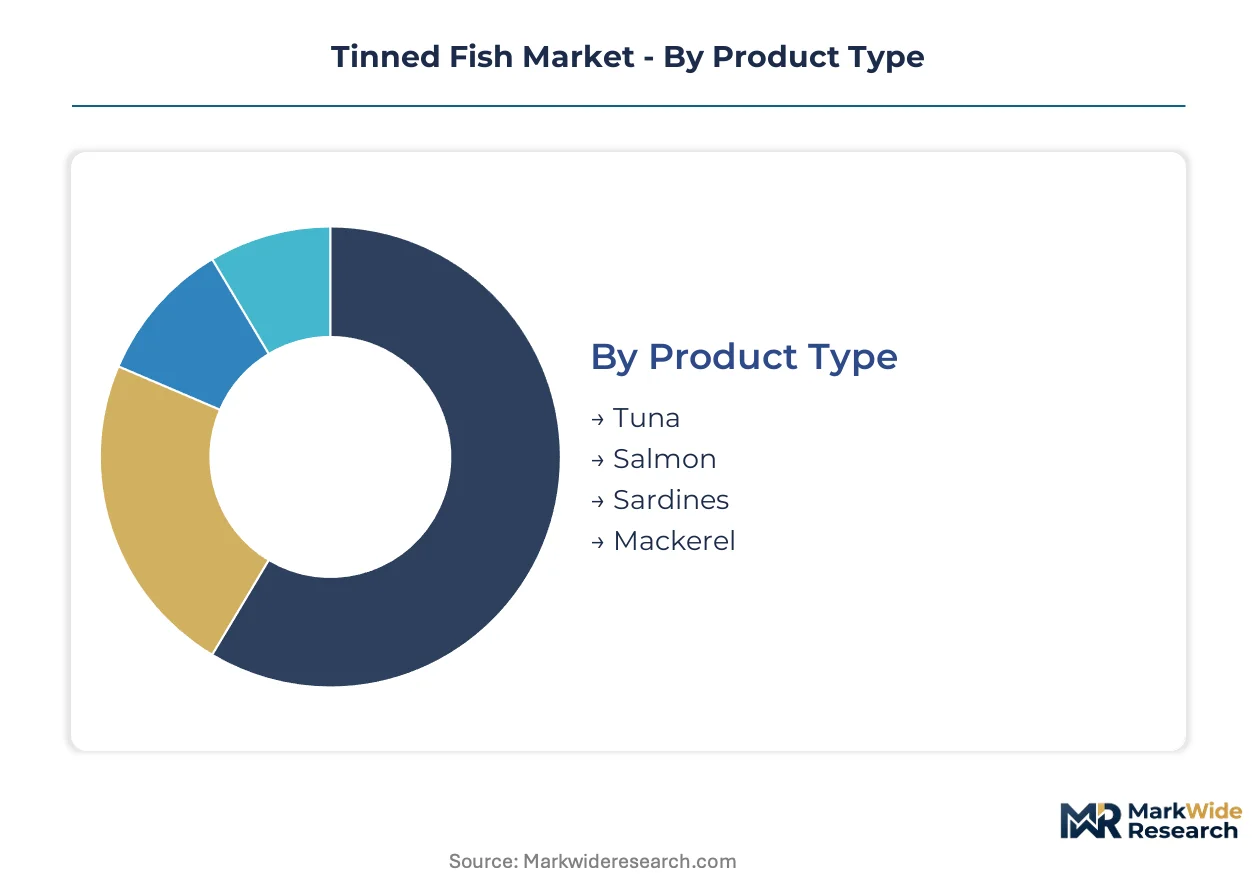
Segmentation in tinned fish reveals how processing specifications, container engineering, and route-to-market economics partition value capture. Manufacturers configure thermal processing lines and coating formulations around specific product-packaging combinations that match regulatory thresholds and retail buyer requirements.
Product Type:
Species selection determines thermal processing parameters, oil medium compatibility, and achievable shelf life under ambient distribution.
- Tuna:Skipjack and yellowfin varieties dominate volume throughput at canneries due to consistent flesh density that validates to F0 standards without texture degradation. Spanish and Portuguese retail banners allocate prime shelf positioning to pole-and-line certified SKUs where EFSA contaminant limits are satisfied through Maldives-sourced offtake agreements.
- Salmon:Pink and sockeye species command glass jar and pouch premiums where smoke-flavored and olive oil pack formats justify price multiples over standard cans. North American specialty channel buyers concentrate procurement on wild-caught Alaskan origin claims that bypass farmed salmon reputational risk.
- Sardines:Portuguese and Spanish conservas tradition sustains artisanal scale production with manual packing into oval tins. Coastal canneries in Matosinhos and Vigo maintain MSC chain of custody for export qualification.
- Mackerel:Higher oil content requires modified thermal processing to prevent lipid oxidation and off-flavor development. Japanese and South Korean import specifications drive fillet orientation standards for aesthetic presentation.
Tuna leads on scale; salmon leads on momentum.
Packaging Type:
Container engineering directly shapes logistics economics, retail shelf differentiation, and regulatory compliance burden across export markets.
- Cans:Three-piece tinplate construction with epoxy-phenolic internal coatings remains the cost-optimized standard for high-volume tuna operations. REACH-compliant BPA-NI reformulations are becoming mandatory for German and French retail access, forcing coating line investments at legacy facilities.
- Pouches:Retortable multilayer structures with aluminum oxide barriers enable 40% weight reduction in finished goods freight. UK and Netherlands lunchbox convenience segments are adopting these SKUs where single-serve portioning matches consumption occasions.
- Glass Jars:Amber and flint pharmaceutical-grade capacity concentrates in German and Italian manufacturing, creating sixteen-week lead time bottlenecks when artisanal brands scale production. Visual transparency supports premium positioning for whole fillet presentation.
- Tetra Pak:Aseptic carton formats with aluminum foil laminates are penetrating ambient seafood segments in Nordic markets where sustainability credentials outweigh traditional can associations. Recyclability claims align with extended producer responsibility frameworks.
Cans dominate absolute volume; pouches are expanding most quickly.
Distribution Channel:
Channel selection determines margin structure, working capital requirements, and the granularity of consumer data available to manufacturers.
- Supermarkets:Banner-controlled shelf space allocation in Spain, Italy, and Portugal prioritizes private label and established brand SKUs with proven velocity. Category managers are expanding facings for premium conservas lines in response to Mediterranean consumption deepening.
- Online Retail:Subscription variety box models build recurring revenue through discovery-oriented curation of regional Portuguese and Spanish specialties. Digital platforms reduce route-to-market establishment costs for emerging canneries.
- Specialty Stores:Italian gastronomia and Portuguese gourmet retailers stock glass jar formats that supermarkets move slowly, absorbing higher-margin production. Staff-assisted selling educates consumers on origin differentiation.
- Food Service:Restaurants in Madrid, Lisbon, and Milan are expanding tinned fish beyond appetizer plates into pasta mains and composed salads. Group purchasing organizations in France and Belgium now require blockchain-verified catch documentation.
Supermarkets anchor volume absorption; food service climbs the fastest.
End User:
Terminal demand segmentation separates household pantry stocking from ingredient procurement governed by food safety certification and supply continuity requirements.
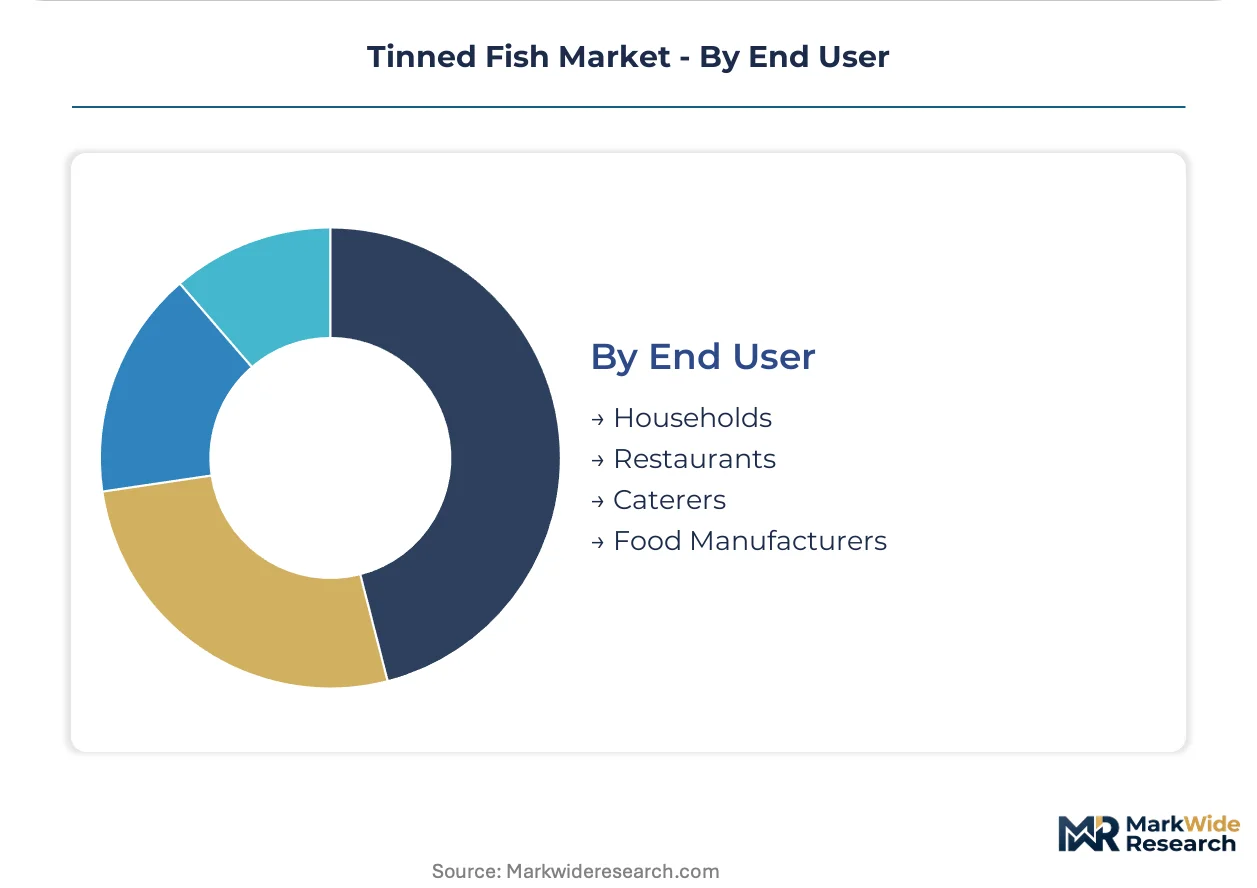
- Households:Retail pantry stocking concentrates in Spain, Portugal, and Italy where per capita consumption traditions support weekly purchase cycles. Multi-pack bundling and curated variety packs expand trial across premium and everyday price points.
- Restaurants:Menu integration as pasta mains and composed salads drives demand for higher-margin glass jar formats with visual presentation value. Direct-to-restaurant distribution bypasses wholesale intermediaries in Barcelona and Rome.
- Caterers:Volume procurement prioritizes consistent specification and ambient storage compatibility for off-site event service. HACCP documentation requirements exceed retail channel standards.
- Food Manufacturers:Ingredient sourcing for prepared meals and seafood spreads requires thermal processing validation and batch-level traceability under incoming EU DPP regulation. Long-term contracts fix pricing through seasonal supply volatility.
Households represent the largest addressable base; restaurants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canning technology for fish preservation originated in France during the Napoleonic era, with Nicolas Appert's hermetic sealing methods establishing the technical foundation that spread to Portugal and Spain by the mid-19th century. These three countries remain the geographic core of artisanal conservas production and premium consumption culture.
Spain
Galician canneries in Vigo and Matosinhos supply MSC-certified sardines and octopus to domestic retail banners and export markets. EFSA contaminant thresholds shape sourcing decisions for skipjack tuna imports from the Indian Ocean. Madrid restaurants drive food service demand through composed conservas plates and pasta integrations.
Portugal
Matosinhos and Aveiro harbor artisanal processors maintaining manual packing traditions for oval tin sardine formats. The national fisheries authority enforces traceability documentation under EU IUU Regulation for export qualification. Lisbon's tasca culture sustains weekly household purchase cycles for multi-pack anchovy and mackerel SKUs.
Italy
Sicilian and Calabrian processors specialize in glass jar tuna and swordfish conservas for gastronomia channel distribution. REACH-compliant BPA-NI coating requirements from ECHA force reformulation investments at legacy canneries in Campania. Milan restaurant procurement departments consolidate supplier lists around blockchain-verified catch documentation.
United States
West Coast pole-and-line tuna processors supply North American specialty retailers with MSC-certified skipjack and albacore. FDA low-acid canned food standards mandate strict thermal process documentation and facility registration. Pacific Northwest direct-to-consumer subscription brands build recurring revenue through curated variety boxes.
Thailand
Bangkok-based integrated processors control frozen inventory capacity to smooth skipjack auction price volatility from El Niño cycles. The national fisheries department coordinates with EFSA on contaminant limit compliance for European market access. Samut Sakhon canneries concentrate high-volume tuna production for global retail private label programs.
Tinned Fish Market Competitive Environment
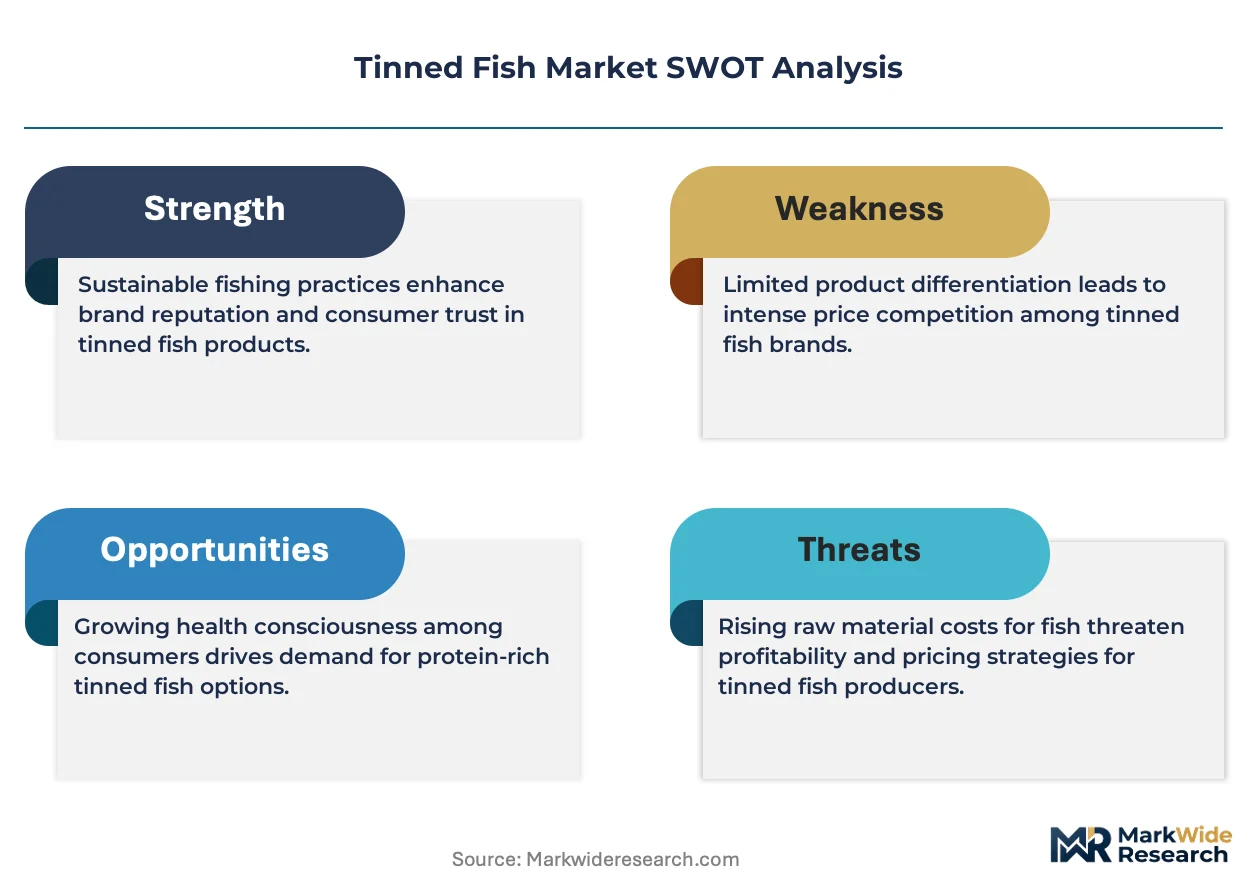
Premium-margin players sit above commodity-margin players across certification tier and packaging format differentiation. The vendor base stratifies between vertically integrated multinational processors with frozen inventory capacity and artisanal canneries dependent on spot-market raw material sourcing. Three archetypes dominate: integrated supply chain operators with direct offtake agreements, specialty conservas houses with heritage positioning, and private label manufacturers serving retail banner programs. Competitive moves concentrate on M&A for MSC certification assets and direct-to-restaurant distribution bypassing wholesale intermediaries.
Within the integrated supply chain tier, Thai Union Group PLC and Maruha Nichiro Corporation represent scale-driven operators with direct offtake agreements in the Maldives and Indonesia. Bolton Group anchors European distribution archetypes through established retail partnerships across multiple countries. Wild Planet Foods Inc. exemplifies specialty channel positioning with pole-and-line caught differentiation in North American markets.
| Leading Market Players |
|---|
| Bolton Group |
| Wild Planet Foods Inc. |
| Thai Union Group PLC |
| American Tuna Inc. |
| Bumble Bee Foods LLC |
| Maruha Nichiro Corporation |
| Century Pacific Food Inc. |
| Frinsa Group |
| Dongwon Industries Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap canneries in Portugal and Spain anchor supply discipline through generational ownership structures that resist quarterly margin pressure, sustaining premium pricing power for MSC-certified conservas while commodity processors in Thailand compete on frozen inventory scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs shelf positioning in European retail banners. Certification grade—specifically MSC chain-of-custody and pole-and-line catch method—separates glass jar premiums from standard tinplate cans. Pricing pressure stems from El Niño-driven skipjack volatility compressing processor margins when retail contracts fix shelf prices. Private label buyers in UK supermarkets show highest price sensitivity, while Italian gastronomia channels absorb premiums for blockchain-verified provenance.
Supply Chain Analysis
Direct-to-restaurant channels handle food service demand growth in Madrid, Lisbon, and Milan, bypassing wholesale intermediaries that dominate supermarket supply. Raw material sourcing concentrates in the Maldives, Indonesia, and Thailand for tuna; Portugal and Spain for sardines and mackerel. Production draws from tinplate coating facilities in Germany and Italy, glass jar manufacturers in pharmaceutical-grade European capacity, and retort pouch converters in the Netherlands. Single-source glass jar supply creates bottleneck risk when artisanal brands scale. Distribution runs through integrated processors with frozen inventory capacity and spot-market dependent canneries competing for auction volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Deforestation Regulation due diligence requirements and extended producer responsibility frameworks are forcing supply chain investments that favor incumbents with existing certification infrastructure.
For Market Incumbents: Acquire MSC-certified offtake agreements in the Maldives and Indonesia to lock in contaminant-compliant raw material access before EFSA threshold tightening. Build backward integration into frozen inventory capacity to smooth Bangkok auction volatility that threatens margin stability. Defend against plant-based analog competition by accelerating BPA-NI coating line investments that qualify for EU Green Deal implementation funds. For New Entrants and Emerging Players: Blockchain-enabled traceability platforms offer technology-first positioning to bypass legacy ERP integration barriers facing family-owned processors. Target direct-to-restaurant distribution in Barcelona and Rome where digital ordering platforms reduce route-to-market establishment costs. White space exists in subscription variety boxes curating regional Portuguese and Spanish conservas for North American discovery-oriented consumers. For Investors and Strategic Acquirers: Valuations sit cheapest among spot-market dependent canneries lacking frozen inventory capacity or direct offtake agreements, presenting consolidation targets for integrated processors. Long-term viability favors vertically integrated operators with REACH-compliant coating infrastructure and food service channel penetration. Watch for EU DPP regulation enforcement timelines as inflection indicator that will fragment compliance-capable from legacy-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| MSC Certification Asset Acquisition | Direct offtake agreements in Maldives and Indonesia bypass auction volatility for European market access. |
| BPA-NI Coating Line Retrofit | REACH-compliant reformulations unlock German and French retail banner shelf access under EU Green Deal financing. |
| Direct-to-Restaurant Distribution Buildout | Digital platforms in Barcelona and Rome capture food service margin pools bypassing wholesale intermediaries. |
| Blockchain Traceability Platform Deployment | Batch-level digital passports satisfy incoming EU DPP regulation and Group Purchasing Organization procurement requirements. |
| Retort Pouch Format Expansion | Aluminum oxide barrier SKUs enable 40% freight weight reduction for UK and Netherlands lunchbox convenience segments. |
Study Parameters
Multiple input streams — primary interviews with cannery operations directors, retail category buyers, and food service procurement managers; secondary validation through EFSA contaminant limit documentation, EU REACH regulatory filings, and customs trade data — were reconciled through bottom-up production volume modeling and top-down consumption pattern triangulation.
Historical catch volume trends were cross-referenced against panel input from thermal process engineers and coating formulation specialists to build analytical frameworks across species type, packaging format, and distribution channel dimensions. CAGRs were derived from modeled production capacity expansion against per capita consumption deepening in Mediterranean markets, with El Niño cycle impacts and regulatory enforcement timelines as scenario inputs.
The model holds under stable EU regulatory enforcement schedules and consistent EFSA contaminant thresholds; deviation in Bangkok auction volatility extremes or accelerated EU DPP implementation would shift volume projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Europe Shrimp Market
Seafood
Sea Biscuits Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
United States Lobster Market
Seafood
Cod Fish Market
Seafood
Fish Hydrolysate Market
Seafood
Seafood Processing Market
Seafood
Trout Market
Seafood
United States Salmon Market
Seafood
Organic Seafood Market
Seafood
Mackerel Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
United States Plant-Based Seafood Market
Seafood
Fish Protein Hydrolysate Market
Seafood
North America Seafood Market