
 3D Printing in Oil and Gas Market | 2026-2036
3D Printing in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing in Oil and Gas Market Analysis
The distance between equipment manufacturers and pure service providers is collapsing as both buyer archetypes internalize additive capabilities. Stratasys Ltd. anchors polymer-based prototyping workflows for field-ready tooling. SLM Solutions Group AG dominates laser powder-bed systems for nickel superalloy components in high-pressure environments.
3D printing in oil and gas encompasses layer-by-layer fabrication of metallic and polymer parts from digital models, typically achieving near-net-shape geometries with tolerances of 50-200 microns for downhole and subsea applications. The technology replaces conventional forging and machining for low-volume, high-complexity components such as custom valve bodies and drilling stabilizers. Spare parts production leads current revenue pools because operators prioritize inventory reduction and obsolescence mitigation over speed. Selective laser sintering captures the fastest technology expansion due to its validated performance with Inconel and cobalt-chrome alloys in corrosive wellbore conditions. Binder jetting occupies an emerging position where sand printing for investment casting patterns reduces lead times for legacy pump components.
API Standard 20S and ISO/ASTM 52900 define qualification pathways for additive parts in pressure-containing service, forcing suppliers to maintain extensive process documentation and mechanical testing records. The EPA and BSEE jointly scrutinize material traceability for subsea installations, extending compliance timelines but raising barriers to uncertified entrants. Stakeholders must weigh capital intensity against the operational flexibility that distributed manufacturing networks provide when geopolitical disruptions constrain traditional supply lanes.
Market Dynamics
Equipment manufacturers and service providers are collapsing their historical distance by internalizing additive manufacturing capabilities, fundamentally restructuring procurement relationships across the oilfield services ecosystem.
Growth Catalysts
- API Standard 20S:This qualification framework for pressure-containing additive parts creates enforceable quality benchmarks that accelerate operator confidence in printed metal components for downhole environments.
- Inventory reduction mandates:Operators facing capital discipline pressures are prioritizing on-demand spare parts production over traditional stocking models, particularly for obsolete pump and valve geometries.
- Selective laser sintering:Its validated performance with Inconel and cobalt-chrome alloys in corrosive wellbore conditions is capturing the fastest technology expansion across high-pressure applications.
Market Restraints
- Raw material powder costs:Nickel superalloy feedstock prices exhibit volatility tied to mining supply constraints, compressing margins for laser powder-bed system operators.
- Equipment supplier concentration:Laser powder-bed system manufacturing concentrates among a limited base of European and Asian machinery builders, creating single-source vulnerability for North American adopters.
- Dimensional tolerance limitations:Near-net-shape geometries still require post-process machining to achieve sub-50-micron tolerances for critical sealing surfaces, limiting full process substitution.
Strategic Opportunities
- Sand printing for investment casting:Binder jetting of foundry patterns offers lead-time compression for legacy pump components where direct metal printing remains uneconomical at volume.
- United Arab Emirates offshore cluster:Subsea installation activity around Abu Dhabi creates demand for corrosion-resistant printed manifolds and connector components with localized supply requirements.
- Distributed manufacturing networks:Geopolitical disruptions to traditional supply lanes are creating structural openings for port-proximate printing hubs serving rig mobilization schedules.
Industry Challenges
- Process documentation burden:ISO/ASTM 52900 compliance requires extensive mechanical testing records and traceability systems that extend qualification timelines for new part introductions.
- Non-destructive evaluation protocols:Internal defect detection in complex printed geometries lacks standardized ultrasonic or radiographic methods, creating acceptance disputes between suppliers and operators.
- Material property anisotropy:Layer-wise deposition creates directional mechanical performance variations that complicate design allowables for rotating equipment applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing in Oil and Gas Market |
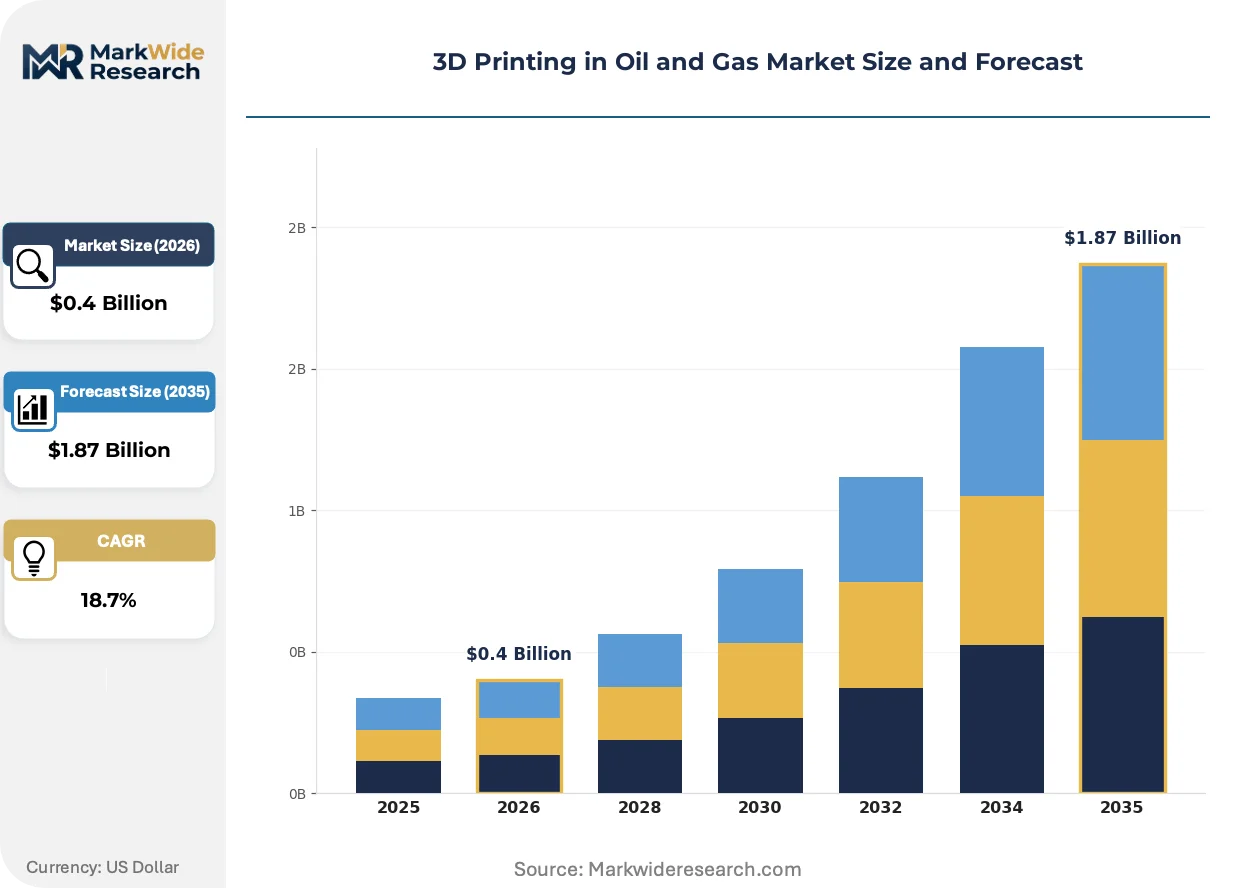
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $1.87 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prototyping, Spare Parts, Tools, Components Technology: Fused Deposition Modeling, Selective Laser Sintering, Binder Jetting, Stereo Lithography Application: Downstream, Upstream, Midstream, Drilling End User: Service Providers, Equipment Manufacturers, Contractors, Research Institutes |
| Companies Covered | Materialise NV, Envisiontec GmbH, Proto Labs, Inc., 3D Systems Corporation, ExOne Company, Voxeljet AG, Optomec Inc., SLM Solutions Group AG, Stratasys Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing in Oil and Gas Market Emerging Trajectories
Digital thread integration from reservoir simulation to printed component geometry is compressing design iteration cycles and enabling mass customization of downhole tools previously constrained by forging die economics.
Multi-laser powder-bed fusion is decomposing the traditional trade-off between build volume and part complexity in nickel superalloy production. Offshore equipment manufacturers are adopting these systems for batch production of custom stabilizer blades and valve bodies. The technology is decomposing centralized forging supply chains into distributed, print-on-demand networks responsive to rig-specific timelines.
EPA and BSEE joint scrutiny of material traceability for subsea installations is extending compliance timelines but raising quality barriers. This regulatory convergence forces suppliers to maintain chain-of-custody documentation from powder atomization through final heat treatment. Subsea cluster operators in the United States Gulf Coast are responding by qualifying dedicated production lines with captive powder supply agreements.
Spare parts procurement is migrating from catalog-based ordering to digital inventory models where operators license part geometries rather than holding physical stock. Oilfield service companies are disintermediating traditional distributor networks by hosting certified print files on proprietary platforms. This shift is most visible among supermajors with centralized procurement functions seeking to reduce working capital tied to slow-moving critical spares.
3D Printing in Oil and Gas Market Segmentation
Segmentation in 3D printing for oil and gas reveals how qualification requirements and operational constraints reshape procurement patterns across the value chain. Each dimension exposes distinct cost structures and regulatory exposure that determine technology deployment feasibility.
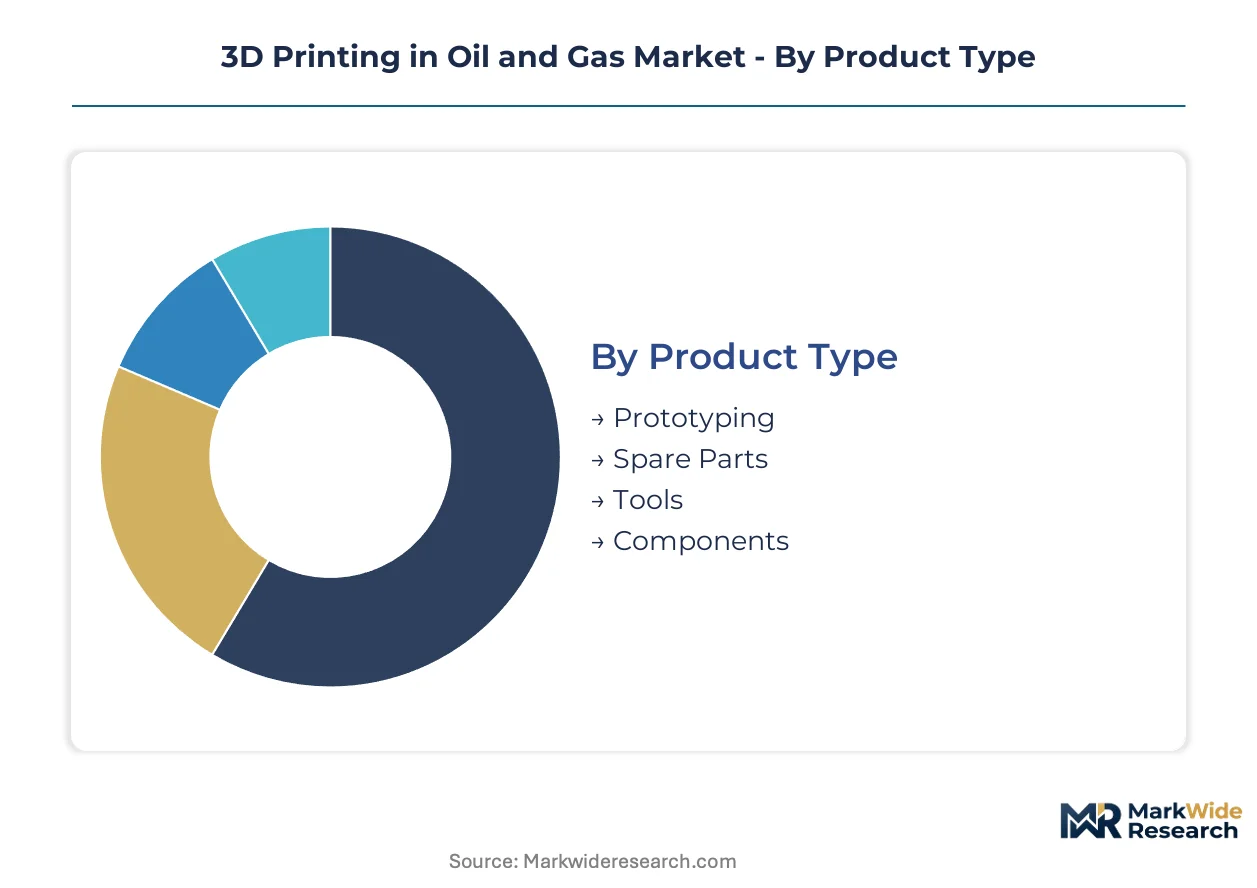
Product Type:
API Standard 20S and ISO/ASTM 52900 impose divergent documentation burdens across product categories, with pressure-containing parts facing extended qualification timelines versus non-critical tooling.
- Spare Parts:Digital inventory models replace physical stocking for obsolete pump geometries and valve bodies. Operators in the United States Gulf Coast cluster prioritize on-demand production to reduce working capital tied to slow-moving critical components facing API qualification protocols.
- Prototyping:Field-ready polymer tooling accelerates design validation for downhole applications. Stratasys polymer workflows dominate this segment where tolerances of 50-200 microns suffice for fit-check and functional testing prior to metal production.
- Tools:Custom drilling stabilizers and jigs achieve near-net-shape geometries through selective laser sintering of nickel superalloys.
- Components:Direct metal printing of valve bodies and manifolds serves subsea installations requiring corrosion-resistant cobalt-chrome alloys.
Spare Parts handles the majority of throughput; Prototyping is the fastest mover on share.
Technology:
Capital intensity and feedstock compatibility create distinct customer tiers, with laser-based systems commanding premium positioning against emerging binder jetting alternatives.
- Selective Laser Sintering:Laser powder-bed fusion of Inconel and cobalt-chrome alloys delivers validated performance in corrosive wellbore conditions. SLM Solutions Group AG anchors this technology for high-pressure components where material anisotropy complicates design allowables.
- Binder Jetting:Sand printing for investment casting patterns compresses lead times for legacy pump components where direct metal printing remains uneconomical at volume. Foundry pattern production in the United Arab Emirates offshore cluster is expanding adoption.
- Fused Deposition Modeling:Polymer extrusion systems produce field-ready prototypes and non-metallic tooling at lower capital thresholds.
- Stereo Lithography:Photopolymer resin curing generates high-resolution patterns for investment casting masters in complex geometries.
Selective Laser Sintering captures the dominant equipment spend; Binder Jetting is climbing the fastest as foundry integration matures.
Application:
Pressure ratings and environmental exposure determine regulatory scrutiny intensity, with subsea installations facing joint EPA and BSEE traceability requirements.
- Upstream:Downhole tools and completion equipment in high-pressure reservoirs demand nickel superalloy components with full material pedigree documentation. The United States Gulf Coast concentration of drilling activity drives localized printing hub development.
- Drilling:Custom stabilizer blades and drill bit bodies benefit from mass customization unconstrained by forging die economics. Multi-laser powder-bed systems enable batch production responsive to rig-specific mobilization schedules.
- Midstream:Pipeline valve components and compression hardware face lower qualification barriers than downhole equipment.
- Downstream:Refinery spare parts and maintenance tooling prioritize inventory reduction over geometric complexity.
Upstream absorbs the largest equipment investment; Drilling is expanding most quickly as digital thread integration compresses design cycles.
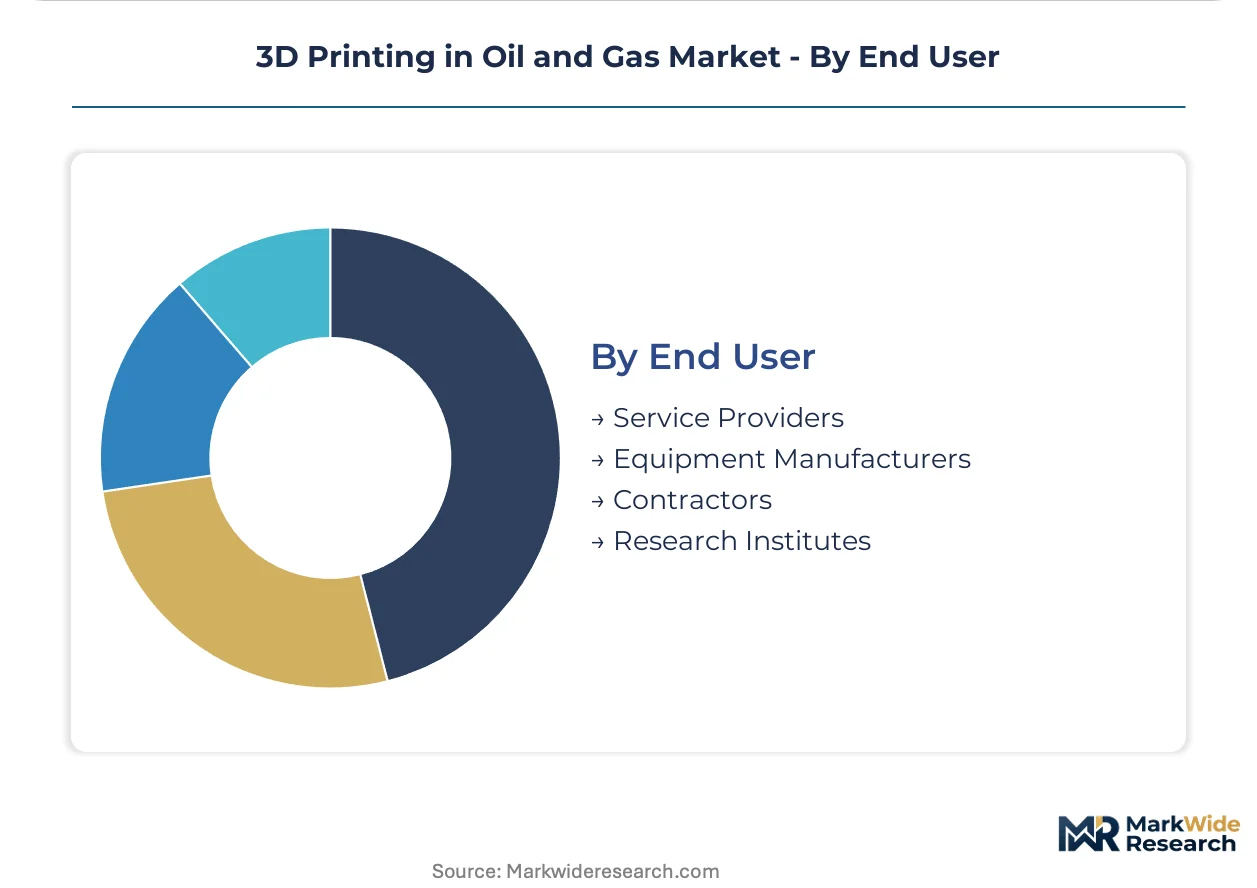
End User:
Internalization of additive capabilities is collapsing historical procurement boundaries between equipment makers and pure service providers.
- Equipment Manufacturers:Downhole tool producers integrate laser powder-bed systems for captive production of nickel superalloy components. API Standard 20S compliance requires dedicated production lines with extensive mechanical testing records.
- Service Providers:Oilfield service companies disintermediate distributor networks through proprietary digital platforms hosting certified print files. Supermajors with centralized procurement functions license geometries rather than holding physical inventory.
- Contractors:Rig operators adopt distributed printing hubs proximate to port facilities for spare parts responsiveness.
- Research Institutes:Technology validation and process development for emerging alloy systems support industry qualification protocols.
Equipment Manufacturers command the primary equipment demand; Service Providers are gaining share fastest as digital inventory models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German laser powder-bed system manufacturers export nickel superalloy printing equipment to United States Gulf Coast operators facing API Standard 20S qualification timelines. This trade corridor supplies critical machinery for downhole component fabrication where material traceability requirements tighten.
United States
Gulf Coast offshore operators drive demand for corrosion-resistant printed manifolds and connector components. EPA and BSEE jointly scrutinize material traceability for subsea installations, extending compliance timelines. Houston-area service providers integrate selective laser sintering into offshore supply chains for rig mobilization responsiveness.
Germany
European machinery builders concentrate laser powder-bed system manufacturing for high-pressure nickel superalloy applications. REACH regulations govern chemical safety in powder atomization processes. Bavarian equipment manufacturers supply North American adopters facing single-source vulnerability concerns.
United Arab Emirates
Abu Dhabi subsea installation activity creates demand for localized corrosion-resistant component supply. MOHAP oversees medical-grade material standards that influence industrial powder specifications. Dubai-based foundries expand binder jetting adoption for sand printing of investment casting patterns.
China
Domestic oilfield service companies internalize additive capabilities for drilling stabilizer production. MIIT standards guide industrial additive manufacturing equipment certification. Yangtze River Delta machinery clusters develop multi-laser powder-bed systems for batch component fabrication.
Norway
North Sea subsea infrastructure operators prioritize on-demand spare parts for obsolete valve geometries. The country's national petroleum regulator enforces strict material pedigree documentation for pressure-containing equipment. Stavanger-area contractors adopt distributed printing hubs to reduce working capital in slow-moving critical inventory.
3D Printing in Oil and Gas Market Vendor Landscape
Player mix skews toward European machinery specialists with deep powder-bed fusion expertise alongside North American polymer workflow providers. Structure concentrates among laser system manufacturers serving high-pressure applications, with secondary tiers of foundry-integrated sand printing operators and field-prototyping service bureaus. Dominant competitive moves include captive powder supply agreements and dedicated production line qualification for API compliance.
Among European machinery specialists, SLM Solutions Group AG and Voxeljet AG exemplify divergent technology vectors within metal additive fabrication. Stratasys Ltd. occupies a distinct position anchoring polymer-based prototyping workflows. These three entities represent the primary competitive anchors: one German Aktiengesellschaft specializing in laser powder-bed systems, one German AG advancing binder jetting for industrial patterns, and one Israeli-American provider dominating field-ready polymer tooling.
| Leading Market Players |
|---|
| Materialise NV |
| Envisiontec GmbH |
| Proto Labs, Inc. |
| 3D Systems Corporation |
| ExOne Company |
| Voxeljet AG |
| Optomec Inc. |
| SLM Solutions Group AG |
| Stratasys Ltd. |
| Others |
Supply Flow & Price Mechanics
Direct metal printing of nickel superalloy valve bodies is displacing forged components in subsea applications, simultaneously shifting supply geography from centralized European forges to distributed Gulf Coast print hubs while compressing pricing premiums for legacy supply chains.
Pricing Analysis
Prior-generation laser powder-bed systems commanded premium pricing against emerging multi-laser platforms, while next-generation binder jetting equipment undercuts both on capital outlay. Three-tier pricing structure across API-qualified, process-documented, and uncertified production tiers separates compliant suppliers from commodity operators. Cost compression in uncertified tiers is intensifying because nickel superalloy powder volatility compresses margins for non-captive feedstock buyers. Equipment manufacturers show lowest price sensitivity due to qualification timelines, while rig contractors face acute budget pressure on spare parts procurement.
Supply Chain Analysis
Germany and China anchor laser powder-bed system manufacturing for high-pressure nickel superalloy applications. Raw material dependencies rest on nickel powder atomization capacity, cobalt-chrome feedstock supply, and argon gas for build chamber atmospheres. Single-source vulnerability concentrates among European machinery builders serving North American adopters. Distribution runs through equipment manufacturer direct sales for production systems and oilfield service platform licensing for digital inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where powder supply agreements and API qualification consulting expand faster than hardware unit sales.
For Market Incumbents: Shield market position by securing captive nickel superalloy powder supply agreements against mining supply volatility, and accelerate dedicated production line qualification for API Standard 20S compliance before regulatory timelines extend further. Vertical integration into powder atomization hedges feedstock cost pressure from mining supply constraints. For New Entrants and Emerging Players: API Standard 20S fast-track qualification for sand printing foundry patterns offers entry into legacy pump component production where direct metal printing remains uneconomical. Target the United Arab Emirates offshore cluster for corrosion-resistant manifold supply with localized production requirements. Go-to-market leverage rests on foundry partnership models rather than capital-intensive laser system ownership. For Investors and Strategic Acquirers: The market sits at a standards-convergence phase that favors qualified production line operators with established API documentation systems. Long-term viability across the next decade hinges on regulatory compliance infrastructure rather than pure technology differentiation. Acquisition targets should demonstrate captive powder supply and dedicated API-compliant production lines. The signal to watch is EPA-BSEE joint enforcement intensity for subsea material traceability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Supply Agreement | Locks nickel superalloy feedstock costs against mining supply volatility for Gulf Coast operators. |
| API Standard 20S Production Line Qualification | Creates enforceable quality benchmarks that accelerate operator confidence in printed metal components. |
| Digital Inventory Platform Licensing | Enables supermajors to license part geometries rather than holding physical slow-moving critical spares. |
| Foundry-Integrated Sand Printing Partnership | Compresses lead times for legacy pump components where direct metal printing remains uneconomical at volume. |
| Multi-Laser Powder-Bed System Deployment | Decomposes trade-offs between build volume and part complexity for batch production of custom stabilizer blades. |
Methodological Framework
Initial hypotheses were tested against primary input from equipment manufacturer procurement directors, oilfield service technology officers, downhole tool design engineers, and API qualification specialists, and refined through secondary validation against SEC filings from additive manufacturing equipment vendors, American Petroleum Institute standard documentation, EPA enforcement records for subsea installations, and BSEE material traceability guidelines, with bottom-up segment sizing triangulated against top-down market aggregation.
Variance decomposition across the projection horizon isolates technology adoption rates, regulatory timeline shifts, and powder feedstock cost trajectories as primary uncertainty sources. Segmentation dimensions modeled include product type, technology platform, application pressure rating, and end-user internalization stage. CAGRs were derived from logistic diffusion curves fitted to equipment installation data and spare parts procurement patterns, with nickel superalloy price indices and rig mobilization schedules serving as industry-specific forecast inputs.
Underlying assumptions cover API Standard 20S enforcement continuity, laser powder-bed system import tariff stability, and nickel mining supply expansion, with deviation risk concentrated in EPA-BSEE regulatory convergence timing and geopolitical disruption to European machinery supply chains. Recalibration cycles align with material shifts in API qualification protocol updates and powder feedstock contract renegotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Underreamers Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Smart Well Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Wellhead System Market
Oil & Gas
Frac Stack Market
Oil & Gas
Coal Mining Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
North Sea Oilfield Equipment Market