
 Bunker Liners Market | 2026-2036
Bunker Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Bunker Liners Market Insights
EU REACH restrictions on persistent organic pollutants is decoupling virgin polyethylene sourcing from circular material streams across European golf developments. Profile Products leverages its vertically integrated fiber operations to control resin quality from pellet to finished liner. TenCate anchors its position through advanced geosynthetic weaving capabilities that extend product lifespan under cyclic loading conditions.
Bunker liners are impermeable or semi-permeable membranes installed at the interface between sand playing surfaces and native subgrade soils, typically manufactured from polyethylene or polypropylene sheeting ranging from 2mm to 5mm thickness to prevent contamination migration while managing subsurface drainage. Their primary purpose is to preserve sand purity, stabilize bunker edges, and reduce maintenance labor across golf course and sports turf applications. Polyethylene formulations dominate current installations due to chemical inertness and installation flexibility, though polypropylene variants occupy premium positions where puncture resistance under heavy equipment traffic proves critical. The 3mm thickness category sustains the broadest addressable market, balancing material cost against performance durability for standard golf course renovation budgets.
The EPA regulates construction site stormwater discharge under NPDES permitting, which shapes liner specification for temporary containment applications in the United States. ISO 10318 geosynthetic classification standards and ASTM D7409 puncture resistance test methods govern product qualification for professional sports turf contracts. Stakeholders must monitor evolving state-level PFAS restrictions, as fluorinated compound bans in California and Maine are forcing reformulation of certain polymer additives without degrading liner impermeability performance.
Market Dynamics
The USGA's 2023 bunker specification rewrite is decoupling sand-only construction from membrane-backed systems, forcing renovation contractors to specify liners in projects previously bid without them. This regulatory pivot is redistributing value from raw sand suppliers toward engineered geosynthetic manufacturers.
Growth Catalysts
- Renovation cycle compression:Southeastern United States golf courses now replace bunker sand every 7-9 years versus 12-15 historically, accelerating liner replacement demand. Florida and Georgia superintendents treat membrane installation as standard practice.
- REACH compliance migration:EU golf developments must source recycled polyethylene liners to satisfy persistent organic pollutant restrictions, redirecting procurement toward circular material certified suppliers.
- ASTM D7409 certification mandate:Professional sports turf contracts now require puncture resistance documentation, disqualifying uncertified sheeting from municipal stadium bids.
Market Restraints
- Resin price volatility:Virgin polyethylene pellet costs fluctuate with ethylene feedstock from Gulf Coast petrochemical complexes, compressing margin on fixed-price renovation contracts.
- Installer capacity concentration:Certified geosynthetic installation crews cluster in Florida, Texas, and Arizona, creating 6-8 month backlogs for courses in the Upper Midwest and Pacific Northwest.
- Natural grass bunker alternatives:Some municipal courses in water-stressed California counties are eliminating sand bunkers entirely, substituting grass-faced depression designs that require no liner.
Strategic Opportunities
- Canadian market underpenetration:Ontario and British Columbia golf developments lag US liner adoption by 8-10 years, presenting first-mover positioning for ASTM-certified suppliers.
- PFAS-free additive formulations:California and Maine fluorinated compound bans are forcing reformulation R&D, with early compliant products commanding specification premiums.
- Direct-to-superintendent digital specification:Bypassing traditional irrigation contractors, liner manufacturers now sell through agronomic purchasing cooperatives that aggregate demand from 50-100 course clusters.
Industry Challenges
- Geosynthetic welding technician shortage:Hot-wedge and extrusion welding certification programs graduate fewer than 200 technicians annually, constraining installation quality at peak renovation seasons.
- Subgrade preparation standardization gaps:No unified protocol exists for native soil compaction testing before liner deployment, causing edge failure disputes between contractors and course owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bunker Liners Market |
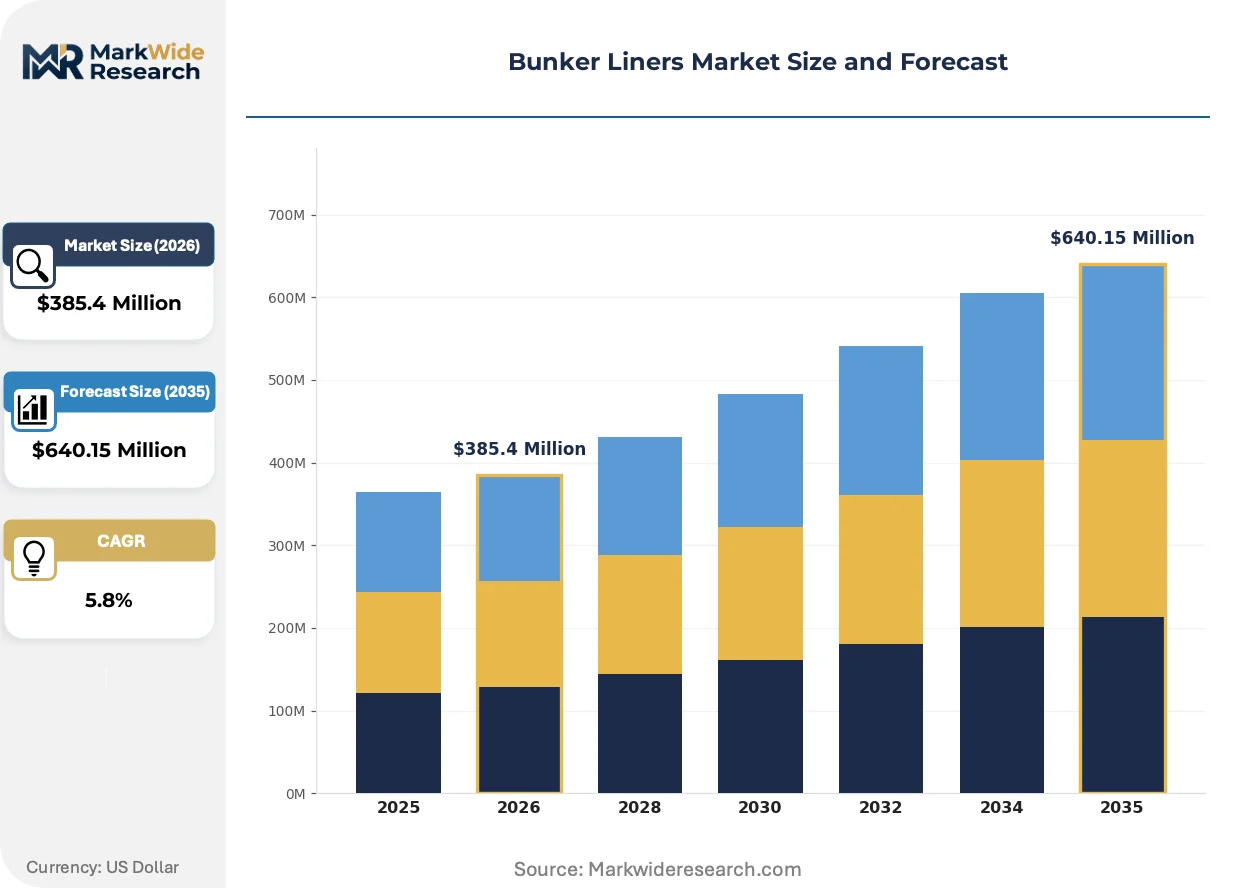
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, PVC, Rubber Thickness: 2mm, 3mm, 4mm, 5mm End User: Shipping Industry, Oil Industry, Construction, Agriculture Application: Fuel Storage, Waste Management, Water Containment, Environmental Protection |
| Companies Covered | CapillaryFlow, USGA, Turface, Revolution Turf, Synlawn, GreenKeeper Fabric, Bunker Solutions, Profile Products, TenCate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bunker Liners Market Trends and Innovations
Material science advances and procurement digitization are compressing specification cycles while extending product service life. Three developments are restructuring competitive positioning.
Multi-layer co-extruded polyethylene is absorbing installation damage that previously caused field failures. Golf course contractors in Florida and the Carolinas now specify 4mm and 5mm variants for high-traffic practice bunkers. Thicker membranes are compressing warranty claim rates and shifting buyer preference toward single-source suppliers with in-house extrusion capacity.
EPA NPDES construction stormwater permits now explicitly reference liner containment for temporary sediment control. Golf development projects exceeding one acre must document impermeable barrier deployment in their stormwater pollution prevention plans. California courses are responding by pre-specifying dual-use liners that transition from construction-phase containment to permanent bunker installation.
Superintendent purchasing cooperatives are consolidating specification authority previously dispersed among irrigation contractors and landscape architects. These buying groups aggregate 40-60 course renovation projects annually, negotiating direct pricing with liner manufacturers. The model is most visible in Texas and Arizona, where agronomic service companies have converted from installation subcontractors to procurement intermediaries.
Bunker Liners Market Segmentation
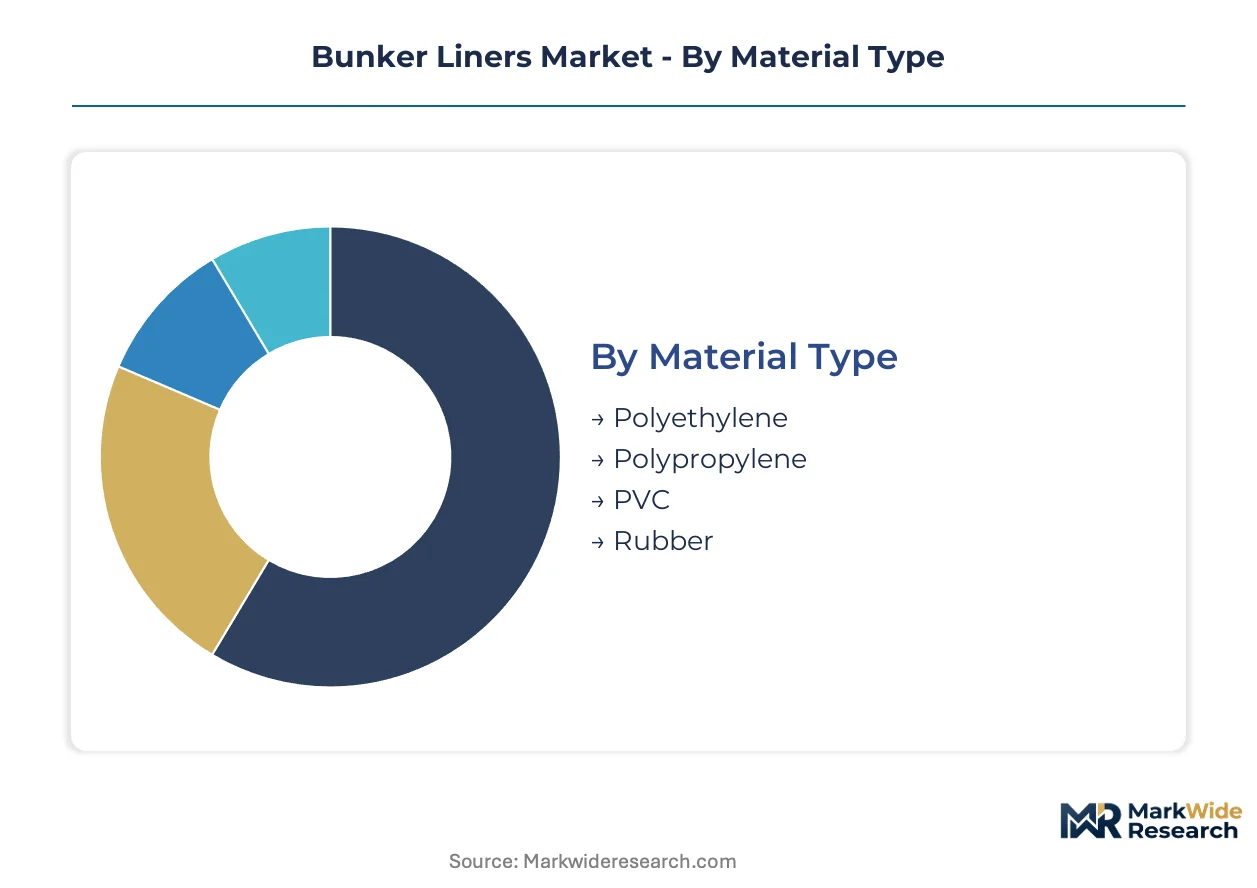
Segmentation in the Bunker Liners Market reveals how capital allocation, regulatory compliance, and installation complexity fragment procurement patterns. Golf course superintendents and industrial facility managers face divergent specification pressures that reshape supplier priorities.
Material Type:
Capital intensity varies sharply across polymer formulations, with virgin resin grades demanding the highest upfront investment but commanding specification premiums in certified applications.
- Polyethylene:Formulated as high-density or linear low-density sheets, polyethylene offers chemical inertness against bunker sand acidity and subsurface moisture. Demand concentrates in Florida and Georgia golf developments where the USGA's membrane-backed specifications have become standard practice, driven by renovation cycles compressing to 7-9 years.
- Polypropylene:Superior puncture resistance under heavy equipment traffic positions this material for high-traffic practice facilities and municipal stadium applications. Installation in Texas and Arizona sports complexes accelerates as ASTM D7409 certification mandates disqualify uncertified alternatives from professional turf contracts.
- PVC:Lower material cost suits temporary construction-phase containment under EPA NPDES permitting requirements.
- Rubber:Recycled content variants address EU REACH compliance for circular material streams in European golf developments.
Most installed capacity flows through Polyethylene. Expansion is steepest in Polypropylene.
Thickness:
Material volume and labor cost scale non-linearly with membrane gauge, creating three distinct procurement tiers that match project durability requirements.
- 3mm:The broadest addressable market sits at this thickness, balancing material cost against performance durability for standard golf course renovation budgets. Southeast US contractors specify this gauge for routine bunker replacements, with Profile Products and TenCate competing on extrusion quality and warranty terms.
- 2mm:Economy positioning suits temporary sediment control and short-lifecycle installations where construction-phase containment transitions to permanent use.
- 4mm:Multi-layer co-extruded variants absorb installation damage that previously caused field failures in high-traffic practice bunkers.
- 5mm:Premium specifications dominate Florida and Carolina practice facilities where warranty claim compression justifies material premium.
Procurement volume clusters at 3mm. Thicker membranes are climbing the fastest as warranty-driven specification rises.
End User:
Customer type determines whether liners serve permanent infrastructure or temporary regulatory compliance, reshaping sales channel strategy.
- Shipping Industry:Fuel containment regulations drive specification for impermeable barriers at port facilities and vessel bunkering stations.
- Oil Industry:Secondary containment mandates under EPA regulations sustain demand for chemical-resistant membrane systems.
- Construction:Stormwater pollution prevention plans now explicitly reference liner deployment for projects exceeding one acre, with California courses pre-specifying dual-use membranes.
- Agriculture:Water containment for irrigation reservoirs and livestock operations applies geosynthetic technology outside traditional golf and sports turf channels.
Construction-phase procurement generates the largest transaction volume. Golf course renovation is gaining share fastest as superintendent purchasing cooperatives consolidate specification authority.
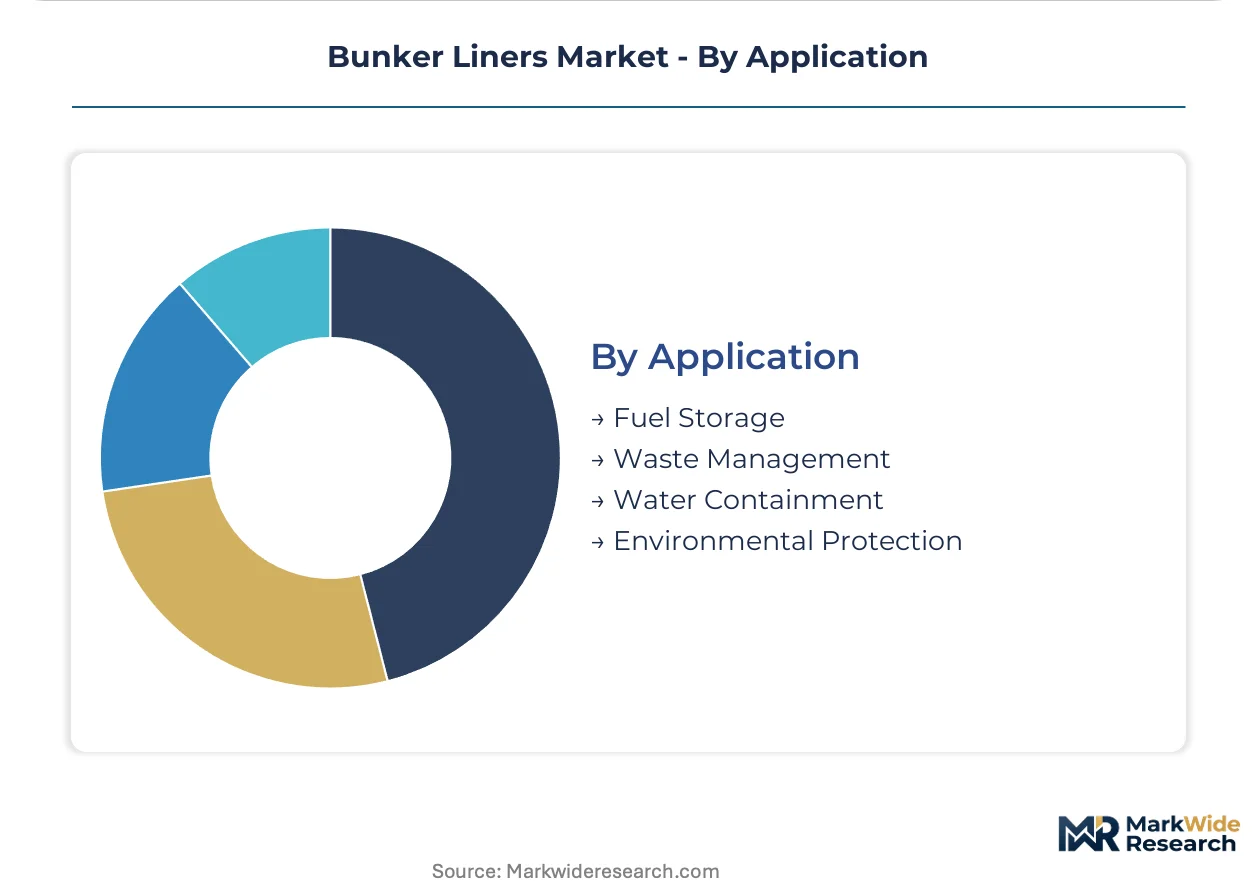
Application:
Use-case specificity determines whether liners face cyclic loading, chemical exposure, or biological degradation, forcing formulation trade-offs.
- Fuel Storage:Chemical resistance requirements demand specialized polyethylene grades for hydrocarbon containment at industrial and marine facilities.
- Waste Management:Landfill liner specifications extend product lifecycles through enhanced UV stabilization and seam integrity protocols.
- Water Containment:Irrigation reservoir and detention pond applications emphasize seam welding quality over puncture resistance.
- Environmental Protection:Construction sediment control represents the entry point for many golf course projects, with dual-use liners transitioning from temporary to permanent installation.
Environmental Protection applications handle the greatest membrane volume. Fuel Storage specifications are expanding most quickly as port infrastructure upgrades accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified geosynthetic welding technicians cluster in Florida, Texas, and Arizona, creating installation backlogs that stretch six to eight months for courses in other regions. This workforce concentration shapes where bunker liner specifications convert to actual deployment.
United States
Florida and Georgia superintendents treat membrane installation as standard practice, with renovation cycles compressing to seven to nine years. The USGA's 2023 bunker specification rewrite forces contractors to specify liners in projects previously bid without them. EPA NPDES construction stormwater permits now explicitly reference liner containment for golf developments exceeding one acre.
Canada
Ontario and British Columbia golf developments lag US liner adoption by eight to ten years, presenting first-mover positioning for ASTM-certified suppliers. Health Canada's environmental protection guidelines shape construction-phase containment requirements without mandating permanent membrane systems. Toronto-area contractors increasingly source certified liners for high-profile club renovations.
Germany
EU REACH restrictions on persistent organic pollutants redirect procurement toward circular material certified suppliers for recycled polyethylene liners. ECHA compliance mandates force reformulation of polymer additives without degrading impermeability performance. Bavarian golf developments lead domestic adoption of membrane-backed construction.
United Kingdom
Links courses in Scotland and coastal England face salt-laden subgrade conditions that accelerate liner specification for sand purity preservation. The Environment Agency's construction pollution prevention guidance shapes temporary containment protocols. Surrey and Kent club renovations drive southeastern demand for 4mm and 5mm premium membranes.
Australia
Water-stressed courses in New South Wales and Victoria substitute grass-faced depression designs for sand bunkers, eliminating liner demand in some municipal segments. TGA-equivalent geosynthetic standards govern professional sports turf contracts requiring puncture resistance documentation. Queensland resort developments sustain premium membrane specification for year-round playability.
Bunker Liners Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the bunker liner supply base. Extrusion-capable manufacturers with captive resin supply chains occupy positions distinct from specification brokers who source third-party sheeting. The market structures around three archetypes: integrated resin-to-membrane fabricators, regional installation contractors with private-label sourcing, and agronomic service companies consolidating procurement authority. Capacity expansion and direct-to-superintendent digital channels represent the dominant competitive moves reshaping channel control.
Within the integrated fabrication tier, Profile Products and TenCate exemplify contrasting geographic anchoring and technical positioning. Profile Products leverages backward integration into fiber operations to control resin quality from pellet to finished liner. TenCate occupies a position anchored in advanced geosynthetic weaving capabilities that extend product lifespan under cyclic loading conditions. CapillaryFlow sits within the specification-driven archetype, representing the shift toward membrane-backed systems decoupled from traditional sand-only construction.
| Leading Market Players |
|---|
| CapillaryFlow |
| USGA |
| Turface |
| Revolution Turf |
| Synlawn |
| GreenKeeper Fabric |
| Bunker Solutions |
| Profile Products |
| TenCate |
| Others |
Pricing and Supply Chain Analysis
Superintendent purchasing cooperatives in Texas and Arizona now aggregate 40-60 course renovation projects annually, forcing suppliers to unbundle liner sales from installation services and compressing margins on fixed-price contracts. This buyer consolidation is redistributing pricing power toward procurement intermediaries while resin cost volatility from Gulf Coast petrochemical complexes constrains manufacturer flexibility.
Pricing Analysis
Bundled installation-and-material contracts dominate premium specifications, while unbundled liner-only sales serve economy-tier procurement through agronomic cooperatives. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D7409 certified membranes from uncertified alternatives and temporary containment grades. Cost compression in the standard tier is intensifying because virgin polyethylene pellet costs fluctuate with ethylene feedstock pricing. Municipal courses in water-stressed regions exhibit highest price sensitivity, while Florida private clubs demonstrate lowest sensitivity due to warranty-driven specification preferences.
Supply Chain Analysis
Regional distribution centers in Florida, Texas, and Arizona maintain hub-and-spoke patterns that position certified geosynthetic sheeting within 48-hour delivery windows for peak renovation seasons. Manufacturing concentration centers on the United States, Germany, and China, with extrusion-capable producers controlling captive resin supply chains. Raw material dependencies draw from virgin polyethylene pellets, recycled post-industrial regrind, and specialized UV stabilizer additives. Single-source vulnerability around certified welding technician availability constrains installation capacity during Q2-Q3 peak demand. Distribution runs through irrigation contractors, agronomic service companies, and direct-to-superintendent digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the USGA's 2023 bunker specification rewrite forcing membrane-backed systems into projects previously bid without liners and permanently expanding addressable demand.
For Market Incumbents: Extend certification coverage into Canadian provinces where Ontario and British Columbia developments lag US adoption by 8-10 years, capturing first-mover positioning before ASTM mandates replicate. Deepen backward integration into fiber operations to control resin quality from pellet to finished liner, insulating margin from ethylene feedstock volatility. Defend against emerging private-label sourcing by regional installation contractors through exclusive agronomic cooperative partnerships. For New Entrants and Emerging Players: The price-point gap between premium 5mm co-extruded membranes and economy 2mm temporary containment grades offers entry positioning for mid-tier ASTM-certified alternatives. Target Canadian golf developments and Upper Midwest courses facing 6-8 month installation backlogs as the most penetrable geographies. Pursue direct-to-superintendent digital specification through agronomic purchasing cooperatives rather than traditional irrigation contractor channels. For Investors and Strategic Acquirers: Asymmetric upside sits with extrusion-capable manufacturers with in-house resin supply chains and established agronomic cooperative relationships. Long-term viability over a multi-year horizon hinges on regulatory replication of USGA-style membrane mandates across additional jurisdictions. Acquisition target archetype: regional installation contractors with private-label sourcing capabilities and certified welding technician benches. Monitor state-level PFAS restriction expansion as the critical inflection signal for reformulation R&D investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene pellet sourcing insulates margin from Gulf Coast feedstock volatility. |
| ASTM D7409 Certification Investment | Puncture resistance documentation unlocks municipal stadium and professional sports turf contracts. |
| Direct-to-Superintendent Digital Channel | Agronomic purchasing cooperatives in Texas and Arizona consolidate specification authority previously dispersed. |
| Canadian Market Entry | Ontario and British Columbia golf developments lag US liner adoption by 8-10 years. |
| PFAS-Free Additive Reformulation | California and Maine fluorinated compound bans force compliant product premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with golf course superintendents, turf management contractors, geosynthetic installation crews, and agronomic purchasing cooperative managers with secondary validation. Secondary sources included USGA specification documents, EPA NPDES permitting records, ASTM D7409 test method publications, and ECHA REACH compliance guidance. Bottom-up project pipeline tracking across 50-100 course clusters triangulated against top-down resin consumption estimates from petrochemical industry disclosures.
Segment-weighting approaches distributed value across material type, thickness gauge, end-user category, and application use-case throughout the projection horizon. The analytical framework modeled polyethylene versus polypropylene formulation splits, 2mm through 5mm thickness tiers, and golf course renovation versus construction-phase containment demand patterns. CAGRs were derived from installation backlog analysis, renovation cycle compression trends, and regulatory mandate adoption curves. Key inputs included certified welding technician graduation rates and superintendent cooperative formation velocity.
The model assumes a particular technology adoption path; alternative pathways for membrane-backed bunker construction versus natural grass bunker elimination would alter the outlook. Forecasts reflect documented assumptions regarding USGA specification replication timing and EU REACH compliance migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
LNG Terminal Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Flexible Pipes for Oil and Gas Market