
 Oil and Gas Pipeline and Transportation Automation Market | 2026-2036
Oil and Gas Pipeline and Transportation Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Pipeline and Transportation Automation Market Insights
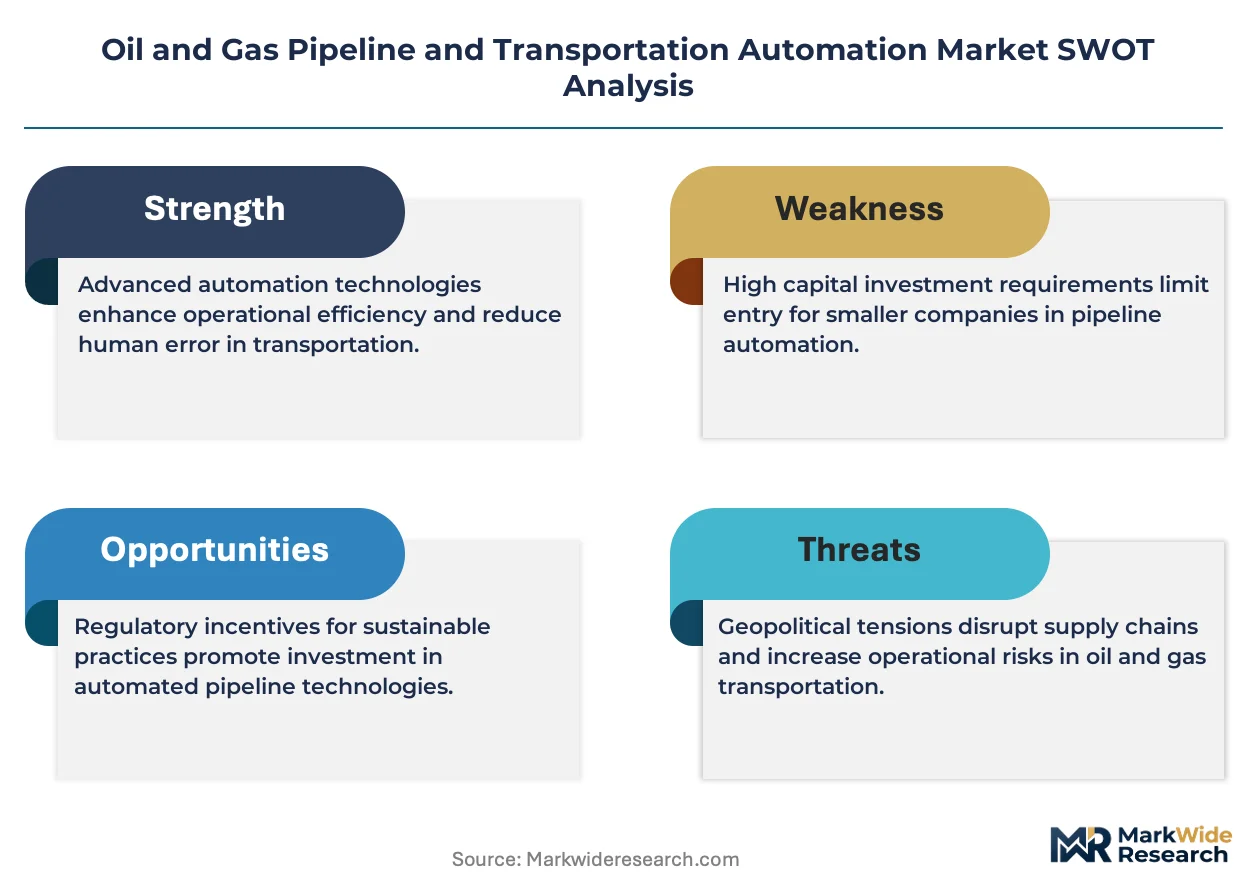
Buyer concentration among North American midstream operators is rebalancing as private-equity-backed pipeline aggregators consolidate scattered regional networks into fewer, larger systems. ABB leverages its integrated electrification and automation portfolio to anchor long-term service contracts across these consolidated networks. Siemens competes through its dominant position in gas turbine control systems tied to compressor station automation. Honeywell International Inc differentiates via its Experion Process Knowledge System deployments that span both greenfield LNG export terminals and brownfield pipeline retrofits.
Oil and gas pipeline and transportation automation encompasses the hardware, software, and communication infrastructure that monitors, controls, and optimizes the movement of hydrocarbons through pipelines and associated storage and distribution facilities, typically operating across pressures ranging from 200 to 1,440 psi and temperatures from -40°C to 60°C depending on product and geography. Its primary purpose is to ensure continuous flow, prevent leaks, minimize energy consumption, and maintain regulatory compliance across thousands of kilometers of infrastructure. SCADA systems occupy the central nervous system role, collecting real-time data from remote terminal units and programmable logic controllers distributed along pipeline routes. The application dimension reveals monitoring as the fastest-expanding segment, driven by methane detection mandates and predictive maintenance algorithms that reduce unplanned downtime.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces integrity management rules that directly shape automation procurement, requiring operators to validate pressure testing and corrosion monitoring through documented control system records. The EU's Corporate Sustainability Reporting Directive and F-Gas Regulation collectively force European operators to deploy more granular emissions tracking automation, tightening market access for vendors without certified environmental monitoring capabilities. Stakeholders must weigh whether to prioritize retrofitting legacy serial-communication pipelines with IP-native architectures or to defer capital until regulatory deadlines crystallize.
Market Dynamics
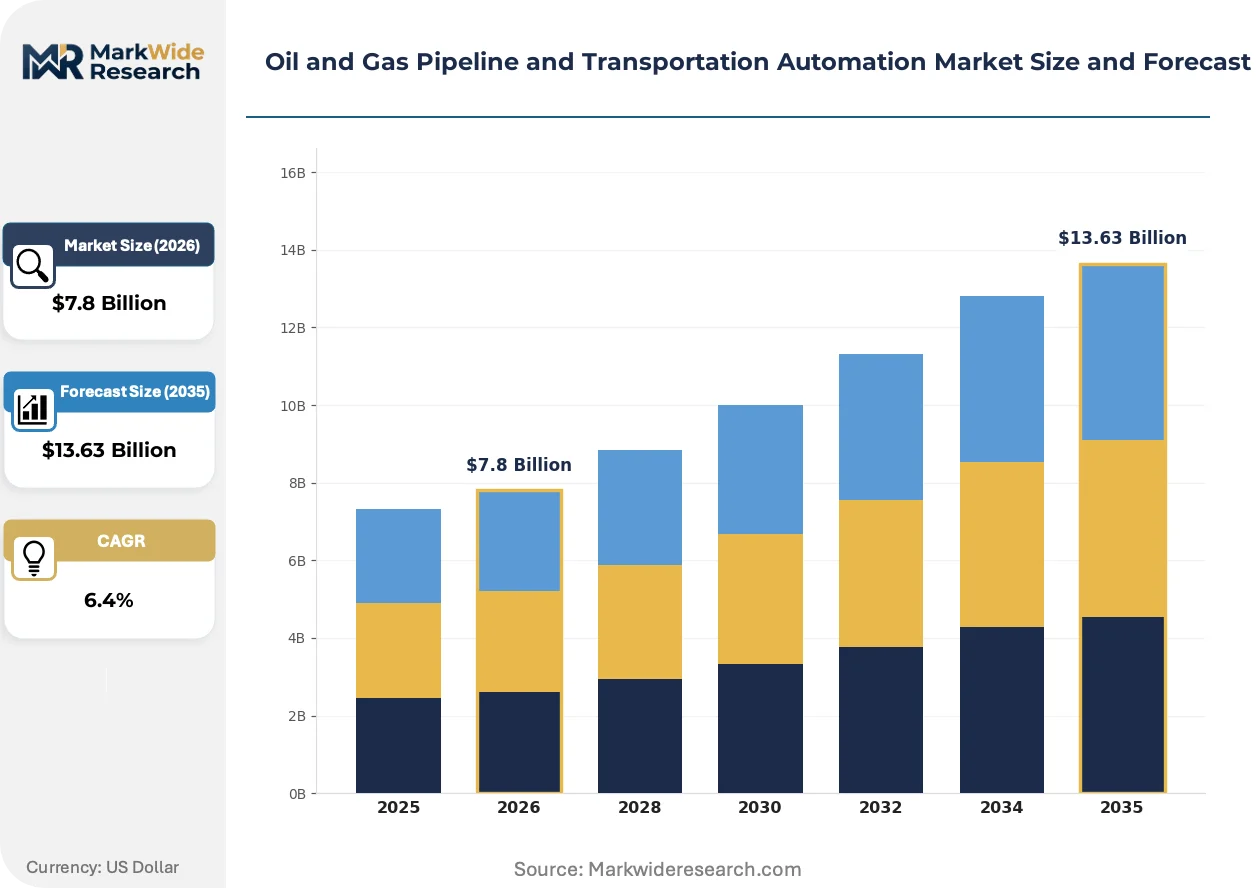
Midstream consolidation is compressing vendor margins while demanding unified automation architectures across previously fragmented pipeline networks. Operators now prioritize SCADA platforms capable of spanning heterogeneous legacy systems without full infrastructure replacement.
Growth Catalysts
- PHMSA Integrity Management:Mandatory validation of pressure testing and corrosion monitoring records forces automation upgrades across US interstate pipelines.
- Permian Basin flaring reduction mandates:Texas and New Mexico regulators impose venting limits that require automated valve and compressor control systems.
- Predictive maintenance algorithms:Machine learning models analyzing vibration and pressure signatures cut unplanned downtime for critical pumping stations.
Market Restraints
- Copper and semiconductor input volatility:Remote terminal unit manufacturing faces cost pressure from fluctuating raw material availability.
- Legacy serial communication protocols:Proprietary fieldbus architectures resist IP-native retrofit without complete control system replacement.
- EU F-Gas Regulation compliance friction:Emissions monitoring certification timelines delay deployment of non-European automation vendors.
Strategic Opportunities
- Hydrogen blending infrastructure:Pipeline operators in Germany and the Netherlands require modified automation for hydrogen-natural gas mixtures.
- Edge computing convergence with satellite telemetry:Low-earth-orbit connectivity enables real-time monitoring in remote Arctic and sub-Saharan corridors.
- CSRD-aligned emissions tracking:European operators seek automated methane quantification systems to satisfy disclosure mandates.
Industry Challenges
- OT cybersecurity skill scarcity:Pipeline control systems require specialists bridging industrial engineering and information security domains.
- Multi-vendor integration complexity:Consolidated networks must harmonize competing SCADA protocols without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Pipeline and Transportation Automation Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SCADA, DCS, PLC, RTU Application: Transportation, Storage, Monitoring, Maintenance End User: Midstream Operators, Oil Producers, Gas Distributors, Industrial Consumers Integration Level: Fully Integrated, Partially Integrated, Standalone, Modular |
| Companies Covered | ABB, Honeywell International Inc, Emerson Electric Co, Rockwell Automation Inc, Siemens, Yokogawa Electric Corporation, Schneider Electric SE, Mitsubishi Electric Corporation, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Pipeline and Transportation Automation Market Trends and Innovations
Digital twin architectures are compressing commissioning cycles for new pipeline segments while enabling scenario testing without physical flow interruption. Three developments dominate vendor R&D priorities and operator procurement specifications.
Edge-deployed machine learning inference engines are overtaking centralized cloud analytics for leak detection decisions. These localized processors analyze acoustic and pressure transient data within 50 milliseconds, enabling immediate valve actuation. US midstream operators in the Bakken formation prioritize this architecture for remote gathering lines lacking reliable fiber connectivity.
The EU Corporate Sustainability Reporting Directive forces granular emissions disclosure down to individual compressor station assets. European operators now demand flow-measurement automation with embedded carbon intensity calculations. Vendors without certified environmental monitoring capabilities face exclusion from tender processes in Germany, Italy, and Poland.
Performance-based service contracts now displace traditional hardware-procurement models for SCADA maintenance. Large North American pipeline aggregators contract uptime guarantees rather than owning spare parts inventories. This shift concentrates vendor risk while transferring operational accountability to automation suppliers across the Permian and Appalachian basins.
Oil and Gas Pipeline and Transportation Automation Market Segmentation
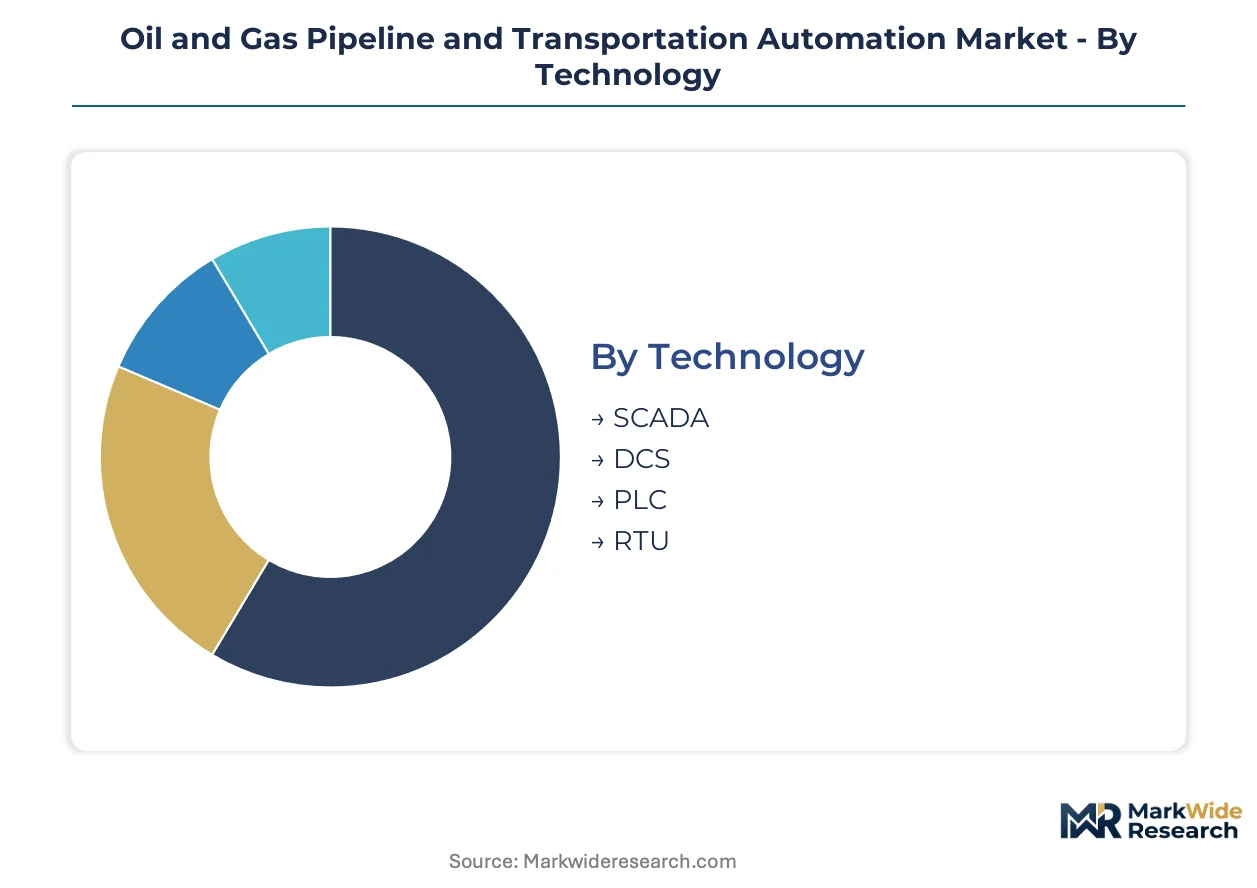
Automation procurement in pipeline infrastructure follows distinct technical and operational logics. Buyers segment investments by control system architecture, functional application, and integration depth against legacy constraints.
Technology:
Supply concentrates among four control system architectures that dominate procurement specifications across transmission and distribution networks.
- SCADA:Supervisory control and data acquisition systems form the centralized monitoring backbone, polling thousands of remote terminal units across extended pipeline corridors. Permian Basin operators deploy these architectures to coordinate compressor stations and valve automation across consolidated midstream networks, driven by PHMSA mandates for documented pressure testing records.
- DCS:Distributed control systems govern continuous process operations at terminal facilities and storage hubs with millisecond loop control. European LNG import terminals favor DCS platforms for cryogenic handling, constrained by EU F-Gas Regulation certification requirements for emissions monitoring integration.
- PLC:Programmable logic controllers execute discrete automation sequences at pumping and metering skids.
- RTU:Remote terminal units transmit field data across serial and IP-native communication links.
SCADA absorbs the bulk of installed capacity; DCS is expanding most quickly at greenfield LNG terminals.
Application:
Functional deployment patterns reveal where capital concentrates against regulatory deadlines and operational risk priorities.
- Transportation:Flow control automation manages pressure regulation and batch sequencing across trunk lines and gathering systems. Bakken operators prioritize this segment for remote gathering line optimization, driven by satellite telemetry enabling real-time valve actuation without fiber infrastructure.
- Monitoring:Leak detection and emissions quantification systems deploy acoustic sensors and methane analyzers along pipeline routes. German and Dutch operators accelerate procurement here, compelled by CSRD-aligned disclosure mandates requiring asset-level carbon intensity tracking.
- Storage:Tank level and vapor recovery automation at cavern and above-ground facilities.
- Maintenance:Predictive algorithms analyzing vibration and pressure signatures for pump and compressor health.
Transportation retains the largest installed base; monitoring climbs the fastest on methane detection mandates.
End User:
Customer concentration patterns reflect consolidation trends and vertical integration strategies across the hydrocarbon value chain.
- Midstream Operators:Pipeline and storage facility owners constitute the primary procurement authority, specifying unified SCADA architectures across acquired networks. Private-equity-backed aggregators in the United States dominate order volumes, prioritizing interoperability across previously fragmented legacy systems.
- Oil Producers:Upstream companies automate gathering lines and lease automatic custody transfer systems. Texas and New Mexico producers face venting limit enforcement, compelling automated compressor and valve control investments.
- Gas Distributors:Local distribution companies automate city gate pressure regulation and odorization systems.
- Industrial Consumers:Refineries and petrochemical plants deploy pipeline receipt automation for feedstock security.
Midstream operators command the dominant share of capital deployment; oil producers are gaining share fastest on flaring reduction compliance.
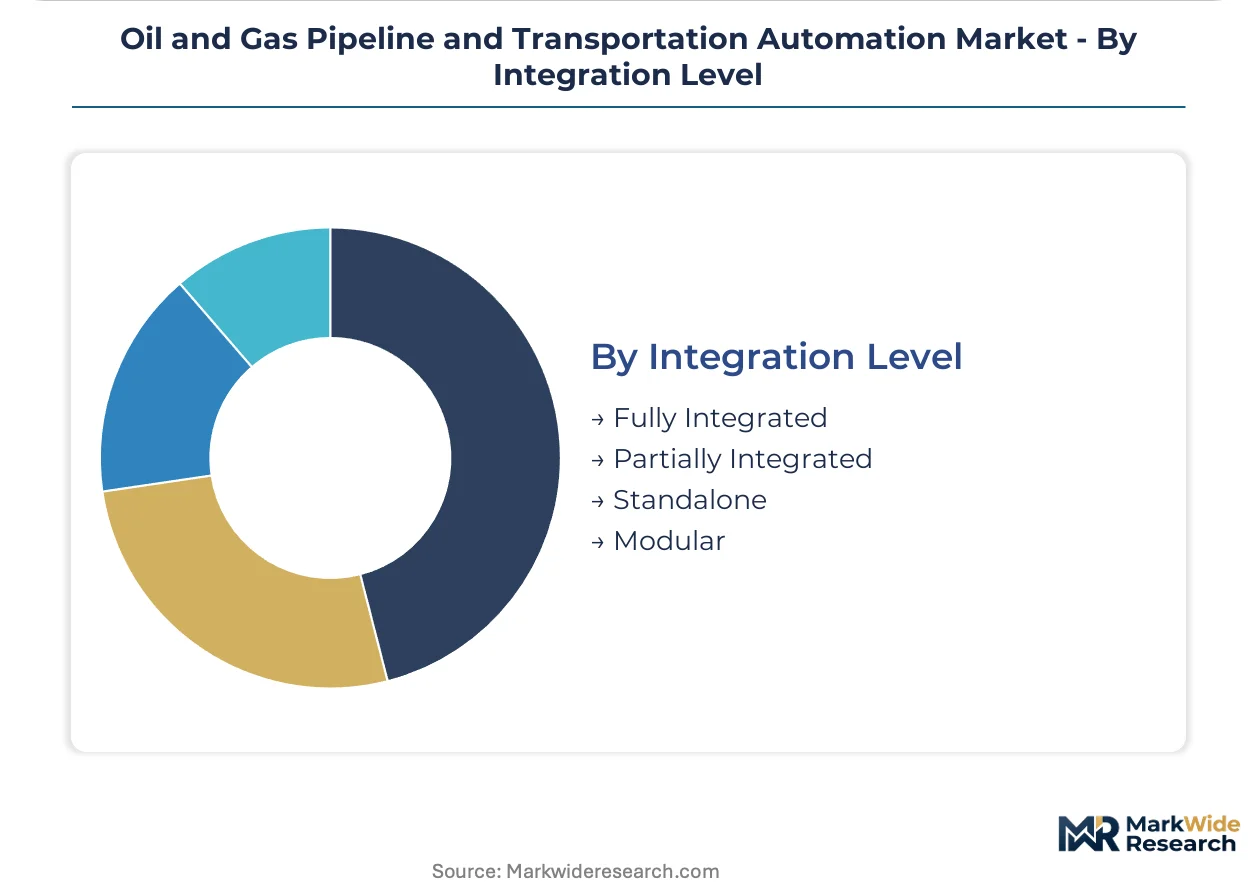
Integration Level:
Architecture decisions balance replacement cost against cybersecurity exposure and operational continuity requirements.
- Fully Integrated:Unified control platforms span SCADA, safety instrumented systems, and enterprise resource planning with single-vendor accountability. Large North American pipeline aggregators specify these architectures for consolidated networks, transferring operational risk to automation suppliers through performance-based uptime contracts.
- Modular:Containerized automation skids enable phased deployment without operational disruption. Arctic corridor projects favor this approach where satellite connectivity and edge computing must integrate with existing serial-communication backbones.
- Partially Integrated:Hybrid architectures retaining legacy fieldbus segments with IP-native overlays.
- Standalone:Independent control systems at isolated facilities without enterprise connectivity.
Fully integrated systems capture the majority of new capital; modular architectures are expanding most quickly in remote and brownfield deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midstream automation procurement concentrates heaviest in the United States, where PHMSA enforcement and private-equity consolidation create sustained upgrade cycles across aging pipeline corridors.
United States
Permian Basin operators deploy SCADA architectures to automate compressor stations and reduce flaring under Texas and New Mexico venting limits. PHMSA integrity management rules mandate documented pressure testing records, forcing serial-communication retrofits across interstate networks. The Appalachian Basin corridor sees accelerated edge-computing adoption for remote gathering line monitoring.
Germany
Pipeline operators prioritize hydrogen-blending automation for natural gas mixtures as the country transitions energy infrastructure. EU F-Gas Regulation compliance requirements screen out vendors lacking certified emissions monitoring capabilities. Industrial clusters in North Rhine-Westphalia drive demand for modified valve control systems handling variable hydrogen concentrations.
Canada
Arctic corridor projects deploy modular automation skids integrating satellite telemetry with legacy fieldbus architectures. Federal pipeline safety regulations align with PHMSA-equivalent integrity management standards. Alberta's oil sands gathering networks require edge-deployed machine learning for leak detection where fiber connectivity remains unavailable.
Netherlands
CSRD-aligned disclosure mandates compel asset-level methane quantification systems at compressor stations. Rotterdam's LNG import terminals specify DCS platforms with embedded carbon intensity calculations. The country's hydrogen backbone initiative requires automation retrofits for converted natural gas pipelines.
Saudi Arabia
Master Gas System expansion drives procurement of unified control platforms spanning greenfield transmission corridors. The kingdom's national oil company specifies fully integrated architectures with performance-based uptime contracts. Eastern Province industrial cities anchor demand for predictive maintenance algorithms at pumping stations.
Oil and Gas Pipeline and Transportation Automation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue satellite-enabled edge analytics and hydrogen-compatible valve control. The vendor base stratifies across three tiers: integrated electrification-automation portfolios, specialized SCADA platform providers, and component suppliers for remote terminal units. Two strategic archetypes dominate: full-stack system integrators capturing long-term service contracts, and modular automation specialists winning brownfield retrofit assignments. Competitive intensity manifests through performance-based contracting and multi-vendor protocol harmonization capabilities.
Among diversified industrial conglomerates, ABB, Siemens, and Honeywell International Inc occupy positions anchoring the premium tier. ABB exemplifies the integrated portfolio archetype spanning electrification and automation infrastructure. Siemens represents turbine control specialization tied to compressor station deployments. Honeywell International Inc sits within the process knowledge system segment serving both greenfield LNG terminals and brownfield pipeline retrofits.
| Leading Market Players |
|---|
| ABB |
| Honeywell International Inc |
| Emerson Electric Co |
| Rockwell Automation Inc |
| Siemens |
| Yokogawa Electric Corporation |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Eaton Corporation |
| Others |
Pricing and Supply Chain Analysis
Copper futures and semiconductor spot indices cascade through remote terminal unit manufacturing, compressing margins for component suppliers while forcing tiered pricing stratification across SCADA hardware, edge computing modules, and integrated service contracts.
Pricing Analysis
Volume concentration among North American pipeline aggregators splits from margin capture by full-stack system integrators. Three-tier pricing structure across premium, standard, and economy levels separates certified emissions-monitoring systems from basic valve automation. Cost compression in standard-tier hardware intensifies because private-equity-backed midstream operators demand interoperability guarantees without full infrastructure replacement. Oil producers in Texas and New Mexico exhibit highest price sensitivity due to venting compliance deadlines, while European LNG terminal operators accept premium positioning for F-Gas Regulation-certified DCS platforms.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries supplying RTU processors and German precision valve manufacturers serving hydrogen-blending retrofits. Component sourcing draws from China for copper cabling, South Korea for memory chips, and the United States for pressure sensor assemblies. Tariff exposure on Chinese electrical components threatens cost predictability for modular automation skids. Distribution runs through authorized system integrators holding PHMSA documentation credentials and compressor station commissioning expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Midstream consolidation functions as a consolidation play, with PHMSA integrity management deadlines forcing weaker automation vendors without certified emissions capabilities from tender processes.
For Market Incumbents: Anchor long-term service contracts through performance-based uptime guarantees across consolidated Permian Basin networks. Deepen backward integration into edge computing hardware to offset semiconductor supply volatility. Prioritize multi-vendor protocol harmonization capabilities as the primary defensive moat against modular specialists winning brownfield retrofit assignments. For New Entrants and Emerging Players: Satellite connectivity providers represent the most penetrable channel partner type for Arctic corridor projects lacking fiber infrastructure. Target hydrogen-blending automation in Germany and the Netherlands where incumbent certification gaps persist. Pursue white-space positioning in predictive maintenance algorithms for remote gathering lines, leveraging low-earth-orbit telemetry as the go-to-market differentiator. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular automation specialists with proven brownfield integration capabilities in Alberta and Saskatchewan. Long-term viability hinges on regulatory compliance technology rather than commodity hardware cycles. Monitor CSRD enforcement intensity across European industrial clusters as the primary inflection signal for emissions-tracking automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contracting | Transfers operational risk to vendors across PHMSA-regulated interstate networks. |
| Hydrogen-Compatible Valve Control Development | Unlocks retrofit opportunities in Germany's hydrogen backbone initiative. |
| Edge Computing Hardware Backward Integration | Reduces exposure to Taiwanese semiconductor supply volatility. |
| CSRD-Aligned Emissions Certification | Qualifies vendors for European tender processes in Italy and Poland. |
| Satellite Telemetry Partnership | Enables real-time monitoring in Bakken formation gathering lines without fiber. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across SCADA platform engineers, midstream procurement directors, PHMSA compliance officers, and compressor station maintenance heads. Bottom-up installation estimates triangulated against top-down capital expenditure disclosures from pipeline aggregators and EPC contractors. PHMSA incident databases, EU F-Gas Regulation certification registries, and North American trade flow statistics provided validation anchors.
Granularity-level modeling deployed technology architecture, functional application, integration depth, and end-user concentration as segmentation dimensions. CAGRs derived from curve-fitting historical upgrade cycles against regulatory deadline clustering across the analysis window. Forecast inputs incorporated Permian Basin flaring enforcement timelines, EU Corporate Sustainability Reporting Directive phase-in schedules, and raw material price elasticity assumptions for copper and semiconductor components.
Caveats apply where PHMSA rulemaking revisions or EU F-Gas Regulation enforcement delays could materially shift the outlook. Forecasts reflect documented assumptions about midstream consolidation velocity and hydrogen infrastructure deployment pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
North America Shale Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Frac Stack Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market