
 Hose Pipe Market | 2026-2036
Hose Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Hose Pipe Market Analysis
China's expanding specialty rubber compounding capacity is reshaping competitive dynamics for reinforced hose exports. Parker Hannifin leverages its integrated distribution network across North American hydraulics channels to sustain premium positioning in high-pressure applications. Alfagomma Group anchors its European manufacturing base in Italy while extending production footprint into Southeast Asian assembly plants for cost-sensitive industrial segments.
A hose pipe is a flexible, hollow conduit engineered from elastomeric or thermoplastic compounds, typically reinforced with textile braids, wire helixes, or synthetic yarn to withstand internal pressure ratings from 150 psi to over 6,000 psi depending on service class. Its primary function is to convey fluids, gases, or granular materials under pressure across industrial, agricultural, commercial, and residential systems where rigid piping cannot accommodate vibration, thermal expansion, or spatial constraints. Industrial hose commands the dominant value share due to extreme pressure and chemical resistance specifications, while polyurethane material formulations represent the fastest-expanding segment driven by abrasion resistance requirements in pneumatic tooling and material handling equipment. Garden hose remains a mature, price-sensitive category with margin pools concentrated in retail-branded seasonal distribution channels.
REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation on fluorinated polymer production are tightening material compliance requirements for European hose manufacturers, directly elevating R&D expenditure on bio-based plasticizer and thermoplastic vulcanizate alternatives. The US EPA and OSHA jointly enforce permeation and workplace exposure standards that dictate compound selection and labeling protocols for fuel-delivery and chemical-transfer hose sold into American industrial end markets. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds have historically enabled critical chemical resistance in high-performance industrial hose constructions.
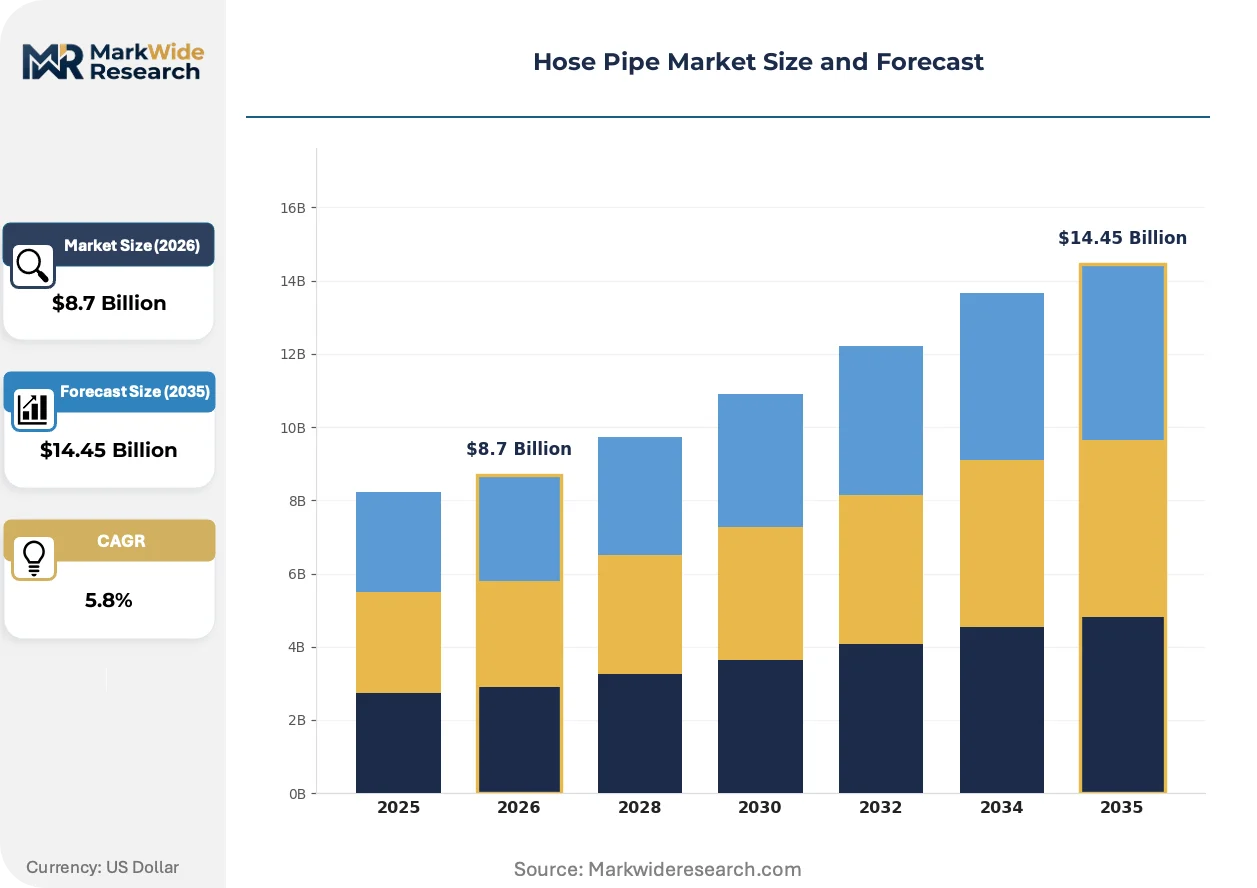
Market Dynamics
REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation are forcing material transitions across European manufacturing bases, while China's Shandong and Zhejiang clusters consolidate integrated rubber compounding and extrusion capabilities for export-grade industrial hose.
Growth Catalysts
- EU REACH compliance mandates:Phased restrictions on legacy plasticizers accelerate thermoplastic elastomer and bio-based compound adoption among German and Italian compounders seeking sustained market access.
- Agricultural mechanization in India and Brazil:Scaled irrigation infrastructure deployment drives reinforced polymer hose procurement for pivot and drip systems across water-stressed farming regions.
- Polyurethane formulation advances:Enhanced abrasion resistance specifications in pneumatic tooling and material handling equipment expand addressable demand in industrial maintenance segments.
Market Restraints
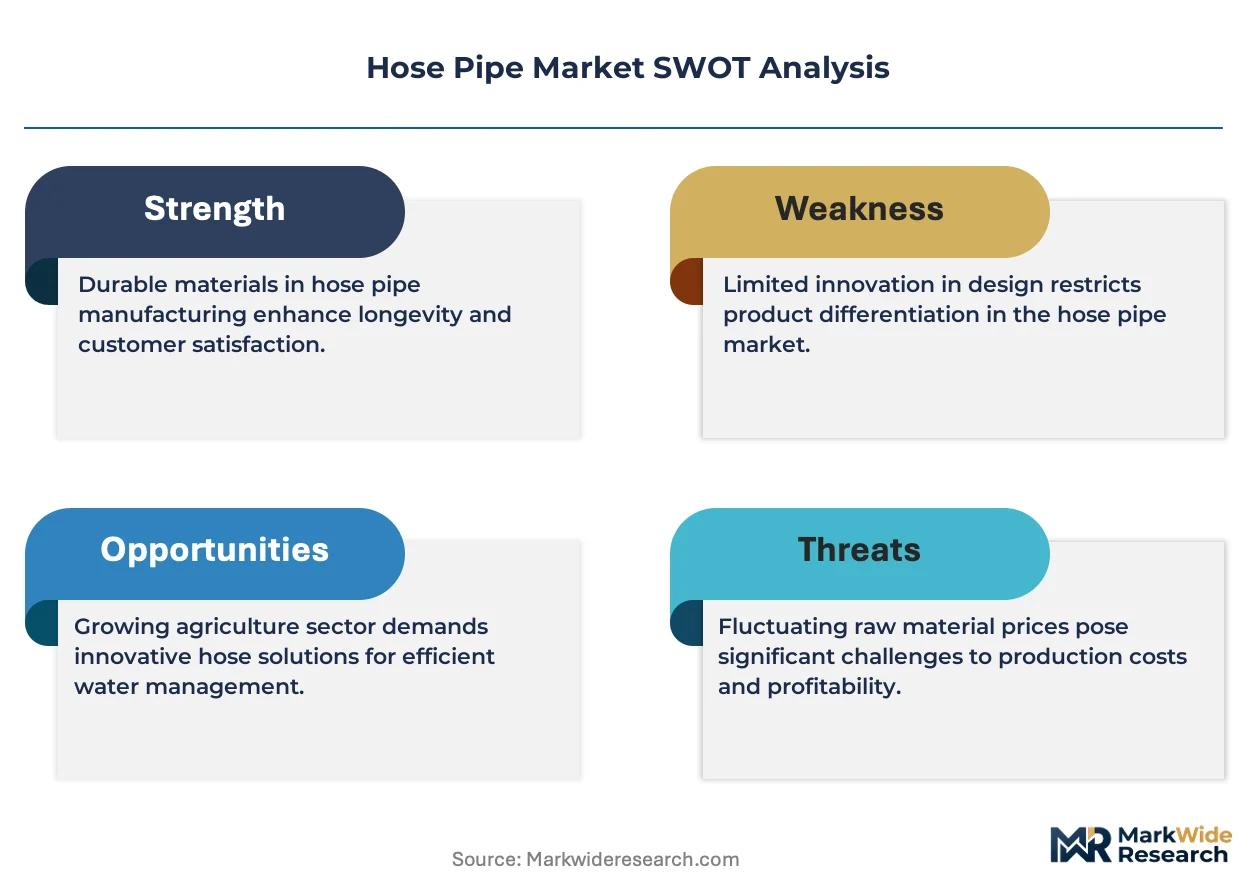
- Crude oil derivative volatility:Synthetic rubber and thermoplastic feedstock costs fluctuate with naphtha and butadiene pricing, compressing margin predictability for compound-dependent manufacturers.
- Fluoropolymer supply concentration:EU F-Gas Regulation constrains domestic fluorinated polymer production, elevating import dependency for chemical-resistant industrial hose constructions.
- Per- and polyfluoroalkyl substance restrictions:Emerging regulatory limits across multiple jurisdictions threaten historical performance advantages in high-specification chemical transfer applications.
Strategic Opportunities
- Thermoplastic vulcanizate scale-up:European compounders investing in TPV production lines capture displaced phthalate-dependent volume while meeting automotive and industrial OEM sustainability scorecards.
- Indonesian and Vietnamese assembly expansion:Southeast Asian manufacturing bases offer tariff-advantaged export positioning for cost-sensitive industrial segments serving Australian and Middle Eastern end markets.
- Integrated rubber-tube-and-hose facilities:Backward integration into captive polymer compounding reduces material cost variance and shortens lead times for specialty reinforced constructions.
Industry Challenges
- Compound formulation expertise scarcity:Migration from legacy plasticizers to bio-based alternatives demands polymer science capabilities concentrated among aging technical workforces in European and Japanese compounders.
- Multi-jurisdiction certification timelines:Parallel EPA, OSHA, and EU harmonized standard compliance extends product launch cycles for fuel-delivery and chemical-transfer hose categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hose Pipe Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Hose, Air Hose, Garden Hose, Industrial Hose Material: Braided PVC, Rubber, Polyurethane, Silicone End User: Construction, Agriculture, Manufacturing, Automotive Diameter: Small, Medium, Large, Extra Large |
| Companies Covered | Manuli Hydraulics, Semperit, Parker Hannifin, Polyhose India, Sinopulse, Gates Corporation, Alfagomma Group, Kuriyama of America, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hose Pipe Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are restructuring competitive advantage around sustainable compound portfolios and integrated manufacturing footprints rather than discrete component assembly.
Thermoplastic vulcanizate compounds are migrating from niche automotive sealing applications into mainstream industrial hose constructions. Agricultural equipment OEMs in India and Brazil specify TPV-sheathed reinforced hoses for UV and microbial resistance in extended field deployment. This technology is migrating from premium positioning toward mid-tier cost structures as Chinese compounders achieve production scale.
EU F-Gas Regulation phase-down schedules constrain domestic fluoropolymer production capacity for chemical-resistant hose liners. German and Italian manufacturers accelerate perfluoroalkoxy alkane and ethylene tetrafluoroethylene alternative qualification programs. High-purity chemical transfer segments in pharmaceutical and semiconductor process industries face extended material validation timelines.
Industrial maintenance buyers consolidate supplier relationships around full-line fluid power distributors capable of technical specification support and inventory pooling. North American hydraulics channel partners displace traditional hose-and-fitting jobbers through integrated sealing, coupling, and assembly services. This concentration pattern is most visible in oil and gas field service operations across Texas and Alberta extraction basins.
Hose Pipe Market Segmentation
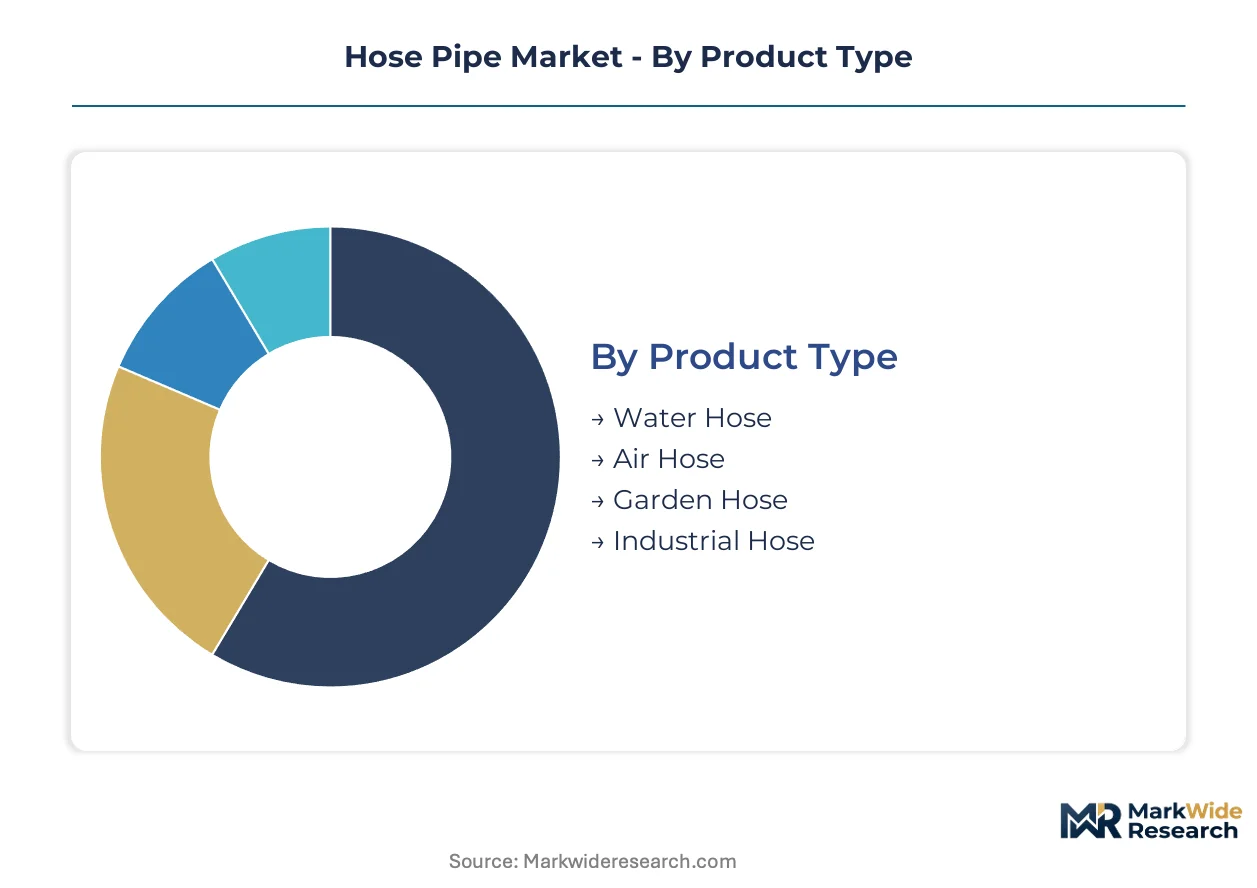
Hose pipe segmentation reveals divergent margin structures across product maturity levels. Material chemistry and end-use specifications create distinct competitive arenas with varying barriers to substitution and regulatory exposure.
Product Type:
Mature commodity categories dominate unit volume while specialized constructions capture expanding specification premiums.
- Industrial Hose:Multi-layer elastomeric constructions reinforced with wire helixes or textile braids withstand pressure ratings exceeding 6,000 psi for hydraulic and chemical transfer applications. Demand concentrates in Texas and Alberta oilfield service operations where integrated fluid power distributors displace traditional hose-and-fitting jobbers through bundled sealing and assembly services.
- Garden Hose:Flexible PVC or rubber tubes with burst pressures of 150-300 psi serve residential irrigation and maintenance tasks. Procurement runs through retail-branded seasonal distribution channels with margin pools concentrated in North American home improvement chains and European garden center networks.
- Water Hose:General-purpose constructions for municipal and commercial fluid conveyance.
- Air Hose:Reinforced thermoplastic or rubber designs for pneumatic tooling and compressor systems.
Industrial Hose retains volume leadership; Garden Hose holds the steepest expansion curve in emerging economy retail penetration.
Material:
Cost tier stratification separates premium performance compounds from commodity formulations facing regulatory displacement.
- Polyurethane:Thermoplastic elastomer formulations deliver superior abrasion resistance for pneumatic conveying and material handling equipment. Agricultural equipment OEMs in India and Brazil specify polyurethane-sheathed reinforced hoses for UV and microbial resistance in extended pivot irrigation deployment.
- Rubber:Natural and synthetic elastomer compounds provide flexibility across temperature extremes from -40°C to 120°C. China's Shandong and Zhejiang manufacturing clusters consolidate integrated rubber compounding and extrusion capabilities for export-grade industrial constructions.
- Braided PVC:Cost-optimized constructions for low-pressure residential and light commercial applications.
- Silicone:High-purity formulations for pharmaceutical and food processing transfer with extreme temperature tolerance.
Rubber formulations anchor volume; Polyurethane climbs the fastest on abrasion resistance specifications.
End User:
Application-driven procurement patterns separate project-based construction demand from recurring agricultural replacement cycles.
- Agriculture:Reinforced polymer hose procurement scales with mechanized irrigation infrastructure across water-stressed farming regions. India's central and state government subsidy programs for drip and sprinkler systems accelerate specification-grade hose adoption beyond traditional gravity-fed alternatives.
- Construction:Temporary fluid power and dewatering applications drive rental fleet and contractor procurement with high replacement frequency. Brazilian infrastructure investment programs sustain demand for high-pressure concrete pumping and slurry transfer constructions.
- Manufacturing:Plant maintenance and process integration requirements across discrete and continuous production environments.
- Automotive:OEM assembly and aftermarket service specifications for coolant, fuel, and brake system conveyance.
Agriculture commands replacement volume leadership; Construction maintains the steepest project-driven expansion trajectory.
Diameter:
Supply concentration favors medium and large formats where extrusion equipment utilization rates maximize manufacturing efficiency.
- Large:Diameters exceeding 50mm serve mining slurry transport, dredging operations, and bulk material handling with reinforced wall constructions. German and Italian manufacturers qualify perfluoroalkoxy alkane liners for high-purity chemical transfer in pharmaceutical process industries facing EU F-Gas Regulation constraints.
- Medium:25-50mm formats balance flow capacity with handling flexibility across industrial maintenance and agricultural mechanization segments. Indonesian and Vietnamese assembly plants target tariff-advantaged export positioning for cost-sensitive medium-diameter industrial segments serving Australian and Middle Eastern end markets.
- Small:Precision formats for instrumentation, lubrication, and compact pneumatic systems.
- Extra Large:Specialized mining and marine applications with custom-engineered reinforcement patterns.
Medium diameter retains volume leadership; Large diameter gains share fastest on mining and process industry specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA and OSHA jointly enforce permeation standards that dictate compound selection for fuel-delivery hose sold into American industrial end markets. China's Shandong and Zhejiang clusters consolidate integrated rubber compounding capabilities that reshape export-grade industrial hose economics.
United States
Oilfield service operations across Texas and Alberta sustain demand for high-pressure hydraulic constructions. EPA workplace exposure standards mandate specific labeling protocols for chemical-transfer categories. Integrated fluid power distributors in Houston displace traditional hose-and-fitting jobbers through bundled sealing and assembly services.
Germany
Automotive and industrial OEM sustainability scorecards accelerate thermoplastic vulcanizate qualification timelines. REACH restrictions on phthalate plasticizers force compound transitions among Baden-Württemberg specialty rubber processors. Stuttgart-area compounders invest in bio-based plasticizer R&D to sustain market access.
China
Shandong and Zhejiang manufacturing clusters achieve production scale that lowers unit costs for reinforced polymer exports. MIIT industrial upgrading policies favor integrated rubber-tube-and-hose facilities with captive compounding capabilities. Qingdao-based producers target Australian and Middle Eastern industrial segments with tariff-advantaged medium-diameter constructions.
India
Central and state government subsidy programs for drip and sprinkler systems accelerate specification-grade hose procurement. BIS certification requirements shape compound selection for agricultural irrigation deployments. Maharashtra and Gujarat equipment OEMs specify reinforced polymer constructions for pivot systems across water-stressed farming regions.
Brazil
Infrastructure investment programs sustain demand for high-pressure concrete pumping and slurry transfer constructions. ANVISA regulatory frameworks influence material selection for food-grade and pharmaceutical transfer applications. São Paulo-state manufacturers serve Mercosur industrial segments with cost-optimized rubber formulations.
Hose Pipe Market Vendor Landscape
Vertically integrated compounders and assembly-focused distributors split the market along specification intensity lines. The vendor base concentrates around three strategic archetypes: integrated rubber compounders with captive extrusion capabilities, full-line fluid power distributors with technical specification support, and regional jobbers serving price-sensitive replacement cycles. Dominant competitive moves include backward integration into polymer compounding to reduce material cost variance, and geographic expansion into Southeast Asian assembly plants for tariff-advantaged export positioning.
Within the integrated compounder tier, Parker Hannifin and Alfagomma Group exemplify divergent geographic anchoring strategies. Parker Hannifin occupies a position tied to North American hydraulics channel density. Alfagomma Group represents European manufacturing base persistence with Italian origins. Gates Corporation sits within the diversified industrial conglomerate archetype with cross-segment fluid power exposure.
| Leading Market Players |
|---|
| Manuli Hydraulics |
| Semperit |
| Parker Hannifin |
| Polyhose India |
| Sinopulse |
| Gates Corporation |
| Alfagomma Group |
| Kuriyama of America |
| Eaton |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor channels synthetic rubber and thermoplastic feedstock flows that directly condition margin structures for European compounders facing REACH compliance costs, while Qingdao-based exporters leverage Shandong cluster density to undercut premium pricing tiers through integrated compounding capabilities.
Pricing Analysis
Geographic price spreads between Italian-manufactured specialty hose and Chinese export-grade constructions exceed three-to-one on equivalent pressure ratings. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification burden and after-sales technical support requirements. Cost compression in economy-tier reinforced polymer hose intensifies because Brazilian and Indian agricultural OEMs consolidate procurement around landed-cost optimization. Municipal water authorities exhibit lowest price sensitivity due to specification-grade compliance mandates, while seasonal garden hose retail buyers drive hardest bargain through private-label sourcing.
Supply Chain Analysis
Contract manufacturing concentration among Shandong and Zhejiang integrated rubber-tube-and-hose facilities supplies the majority of export-grade industrial constructions serving Australian and Middle Eastern end markets. Geographic supply concentration centers on China, Germany, and Italy for compounding expertise and extrusion capacity. Raw material dependencies rest on naphtha-derived synthetic rubber, butadiene monomer, and thermoplastic elastomer pellets sourced from petrochemical complexes. Single-source vulnerability concentrates in fluoropolymer liner supply following EU F-Gas Regulation phase-downs. Distribution runs through full-line fluid power distributors displacing traditional hose-and-fitting jobbers in North American oilfield service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hose pipe demand sits in early-cycle expansion as agricultural mechanization subsidies in India and Brazil accelerate specification-grade polymer adoption beyond gravity-fed legacy systems.
For Market Incumbents: Harden compound formulation capabilities against bio-based plasticizer transitions mandated by REACH restrictions. Secure captive supply of thermoplastic vulcanizate production lines to displace phthalate-dependent volume. Deepen channel control through integrated sealing and assembly services that technical buyers now require.
For New Entrants and Emerging Players: Establish a beachhead in Indonesian and Vietnamese assembly plants for tariff-advantaged export positioning serving Australian industrial maintenance segments. Target cost-sensitive medium-diameter constructions where incumbent premium pricing leaves margin headroom. Pursue agricultural equipment OEM direct procurement relationships bypassing established distributor networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming fluid power divisions lacking technical specification support infrastructure. Long-term viability hinges on compound science capabilities and regulatory compliance infrastructure rather than discrete assembly scale. Monitor BIS certification acceleration in Indian agricultural subsidy programs as inflection signal for specification-grade demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Polymer Compounding | Reduces material cost variance for Shandong exporters serving Middle Eastern oilfield contractors. |
| Thermoplastic Vulcanizate Production Line Investment | Captures displaced phthalate-dependent volume among German automotive OEM sustainability scorecards. |
| Southeast Asian Assembly Plant Expansion | Delivers tariff-advantaged positioning for Vietnamese producers targeting Australian mining slurry segments. |
| Integrated Sealing and Assembly Service Bundling | Enables Houston-based fluid power distributors to displace traditional hose-and-fitting jobbers. |
| Bio-Based Plasticizer R&D Program | Sustains EU market access for Stuttgart-area compounders facing REACH restriction timelines. |
Methodological Framework
Desk research of customs trade databases, MIIT industrial policy filings, and EPA enforcement records preceded structured interviews with plant engineers at agricultural equipment OEMs, procurement leads at fluid power distributors, technical R&D directors at compounders, and aftermarket service heads at oilfield service contractors. Primary fieldwork combined with secondary validation from SEC 10-K disclosures, BIS certification registries, and EU F-Gas Regulation implementation reports. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume estimates.
Assumption sets held regulatory phase-down schedules and crude oil derivative pricing bands fixed while varying agricultural subsidy intensity and infrastructure investment cycles across the projection horizon. Segmentation dimensions modeled include product type, material chemistry, end-use industry, diameter format, and regional manufacturing cluster. CAGRs derived from historical elasticity analysis applied to demand drivers. Industry-specific inputs incorporated irrigation mechanization penetration rates and fluoropolymer supply constraint scenarios.
Stress conditions across naphtha price volatility, REACH enforcement intensity, and Indian monsoon rainfall patterns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on subsidy program continuity and regulatory timeline adherence. Quarterly review of BIS certification issuance rates and EU ECHA substance restriction proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Sorting Equipment Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Global Submersible Slurry Pumps Market