
 Truck Mounted Loader Cranes Market | 2026-2036
Truck Mounted Loader Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Mounted Loader Cranes Market Insights
The gap between premium and commodity tiers is broadening in the truck mounted loader cranes space. Palfinger AG leverages its European manufacturing footprint to sustain high-specification output for regulated markets. Hiab AB dominates Nordic and Baltic channels through dense service networks and standardized knuckle-boom configurations.
Truck mounted loader cranes are hydraulic lifting devices permanently installed on commercial vehicle chassis, typically offering load moments from 30 kNm to over 100 kNm and controlled via radio remote or seated operation for material handling in constrained spaces. Knuckle-boom architectures lead European urban deployment due to compact stowage and maneuverability, while telescopic boom variants anchor long-reach applications in North American construction and energy logistics where single-set-up efficiency commands premium positioning.
The EU Machinery Directive, CE marking requirements, and OSHA crane standards in the United States collectively shape product certification cycles and aftermarket compliance costs for manufacturers serving transatlantic customer bases. China's GB standards and NMPA-equivalent equipment safety frameworks add parallel testing obligations for suppliers targeting domestic infrastructure programs. Stakeholders must weigh regional certification divergence against platform standardization economics when allocating R&D budgets and assembly capacity across manufacturing footprints.
Market Dynamics
EU Machinery Directive recertification deadlines and OSHA crane standard updates are compressing product development cycles, forcing simultaneous redesign of hydraulic architectures across multiple certification regimes.
Growth Catalysts
- India National Highway Expansion:Port modernization and logistics corridor construction sustain procurement of knuckle-boom and telescopic units for material handling in constrained urban sites.
- EU F-Gas Regulation:Phasedown of high-GWP refrigerants accelerates electrification of auxiliary power units in loader crane systems, opening retrofit demand.
- Telematics integration:Real-time load monitoring and predictive maintenance capabilities reduce downtime for fleet operators managing distributed construction assets.
Market Restraints
- Specialized steel alloy costs:High-strength boom steel price volatility compresses margin buffers for mid-tier OEMs without long-term supply agreements.
- Hydraulic component concentration:German and Italian pump and valve suppliers control critical subassembly capacity, creating single-source vulnerability.
- Battery energy density limits:Current lithium-ion configurations restrict all-electric crane duty cycles below diesel-hybrid alternatives in heavy-lift applications.
Strategic Opportunities
- Vietnam infrastructure buildout:ASEAN logistics hub investments lack established loader crane service networks, creating first-mover positioning for rental fleet operators.
- EU CSRD disclosure mandates:Scope 3 emissions reporting requirements favor suppliers with verified lifecycle carbon data, differentiating certified manufacturers.
- Remote operation convergence:Integration of 5G low-latency control with camera-based load positioning enables operation in hazardous environments without cab presence.
Industry Challenges
- Certification timeline compression:Parallel CE marking, OSHA, and GB standard testing extends product launch windows by 8-14 months for multi-region platforms.
- Hydraulics-electronics skill gap:Maintenance technician shortages in emerging markets delay service response times and inflate warranty costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Mounted Loader Cranes Market |
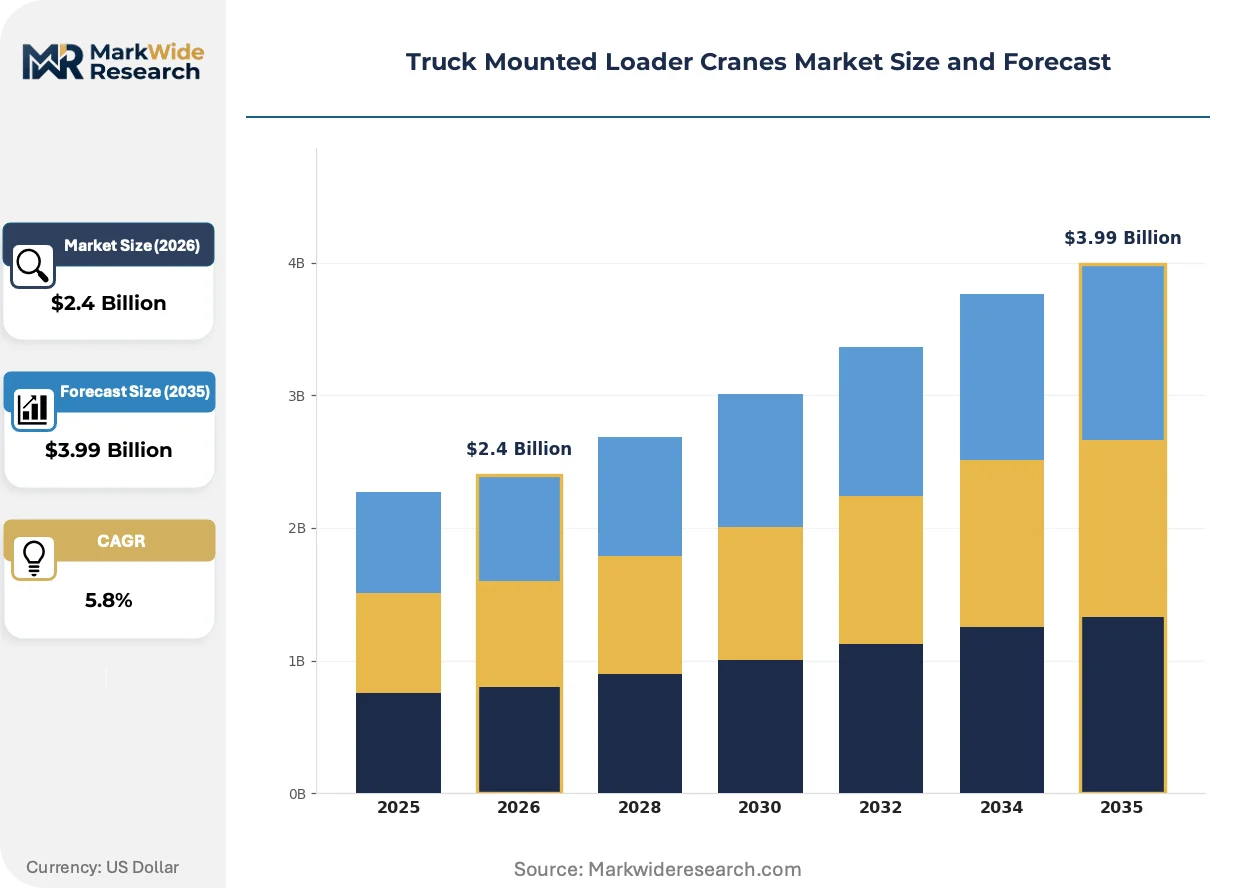
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knuckle Boom, Straight Boom, Telescopic Boom, Articulated Boom Application: Construction Sites, Maritime Operations, Logistics & Transport, Waste Management, Forestry End User: Infrastructure Contractors, Shipping Companies, Freight Operators, Waste Collection Agencies Deployment: Urban Areas, Industrial Parks, Remote Locations, Ports |
| Companies Covered | Palfinger AG, Tadano Ltd, Fassi Gru S.p.A, Hiab AB, Manitex International, Inc, Sany Group Co. Ltd, Hyva Crane, XCMG Group, Liebherr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Mounted Loader Cranes Market Trends and Innovations
Electrification of auxiliary systems and digital load management are redefining equipment specification criteria, with buyers prioritizing connectivity-enabled uptime guarantees over standalone mechanical performance metrics.
Sensor-fusion load monitoring is automating stability control in real-time boom operation. Construction contractors in Germany and France are specifying these systems on new knuckle-boom orders to reduce operator certification burden. The technology is automating the displacement of manual load-chart consultation, compressing setup time and reducing tip-over incidents in urban deployment.
REACH substance restrictions on hydraulic fluids are forcing reformulation of synthetic lubricants across European supply chains. OEMs serving transatlantic markets face parallel inventory management for compliant and non-compliant fluid specifications. Nordic rental fleets are absorbing the cost premium fastest due to national environmental procurement mandates.
Equipment-as-a-service contracting is displacing traditional capital purchase for mid-size logistics operators. Dutch and Belgian transport companies now specify availability-based payment structures with bundled maintenance. This shift concentrates most visibly in Benelux urban delivery networks where fleet utilization rates justify operational expenditure models.
Truck Mounted Loader Cranes Market Segmentation
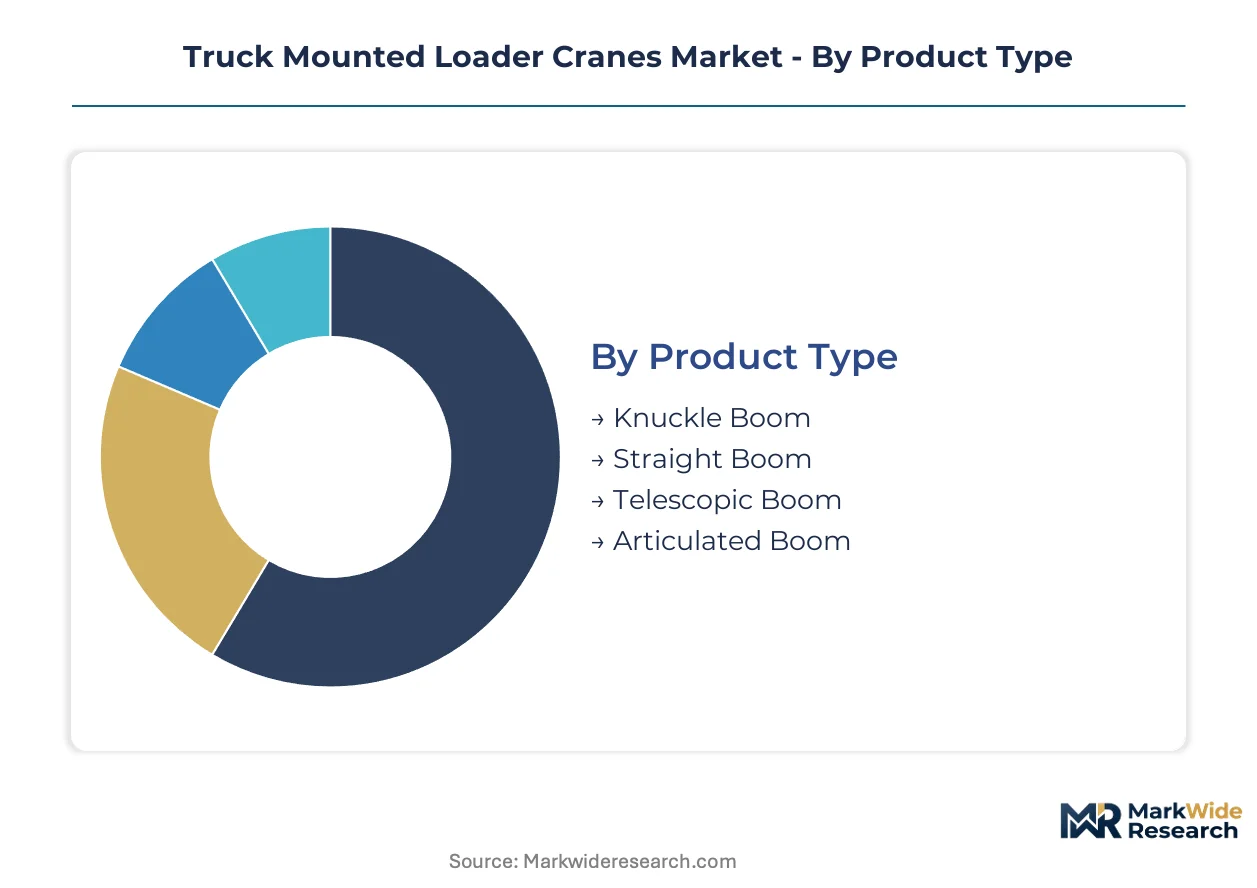
Truck mounted loader cranes serve heterogeneous operational environments where boom geometry, duty cycle intensity, and site accessibility dictate specification requirements. Procurement patterns diverge sharply between fleet operators optimizing for stowage efficiency and contractors prioritizing single-set-up reach.
Product Type:
Supply concentration tilts toward knuckle-boom architectures where European OEMs maintain captive manufacturing of high-strength steel fabrications and proprietary hydraulic valve blocks.
- Knuckle Boom:Multi-articulated arm geometry enables compact stowage alongside truck cabs and operation within confined urban corridors. German and Austrian infrastructure contractors specify these units for metropolitan utility work where street width restrictions apply.
- Telescopic Boom:Nested box-section extensions deliver extended horizontal reach without articulation joints. North American energy logistics operators deploy these for pipeline maintenance where single-position loading eliminates repositioning downtime.
- Straight Boom:Fixed-length lattice or box construction optimized for vertical lift capacity at minimal cost. Rural construction fleets in emerging markets favor these for repetitive material hoisting where maneuverability is secondary.
- Articulated Boom:Hybrid geometry combining knuckle joints with telescopic sections for specialized reach-around applications. Scandinavian forestry equipment specialists specify these for loading cut timber in dense stand conditions.
Knuckle boom configurations absorb the bulk of installed capacity in regulated European markets; telescopic boom variants are expanding most quickly in North American energy corridor applications.
Application:
Cost tier differentiation separates premium-specification units bound for maritime corrosion environments from standardized configurations serving inland logistics.
- Construction Sites:High-cycle material handling demands reinforced boom structures and overload protection systems. Indian national highway contractors are procuring knuckle-boom fleets for bridge deck work where crane positioning space is constrained.
- Logistics & Transport:Rapid loading cycles and driver-operated controls dominate specification criteria. Benelux distribution networks specify radio-remote units for last-mile pallet handling without dedicated crane operators.
- Maritime Operations:Salt-air corrosion resistance requires specialized coatings and stainless hydraulic lines. Port modernization programs in India specify these for container lashing and ship supply operations.
- Waste Management:Continuous-duty hydraulic cooling and contamination-resistant seals address refuse compaction cycles. Municipal fleets in France specify these for underground container emptying operations.
- Forestry:Severe shock loading and off-road chassis integration dominate technical requirements. Nordic cut-to-length harvesting operations specify articulated boom geometries for roadside log concentration.
Construction site deployment commands the largest share of annual procurement volume; logistics and transport applications are gaining share fastest as e-commerce fulfillment networks expand fleet specifications.
End User:
Customer type determines aftermarket service bundling intensity, with infrastructure contractors demanding predictive maintenance integration and freight operators prioritizing acquisition cost minimization.
- Infrastructure Contractors:Project-based procurement cycles favor rental fleet relationships and availability guarantees. German highway construction consortia specify telematics-enabled units for distributed asset tracking across multiple simultaneous sites.
- Freight Operators:High fleet turnover and standardized specifications drive volume purchasing agreements. Belgian parcel delivery networks are shifting toward equipment-as-a-service contracting with bundled maintenance obligations.
- Shipping Companies:Port authority compliance requirements and shore-power compatibility shape procurement checklists. Mediterranean container terminal operators specify these for intermodal transfer operations.
- Waste Collection Agencies:Municipal procurement mandates favor lifecycle cost analysis over upfront capital expenditure. French departmental authorities specify these for automated underground waste system servicing.
Infrastructure contractors represent the dominant installed base by unit count; freight operators are expanding their share fastest through operational expenditure contracting models.
Deployment:
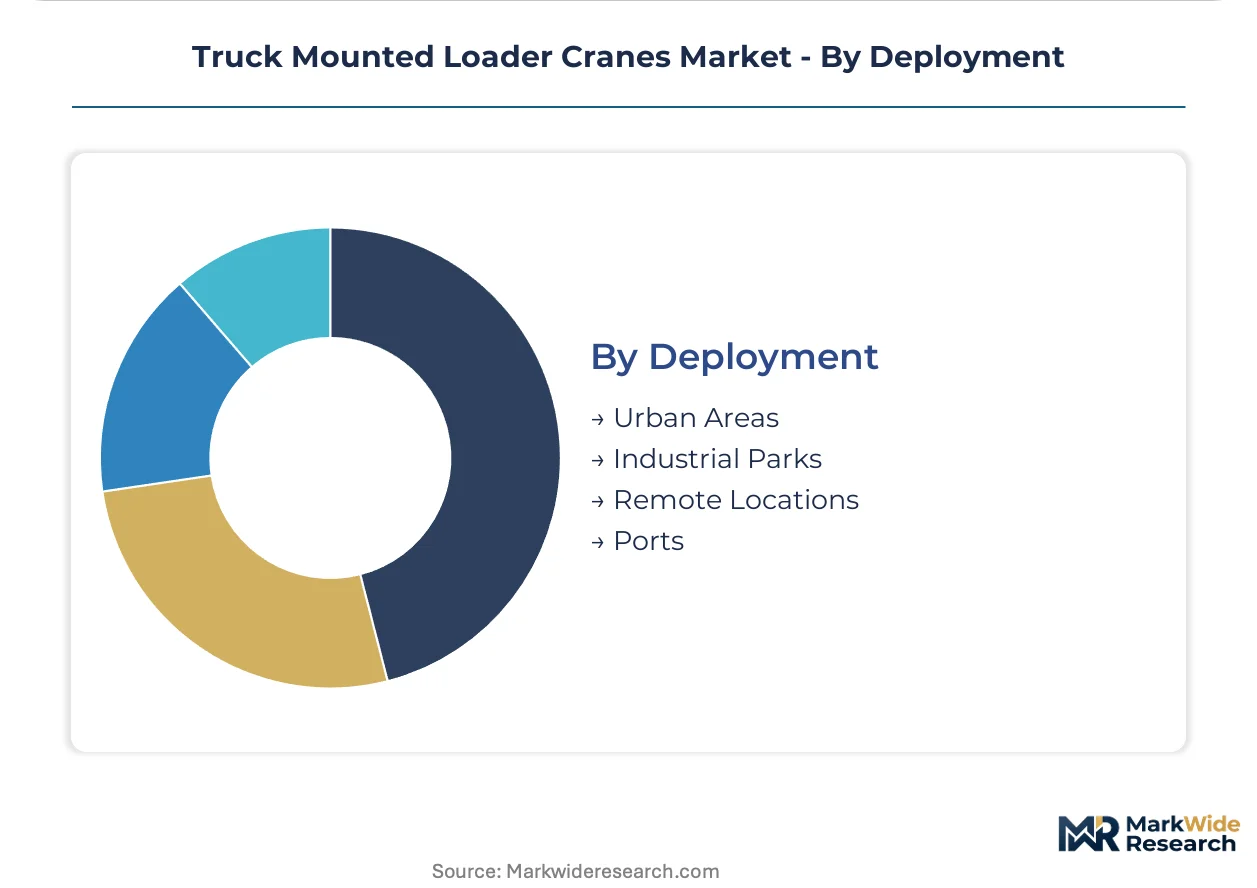
Geographic deployment patterns correlate with regulatory stringency, with urban areas imposing emissions and noise restrictions that accelerate electrification investment.
- Urban Areas:Noise ordinances and congestion charging zones favor electric auxiliary power units and compact stowage geometries. Paris and Berlin municipal fleets specify EU F-Gas compliant refrigerant systems for auxiliary climate control.
- Ports:Shore power availability and emissions control areas drive specification of electrified or hybrid powertrains. Indian port modernization programs specify knuckle-boom units for container handling in confined terminal layouts.
- Industrial Parks:Predictable duty cycles and centralized maintenance facilities enable standardized fleet configurations. German automotive supplier parks specify these for just-in-time component sequencing.
- Remote Locations:Diesel self-sufficiency and field serviceability dominate specification criteria. North American oilfield service operators specify these for wellhead maintenance where grid connectivity is absent.
Urban deployment environments absorb the majority of premium-specification production; port applications are climbing the fastest as maritime decarbonization timelines accelerate fleet replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates German loader crane demand through dense logistics networks serving automotive supplier parks and construction material distribution.
Germany
Rhineland-Palatinate infrastructure contractors specify knuckle-boom fleets for metropolitan utility corridors where street width restrictions apply. KBA vehicle certification requirements and EU Machinery Directive recertification deadlines compress product development cycles for domestic OEMs. Stuttgart automotive supplier parks drive standardized fleet procurement for just-in-time component sequencing operations.
United States
Permian Basin oilfield service operators deploy telescopic boom units for wellhead maintenance where grid connectivity is absent and single-position loading eliminates repositioning downtime. OSHA crane standard updates force simultaneous hydraulic architecture redesigns alongside European certification regimes. Houston-Galveston port complexes anchor maritime specification demand for corrosion-resistant configurations.
India
National highway expansion programs sustain bridge deck construction procurement where crane positioning space is severely constrained. BIS equipment safety frameworks and DGFT import regulations add parallel testing obligations for multinational suppliers establishing local assembly. Jawaharlal Nehru Port Trust modernization drives knuckle-boom deployment for container lashing in confined terminal layouts.
China
Yangtze River Delta logistics hubs absorb high-volume telescopic boom procurement for intermodal container transfer operations. GB standards and NMPA-equivalent equipment safety frameworks require dedicated certification tracks distinct from European or North American regimes. Shanghai port automation programs specify hybrid powertrain compatibility for shore-power electrification timelines.
France
Paris municipal fleets specify EU F-Gas compliant refrigerant systems for auxiliary climate control in congestion charging zones. ANSM environmental procurement mandates accelerate absorption of REACH-compliant hydraulic fluid reformulation costs. Île-de-France waste collection authorities specify continuous-duty hydraulic cooling for underground container emptying operations.
Truck Mounted Loader Cranes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and aftermarket service bundling intensity. The vendor base stratifies into three tiers: integrated European OEMs with captive hydraulic valve production, Asian scale manufacturers serving price-sensitive emerging markets, and regional fabricators specializing in chassis integration for local transport regulations. Dominant competitive moves include backward integration into high-strength steel supply agreements and technology licensing partnerships for telematics-enabled load monitoring systems.
Among Austrian-integrated specialists, Palfinger AG exemplifies the premium-tier archetype through European manufacturing footprint concentration. Hiab AB and Fassi Gru S.p.A occupy positions within the knuckle-boom specialization vector, with the former anchoring Nordic service network density and the latter representing Italian hydraulic fabrication heritage. Sany Group Co. Ltd and XCMG Group exemplify scale-driven Chinese manufacturers expanding through emerging market infrastructure programs.
| Leading Market Players |
|---|
| Palfinger AG |
| Tadano Ltd |
| Fassi Gru S.p.A |
| Hiab AB |
| Manitex International, Inc |
| Sany Group Co. Ltd |
| Hyva Crane |
| XCMG Group |
| Liebherr Group |
| Others |
Pricing and Supply Chain Analysis
High-strength steel alloy costs cascade through loader crane manufacturing tiers, with German and Austrian fabricators commanding premium positioning for specialized boom constructions while Asian scale producers absorb margin compression through volume procurement of standardized plate grades.
Pricing Analysis
Uptime-based availability contracts anchor value-based pricing for mid-size logistics operators in Benelux urban delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified European OEMs with captive hydraulic production from Chinese manufacturers serving price-sensitive emerging market contractors. Cost compression in the commodity tier is intensifying because Indian highway expansion programs prioritize acquisition cost minimization over lifecycle service bundling. Freight operators exhibit highest price sensitivity; infrastructure contractors with project-based procurement cycles demonstrate lowest sensitivity due to rental fleet availability guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Indian national highway consortia and Chinese Yangtze River Delta logistics hubs, while specialized distributors serve fragmented European construction contractors. Manufacturing concentration centers on Germany, Italy, and China, with German and Italian pump and valve suppliers controlling critical hydraulic subassembly capacity. The supply chain draws from specialized high-strength steel alloys, precision hydraulic components, and corrosion-resistant coating systems. Single-source vulnerability in hydraulic valve blocks creates structural risk for multi-region platform launches. Distribution runs through OEM-captive service networks in regulated markets and independent chassis integrators in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Loader crane manufacturing is consolidating around backward integration into high-strength steel supply agreements and in-house production of telematics-enabled load monitoring systems as the primary competitive lever.
For Market Incumbents: Acquire captive hydraulic valve production capacity to neutralize single-source vulnerability from German and Italian suppliers. Secure long-term supply agreements for specialized boom steel alloys to buffer margin compression from spot market volatility. Palfinger AG and Hiab AB must deepen certification investment across parallel CE marking, OSHA, and GB standard regimes to defend against emerging Chinese scale manufacturers expanding through Belt and Road infrastructure programs. For New Entrants and Emerging Players: EU F-Gas Regulation phasedown of high-GWP refrigerants opens a window for electrified auxiliary power unit specialists to capture retrofit demand in Nordic and Benelux municipal fleets. Vietnam infrastructure buildout lacks established service networks, creating first-mover positioning for rental fleet operators with telematics-enabled asset tracking. Target equipment-as-a-service contracting models for mid-size logistics operators shifting from capital purchase to operational expenditure structures. For Investors and Strategic Acquirers: Accelerated procurement of knuckle-boom fleets by Indian national highway contractors is the leading indicator that emerging market infrastructure programs will sustain volume growth independent of developed market cyclicality. Focus acquisition screening on European OEMs with verified lifecycle carbon data for EU CSRD Scope 3 disclosure compliance. Watch for 5G low-latency remote operation integration announcements as the signal for technology-led competitive repositioning in hazardous environment applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Strength Steel Supply | Secures margin buffers against alloy price volatility for boom fabrication. |
| Telematics-Enabled Load Monitoring Development | Reduces operator certification burden through sensor-fusion automation. |
| EU F-Gas Compliant Electrification Program | Captures retrofit demand from Nordic environmental procurement mandates. |
| Equipment-as-a-Service Platform Launch | Aligns with Benelux logistics operators shifting to availability-based payments. |
| Multi-Region Certification Parallelization | Compresses product launch windows across CE marking, OSHA, and GB standard regimes. |
Research Methodology
Trade association filings, customs and import-export databases, and OEM technical documentation formed the secondary backbone for supply chain mapping and pricing tier analysis. Primary interviews with fleet maintenance directors, infrastructure project procurement managers, hydraulic component sourcing leads, and aftermarket service heads validated demand patterns and certification timeline compression effects. Bottom-up unit shipment estimates triangulated against top-down construction and logistics equipment expenditure data.
Historical trendline analysis of knuckle-boom versus telescopic boom procurement ratios informed segmentation splits across boom geometry types. The analytical framework modeled deployment environment, end-user contracting structure, and duty cycle intensity as core dimensions throughout the forecast period. CAGRs derived from equipment replacement cycle analysis and infrastructure program announcement tracking. Forecast inputs incorporated EU Machinery Directive recertification deadlines and Indian port modernization procurement schedules.
The model assumes a particular technology adoption path for electrified auxiliary systems; alternative pathways for battery energy density improvement or hydrogen fuel cell integration would alter the outlook for all-electric crane duty cycles. Forecasts reflect assumptions about regulatory timeline adherence and steel alloy supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Roller Crusher Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Australia Forklift Market