
 Precision Gearbox Machinery Market | 2026-2036
Precision Gearbox Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Gearbox Machinery Market Analysis
Robotics end user demand is rebalancing the precision gearbox machinery landscape as collaborative and surgical automation systems multiply. Nabtesco Corporation dominates cycloidal precision reducers for industrial robot joints. SEW-Eurodrive leverages modular platform architectures to sustain position across material handling and conveying applications. Harmonic Drive LLC specializes in strain wave gearing for semiconductor and medical robotics, anchoring its niche against broader planetary competitors.
Precision gearbox machinery encompasses enclosed mechanical power transmission systems engineered to reduce input speed while multiplying torque output within tight backlash tolerances, typically below three arc-minutes for servo-grade units. These assemblies integrate hardened alloy steel gearing with synthetic lubrication and preloaded bearing arrangements to deliver positional repeatability for CNC axes, robotic articulation, and automated process lines. Planetary gearbox configurations capture the dominant share of new robotics and aerospace actuator demand due to coaxial input-output geometry and superior torque density. Worm gearbox designs retain entrenched positions in conveying systems and agricultural equipment where self-locking characteristics and cost efficiency outweigh efficiency losses. Helical variants occupy premium industrial machinery segments where noise reduction and load distribution justify higher manufacturing complexity.
EU machinery safety directives and CE marking requirements enforce functional safety ratings for integrated drive systems deployed across European automation lines. Japan's METI energy efficiency standards and JIS B 1452 gearbox performance specifications shape product development priorities for exporters targeting precision motion markets. China's GB standards and MIIT industrial upgrading mandates accelerate domestic substitution programs for high-precision reducers previously imported from German and Japanese suppliers. Stakeholders must evaluate certification roadmaps and local content thresholds before committing capacity expansion across these regulatory jurisdictions.
Market Dynamics
Robot joint articulation is absorbing the majority of precision gearbox R&D investment as collaborative automation penetrates surgical suites and logistics hubs. This demand concentration is compressing lead times for cycloidal and harmonic units while stretching capacity for specialized grinding equipment.
Growth Catalysts
- EU REACH and RoHS compliance tightening:Material specifications for lubricants and housings are forcing upgrades across European automation lines. German automotive OEMs are accelerating servo-grade gearbox replacement cycles.
- Semiconductor fabrication expansion:Strain wave gearing for wafer handling robots is pulling capacity from industrial robot suppliers. Taiwan and South Korea fab construction is concentrating orders.
- China MIIT industrial upgrading mandates:Domestic substitution programs for high-precision reducers are redirecting procurement toward local suppliers. GB standards alignment is prerequisite for state-funded automation grants.
Market Restraints
- Hardened alloy steel input volatility:Specialty steel pricing swings compress margin predictability for batch producers. Japanese and German mills control premium vacuum-remelted supply.
- Grinding equipment supply concentration:CNC gear grinding machine builders cluster in Switzerland and Germany. Equipment lead times now extend 18-24 months for sub-micron accuracy classes.
- Technical limitation in miniaturization:Torque density plateaus below 40mm outer diameter constrain surgical robot wrist designs. Alternative magnetic gearing remains uncompetitive on backlash.
Strategic Opportunities
- India PLI scheme for robotics components:Production-linked incentives for precision mechanical parts are attracting joint venture proposals. BIS certification harmonization is underway.
- Regenerative agriculture automation:Autonomous vineyard and orchard platforms require sealed planetary units with IP69K ratings. European wine regions are piloting deployments.
- Digital twin convergence with condition monitoring:Vibration signature analysis integrated with gearbox digital twins enables predictive maintenance contracts. Japanese METI funding supports demonstration projects.
Industry Challenges
- CNC gear grinding operator scarcity:Master crafts capable of sub-arc-minute setup are retiring faster than apprenticeships replenish. German and Swiss technical institutes are expanding programs.
- CE machinery safety directive certification timelines:Functional safety validation for integrated drive systems extends product launch schedules. Notified body capacity constraints add quarters to approval cycles.
- Legacy servo motor interface standardization:Proprietary encoder protocols fragment aftermarket retrofit opportunities. IEC 61800-7 compliance remains uneven across Japanese and European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Gearbox Machinery Market |
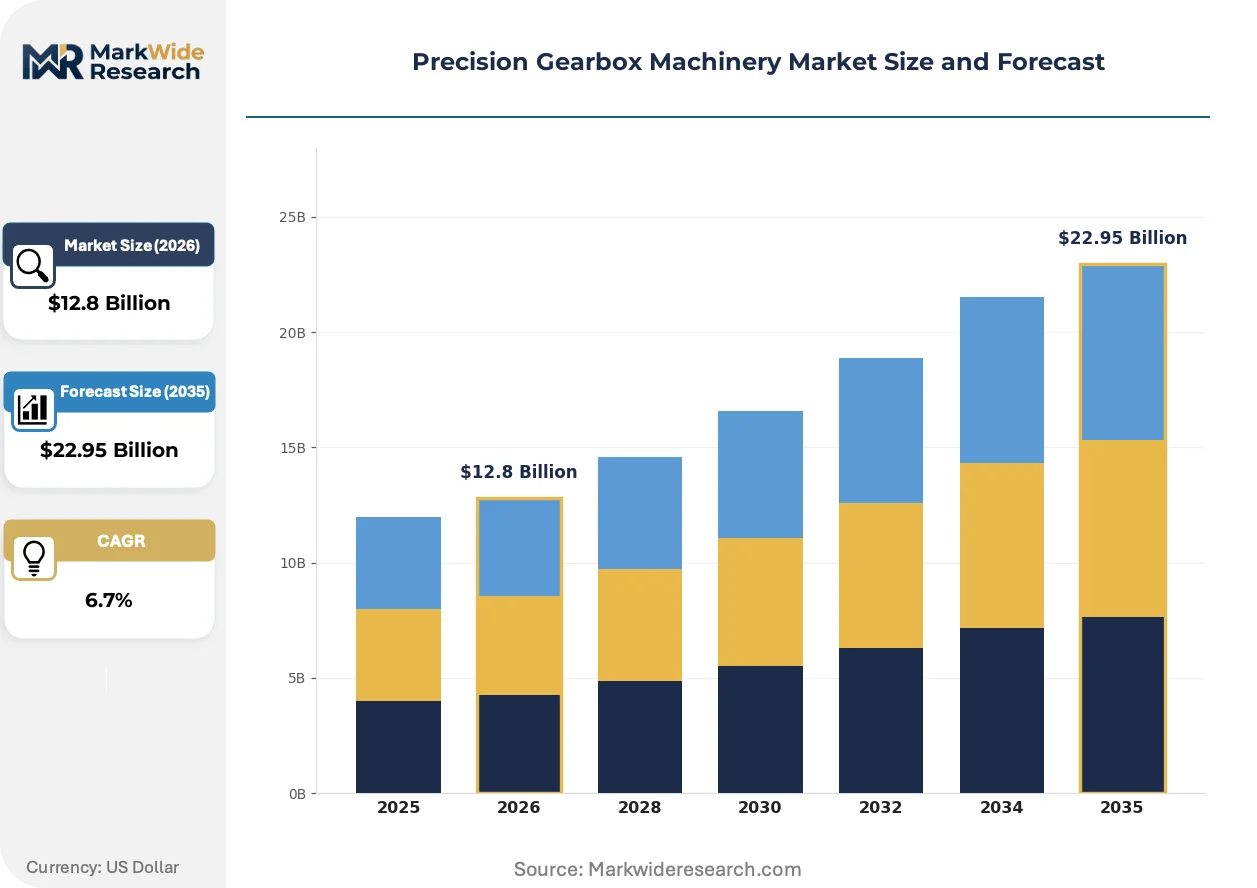
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical Gearbox, Planetary Gearbox, Worm Gearbox, Bevel Gearbox End User: Aerospace, Automotive, Robotics, Industrial Machinery Technology: Mechanical, Electrical, Hybrid, Pneumatic Application: Material Handling, Conveying Systems, Agricultural Equipment, Mining Equipment |
| Companies Covered | SEW-Eurodrive, Neugart GmbH, Nabtesco Corporation, Wittenstein SE, Harmonic Drive LLC, Bonfiglioli Riduttori S.p.A., Apex Dynamics, Inc., NIDEC-SHIMPO Corporation, Sumitomo Drive Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Gearbox Machinery Market Emerging Trajectories
Additive manufacturing of gear blanks is compressing prototyping cycles for custom ratios. This capability is reshaping how OEMs validate new joint configurations before committing to hard tooling.
Hybrid metal-polymer gear compounds are absorbing shock loads in collaborative robot applications previously requiring all-steel construction. Universal Robots and Fanuc integrators are specifying these compounds for force-limited joints. The technology is absorbing market share from conventional carburized steel in sub-50Nm duty cycles.
Japan's METI energy efficiency standards are mandating loss reduction in servo drive trains. Gearbox suppliers must document transmission efficiency across operating maps to maintain JIS B 1452 certification. Industrial robot builders targeting Japanese automotive OEMs are prioritizing efficiency-optimized planetary stages over legacy designs.
Certification-driven procurement is consolidating supplier lists around ISO 13849-compliant integrated drive systems. Automotive Tier-1 automation integrators are disqualifying non-certified vendors from RFQ participation. This pattern is most visible in German and Austrian packaging machinery buildouts where CE marking liability rests with the integrator.
Precision Gearbox Machinery Market Segmentation
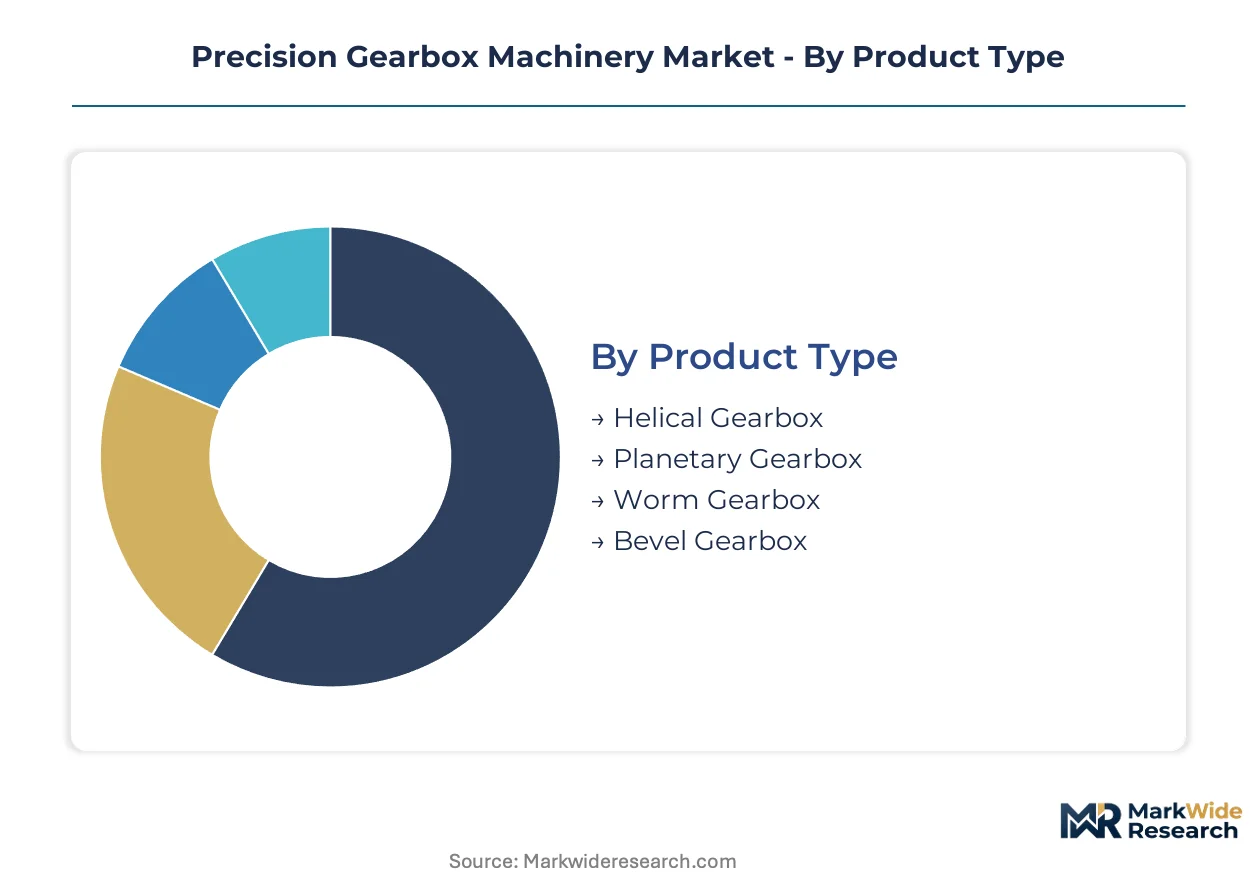
Precision gearbox procurement patterns diverge sharply across product architectures and end-use certifications. Segment boundaries determine which suppliers qualify for automotive safety ratings versus aerospace traceability requirements.
Product Type:
CE machinery safety directives and ISO 13849 functional safety ratings segment supplier eligibility across European automation lines, with JIS B 1452 certification gating access to Japanese robotics OEMs.
- Planetary Gearbox:Coaxial input-output geometry delivers superior torque density for servo-grade positioning. Robotics manufacturers in Germany and Japan concentrate orders here for collaborative robot joints, though sub-micron grinding equipment lead times now stretch 18-24 months.
- Helical Gearbox:Angled tooth engagement distributes load across multiple contact points for noise-sensitive industrial machinery. German automotive packaging lines specify these for CE-marked integrated drive systems where functional safety validation extends approval cycles.
- Worm Gearbox:Self-locking characteristics suit conveying systems and agricultural equipment where cost efficiency outweighs efficiency losses. REACH-compliant lubricant specifications are forcing material upgrades across European installations.
- Bevel Gearbox:Right-angle power transmission serves confined machinery layouts in mining equipment and material handling. Chinese MIIT industrial upgrading mandates now require GB standards alignment for state-funded automation grants.
Planetary configurations sit at the top of the volume ranking, with helical variants climbing the fastest on semiconductor fabrication and medical robotics demand.
End User:
Customer procurement authority concentrates with automotive Tier-1 integrators and semiconductor fab builders, each imposing distinct certification burdens on gearbox suppliers.
- Robotics:Strain wave and cycloidal precision reducers dominate industrial and surgical robot joints. Taiwan and South Korea fab construction is pulling capacity from industrial suppliers, while collaborative automation penetration accelerates servo-grade replacement cycles in German automotive OEMs.
- Automotive:Servo-grade gearboxes for powertrain and assembly automation require ISO 13849 PLd certification. German packaging machinery integrators now disqualify non-certified vendors from RFQ participation, consolidating supplier lists.
- Aerospace:Actuator systems demand full material traceability and vacuum-remelted alloy steel sourcing. Japanese and German mills control premium supply, compressing margin predictability for batch producers.
- Industrial Machinery:Broad application span from CNC axes to process lines accepts wider backlash tolerances. METI energy efficiency standards are mandating documented transmission efficiency across operating maps for Japanese market access.
Robotics commands the steepest expansion trajectory, with automotive maintaining the largest absolute procurement volume.
Technology:
Cost tier stratification separates premium electromechanical integration from pneumatic legacy systems, with hybrid architectures capturing mid-range automation budgets.
- Mechanical:Enclosed gear trains with hardened alloy steel and synthetic lubrication remain dominant for positional repeatability. Master grinder scarcity for sub-arc-minute setup is constraining output expansion.
- Electrical:Integrated servo motor-gearbox units with proprietary encoder protocols fragment aftermarket retrofit opportunities. IEC 61800-7 compliance remains uneven across Japanese and European suppliers.
- Hybrid:Metal-polymer gear compounds absorb shock loads in force-limited collaborative robot joints. Universal Robots integrators are specifying these for sub-50Nm duty cycles, displacing conventional carburized steel.
- Pneumatic:Compressed air actuation retains position in explosive-environment conveying where electrical spark risk is prohibitive. Lower precision requirements exclude these from servo-grade certification pathways.
Mechanical technology retains volume leadership, with hybrid systems gaining share fastest on collaborative robotics proliferation.
Application:
Geographic demand concentration varies by application, with European wine regions piloting autonomous vineyard platforms and East Asian fab construction driving wafer handling specifications.
- Material Handling:SEW-Eurodrive modular platforms sustain entrenched position across logistics hubs and distribution centers. CE marking liability rests with integrators in German and Austrian packaging machinery buildouts.
- Conveying Systems:Worm gearbox self-locking characteristics suit inclined transport applications. RoHS compliance tightening is forcing lubricant and housing material upgrades.
- Agricultural Equipment:Sealed planetary units with IP69K ratings serve autonomous vineyard and orchard platforms. European wine regions are piloting deployments under regenerative agriculture automation programs.
- Mining Equipment:Bevel gearbox right-angle configurations fit confined underground machinery layouts. Heavy shock loading tolerances prioritize durability over arc-minute precision.
Material Handling anchors procurement volume, with Agricultural Equipment expanding most quickly on autonomous platform pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting precision gearbox capacity toward jurisdictions where REACH compliance costs and MIIT localization mandates create divergent cost-of-compliance profiles. German and Japanese suppliers face margin compression from dual carbon and energy efficiency standards, while Chinese domestic substitution programs absorb capacity previously allocated for export.
Germany
Automotive Tier-1 integrators in Baden-Württemberg and Bavaria concentrate servo-grade gearbox procurement for powertrain automation. CE machinery safety directives and ISO 13849 PLd certification requirements extend product validation cycles, consolidating supplier lists around notified-body-approved vendors. Stuttgart's industrial cluster anchors precision grinding equipment demand, though master operator scarcity constrains output expansion.
China
MIIT industrial upgrading mandates and GB standards alignment prerequisites redirect state-funded automation grants toward domestic reducer suppliers. Yangtze River Delta fab construction in Shanghai and Suzhou pulls strain wave gearing capacity for wafer handling robots. Local substitution programs previously dependent on German and Japanese imports now favor certified domestic producers.
Japan
METI energy efficiency standards and JIS B 1452 certification requirements shape gearbox development priorities for industrial robot OEMs. Nagoya's automotive robotics corridor and Osaka's precision manufacturing belt concentrate cycloidal and harmonic reducer demand. Vacuum-remelted alloy steel sourcing from domestic mills secures material traceability for aerospace actuator applications.
United States
Semiconductor CHIPS Act fab construction in Arizona and Texas concentrates orders for cleanroom-compatible precision reducers. FDA regulatory pathways for surgical robotics impose material biocompatibility specifications distinct from industrial grades. Midwest logistics hubs specify SEW-Eurodrive modular platforms for distribution center automation.
South Korea
Memory and logic fab expansion in Pyeongtaek and Yongin drives strain wave gearing demand for vacuum wafer handling systems. MFDS medical device regulations intersect with industrial robot safety standards for surgical automation applications. Busan's machinery manufacturing base supplies precision components for export-oriented automation integrators.
Precision Gearbox Machinery Market Vendor Landscape
Certification-driven consolidation dominates the current landscape as automotive Tier-1 integrators disqualify non-ISO 13849-compliant vendors from RFQ participation. The supplier base stratifies into three tiers: premium integrated drive systems, mid-range modular platforms, and cost-optimized standard units. Strategic archetypes include European precision specialists with CE marking authority, Japanese cycloidal and harmonic gearing experts, and Chinese domestic champions capturing state-funded substitution demand. Competitive moves center on M&A for grinding equipment capacity and strategic partnerships for semiconductor fab qualification.
Among European precision specialists, SEW-Eurodrive GmbH & Co. KG and Neugart GmbH exemplify the modular platform archetype serving material handling and logistics automation. Wittenstein SE occupies a position within the premium integrated drive tier, while Nabtesco Corporation anchors the cycloidal precision reducer segment for industrial robot joints. Harmonic Drive LLC represents the strain wave gearing specialization serving semiconductor and medical robotics applications. These named entities illustrate how geographic origin and corporate structure suffixes map to distinct competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| SEW-Eurodrive |
| Neugart GmbH |
| Nabtesco Corporation |
| Wittenstein SE |
| Harmonic Drive LLC |
| Bonfiglioli Riduttori S.p.A. |
| Apex Dynamics, Inc. |
| NIDEC-SHIMPO Corporation |
| Sumitomo Drive Technologies |
| Others |
Supply Flow & Price Mechanics
Automotive Tier-1 integrators in Germany and Japan concentrate procurement authority for servo-grade gearboxes, anchoring a contract-based long-term offtake pricing model where ISO 13849 PLd certification tiers separate premium integrated drive systems from standard modular units. This buyer concentration compresses margin predictability for batch producers facing hardened alloy steel input volatility from Japanese and German vacuum-remelted mills.
Pricing Analysis
Distributor margins for precision gearbox machinery typically range 15-25 percent above direct OEM contracts, with three-tier pricing structure across premium, standard, and economy levels differentiated by arc-minute precision grade and JIS B 1452 or CE marking certification status. Cost compression in the standard tier intensifies as Chinese domestic substitution programs redirect state-funded automation grants toward local suppliers. Semiconductor fab builders exhibit the least price sensitivity due to strain wave gearing capacity constraints, while agricultural equipment OEMs prioritize cost efficiency over arc-minute specifications.
Supply Chain Analysis
China's MIIT industrial upgrading mandates and GB standards alignment prerequisites are reshaping sourcing patterns, with Yangtze River Delta fab construction pulling capacity previously allocated for German and Japanese export markets. Precision gearbox production draws from vacuum-remelted alloy steel mills in Japan and Germany, CNC gear grinding equipment concentrated in Switzerland, and synthetic lubricant formulations subject to EU REACH compliance. Single-source vulnerability around sub-micron grinding machine builders extends equipment lead times and constrains output expansion. Distribution runs through authorized distributor networks for aftermarket service, with direct OEM relationships dominating high-volume robotics and automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe and MIIT localization mandates in China create divergent cost-of-compliance profiles, rewarding suppliers with dual-certification capabilities across CE marking and GB standards pathways.
For Market Incumbents: Anticipate margin compression from Chinese domestic substitution programs by securing JIS B 1452 certification for Japanese automotive robotics corridors and accelerating backward integration into vacuum-remelted alloy steel sourcing. Certification investment represents the critical lever for maintaining RFQ participation as automotive Tier-1 integrators consolidate supplier lists around ISO 13849 PLd compliance. For New Entrants and Emerging Players: Semiconductor fab channel partners offer the most penetrable entry vector given strain wave gearing capacity constraints pulling orders from industrial robot suppliers. Target white-space opportunities in regenerative agriculture automation for sealed planetary units with IP69K ratings, leveraging BIS certification harmonization under India's PLI scheme for robotics components as the go-to-market angle. For Investors and Strategic Acquirers: Industrial robot OEMs are the most active acquirer in this space, pursuing grinding equipment capacity and semiconductor fab qualification partnerships. Long-term viability over the next decade hinges on digital twin convergence with condition monitoring capabilities. Watch for METI demonstration project funding announcements as the inflection indicator for predictive maintenance contract adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Grinding Equipment Capacity Expansion | Sub-micron CNC gear grinder acquisition from Swiss and German builders reduces lead time exposure. |
| Dual Certification Investment | Simultaneous CE marking and GB standards alignment unlocks European and Chinese automotive RFQ participation. |
| Backward Integration into Alloy Steel | Captive vacuum-remelted supply from Japanese or German mills secures material traceability for aerospace actuators. |
| Digital Twin Platform Development | Vibration signature analysis integration with gearbox digital twins enables predictive maintenance contracts under METI funding. |
| Semiconductor Fab Qualification Partnership | Strain wave gearing validation for Taiwan and South Korea wafer handling robots captures fab construction demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with robotics OEM procurement teams, precision gearbox plant engineers, CNC grinding equipment operators, and aftermarket service heads with secondary validation from customs trade data, JIS B 1452 certification registries, MIIT industrial upgrading grant disclosures, and SEC filings from listed automation suppliers. Bottom-up demand modeling across end-use segments triangulated against top-down macroeconomic indicators for industrial capital expenditure.
Segment-weighting approaches distributed precision gearbox demand across planetary, helical, worm, and bevel architectures, with further disaggregation by robotics, automotive, aerospace, and industrial machinery end uses across the projection horizon. CAGRs were derived from historical shipment patterns and forward-looking capacity expansion announcements, with semiconductor fabrication buildout timelines and automotive electrification capex cycles serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hardened alloy steel pricing volatility, grinding equipment delivery delays, and regulatory shifts in REACH compliance or MIIT localization mandates. Forecasts reflect documented assumptions regarding certification timeline stability and master grinder workforce replenishment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Hydraulic Hose Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Rolling Mill Machine Market