
 Heavy Duty Telehandler Market | 2026-2036
Heavy Duty Telehandler Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Telehandler Market Outlook
High-lift-capacity specification tiers above 12,000 pounds is collapsing the gap between traditional rough-terrain forklifts and small cranes, forcing manufacturers to redesign booms and chassis for stability at extended reaches. JCB sustains engineering leadership through its Loadall platform with proprietary boom profiles. Manitou BF S.A. dominates European distribution through owned dealer networks and rental fleet partnerships. XCMG anchors Asia-Pacific supply with vertically integrated hydraulic component production.
A heavy duty telehandler is a self-propelled, articulated boom-mounted lifting machine with rated capacities from 12,000 to 30,000 pounds and lift heights exceeding 40 feet, engineered with hydrostatic or powershift transmissions for variable terrain traction. Its primary purpose is material placement and load management across uneven ground where conventional forklifts lack reach or stability. Rough terrain configurations lead unit volumes in construction applications, while electric drive systems represent the fastest-growing technology segment as job sites impose emissions restrictions. Equipment rental services command the largest end-user margin pool due to fleet turnover cycles and utilization-based revenue models.
EPA Tier 4 Final and EU Stage V emissions frameworks compel engine suppliers to integrate selective catalytic reduction and diesel particulate filters, adding cost and service complexity to diesel product lines. OSHA crane certification rules in the United States and CE machinery directives in Europe shape operator training requirements and machine guarding standards. China MIIT enforces GB national standards on construction machinery safety that affect export eligibility for non-domestic producers. Stakeholders must monitor how battery-electric range limitations interact with duty-cycle intensity in mining and industrial applications as charging infrastructure deployment lags machine development timelines.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions mandates are forcing diesel engine architecture redesigns while battery-electric platforms struggle with duty-cycle intensity in high-lift applications.
Growth Catalysts
- Mega-construction programs:Infrastructure spending in the United States, Germany, and China generates concentrated demand for 12,000+ pound lift capacity machines.
- Rental fleet expansion:Equipment rental services are scaling fleet investments across North American job sites, creating utilization-based revenue pools.
- Stage V compliance:The European Union's emissions framework accelerates replacement cycles as older diesel units face operational restrictions in urban zones.
Market Restraints
- Battery energy density limitations:Lithium-ion cell chemistry constrains electric telehandler runtime during continuous heavy-lift cycles.
- Aftertreatment cost inflation:Selective catalytic reduction and diesel particulate filter integration adds service complexity to Tier 4 Final product lines.
- Hydraulic component concentration:Vertically integrated Asian suppliers control critical boom cylinder and valve manufacturing capacity.
Strategic Opportunities
- Electrification incentives:The US Inflation Reduction Act and EU Green Deal subsidies offset battery-electric platform development costs.
- Precision agriculture mechanization:Brazilian and Australian farm operations present underpenetrated demand for high-reach material handlers.
- Telematics-integrated rental models:IoT-enabled fleet management allows outcome-based pricing tied to actual lift cycles rather than calendar time.
Industry Challenges
- OSHA crane certification gaps:Operator licensing requirements for high-capacity telehandlers vary by state, creating workforce deployment friction.
- Charging infrastructure timing:Mining and industrial site electrification lags machine development, stranding early electric adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Telehandler Market |
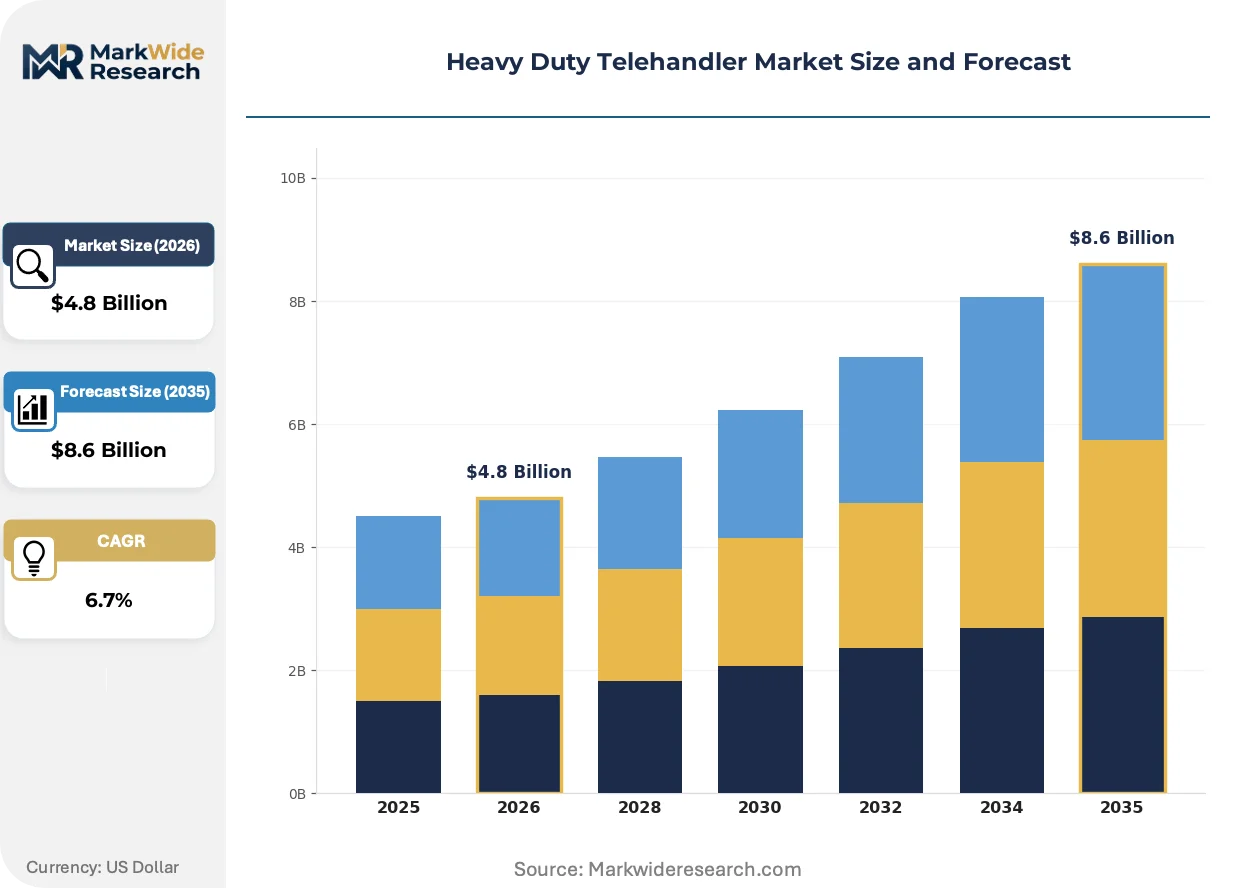
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rough Terrain, Electric, Diesel, LPG Application: Construction, Agriculture, Industrial, Mining End User: Contractors, Farmers, Logistics Providers, Equipment Rental Services Technology: Telematics, Hydraulic Systems, Drive Systems, Automated Control |
| Companies Covered | Terex Corporation, Merlo S.p.A., J.C. Bamford Excavators Limited (JCB), Dieci S.r.l., Liebherr-International AG, Manitou BF S.A., CNH Industrial N.V., Xuzhou Construction Machinery Group Co., Ltd. (XCMG), Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Telehandler Market Strategic Shifts
Electrification architectures, emissions compliance systems, and data-enabled service models are compressing product development timelines while expanding functional boundaries between material handlers and lifting equipment.
High-voltage battery packs paired with permanent magnet motors are miniaturizing powertrain footprints without sacrificing torque output. Mining contractors and port operators are piloting these configurations for indoor and emissions-restricted zones. The technology is miniaturizing engine bay requirements, allowing manufacturers to redistribute mass toward counterweight and boom stability.
EU Stage V and EPA Tier 4 Final frameworks are forcing selective catalytic reduction and diesel particulate filter integration into compact engine envelopes. These aftertreatment systems add thermal management complexity and service interval density. Rough-terrain construction units face the steepest compliance cost inflation, pushing fleet operators toward rental models that externalize obsolescence risk.
Equipment-as-a-service contracting is displacing traditional capital purchase and finance lease structures. Rental fleet operators and large general contractors are consolidating procurement through national framework agreements with telemetry-backed utilization guarantees. This shift is most advanced in the United States, where equipment rental penetration exceeds ownership rates in commercial construction.
Heavy Duty Telehandler Market Segmentation
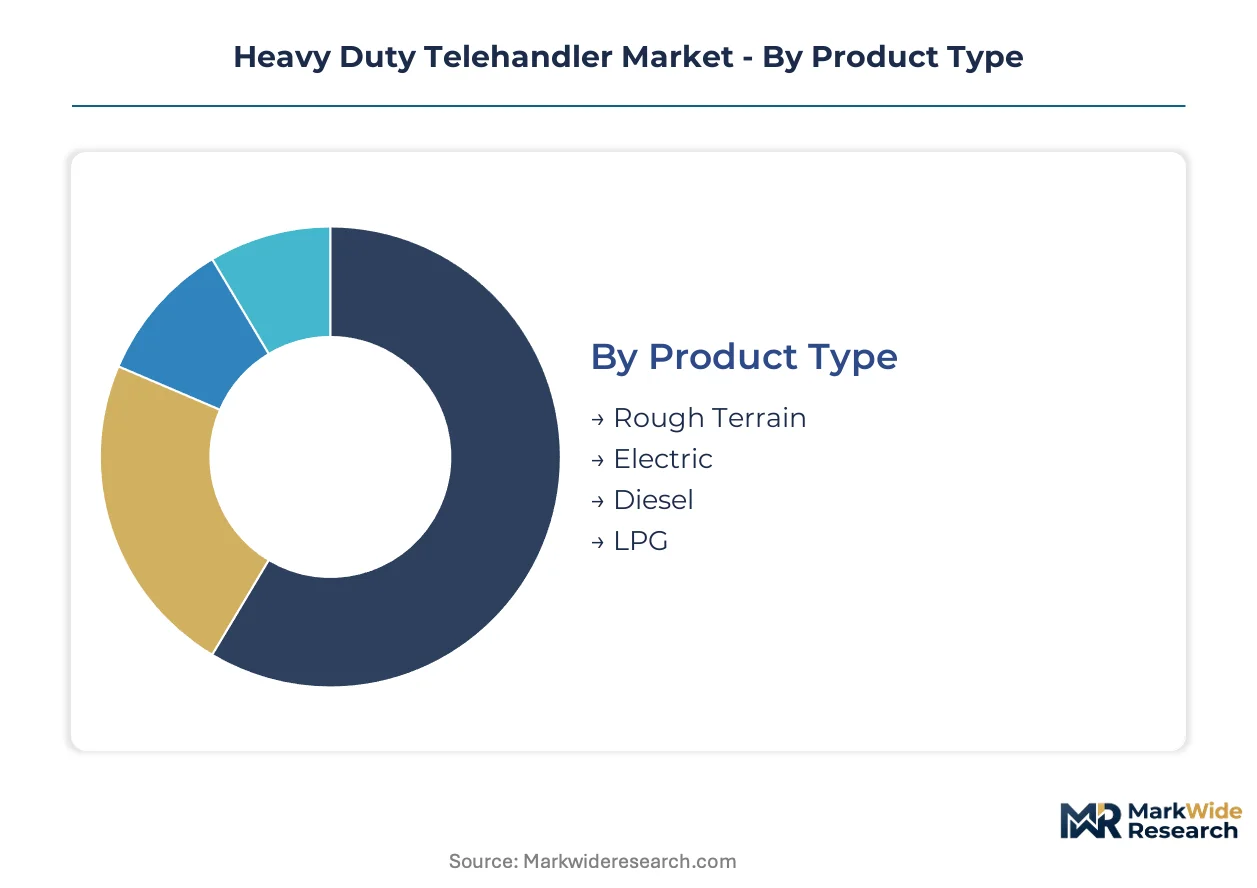
Segmentation in heavy duty telehandlers reveals how duty-cycle intensity, terrain demands, and ownership economics fragment procurement patterns. Equipment rental services concentrate fleet purchasing power while emissions regulations split technology adoption curves across geographies.
Product Type:
Domestic production dominates rough terrain and diesel variants in North America and Europe, while electric platforms draw cross-border technology sourcing from Asian battery suppliers.
- Rough Terrain:Articulated chassis with hydrostatic transmissions and all-wheel drive handle gradients exceeding 25 degrees on unpaved construction sites. Demand clusters with general contractors in the United States and Germany where OSHA and CE machinery directives mandate stability certification for high-reach operations.
- Electric:High-voltage lithium-ion packs paired with permanent magnet motors eliminate exhaust emissions for indoor industrial and port applications. Adoption concentrates in California, Netherlands, and Chinese mega-cities where municipal bans on diesel equipment in urban zones force fleet electrification timelines ahead of charging infrastructure readiness.
- Diesel:Compression-ignition engines with integrated selective catalytic reduction and diesel particulate filters remain the default for mining and remote agricultural operations lacking grid access.
- LPG:Propane-fueled spark-ignition variants serve indoor warehouse and food processing facilities where diesel particulate emissions face facility-level prohibitions.
Rough terrain configurations command the established base. The steepest expansion runs through electric platforms.
Application:
Cost tier stratification separates capital-intensive mining deployments from utilization-sensitive rental construction fleets.
- Construction:Material placement on commercial and infrastructure job sites drives the highest unit volumes, with general contractors prioritizing 12,000-20,000 pound lift capacity machines for steel erection and prefabricated panel installation. United States infrastructure spending and German residential construction programs concentrate demand.
- Agriculture:Brazilian grain handling and Australian livestock operations present underpenetrated demand for high-reach bale stacking and feed placement. Farm ownership economics favor purchase over rental, compressing margin structures versus construction applications.
- Industrial:Manufacturing facilities and port terminals utilize compact electric variants for container stuffing and warehouse vertical storage.
- Mining:Underground and surface extraction operations specify explosion-proof diesel configurations with reinforced booms for abrasive material handling.
Construction applications anchor volume leadership. Agriculture presents the steepest untapped trajectory for high-capacity mechanization.
End User:
Customer type determines procurement modality, with rental services consolidating national framework agreements while farmers and contractors fragment across regional dealers.
- Equipment Rental Services:National and regional fleet operators in the United States command the largest margin pool through utilization-based revenue models and telemetry-backed maintenance contracts. Their procurement power forces manufacturers into equipment-as-a-service pricing structures.
- Contractors:Commercial construction general contractors balance capital purchase against seasonal rental based on backlog visibility and tax depreciation schedules.
- Farmers:Owner-operators in Brazil, Australia, and the United States Midwest prioritize total cost of ownership and dealer service proximity over technology sophistication.
- Logistics Providers:Third-party warehousing and port terminal operators specify electric variants for indoor duty cycles with standardized maintenance protocols.
Equipment rental services concentrate purchasing leverage. Contractors show the steepest sensitivity to financing cost fluctuations.
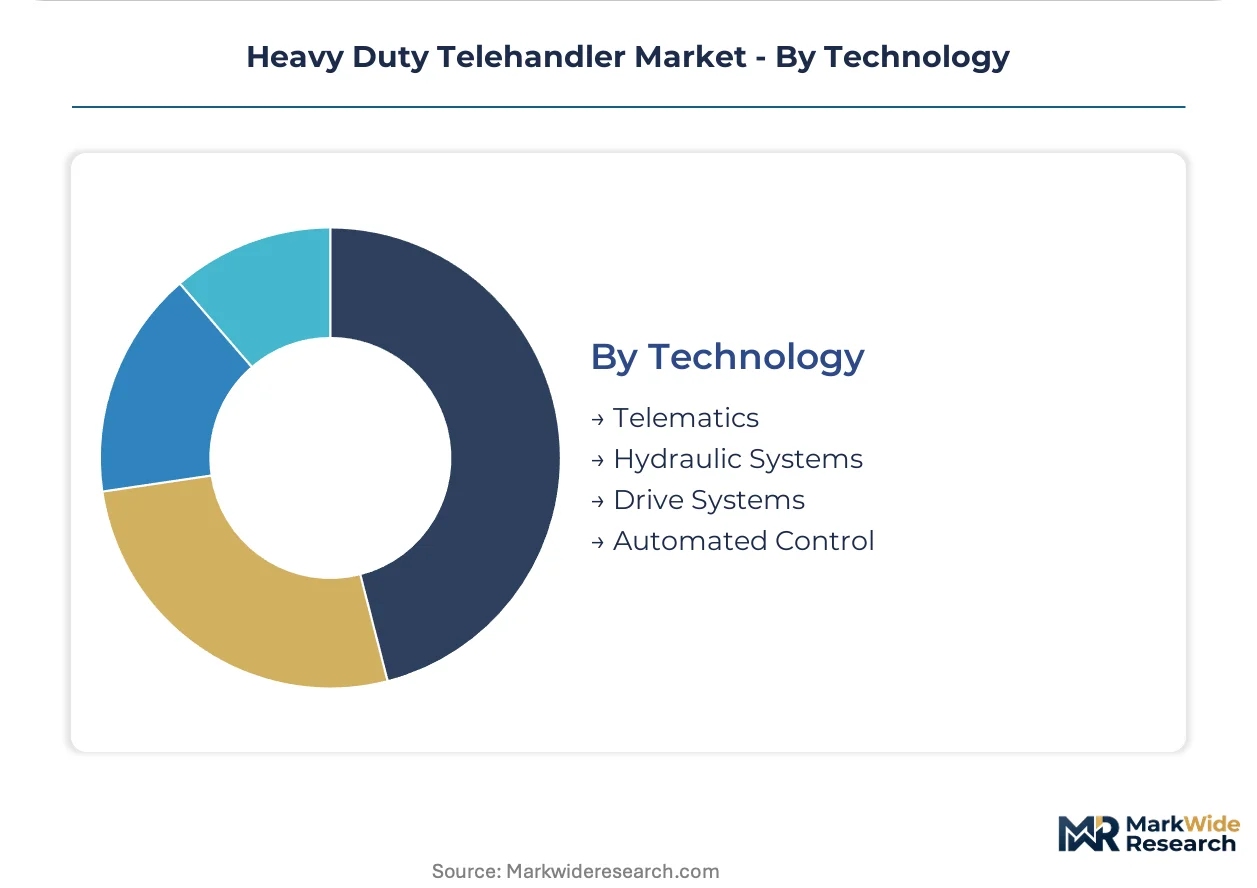
Technology:
Supply concentration in hydraulic component manufacturing shapes competitive access to boom cylinder and valve systems.
- Hydraulic Systems:Load-sensing proportional valves and telescoping boom cylinders determine lift precision and stability at extended reach. Vertically integrated Asian suppliers control critical casting and machining capacity.
- Telematics:IoT-enabled fleet management platforms allow rental operators to monitor utilization, geofence job sites, and predict maintenance intervals based on actual lift cycle counts.
- Drive Systems:Hydrostatic transmissions dominate rough terrain applications while electric permanent magnet motors displace mechanical drivelines in indoor configurations.
- Automated Control:Load moment indicators and stability limiters integrate with boom angle sensors to prevent tip-over incidents under variable ground conditions.
Hydraulic systems anchor the technology stack. Telematics integration is climbing the fastest as rental models displace ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine and hydraulic component manufacturing clusters in Germany, the United States, and China shape competitive access to high-capacity telehandler supply. Fleet procurement concentrates where infrastructure spending and emissions regulations accelerate replacement cycles.
United States
Infrastructure Investment and Jobs Act spending drives demand for 12,000-20,000 pound lift capacity machines on commercial job sites. OSHA crane certification rules create state-level operator licensing friction for high-reach equipment. Texas and Florida construction corridors concentrate rental fleet deployment for prefabricated building erection.
Germany
Residential construction programs and industrial facility modernization sustain rough terrain telehandler volumes. EU Stage V emissions frameworks accelerate diesel unit replacement in urban zones. Bavaria and Baden-Württemberg anchor manufacturing clusters for boom cylinder and valve systems.
China
Mega-construction and agricultural mechanization programs generate concentrated demand for high-lift-capacity handlers. MIIT enforces GB national standards on construction machinery safety affecting export eligibility. Yangtze River Delta and Pearl River Delta regions dominate vertically integrated hydraulic component production.
Brazil
Grain handling and livestock operations present underpenetrated demand for high-reach bale stacking equipment. ANVISA regulates workplace safety equipment standards affecting operator protection systems. São Paulo and Minas Gerais states concentrate agribusiness procurement for mechanized feed placement.
Australia
Mining and remote agricultural operations specify explosion-proof diesel configurations for abrasive material handling. The country's national machinery safety regulator mandates stability certification for high-reach operations. Western Australia and Queensland mining belts drive specialized heavy-lift equipment specification.
Heavy Duty Telehandler Market Competitive Environment
Concentration sits with diversified industrial equipment manufacturers holding captive distribution networks and rental fleet partnerships. The vendor base spans three tiers: premium engineering specialists with proprietary boom architectures, scale-driven broad-liners with construction equipment portfolios, and regional fabricators serving price-sensitive agricultural markets. Dominant competitive moves include equipment-as-a-service contracting structures and telematics-integrated fleet management platforms that displace traditional capital purchase models.
Among European-based engineering specialists, Manitou BF S.A. and Liebherr-International AG exemplify the premium-tier archetype through owned dealer networks and vertically controlled service infrastructure. J.C. Bamford Excavators Limited (JCB) anchors British engineering leadership with its Loadall platform lineage. Xuzhou Construction Machinery Group Co., Ltd. (XCMG) represents the Asia-Pacific supply anchor through integrated hydraulic component manufacturing. Terex Corporation and Caterpillar Inc. occupy positions within the North American scale-driven tier, leveraging construction equipment distribution density for fleet procurement access.
| Leading Market Players |
|---|
| Terex Corporation |
| Merlo S.p.A. |
| J.C. Bamford Excavators Limited (JCB) |
| Dieci S.r.l. |
| Liebherr-International AG |
| Manitou BF S.A. |
| CNH Industrial N.V. |
| Xuzhou Construction Machinery Group Co., Ltd. (XCMG) |
| Caterpillar Inc. |
| Others |
Value Chain & Pricing Dynamics
High-voltage battery pack substitution for diesel powertrains is redistributing component sourcing from German and U.S. engine foundries toward Chinese and South Korean cell manufacturers, compressing margins on legacy diesel architectures while inflating upfront capital requirements for electric platforms. This input transition simultaneously fragments supplier power across geographies and forces fleet operators into longer payback calculations.
Pricing Analysis
EPA Tier 4 Final and EU Stage V dictate the pricing tier structure across diesel product lines, with aftertreatment integration separating premium compliant units from non-certified residual inventory. Three-tier pricing structure across premium, standard, and economy levels tracks lift capacity, emissions certification grade, and telematics bundling. Cost compression in rough-terrain diesel configurations is intensifying because rental fleet operators consolidate procurement through national framework agreements. Equipment rental services show the steepest price sensitivity due to utilization-based revenue models, while mining contractors demonstrate lowest sensitivity given explosion-proof specification requirements.
Supply Chain Analysis
Inventory lead times for telescoping boom cylinders and load-sensing valves have extended as vertically integrated Chinese suppliers throttle export capacity. Component manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta foundries controlling critical hydraulic casting capacity. Supply chains draw from lithium-ion cell producers, high-strength steel mills, and permanent magnet rare earth processors. Single-source vulnerability in hydraulic valve systems poses structural risk as Asian suppliers prioritize domestic OEM allocation. Distribution runs through manufacturer-owned dealer networks and rental fleet direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where telemetry-enabled maintenance contracts and utilization-based fleet management expand faster than hardware unit sales, rewarding manufacturers who embed recurring revenue into equipment-as-a-service structures.
For Market Incumbents: Secure captive distribution through exclusive rental fleet partnerships before electric platform commoditization erodes brand differentiation. Backward integration into hydraulic component machining insulates against Asian supplier allocation restrictions. Invest in telematics R&D to defend against software-enabled entrants offering predictive maintenance overlays. For New Entrants and Emerging Players: Aftermarket parts availability gaps in Brazilian and Australian agricultural markets present white-space entry points where incumbent service networks remain sparse. Target precision agriculture mechanization programs with simplified maintenance protocols and dealer-proximity guarantees. Pursue joint venture structures with regional hydraulic fabricators to bypass vertical integration barriers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component specialists with electric powertrain integration capabilities. Five-to-ten year viability hinges on battery energy density improvements and charging infrastructure deployment pace. Acquisition targets should demonstrate captive hydraulic valve production or permanent magnet motor assembly competence. Monitor EU Green Deal subsidy disbursement velocity as inflection indicator for electric fleet replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Telemetry-backed utilization guarantees displace capital purchase models for U.S. rental fleets. |
| Backward Integration into Hydraulics | In-house boom cylinder production reduces exposure to Chinese supplier allocation restrictions. |
| Electric Platform Certification | CE machinery directive pre-approval accelerates EU urban zone deployment timelines. |
| Telematics-Integrated Fleet Management | IoT-enabled predictive maintenance contracts capture recurring revenue from rental operators. |
| Regional Manufacturing Footprint | Texas and Florida assembly hubs reduce logistics costs for North American infrastructure projects. |
Study Parameters
Cross-validation between OEM procurement director interviews and rental fleet operator surveys anchors the qualitative findings on utilization-based revenue models and electrification adoption timelines. Primary fieldwork encompassed maintenance directors at mining contractors, plant engineers at port terminals, aftermarket service heads at dealer networks, and OEM procurement teams at construction equipment manufacturers. Secondary validation drew from OSHA crane certification filings, EPA Tier 4 Final compliance databases, EU Stage V type-approval records, and customs trade data on hydraulic component flows. Bottom-up unit demand modeling triangulated against top-down infrastructure spending projections.
Sensitivity analysis across battery cost decline curves and diesel aftertreatment reliability assumptions stress-tested volume and value outputs over the projection horizon. Segmentation dimensions modeled include product type (rough terrain, electric, diesel, LPG), application (construction, agriculture, industrial, mining), end user (equipment rental services, contractors, farmers, logistics providers), and technology tier (hydraulic systems, telematics, drive systems, automated control). CAGRs derived from regression analysis against macroeconomic indicators and replacement cycle dynamics. Industry-specific forecast inputs incorporated infrastructure appropriations tracking and emissions regulatory phase-in schedules.
Forecasts assume regulatory continuity in EPA Tier 4 Final, EU Stage V, and China MIIT GB standards; material policy shifts would require re-modeling. Assumptions reflect stable lithium-ion supply chain expansion and charging infrastructure deployment pace. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
US Forklift Market