
 Pipe Clamp Market | 2026-2036
Pipe Clamp Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Clamp Market Analytics
Asset-light leasing models for industrial fastening inventories is reconfiguring competitive entry barriers across the pipe clamp supply chain. Norma Group leverages captive polymer compounding capacity to sustain margin control on cushion clamp variants. Parker Hannifin Corporation anchors its position through integrated distribution across fluid power channels. STAUFF specializes in DIN-standard metric formats that dominate European machinery OEM specifications.
A pipe clamp is a mechanical fastening device designed to secure cylindrical conduits to structural surfaces, typically manufactured from stamped metal bands or injection-molded housings with torque-rated fastening hardware. The device maintains positional stability under vibration, thermal expansion, and pressure pulsation across fluid transport systems. Stainless steel U-clamps command premium positioning in offshore and chemical processing environments where chloride exposure degrades carbon steel alternatives. Plastic and rubber cushion clamps are gaining fastest in HVAC and pneumatic applications where electrical isolation and acoustic damping outweigh mechanical load requirements. Rigid clamp formats remain mature in commercial plumbing, with margin pools concentrating in specification-grade products carrying third-party fire resistance certification.
ISO 9001 quality management and REACH chemical compliance frameworks govern material eligibility and traceability for clamps entering European industrial supply chains. The EPA's lead-free plumbing requirements under the Safe Drinking Water Act constrain alloy composition for potable water applications in the United States. China's GB standards for mechanical fasteners impose dimensional and load-testing protocols that differentiate export-grade from domestic-market production. Stakeholders must monitor evolving material disclosure mandates and certification reciprocity agreements between major import jurisdictions.
Market Dynamics
Water infrastructure renewal cycles across municipal utilities are accelerating specification-grade procurement for corrosion-resistant fastening systems, while EU F-Gas Regulation compliance redirects HVAC contractor specifications toward low-leakage clamp geometries.
Growth Catalysts
- EU F-Gas Regulation:HVAC contractors across Germany, France, and Italy are specifying low-leakage clamp designs for refrigerant line installations to minimize fugitive emissions and avoid penalty structures.
- Stainless steel substitution:Offshore platform operators and chemical processors are replacing carbon steel U-clamps with 316L stainless variants to withstand chloride-rich process environments and extend replacement intervals.
- Polymer compounding advances:Cushion clamp manufacturers are integrating acoustic-damping elastomers that meet DIN 4109 sound insulation standards for European machinery OEM specifications.
Market Restraints
- Nickel price volatility:Austenitic stainless steel grades depend on nickel content, and LME nickel contract swings compress margin predictability for clamp fabricators serving price-sensitive commercial plumbing segments.
- Chinese domestic capacity concentration:Mid-volume carbon steel clamp production clusters in Zhejiang and Jiangsu provinces, creating single-source vulnerability for distributors without dual-qualified supply bases.
- Lead-free alloy constraints:EPA Safe Drinking Water Act requirements restrict brass alloy compositions for potable water applications, forcing reformulation of traditional silicon bronze fastening hardware.
Strategic Opportunities
- India infrastructure buildout:National highway and metro rail expansion is generating specification demand for vibration-rated clamp assemblies in bridge-mounted utility corridors and tunnel ventilation systems.
- Digital twin integration:BIM-compliant clamp libraries with embedded torque specifications and material traceability are enabling MEP contractors to pre-validate installation sequences before site mobilization.
- Asset-light leasing models:Industrial fastening inventory pools managed by third-party logistics providers are reducing working capital requirements for maintenance contractors serving intermittent turnaround schedules.
Industry Challenges
- Weld qualification bottlenecks:Offshore fabricators require clamp attachment welds certified to ASME Section IX or EN ISO 9606, and qualified welder availability constrains project mobilization timelines.
- REACH substance disclosure complexity:European OEMs are demanding full material composition data for rubber cushion elements, forcing compounders to requalify formulations against SVHC candidate list updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Clamp Market |
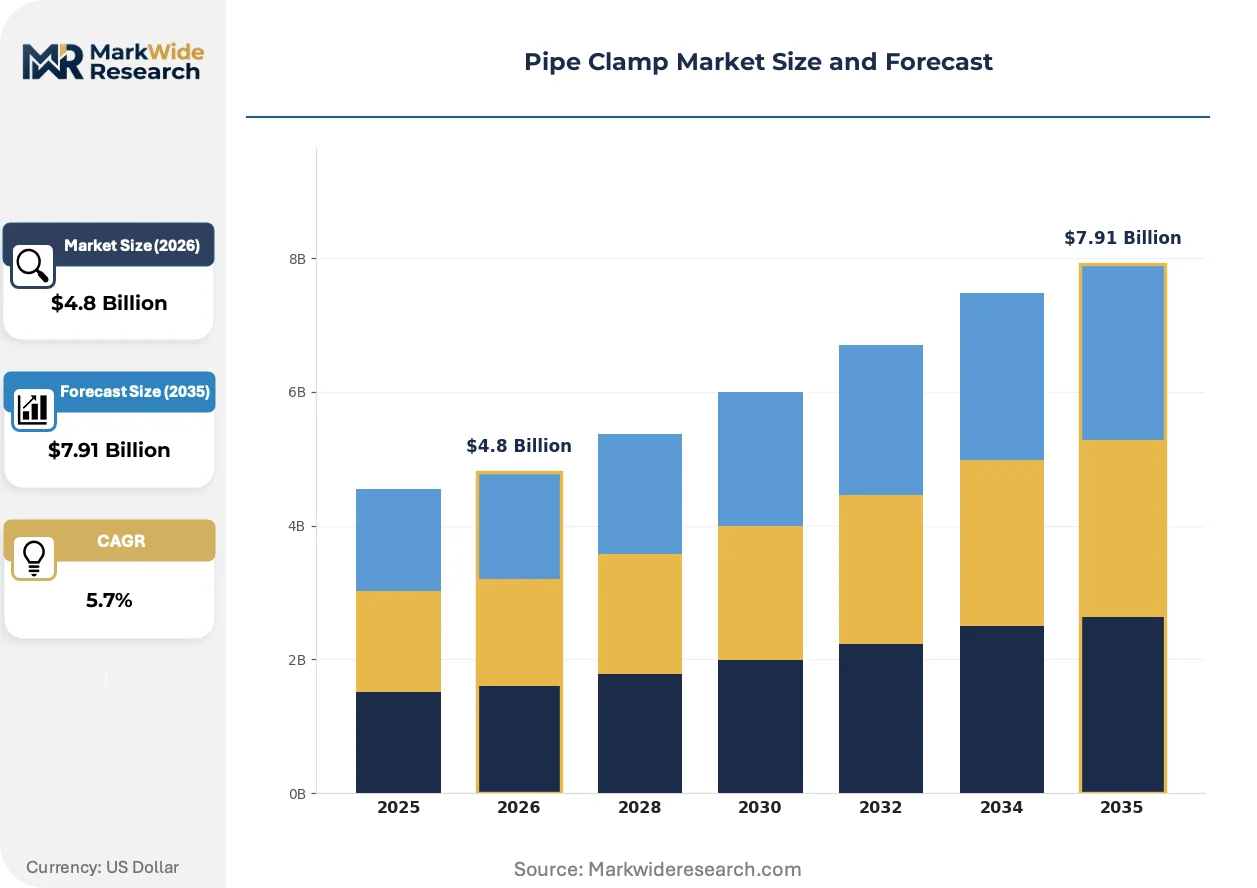
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: U-Clamps, Adjustable Clamps, Rigid Clamps, Cushion Clamps Material: Stainless Steel, Carbon Steel, Plastic, Rubber Application: Pneumatic Systems, HVAC Systems, Plumbing, Construction End User: Manufacturers, Contractors, Maintenance Providers, Installers |
| Companies Covered | Norma Group, Panduit Corporation, Parker Hannifin Corporation, Oetiker Group, STAUFF, Walraven Group, BPC Engineering, Piping Technology & Products, Rilco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Clamp Market Evolving Landscape
Specification-grade fastening systems are converging with digital traceability requirements and material science advances, compressing traditional procurement cycles while elevating compliance documentation burdens.
Additive manufacturing of titanium clamp prototypes is virtualizing traditional tool-and-die development timelines for custom offshore geometries. Norwegian subsea contractors are qualifying electron-beam melted Ti-6Al-4V brackets for deep-water manifold installations. This process is virtualizing the six-month mold fabrication sequence into two-week digital iterations, collapsing supplier qualification cycles.
REACH chemical compliance frameworks are mandating SCIP database registration for clamp articles containing candidate list substances above threshold concentrations. European machinery OEMs are now rejecting suppliers without digitized material passports traceable to polymer compounding batches. Stainless steel cushion clamp variants with silicone-free elastomers are capturing specification share in food-contact and pharmaceutical cleanroom environments.
Consolidated MEP procurement desks at major infrastructure contractors are unbundling clamp supply from full mechanical package awards, creating direct specification relationships with specialized fastening manufacturers. Tier-one contractors in Germany and the Netherlands are maintaining approved manufacturer lists with locked torque specifications and pre-negotiated volume tiers. This disintermediation compresses distributor margins while rewarding clamp producers with captive polymer compounding and in-house load-testing capabilities.
Pipe Clamp Market Segmentation
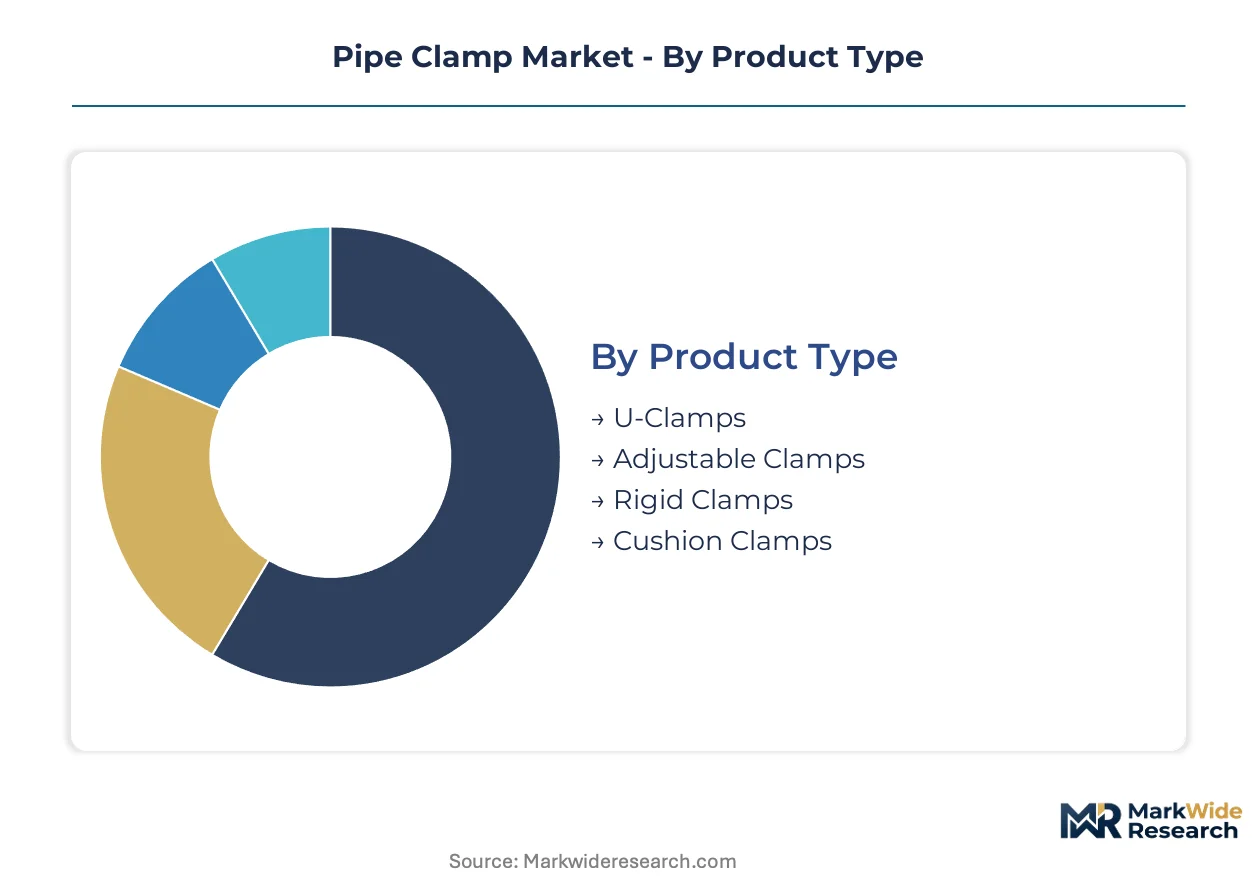
Pipe clamp procurement patterns diverge sharply across material grades, installation environments, and buyer sophistication levels. Specification-grade stainless steel variants command premium positioning in chemical processing and offshore applications, while standardized carbon steel formats dominate high-volume municipal infrastructure awards.
Product Type:
Mature formats dominate specification-grade procurement, though emerging geometries are capturing share in refrigerant containment and vibration-isolation applications.
- U-Clamps:Manufactured from stamped metal bands with torque-rated fastening hardware, these devices secure cylindrical conduits to structural surfaces under vibration and thermal expansion. Offshore platform operators in the North Sea specify 316L stainless variants to withstand chloride-rich process environments and extend replacement intervals.
- Cushion Clamps:Injection-molded housings integrate acoustic-damping elastomers that meet DIN 4109 sound insulation standards for European machinery OEM specifications. HVAC contractors across Germany, France, and Italy are specifying these designs for refrigerant line installations to minimize fugitive emissions under EU F-Gas Regulation compliance.
- Adjustable Clamps:Modular band designs accommodate diameter variation across mixed-diameter piping runs without inventory proliferation.
- Rigid Clamps:Fixed-dimension stamped formats remain mature in commercial plumbing, with margin pools concentrating in specification-grade products carrying third-party fire resistance certification.
U-Clamps handle the majority of throughput; Cushion Clamps are expanding most quickly on specification share.
Material:
Cost tiers separate specification-grade procurement from commodity replacement cycles, with alloy composition determining eligibility for potable water, offshore, and cleanroom environments.
- Stainless Steel:Austenitic grades 304 and 316L provide chloride corrosion resistance for chemical processing and marine applications. Germany, China, and the United States absorb disproportionate share of premium stainless demand for infrastructure upgrades and industrial capacity expansion.
- Carbon Steel:Zinc-coated or painted variants serve price-sensitive commercial plumbing and general construction where atmospheric exposure remains moderate. Mid-volume production clusters in Zhejiang and Jiangsu provinces create single-source vulnerability for distributors without dual-qualified supply bases.
- Plastic:Polypropylene and nylon formulations deliver electrical isolation for pneumatic control systems and instrumentation tubing.
- Rubber:EPDM and silicone cushion elements provide acoustic damping and thermal isolation, though REACH substance disclosure mandates are forcing compounders to requalify formulations against SVHC candidate list updates.
Carbon Steel moves the highest unit volumes; Stainless Steel generates the steepest margin expansion trajectory.
Application:
Customer type and regulatory exposure separate specification-grade procurement from commodity replacement cycles across fluid transport systems.
- HVAC Systems:Low-leakage clamp geometries dominate refrigerant line specifications as EU F-Gas Regulation redirects contractor procurement toward emission-minimizing fastening systems. German and Italian mechanical contractors now require torque-rated installations with documented material traceability.
- Pneumatic Systems:Plastic and rubber cushion variants gain specification share where electrical isolation and acoustic damping outweigh mechanical load requirements in compressed air distribution networks.
- Plumbing:EPA Safe Drinking Water Act requirements restrict brass alloy compositions for potable water applications, forcing reformulation of traditional silicon bronze fastening hardware in the United States.
- Construction:Bridge-mounted utility corridors and tunnel ventilation systems in India generate specification demand for vibration-rated clamp assemblies under national highway and metro rail expansion programs.
Plumbing absorbs the largest installed base; HVAC Systems are climbing the fastest on regulatory-driven specification upgrades.
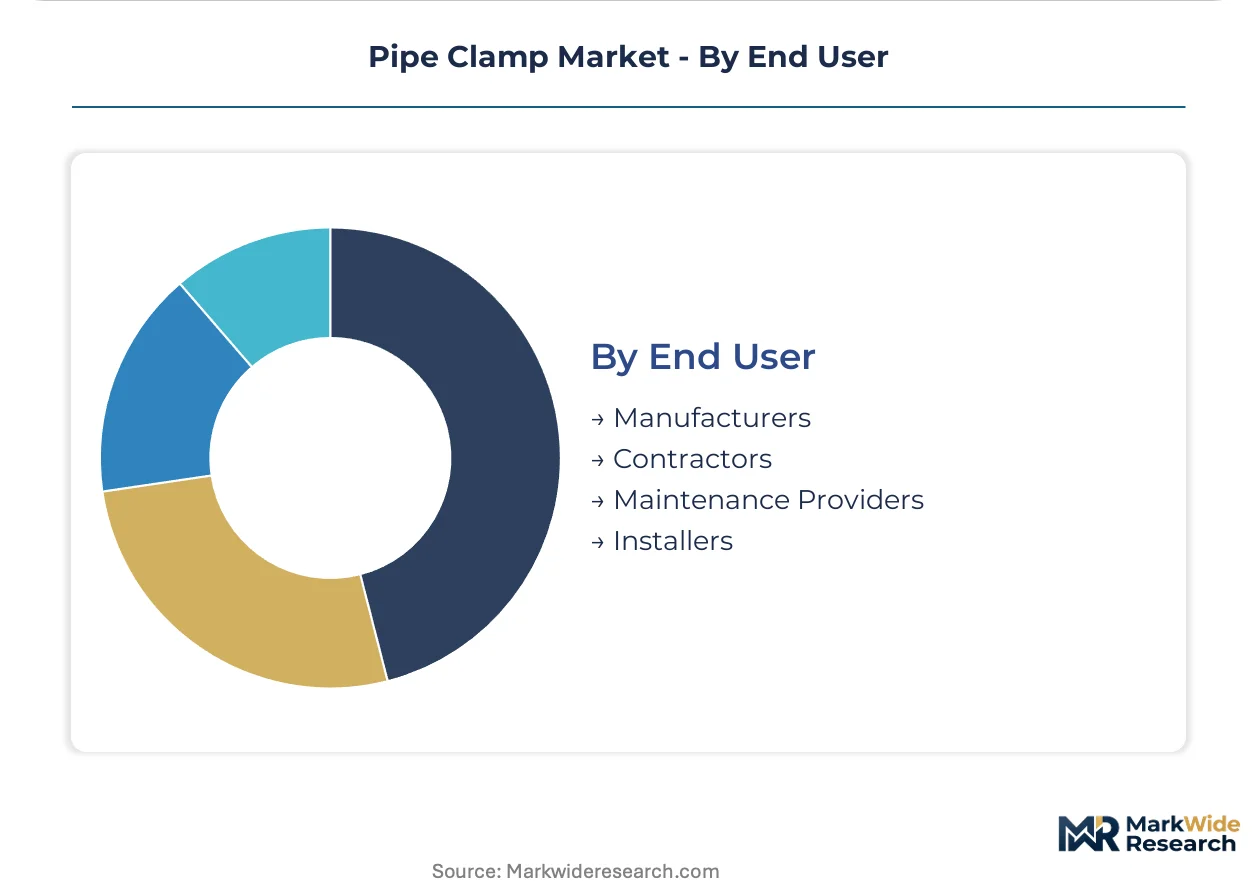
End User:
Volume concentration and margin capture separate direct OEM relationships from distributor-mediated procurement channels.
- Contractors:Consolidated MEP procurement desks at major infrastructure contractors in Germany and the Netherlands maintain approved manufacturer lists with locked torque specifications and pre-negotiated volume tiers.
- Manufacturers:European machinery OEMs demand full material composition data and digitized material passports traceable to polymer compounding batches for rubber cushion elements.
- Maintenance Providers:Asset-light leasing models for industrial fastening inventories reduce working capital requirements for contractors serving intermittent turnaround schedules.
- Installers:BIM-compliant clamp libraries with embedded torque specifications enable pre-validation of installation sequences before site mobilization.
Contractors control the dominant procurement volume; Manufacturers are gaining specification influence fastest through direct material qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-grade stainless steel clamp fabrication concentrates in Germany and China, while import-dependent markets in India and the Middle East absorb specification-grade volumes for infrastructure buildouts. Trade flows reflect divergent cost structures: Asian carbon steel clusters serve price-sensitive commercial plumbing, European fabricators capture premium chemical processing demand.
Germany
Municipal water infrastructure renewal drives specification-grade procurement for 316L stainless variants across North Rhine-Westphalia and Bavaria. The EU F-Gas Regulation redirects HVAC contractor specifications toward low-leakage clamp geometries for refrigerant containment. Stuttgart-based machinery OEMs maintain approved manufacturer lists with locked torque specifications and DIN-standard metric formats.
China
Mid-volume carbon steel production clusters in Zhejiang and Jiangsu provinces create export capacity for commercial plumbing markets. GB standards for mechanical fasteners impose dimensional and load-testing protocols that differentiate export-grade from domestic-market production. Shanghai port logistics hubs consolidate containerized shipments to Southeast Asian construction markets.
United States
Offshore platform operators in the Gulf of Mexico specify 316L stainless U-clamps to withstand chloride-rich process environments. EPA Safe Drinking Water Act requirements restrict brass alloy compositions for potable water applications, forcing hardware reformulation. Houston-area distributors maintain dual-qualified supply bases to mitigate single-source vulnerability.
India
National highway and metro rail expansion generates specification demand for vibration-rated clamp assemblies in bridge-mounted utility corridors. The Bureau of Indian Standards imposes mechanical fastener protocols for infrastructure procurement. Mumbai and Delhi fabrication clusters scale capacity for tunnel ventilation and pneumatic distribution systems.
United Arab Emirates
Desalination plant operators and petrochemical processors import premium stainless fastening systems for corrosive process environments. Local content requirements under Abu Dhabi National Oil Company procurement frameworks favor joint-venture fabrication partnerships. Dubai Jebel Ali free zone logistics hubs re-export specification-grade inventories to Saudi Eastern Province and Kuwait.
Pipe Clamp Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive polymer compounding and load-testing capabilities. The vendor base separates into three functional layers: diversified fluid power conglomerates with integrated distribution networks, mid-cap specialists with DIN-standard or ASME-certified product lines, and regional fabricators serving price-sensitive commercial plumbing. Consolidation pressures concentrate in specification-grade segments where material traceability and third-party fire resistance certification create switching costs. Competitive moves center on backward integration into elastomer compounding and BIM-compliant digital product libraries.
Among European specialists, Norma Group and STAUFF occupy positions anchored by captive manufacturing capabilities and standard-setting influence. Norma Group exemplifies the polymer-integrated archetype with in-house cushion clamp production. STAUFF represents the metric-standard specialist tier with DIN-format dominance in machinery OEM specifications. Parker Hannifin Corporation sits within the diversified platform tier, leveraging fluid power channel integration to bundle clamp supply with broader system awards.
| Leading Market Players |
|---|
| Norma Group |
| Panduit Corporation |
| Parker Hannifin Corporation |
| Oetiker Group |
| STAUFF |
| Walraven Group |
| BPC Engineering |
| Piping Technology & Products |
| Rilco |
| Others |
Value Network & Pricing Analysis
Zhejiang and Jiangsu province clusters anchor carbon steel clamp capacity for commercial plumbing markets, while their export pricing power erodes when nickel volatility compresses austenitic stainless margins. Specification-grade procurement concentrates leverage with DIN-standard fabricators in Germany and captive-polymer compounders who control cushion clamp formulations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade—REACH-compliant material passports versus uncertified commodity formats—and volume scale drive price differentiation. Cost compression in carbon steel tiers intensifies because Chinese domestic overcapacity floods export channels. Municipal contractors exhibit highest price sensitivity; offshore platform operators demonstrate least sensitivity due to replacement interval economics.
Supply Chain Analysis
Contract manufacturing concentrates with mid-volume fabricators in Zhejiang and Jiangsu provinces, specialty DIN-standard producers in Germany, and polymer-integrated compounders serving European machinery OEMs. Raw material sourcing draws from LME nickel contracts for austenitic grades, EPDM rubber feedstocks for cushion elements, and zinc-coated carbon steel coil. Single-source vulnerability concentrates in Chinese export capacity without dual-qualified alternatives. Distribution runs through fluid power channel integrators, MEP procurement desks, and third-party logistics providers managing asset-light leasing pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade pipe clamp procurement increasingly bundles digital traceability services and BIM-compliant library subscriptions, with recurring-revenue attach rates expanding faster than hardware unit economics across European machinery OEM accounts.
For Market Incumbents: Insulate margin pools by deepening backward integration into elastomer compounding and maintaining locked torque specifications on approved manufacturer lists. Counter nickel price volatility through long-term offtake agreements with stainless steel mills. Prioritize SCIP database registration capabilities to meet REACH substance disclosure mandates before compounders face SVHC requalification deadlines. For New Entrants and Emerging Players: Establish a beachhead in India's vibration-rated clamp assemblies for bridge-mounted utility corridors under national highway expansion. Target specification gaps in silicone-free elastomer formulations for food-contact cleanroom environments. Lead with BIM-compliant digital product libraries to bypass incumbent distributor relationships and secure direct MEP contractor engagement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified fluid power conglomerates with non-core clamp divisions lacking polymer compounding integration. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than scale alone. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for low-leakage clamp specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive polymer formulation control secures margin defense against REACH requalification cycles. |
| BIM-Compliant Digital Product Library Launch | Embedded torque specifications enable MEP contractors to pre-validate installation sequences. |
| Dual-Qualified Supply Base Establishment | Mitigates single-source vulnerability from Zhejiang-Jiangsu concentration for Houston distributors. |
| SCIP Database Registration Investment | Material passport digitization satisfies European machinery OEM rejection thresholds. |
| Asset-Light Leasing Model Partnership | Third-party logistics inventory pools reduce working capital for intermittent turnaround contractors. |
Research Methodology
The analysis maps stainless steel specification-grade, carbon steel commodity-grade, and polymer cushion clamp sub-sectors, each validated through procurement directors at municipal utilities, HVAC contractors, offshore fabricators, and European machinery OEMs. Primary fieldwork combined with customs trade data, DIN standard certification registries, EPA Safe Drinking Water Act filings, and SEC 10-K supply chain disclosures enabled bottom-up and top-down triangulation.
Forecast assumptions held EU F-Gas Regulation enforcement trajectory and nickel price band volatility fixed across the projection horizon. Segmentation dimensions modeled include material grade tier, application environment, end-user procurement channel, and regional regulatory cluster. CAGRs derived from unit volume build-ups by specification grade and value-per-unit trajectories tied to alloy composition and certification requirements.
Stress conditions across LME nickel contract swings, REACH SVHC list expansion timing, and Indian infrastructure award cadence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory reciprocity and certification reciprocity between import jurisdictions. Quarterly review of EU F-Gas penalty enforcement rates and BIS mechanical fastener protocol updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Hydraulic Hose Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Global Loading Dock Bumpers Market